
 Grid Optimization Solution Market | 2026-2036
Grid Optimization Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Grid Optimization Solution Market Outlook
The EU Green Deal is decoupling legacy grid infrastructure from carbon-intensive operations, rewriting the cost-of-entry calculus for new market participants. Siemens AG leverages deep vertical integration across hardware and software stacks to sustain technology leadership in predictive grid analytics. Schneider Electric SE anchors its competitive position through geographic dominance in European smart grid deployments, while ABB Ltd specializes in high-voltage direct current integration for cross-border transmission networks.
Grid optimization solutions encompass software platforms, sensor networks, and control systems that dynamically balance electricity load, voltage, and frequency across transmission and distribution infrastructure, typically operating with sub-second response times to maintain grid stability. These systems serve the primary commercial purpose of minimizing technical losses, deferring capital-intensive infrastructure upgrades, and enabling bidirectional power flows from distributed energy resources. Software solutions currently occupy the largest margin pool as recurring licensing models displace one-time hardware sales, while cloud-based deployment models represent the fastest-growing architecture as utilities outsource computational infrastructure. Predictive analytics leads technology adoption among utility providers seeking to preempt equipment failures before outage events cascade.
FERC Order 2222 in the United States and the EU Cybersecurity Act collectively reshape product standards by mandating interoperable distributed energy resource aggregation and certifying critical infrastructure protection protocols. Germany's BNetzA and France's CRE enforce grid codes that require real-time visibility into renewable injection points, directly stimulating demand for IoT-integrated monitoring suites. Stakeholders must weigh the capital allocation trade-off between retrofitting aging substations with edge-computing nodes versus full cloud migration, as regulatory compliance timelines tighten and cyber insurance requirements harden.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing utilities to abandon sulfur hexafluoride-based switchgear and carbon-intensive grid operations, accelerating capital redeployment toward digital optimization platforms that enable real-time renewable integration.
Growth Catalysts
- FERC Order 2222:This US mandate requires grid operators to accept aggregated distributed energy resources, compelling utilities to deploy interoperable optimization software for bidirectional power flow management.
- AI-driven predictive analytics:Machine learning platforms that preempt equipment failures are displacing scheduled maintenance regimes, with utility providers prioritizing outage prevention over reactive repair protocols.
- Germany:BNetzA grid codes mandating real-time visibility into renewable injection points are stimulating demand for IoT-integrated monitoring suites across transmission infrastructure.
Market Restraints
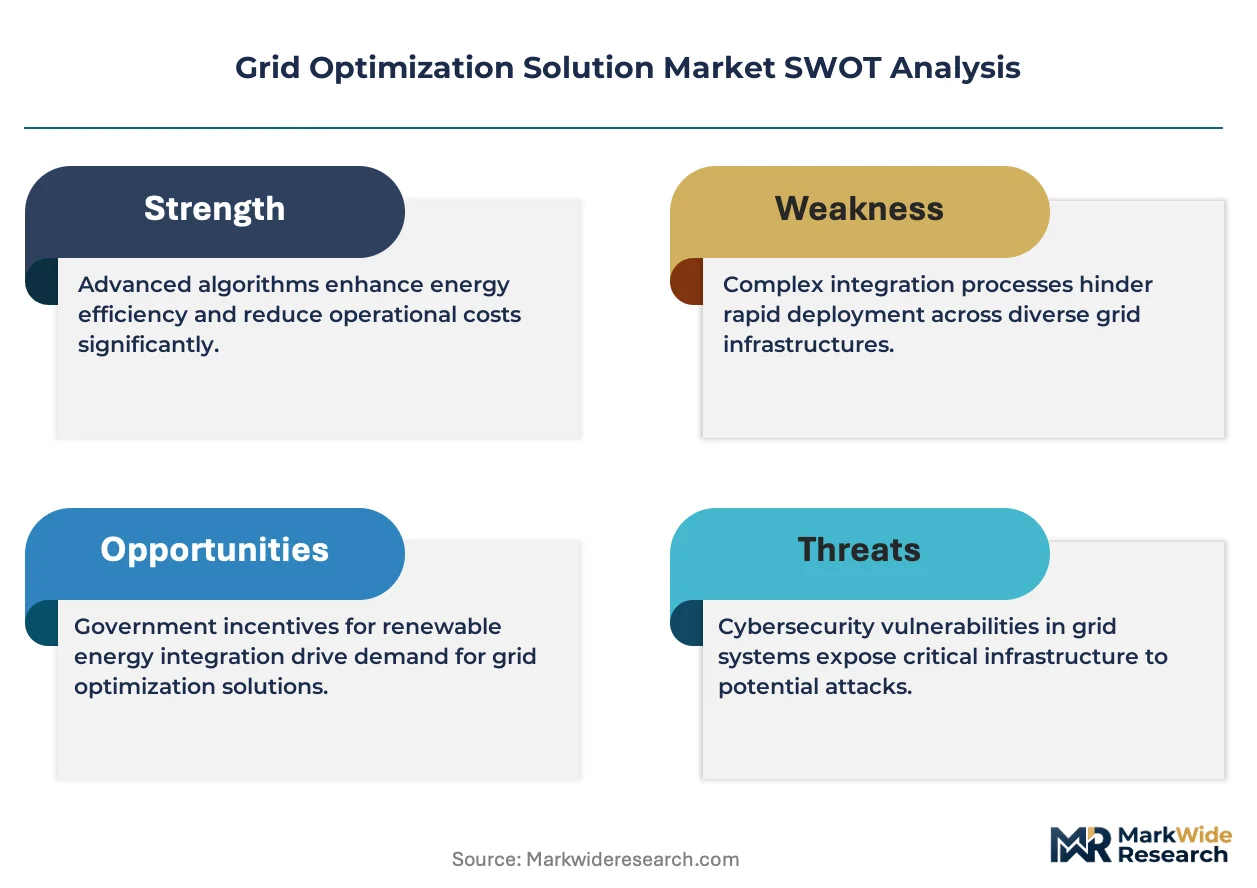
- Copper and rare earth price volatility:Sensor networks and power electronics depend on concentrated supply chains from limited producer geographies, compressing hardware margins when commodity cycles spike.
- Cyber insurance hardening:Critical infrastructure protection requirements under the EU Cybersecurity Act are raising compliance costs for cloud-based grid management deployments.
- Legacy SCADA incompatibility:Proprietary protocols in aging substations create technical debt that slows edge-computing node integration and extends payback periods for hybrid architectures.
Strategic Opportunities
- France CRE capacity mechanisms:These market designs reward demand-response aggregation, creating openings for optimization vendors to bundle software with behind-the-meter storage control.
- Digital twin convergence with edge AI:Combining physics-based grid modeling with localized inference engines enables sub-second voltage regulation without full cloud dependency.
- Utility-as-a-service channels:Municipal cooperatives and smaller distribution operators are outsourcing grid management to platform providers rather than building in-house analytics capabilities.
Industry Challenges
- Power systems engineering talent scarcity:The intersection of electrical engineering and data science skills required for grid optimization platform deployment outpaces university pipeline output.
- Multi-vendor integration complexity:Utilities operating mixed fleets of Siemens, ABB, and Schneider hardware face protocol fragmentation when unifying optimization layers across substation tiers.
- Certification timeline compression:IEC 61850 and IEEE 2030.5 compliance testing for new software releases is extending product launch cycles as regulatory scrutiny intensifies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid Optimization Solution Market |
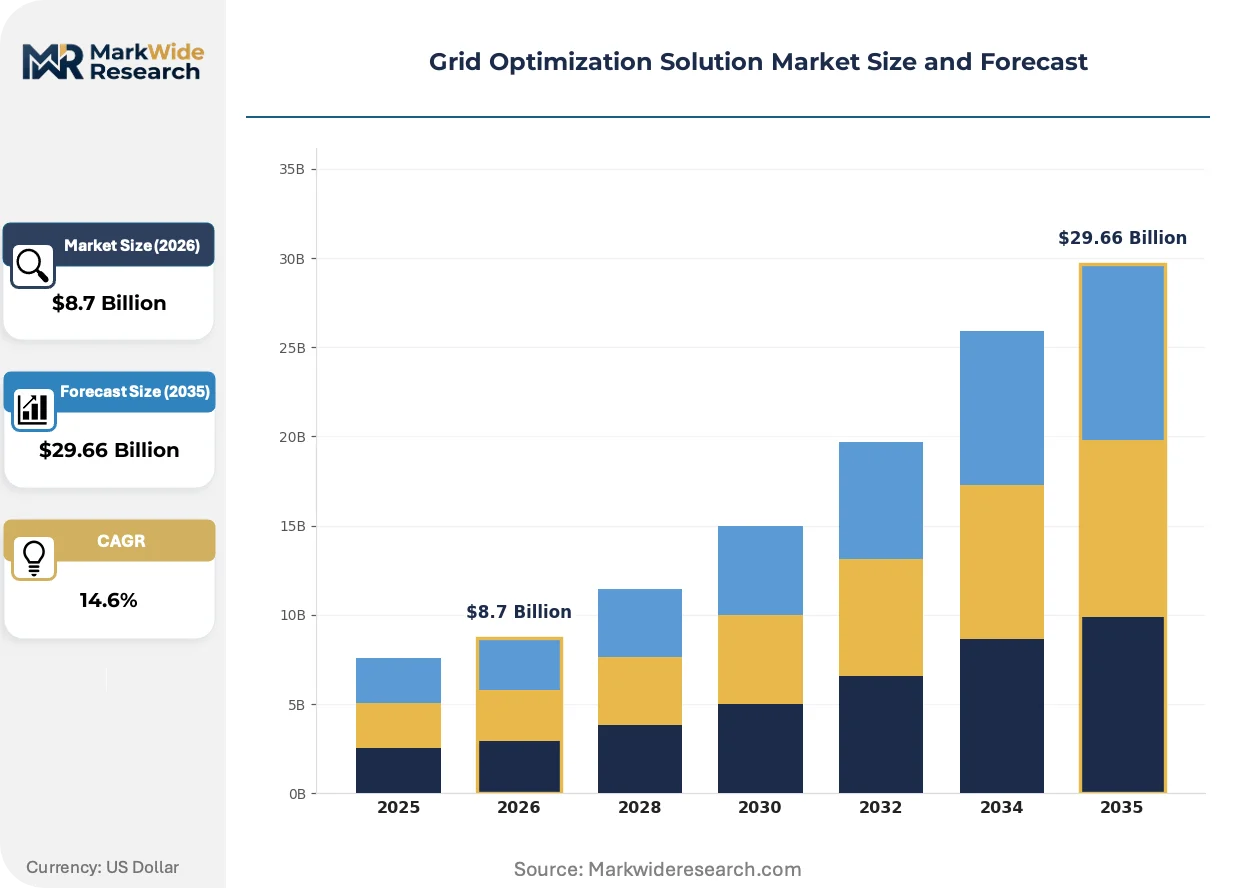
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Components, Integrated Systems, Consulting Services End User: Utility Providers, Industrial Operators, Commercial Establishments, Renewable Energy Firms Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services Technology: Predictive Analytics, AI Algorithms, IoT Integration, Data Management Tools |
| Companies Covered | Siemens AG, General Electric Company, Schneider Electric SE, ABB Ltd, Hitachi Energy Ltd, Honeywell International Inc, Eaton Corporation plc, Cisco Systems Inc, Itron Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid Optimization Solution Market Strategic Shifts
Software-defined grid architectures are displacing hardware-centric control systems, with virtualization layers enabling centralized management of geographically dispersed assets without proprietary lock-in.
Containerized microgrid control software is modularizing how utilities deploy optimization logic, allowing incremental capability expansion without wholesale platform replacement. Mid-sized distribution operators in Denmark and the Netherlands are adopting this architecture fastest, drawn by reduced upfront capital requirements. The approach is modularizing vendor relationships, letting buyers mix control modules from specialized providers rather than accepting bundled suites.
The EU AI Act's risk classification framework for critical infrastructure is mandating explainability standards in automated grid decision systems, forcing algorithm developers to document inference pathways. High-voltage transmission operators face the steepest compliance burden, with France's RTE and Germany's TenneT accelerating procurement of certified transparent AI platforms. This regulatory pressure is segmenting the vendor landscape between compliant enterprise-grade offerings and non-compliant niche tools.
Performance-based contracting is displacing perpetual licensing for grid optimization software, with buyers preferring fees tied to measurable loss reduction or deferral of capital upgrades. European utilities lead this transition, with E.ON and Enel structuring multi-year agreements where vendor compensation scales with documented efficiency gains. This model concentrates risk with platform providers while aligning incentives around operational outcomes rather than feature proliferation.
Grid Optimization Solution Market Segmentation
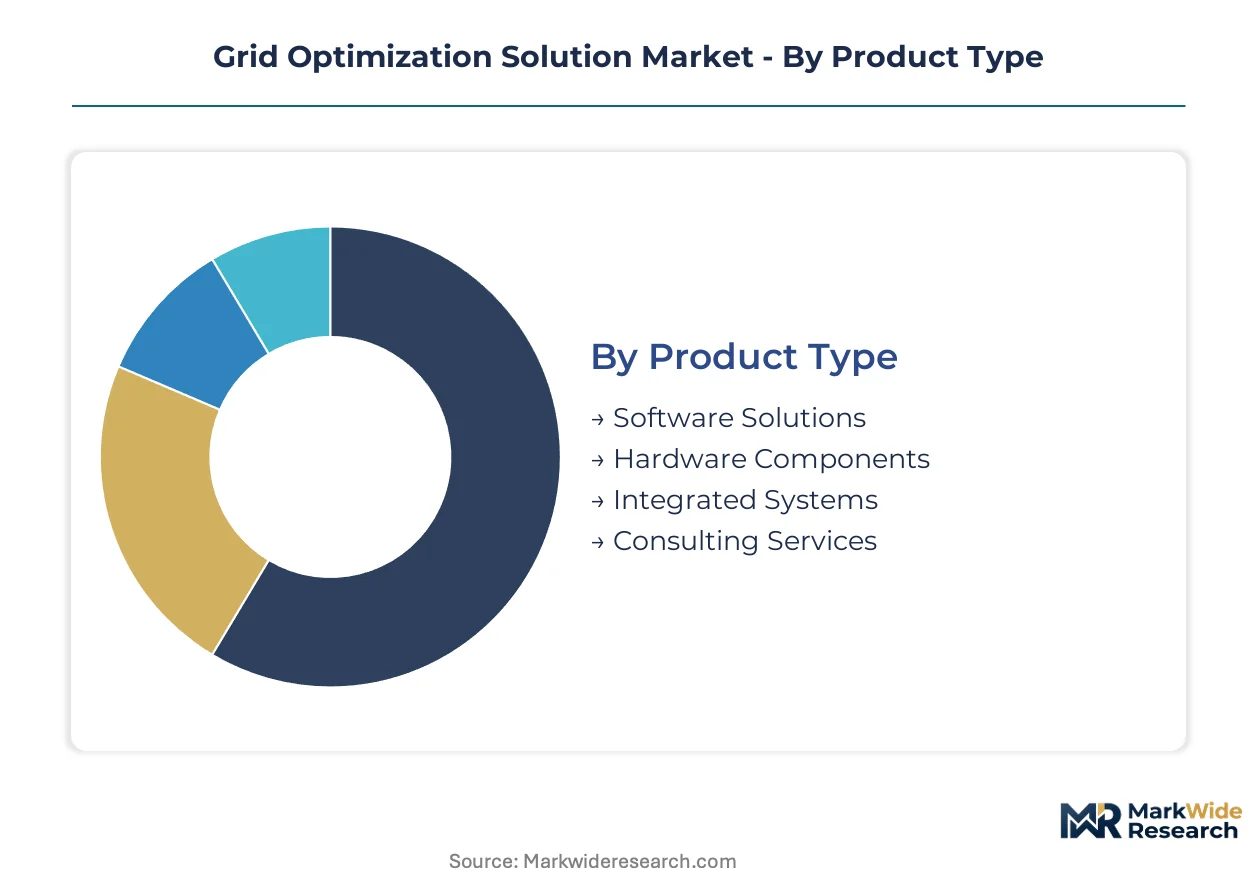
Grid optimization solutions segment across four critical dimensions that determine procurement patterns, certification burdens, and margin structures. Product type dictates recurring revenue potential versus capital intensity. Deployment model shapes cyber insurance exposure and regulatory compliance pathways under EU Cybersecurity Act and FERC mandates.
Product Type:
Certification requirements diverge sharply across product categories. Software solutions face IEC 61850 and IEEE 2030.5 compliance testing. Hardware components trigger CE marking and F-Gas Regulation scrutiny for sulfur hexafluoride alternatives. Integrated systems combine both burden sets. Consulting services operate under lighter direct product certification but carry professional liability exposure.
- Software Solutions:Platforms orchestrating load balancing, voltage regulation, and frequency control through algorithmic optimization. Demand concentrates among Germany's transmission operators and France's RTE as BNetzA and CRE grid codes mandate real-time visibility. Recurring licensing models displace one-time hardware sales, capturing the largest margin pool in the category.
- Hardware Components:Sensor networks, power electronics, and edge-computing nodes requiring copper and rare earth inputs. Procurement runs through Siemens and ABB supply chains for substation retrofit projects. Copper price volatility compresses margins when commodity cycles spike, forcing inventory hedging strategies.
- Integrated Systems:Bundled hardware-software architectures with unified control layers. Municipal cooperatives in Denmark and the Netherlands favor these for reduced vendor management overhead.
- Consulting Services:Grid modernization advisory, implementation support, and ongoing optimization tuning. Smaller distribution operators outsource analytics capabilities here rather than building in-house teams.
Leading the category by volume: Software Solutions. Growing fastest: Integrated Systems.
End User:
Customer type determines solution complexity and procurement authority concentration. Utility providers command enterprise-scale budgets with centralized technical standards. Industrial operators prioritize uptime guarantees over grid-wide optimization. Commercial establishments and renewable energy firms represent fragmented demand with divergent regulatory exposure.
- Utility Providers:Transmission and distribution operators managing regional grid stability with sub-second response requirements. Germany's TenneT and France's RTE drive demand for AI-driven predictive analytics platforms. FERC Order 2222 compels US utilities to accept aggregated distributed energy resources, forcing interoperable software procurement.
- Industrial Operators:Manufacturing and heavy industry facilities with captive generation and demand-response capabilities. Energy-intensive German chemical clusters prioritize outage prevention over reactive repair protocols.
- Commercial Establishments:Office complexes, retail chains, and data centers with behind-the-meter storage and solar assets. France CRE capacity mechanisms reward demand-response aggregation here.
- Renewable Energy Firms:Wind and solar developers requiring grid code compliance for injection point visibility. Real-time monitoring suites from IoT-integrated vendors dominate procurement.
Dominating procurement volume: Utility Providers. Expanding most quickly: Renewable Energy Firms.
Deployment Model:
Architecture choice shapes capital allocation between operational expenditure and infrastructure ownership. On-premises deployments retain data sovereignty but demand specialized engineering talent. Cloud-based models outsource computational infrastructure but harden cyber insurance requirements. Hybrid and managed service approaches split the difference for risk-averse buyers.
- On-Premises:Localized server infrastructure with full data control and air-gapped security postures. Critical infrastructure operators in Germany favor this for EU Cybersecurity Act compliance.
- Cloud-Based:Utility providers outsource computational infrastructure to specialized platform vendors. This architecture climbs the fastest as mid-sized European distribution operators seek reduced upfront capital requirements.
- Hybrid Solutions:Edge-computing nodes for sub-second inference combined with cloud analytics for longitudinal optimization. Digital twin convergence with localized AI enables voltage regulation without full cloud dependency.
- Managed Services:Complete grid management outsourcing including software, hardware, and operational staffing. Municipal cooperatives adopt this channel to access capabilities without building in-house analytics teams.
Capturing largest current share: On-Premises. Steepest expansion trajectory: Cloud-Based.
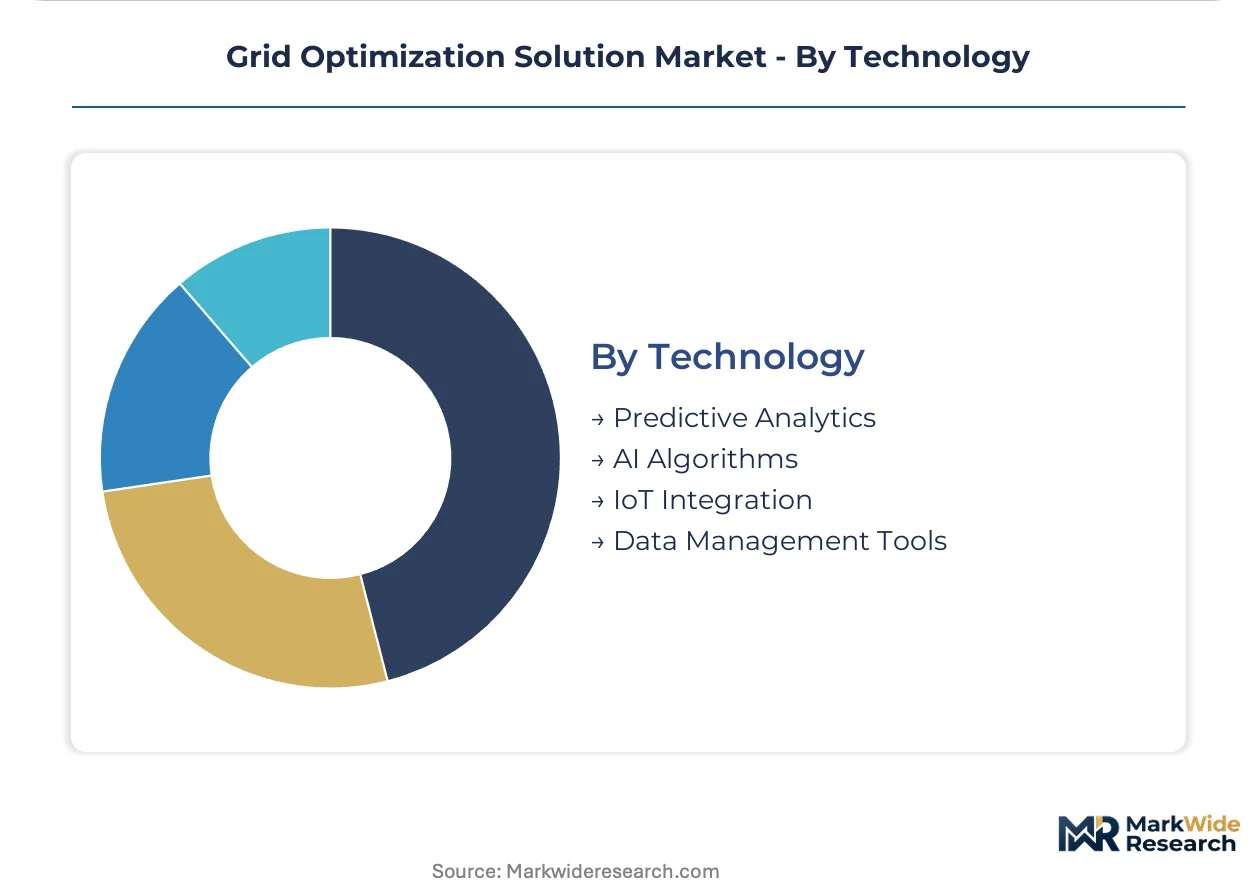
Technology:
Technology selection determines algorithmic capability boundaries and regulatory scrutiny intensity. Predictive analytics and AI algorithms face EU AI Act explainability mandates for critical infrastructure. IoT integration triggers data management and cybersecurity protocols. Tool selection cascades into staffing requirements and vendor lock-in risk.
- Predictive Analytics:Machine learning platforms preempting equipment failures before outage events cascade. Utility providers prioritize this technology for scheduled maintenance displacement. Germany's BNetzA grid codes directly stimulate procurement through real-time visibility mandates.
- AI Algorithms:Automated decision systems for load forecasting and renewable integration optimization. France's RTE and Germany's TenneT accelerate procurement of certified transparent AI platforms under EU AI Act risk classification frameworks.
- IoT Integration:Sensor networks and communication protocols enabling distributed asset monitoring. Smart meter deployments and substation automation drive hardware procurement.
- Data Management Tools:Platforms for grid telemetry storage, retrieval, and analytics pipeline orchestration. Cyber insurance hardening raises compliance costs for centralized data architectures.
Highest current penetration: Predictive Analytics. Gaining share fastest: AI Algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in the United Arab Emirates concentrate smart grid investment through Abu Dhabi's Masdar City and Dubai's Silicon Oasis, drawing technology transfer from European optimization vendors seeking Middle East beachheads.
Germany
Transmission operators TenneT and 50Hertz drive demand for AI-driven predictive analytics platforms as BNetzA grid codes mandate real-time visibility into renewable injection points. The EU Green Deal accelerates sulfur hexafluoride phase-out in switchgear, forcing capital redeployment toward digital optimization. Industrial clusters in North Rhine-Westphalia's Ruhr region retrofit aging substations with edge-computing nodes for hybrid cloud architectures.
United States
FERC Order 2222 compels regional transmission organizations to accept aggregated distributed energy resources, stimulating interoperable software procurement. Texas ERCOT market participants prioritize outage prevention systems following 2021 grid stress events. California's CAISO territory leads cloud-based deployment adoption among municipal cooperatives seeking reduced upfront capital requirements.
France
CRE capacity mechanisms reward demand-response aggregation, creating procurement openings for optimization vendors bundling software with behind-the-meter storage control. RTE accelerates certified transparent AI platform procurement under EU AI Act risk classification frameworks. The Île-de-France region concentrates smart grid pilot programs integrating digital twin convergence with edge AI for sub-second voltage regulation.
China
State Grid Corporation deploys ultra-high-voltage direct current transmission optimization systems across western renewable bases to eastern load centers. MIIT standards mandate domestic cybersecurity protocols for critical infrastructure protection. Yangtze River Delta municipalities in Jiangsu and Zhejiang provinces trial containerized microgrid control software for incremental capability expansion.
United Kingdom
Ofgem's RIIO-2 price controls incentivize distribution network operators to defer capital-intensive reinforcement through active network management. National Grid ESO procures grid-scale battery optimization platforms for frequency response services. Scottish Power's central Scotland transmission corridor integrates IoT monitoring suites for real-time wind farm output visibility.
Grid Optimization Solution Market Competitive Environment
German and Swiss producers anchor one tier of the market through deep industrial automation heritage; US technology conglomerates hold another through software-defined infrastructure capabilities. The vendor landscape organizes around three strategic archetypes: vertically integrated industrial conglomerates with captive hardware-software stacks, specialized power electronics firms with high-voltage transmission expertise, and cloud-native software vendors with AI/ML optimization engines. Competitive moves concentrate on strategic partnerships between hardware incumbents and cloud platform providers, alongside portfolio diversification into behind-the-meter storage control systems.
Among European industrial conglomerates, Siemens AG and ABB Ltd occupy positions exemplifying the vertically integrated archetype with unified control layers across substation tiers. Schneider Electric SE represents the geographic dominance model in European smart grid deployments. These three anchors illustrate how certification burdens under IEC 61850 and EU Cybersecurity Act favor established players with dedicated compliance infrastructure over emerging software entrants.
| Leading Market Players |
|---|
| Siemens AG |
| General Electric Company |
| Schneider Electric SE |
| ABB Ltd |
| Hitachi Energy Ltd |
| Honeywell International Inc |
| Eaton Corporation plc |
| Cisco Systems Inc |
| Itron Inc |
| Others |
Value Chain & Pricing Dynamics
FERC Order 2222 compliance timelines are compressing procurement cycles for interoperable optimization software, forcing vendors to hold finished goods inventory closer to US transmission operators and compressing margins on expedited delivery contracts. This demand-side urgency interacts with concentrated sensor component supply chains, creating pricing power asymmetries that favor integrated hardware-software vendors over pure-play software entrants.
Pricing Analysis
Short lead-time premiums of 15-25% apply to cloud-based deployment configurations where utilities demand sub-90-day implementation windows to meet regulatory deadlines. The dominant pricing structure is a three-tier subscription model across premium, standard, and economy levels, with differentiation driven by IEC 61850 certification tier and bundled cyber insurance coverage. Price erosion runs through the hardware component tier as copper and rare earth commodity cycles spike, compressing margins for sensor network vendors. Municipal cooperatives exhibit highest price sensitivity due to constrained capital budgets, while Germany's TenneT and France's RTE prioritize certification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for power electronics and Taiwanese semiconductor fabrication for edge-computing nodes. Manufacturing concentrates in Germany, China, and the United States for grid hardware, while software development clusters in India and Eastern Europe. The supply chain draws from copper concentrate, neodymium magnets, and silicon carbide wafers as critical inputs. Tariff exposure on Chinese rare earth exports constitutes the primary structural risk. Distribution runs through Siemens, ABB, and Schneider Electric's captive service networks for integrated systems, with direct cloud provisioning displacing hardware channels fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive compliance infrastructure, as EU Cybersecurity Act certification burdens and IEC 61850 testing timelines force smaller software entrants into strategic exits or acquisition.
For Market Incumbents: Cement technology leadership by deepening backward integration into edge-computing semiconductor supply and acquiring niche AI optimization shops with EU AI Act-compliant algorithm documentation. Cloud-native entrants with transparent inference engines threaten the software tier; incumbents should preempt through exclusive distribution partnerships with Germany's municipal cooperatives. For New Entrants and Emerging Players: Municipal cooperatives in Denmark and the Netherlands represent the most penetrable buyer archetype, underserved by legacy vendor sales coverage and receptive to utility-as-a-service outsourcing models. Containerized microgrid control software offers a white-space entry point with reduced certification burden compared to transmission-grade platforms. A direct channel strategy bypassing incumbent distributor networks enables faster proof-of-concept deployment. For Investors and Strategic Acquirers: The window for entry favors specialized power electronics firms with high-voltage DC expertise and existing IEC certification infrastructure. Long-term viability hinges on regulatory compliance capabilities rather than algorithmic differentiation alone. Watch France's RTE and Germany's TenneT procurement patterns for certified transparent AI platforms as the inflection signal for enterprise-grade vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies Siemens and ABB hardware stacks with cloud-native AI layers for mixed-fleet utilities. |
| Acquisition of Specialist Firm | Captures EU AI Act-compliant algorithm documentation and transparent inference engine IP. |
| Strategic Partnership | Links edge-computing vendors with cyber insurance underwriters to reduce compliance costs. |
| Geographic Expansion | Establishes Denmark and Netherlands beachheads for utility-as-a-service channel development. |
| Product Launch | Introduces containerized microgrid control software for incremental capability expansion. |
Study Parameters
Regulatory filings from FERC, BNetzA, and CRE, alongside IEC standards documentation and EU Cybersecurity Act implementation guidance, formed the secondary backbone of this analysis. Primary interviews with utility planning officers, grid operators at TenneT and RTE, EPC contractors specializing in substation retrofit, and cyber insurance underwriters validated demand assumptions. EIA grid investment data, IEA power system transformation reports, and hyperscaler utility partnership disclosures provided secondary triangulation. Bottom-up segmentation modeling across product type, deployment architecture, and end-user category was cross-checked against top-down market sizing from capital expenditure tracking.
Historical trendline analysis of utility software procurement patterns and hardware component trade flows established baseline growth trajectories across the projection horizon. The analytical framework modeled deployment model, end-user scale tier, technology adoption stage, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from elasticity-adjusted investment schedules and technology substitution curves. Forecast inputs included FERC Order 2222 implementation pace, EU F-Gas Regulation phase-out schedules, and copper price volatility assumptions.
Revisions become necessary when EU AI Act enforcement intensity exceeds current guidance, rare earth export restrictions materialize, or cyber insurance market capacity contracts beyond modeled scenarios. Forecasts reflect documented assumptions about regulatory timeline adherence and technology adoption S-curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Airflow Management Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Global Digital Utility Market