
 Evaporative Air Cooler Market | 2026-2036
Evaporative Air Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Evaporative Air Cooler Market Intelligence
Commercial warehousing is decoupling from traditional compressor-based cooling as humidity-tolerant operators seek lower operational expenditure. Symphony Ltd leverages its captive distribution across India's tier-two cities to sustain price competitiveness. Honeywell International anchors its position through industrial-grade control systems that integrate with building automation protocols.
An evaporative air cooler draws ambient air through water-saturated cooling pads, achieving temperature reduction of 15°F to 40°F depending on wet-bulb depression and airflow rates, with power consumption typically 75% below equivalent refrigerated air conditioning. Portable coolers dominate residential replacement cycles in arid climates, while ducted systems command the industrial margin pool due to installation complexity and custom engineering requirements. Smart coolers represent the fastest-growing technology segment as IoT-enabled humidity sensing and variable-speed pumps reduce water waste.
India's BIS mandates minimum energy performance standards for cooling appliances, while the EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in conventional air conditioning, indirectly expanding evaporative cooling's addressable market. The US EPA WaterSense program certifies efficient evaporative equipment for federal procurement eligibility. Stakeholders must monitor evolving water-use restrictions in drought-prone jurisdictions, as regulatory trade-offs between energy savings and water consumption will determine product configuration priorities.
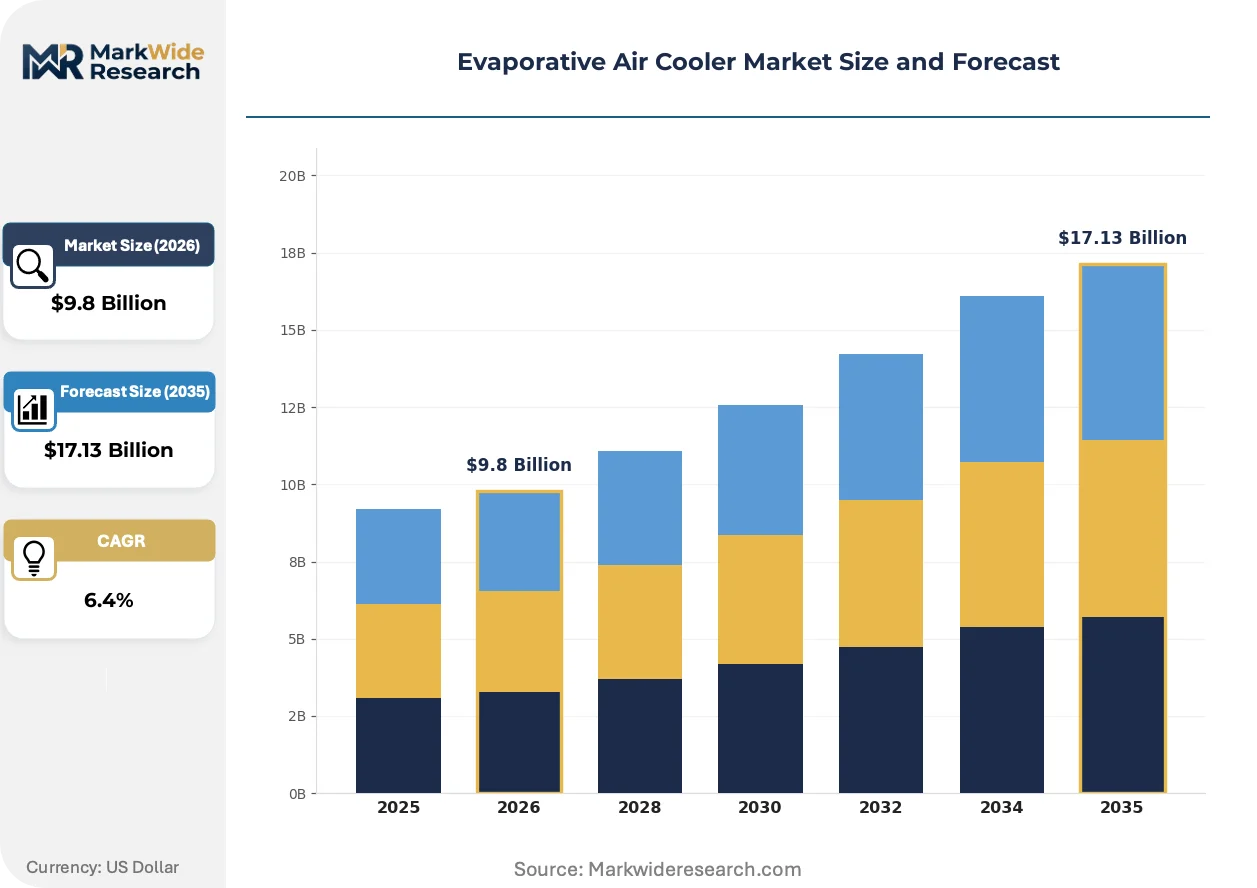
Market Dynamics
Commercial warehouse operators are decoupling from compressor-based cooling as energy costs climb, redirecting capital toward ducted evaporative systems that exploit arid climate advantages. India's BIS energy-efficiency labeling mandates are compressing manufacturer margins while accelerating inverter-based cooling pad adoption.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon restrictions in conventional air conditioning indirectly expand evaporative cooling's addressable market across industrial facilities seeking refrigerant-free alternatives.
- Industrial corridor clustering:Demand concentrates in Gujarat's manufacturing belt where ambient humidity levels below 40% favor direct evaporative technology deployment.
- Variable-speed pump technology:IoT-enabled humidity sensing and adaptive water flow reduce operational waste, cutting utility expenditures for commercial end-users.
Market Restraints
- Water dependency:Drought-prone jurisdictions impose usage restrictions that cap deployment feasibility regardless of energy savings.
- Climate ceiling:Wet-bulb temperature limits render direct evaporative systems ineffective where ambient humidity exceeds 60%.
- Refrigerated AC substitution threat:Falling heat pump costs in temperate zones siphon commercial retrofit budgets from evaporative alternatives.
Strategic Opportunities
- Smart cooler convergence:Integration of building automation protocols with industrial-grade control systems opens premium specification channels.
- US federal procurement:EPA WaterSense certification creates eligibility pathways for evaporative equipment in government facility upgrades.
- Replacement cycle acceleration:Portable cooler demand in arid residential markets shortens as efficiency standards obsolete legacy pad designs.
Industry Challenges
- Skill scarcity in ducted installation:Custom engineering requirements for industrial systems outpace qualified technician supply.
- Pad material certification timelines:BIS compliance testing for cellulose and synthetic media extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evaporative Air Cooler Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Coolers, Window Units, Ducted Systems, Roof-Mounted Systems Technology: Direct Evaporative Cooling, Indirect Evaporative Cooling, Hybrid Systems, Smart Coolers End User: Residential, Commercial, Industrial, Agricultural Sales Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Symphony Ltd, Bajaj Electricals, Honeywell International, Aolan Industry, Hessaire Products, Shenzhen Lianchuang Technology Group, Midea Group, Seeley International, Portacool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evaporative Air Cooler Market Strategic Shifts & Innovations
Active reshaping in this market centers on control system sophistication, regulatory displacement of competing technologies, and procurement model compression that favors integrated solution providers over component vendors.
Variable-frequency drive technology is integrating with evaporative cooling pad assemblies to modulate airflow against real-time wet-bulb differentials. Commercial warehouse operators in India's tier-two cities adopt these systems fastest, seeking operational expenditure reduction. The technology is integrating formerly separate pump, fan, and sensor subsystems into unified control architectures that compress maintenance overhead.
The EU F-Gas Regulation tightens hydrofluorocarbon phase-down schedules through 2030, eliminating refrigerant options for conventional air conditioning retrofits. Industrial facility managers face stranded asset risk in existing compressor-based systems. European commercial real estate portfolios accelerate evaporative cooling evaluation as compliance deadlines approach.
Facility management procurement is consolidating vendor relationships around building automation integration capability. Single-source specification contracts displace fragmented component purchasing in commercial warehousing. This concentration is most visible in India's industrial corridor, where operators prioritize unified control interfaces over standalone equipment procurement.
Evaporative Air Cooler Market Segmentation
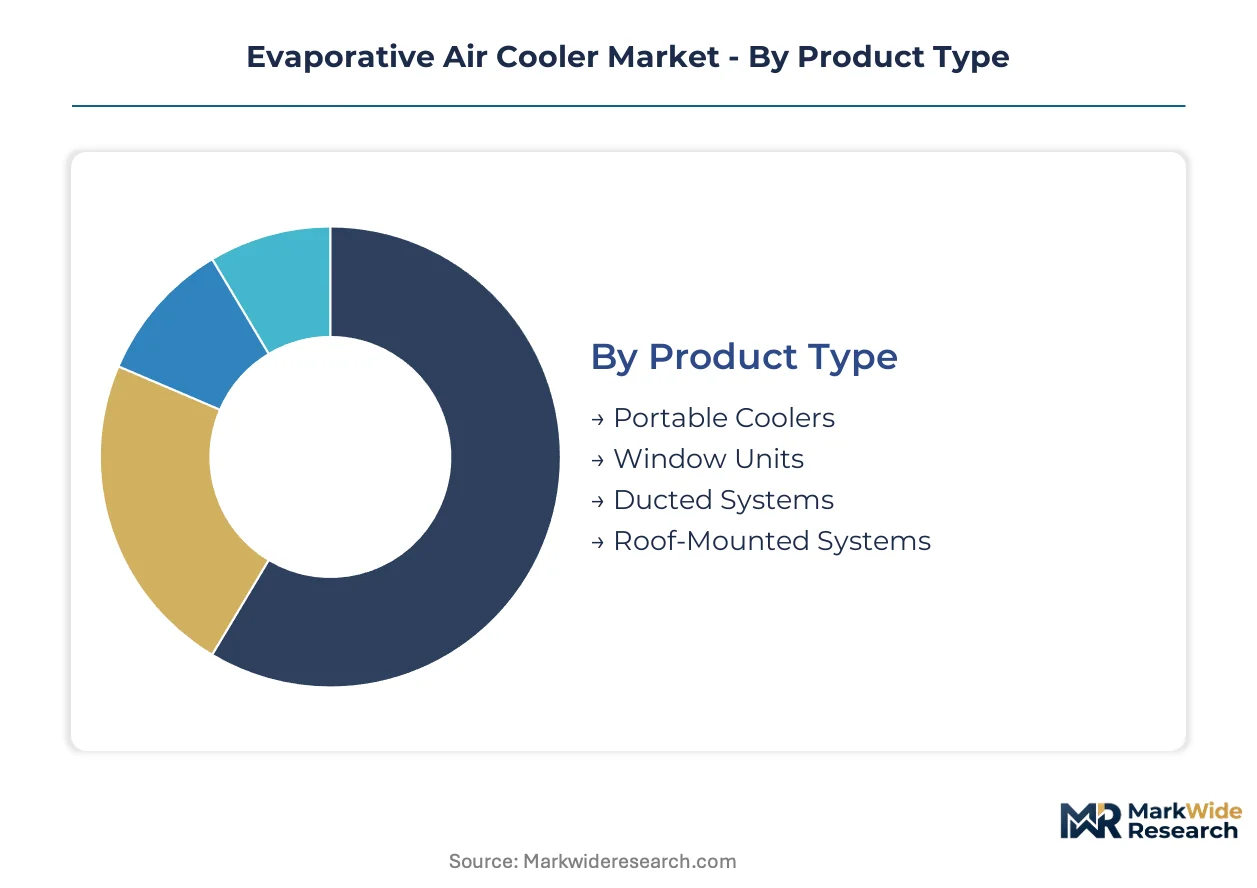
Evaporative air cooler procurement patterns diverge sharply across installation scale and control sophistication. Product configuration choices directly determine whether operators capture energy savings or face stranded asset risk from climate constraints.
Product Type:
Supply concentrates in ducted and roof-mounted configurations for industrial margin pools, while portable units dominate residential replacement velocity.
- Ducted Systems:Custom-engineered distribution networks deliver conditioned air across large commercial footprints. Warehouse operators in Gujarat's industrial corridor favor these systems for their 75% power reduction against refrigerated alternatives.
- Portable Coolers:Self-contained units with water tanks and caster-mounted mobility. Arid-climate residential markets in India's tier-two cities drive replacement cycles as BIS efficiency standards obsolete legacy pad designs.
- Window Units:Through-wall installations bridging residential and light commercial applications.
- Roof-Mounted Systems:Centralized evaporative plants serving multi-zone industrial facilities.
Ducted systems absorb the bulk of installed capacity; portable coolers are expanding most quickly in residential retrofit markets.
Technology:
Cost tiers separate basic direct evaporative units from premium smart systems with IoT-enabled optimization.
- Smart Coolers:Variable-speed pumps and humidity sensors adapt water flow to real-time wet-bulb differentials. Commercial end-users adopt these fastest for utility expenditure reduction and EPA WaterSense procurement eligibility.
- Direct Evaporative Cooling:Ambient air passes through water-saturated cellulose pads for immediate temperature depression. Deployment concentrates where ambient humidity remains below 40%.
- Indirect Evaporative Cooling:Heat exchangers separate working air from conditioned air, enabling operation in moderately humid conditions.
- Hybrid Systems:Combined direct-indirect stages extend effective range across variable climate zones.
Direct evaporative technology holds the largest installed base; smart coolers are gaining share fastest through building automation integration.
End User:
Application requirements dictate specification intensity, with industrial users demanding custom engineering and residential buyers prioritizing first-cost minimization.
- Commercial:Office buildings, retail spaces, and hospitality venues requiring consistent comfort control. EU F-Gas Regulation compliance deadlines accelerate evaluation of refrigerant-free alternatives in European commercial real estate.
- Industrial:Manufacturing plants and warehouse facilities with high internal heat loads. Skill scarcity in ducted installation outpaces qualified technician supply, compressing deployment timelines.
- Residential:Single-family and multi-family dwellings in arid climate zones.
- Agricultural:Livestock housing and greenhouse climate management.
Industrial end-users command the highest specification intensity; commercial adoption is climbing the fastest as energy costs escalate.
Sales Channel:
Volume flows through offline retail for immediate replacement needs, while direct sales capture complex industrial specifications.
- Distributors:Regional networks providing installation support and spare parts logistics. India's captive distribution infrastructure sustains price competitiveness for domestic manufacturers.
- Direct Sales:Factory-direct relationships for large commercial and industrial projects requiring custom engineering.
- Online Retail:E-commerce platforms serving price-transparent residential buyers.
- Offline Retail:Brick-and-mortar dealers offering immediate product availability and local service.
Distributors handle the majority of unit volume; direct sales are expanding most quickly in commercial warehousing procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridor operates as India's primary evaporative cooling concentration zone, with Special Economic Zone tax incentives drawing warehouse operators toward ducted system deployment. Arid climate conditions across the state's manufacturing belt sustain year-round equipment utilization rates.
United States
Commercial warehouse operators in Arizona and Texas accelerate evaporative retrofits as EPA WaterSense procurement eligibility opens federal facility upgrade budgets. The US EPA certifies efficient equipment for government building mandates. Phoenix and Dallas-Fort Worth industrial parks absorb the bulk of ducted system installations.
India
BIS energy-efficiency labeling compresses manufacturer margins while forcing inverter-based cooling pad adoption across domestic production. The Bureau of Indian Standards mandates minimum performance thresholds for cooling appliances. Ahmedabad and Surat anchor demand concentration in Gujarat's sub-40% humidity manufacturing belt.
Australia
Livestock housing and greenhouse operators adopt roof-mounted evaporative plants as water-use restrictions tighten in drought-prone agricultural zones. The country's national water regulator imposes usage caps that favor adaptive pump technology. Victoria's dairy corridor and Queensland's poultry belt drive specification intensity.
Germany
Industrial facility managers face stranded asset risk from EU F-Gas Regulation hydrofluorocarbon phase-down deadlines through 2030. The European Commission's refrigerant restrictions eliminate conventional AC retrofit options. Bavaria's automotive component plants and North Rhine-Westphalia logistics hubs evaluate refrigerant-free alternatives.
China
MIIT efficiency standards for cooling equipment push manufacturers toward variable-frequency drive integration in industrial-grade systems. The Ministry of Industry and Information Technology governs appliance performance certification. Pearl River Delta electronics factories and Yangtze River Delta logistics centers concentrate procurement volume.
Evaporative Air Cooler Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with residential portable markets favoring recognized consumer brands while industrial ducted specifications flow through direct sales relationships. The vendor base organizes into three tiers: integrated building automation providers, cooling pad component specialists, and regional assembly operations. Consolidation pressure concentrates in the middle tier as procurement models favor single-source contracts. Capacity expansion and technology licensing represent the dominant competitive moves.
Among India-based branded specialists, Symphony Ltd and Bajaj Electricals occupy positions within the consumer appliance tier, leveraging captive distribution infrastructure across tier-two cities. Honeywell International anchors the industrial control systems segment through building automation protocol integration. Shenzhen Lianchuang Technology Group exemplifies the scale-driven contract manufacturing archetype serving OEM specification channels.
| Leading Market Players |
|---|
| Symphony Ltd |
| Bajaj Electricals |
| Honeywell International |
| Aolan Industry |
| Hessaire Products |
| Shenzhen Lianchuang Technology Group |
| Midea Group |
| Seeley International |
| Portacool |
| Others |
Cost & Logistics Intelligence
Skilled ducted-installation technicians in Gujarat's industrial corridor command wage premiums that compress margins for custom-engineered systems while widening spreads between premium specification and economy portable units. Labor-cost differentials between certified industrial installers and residential retail channels separate pricing tiers more sharply than raw material inputs.
Pricing Analysis
Short lead-time premiums apply to EPA WaterSense-certified smart coolers needed for federal procurement deadlines, while spot inventory of legacy portable units trades at discounts. Three-tier pricing structure across premium smart systems, standard direct evaporative units, and economy portable coolers separates buyers by certification level and customization depth. Cost compression in the standard tier intensifies as inverter-based cooling pad adoption spreads under BIS mandates. Residential buyers in India's tier-two cities exhibit highest price sensitivity; commercial warehouse operators demonstrate lowest sensitivity due to operational expenditure reduction priorities.
Supply Chain Analysis
Freight cost volatility from China and India to European and North American distribution hubs pressures landed costs for cellulose cooling pad media and variable-frequency drive components. Manufacturing concentrates in China, India, and Mexico for finished assemblies, with component sourcing from Taiwan and South Korea for sensor subsystems. Supply chain risk centers on single-source vulnerability for specialized pump assemblies. Distribution runs through captive regional networks in India, direct sales relationships for industrial projects, and e-commerce platforms for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The evaporative air cooler market is becoming a vertical-integration race as manufacturers pursue captive control over cooling pad media production to defend margin structures against BIS compliance costs.
For Market Incumbents: Extend building automation protocol integration to capture procurement consolidation in commercial warehousing. Add certified installation capacity in Gujarat's industrial corridor to compress deployment timelines. Defend against falling heat pump substitution threats by emphasizing refrigerant-free compliance under EU F-Gas Regulation deadlines. For New Entrants and Emerging Players: Agricultural greenhouse operators in drought-prone Australian zones represent an underserved buyer archetype with unmet demand for adaptive pump technology. Tier-two city residential markets in India offer penetrable volume for BIS-compliant portable coolers. Pursue EPA WaterSense certification as the fastest go-to-market angle for federal procurement eligibility. For Investors and Strategic Acquirers: Re-rating potential sits with industrial control system specialists given building automation convergence catalysts. Long-term viability favors vendors with unified hardware-software architectures over component assemblers. Acquisition targets should demonstrate captive distribution infrastructure or certified pad media production. Watch BIS compliance timeline acceleration as the inflection signal for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooling Pad Media | Captive cellulose and synthetic media production defends margins against BIS certification cost inflation. |
| Building Automation Protocol Integration | Honeywell-compatible control architectures unlock premium specification channels in commercial warehousing. |
| EPA WaterSense Certification Program | Federal procurement eligibility opens government facility upgrade budgets in Arizona and Texas. |
| Variable-Frequency Drive Technology Licensing | MIIT-compliant efficiency standards in China accelerate adoption across Pearl River Delta electronics factories. |
| Certified Installation Network Expansion | Qualified technician scarcity in Gujarat compresses deployment timelines for ducted industrial systems. |
Research Approach
Multi-period observation of BIS compliance timelines, EPA WaterSense certification volumes, and EU F-Gas Regulation implementation anchored the trend analysis, supplemented by interviews with plant engineers, warehouse facility managers, cooling pad material suppliers, and building automation integrators. Secondary validation drew from Bureau of Indian Standards filings, EPA procurement databases, EU regulatory impact assessments, and customs trade records for cooling equipment. Bottom-up shipment data triangulated against top-down energy consumption projections across the analysis window.
Segment-weighting applied differential growth assumptions to smart coolers, direct evaporative systems, portable units, and ducted configurations, with end-user intensity scores for industrial, commercial, residential, and agricultural applications. CAGRs derived from installed base turnover rates, replacement cycle compression, and regulatory displacement effects. Forecast inputs incorporated wet-bulb climate zone mapping and water-use restriction severity indices for drought-prone jurisdictions.
Revisions become necessary when EU F-Gas Regulation phase-down schedules accelerate, BIS testing protocols expand to additional pad materials, or heat pump cost curves shift substitution economics in temperate zones. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market