
 Global Retail Management Systems Software Market | 2026-2036
Global Retail Management Systems Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail Management Systems Software Market Foresight
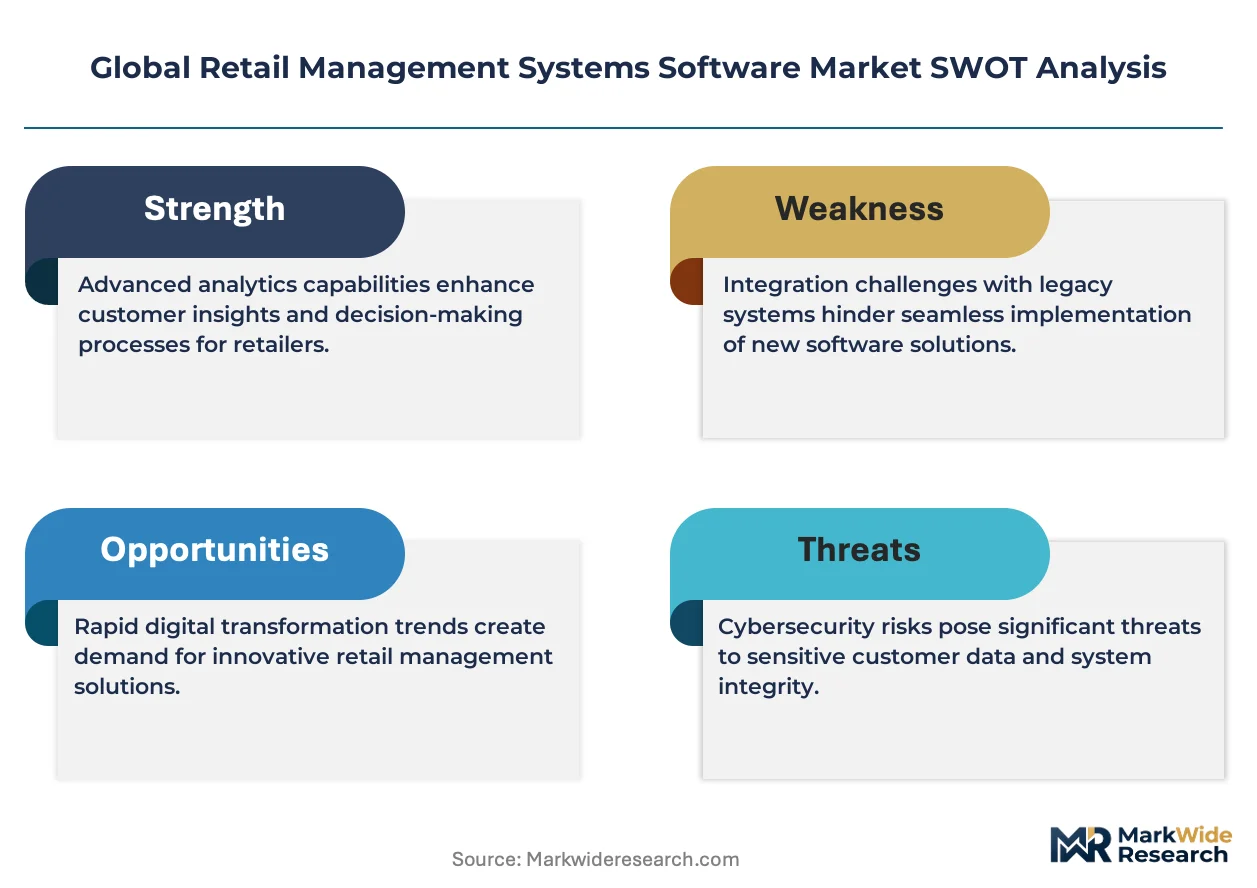
Legacy server infrastructure is shifting toward containerized cloud-native architectures across retail IT estates, collapsing total cost of ownership for multi-store operators. Oracle leverages its database heritage to anchor enterprise-grade inventory management deployments across North American grocery chains. SAP SE competes through deep ERP integration that sustains renewal rates among European department store conglomerates. Microsoft Corporation differentiates via Azure-native retail tooling that extends Copilot AI capabilities into workforce scheduling and demand forecasting workflows.
Retail management systems software encompasses integrated applications that orchestrate point-of-sale transactions, inventory tracking, customer data management, and supply chain coordination through centralized databases with real-time synchronization across distributed store networks. Cloud-based deployment leads current uptake velocity as retailers abandon capital-intensive server maintenance for subscription scalability, while point-of-sale solutions capture disproportionate margin pools due to payment processing integration and hardware attachment revenues. Inventory management segments show fastest acceleration where RFID and computer-vision stock monitoring reduce shrinkage and automate replenishment triggers.
FDA food traceability rules, EU GDPR data residency mandates, and Japan's METI digital transformation incentives collectively shape product roadmaps and market access requirements for retail software vendors. The EU AI Act imposes algorithmic transparency obligations on automated pricing and recommendation engines, forcing vendors to embed explainability dashboards or risk exclusion from European procurement cycles. Stakeholders must weigh compliance investment against cloud migration timelines to avoid stranded on-premises assets as regulatory thresholds tighten.
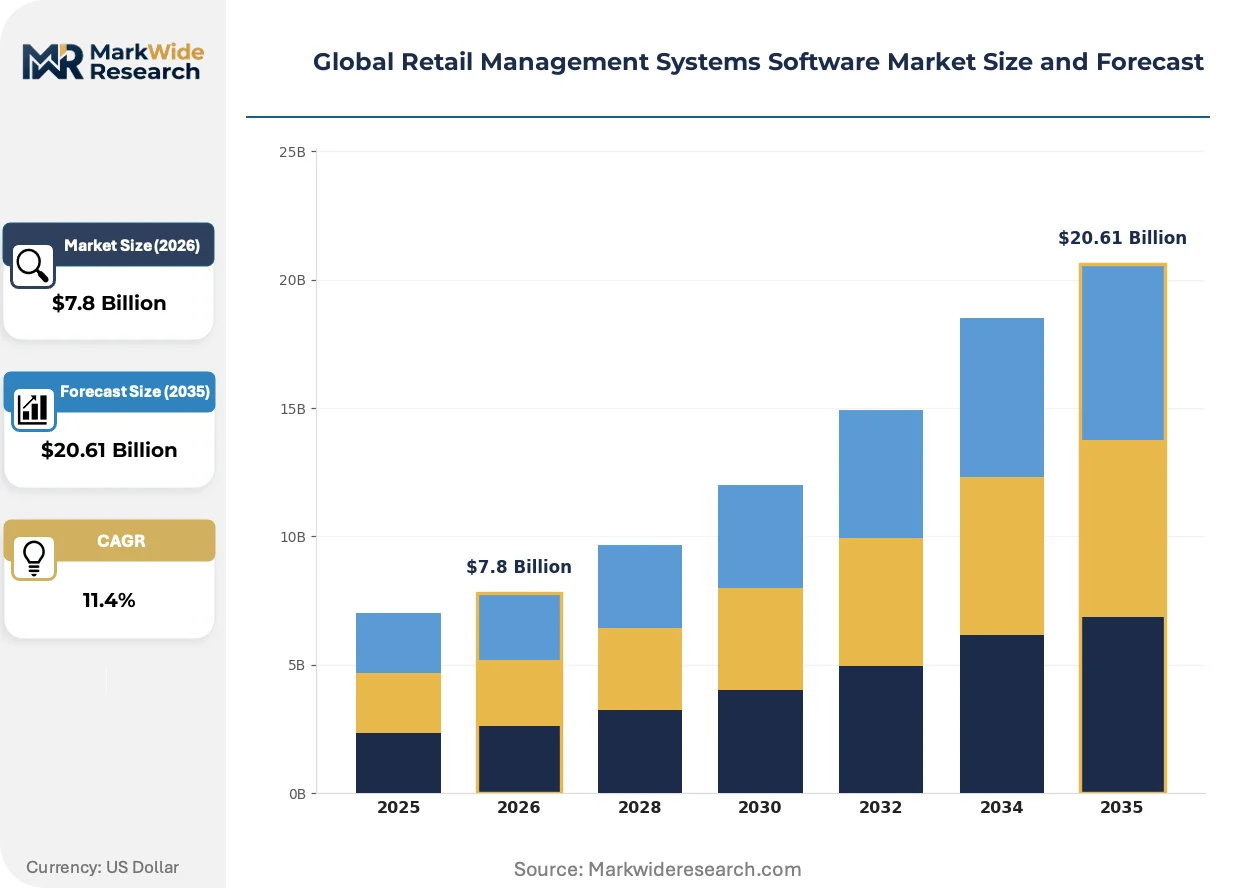
Market Dynamics
Cloud-native architecture is collapsing legacy on-premises infrastructure across multi-store retail operators, compressing total cost of ownership while embedding compliance modules directly into software stacks. This structural migration is reshaping vendor competitive positioning and procurement timelines simultaneously.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated pricing and recommendation engines now require explainability dashboards, forcing retailers to upgrade systems and creating replacement demand across European grocery and fashion segments.
- RFID and computer-vision inventory monitoring:Shrinkage reduction and automated replenishment triggers are accelerating adoption in large enterprise grocery chains across Germany, Japan, and the United States.
- METI digital transformation incentives:Japanese retail conglomerates are receiving government support for cloud migration, accelerating displacement of legacy server estates in the Asia-Pacific region.
Market Restraints
- GDPR data residency compliance costs:Multi-tenant cloud architectures face fragmentation as EU member states impose divergent localization interpretations, raising operational complexity for vendors serving cross-border retailers.
- Legacy ERP integration technical debt:Decades-old on-premises inventory databases in North American grocery chains resist API-native connectivity, prolonging hybrid-environment maintenance burdens.
- Specialized retail-tech talent scarcity:Shortages of engineers fluent in both payment processing protocols and container orchestration are constraining deployment velocity for mid-market operators.
Strategic Opportunities
- FDA food traceability rule compliance:Upcoming traceability mandates for fresh produce supply chains create embedded software demand for lot-tracking and supplier-verification modules in US grocery retail.
- Subscription-based SaaS pricing penetration:Small and mid-size fashion retailers in Italy and Spain remain underpenetrated by cloud-native POS solutions, representing greenfield conversion potential.
- Edge computing and 5G convergence:Real-time inventory synchronization across distributed store networks is enabling new architectures for pop-up and seasonal retail formats in urban Japan.
Industry Challenges
- Container orchestration skill gaps:Retail IT departments lack Kubernetes expertise for managing microservices-based POS deployments, forcing reliance on vendor-managed services at premium pricing.
- Payment processor certification timelines:PCI-DSS compliance validation for new cloud-native terminals stretches 8-14 months, delaying revenue recognition for hardware-software bundles.
- Legacy database migration complexity:Decades of transaction history in Oracle and SQL Server estates resist clean extraction, fragmenting customer 360-degree views during cloud transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail Management Systems Software Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, SaaS Solution Type: Point of Sale, Inventory Management, Customer Relationship Management, Supply Chain Management, Workforce Management Application: Fashion Outlets, Electronics Stores, Grocery Chains, Specialty Shops, Department Stores Customer Type: Small & Medium Enterprises, Large Enterprises, Franchises, Independent Retailers, Cooperatives |
| Companies Covered | Oracle, NCR Corporation, Microsoft Corporation, SAP SE, IBM Corporation, Blue Yonder Group, Epicor Software Corporation, LS Retail, Retail Pro International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail Management Systems Software Market Shifts & Advancements
Retail software architecture is converging around API-first platforms that embed compliance, analytics, and workforce tools into unified stacks. This integration is compressing vendor consolidation timelines and reshaping how retailers evaluate total cost of ownership.
Microservices-based POS platforms are consolidating transaction processing, inventory synchronization, and customer data management into single cloud-native stacks. Large grocery chains in Germany and Japan are deploying these architectures at scale, collapsing the traditional separation between front-end terminals and back-office systems. The structural consequence is that point-of-sale hardware vendors are losing attachment revenue as software subscriptions absorb their margin pools.
The EU AI Act's algorithmic transparency obligations are forcing explainability dashboards into automated pricing engines. European department store conglomerates must now document recommendation logic for regulatory audits, accelerating procurement of governance modules. Fashion retail segments with dynamic pricing algorithms face the steepest compliance investment requirements.
Outcome-based contracting is displacing perpetual-license models as retail procurement teams prioritize operational expenditure predictability. Large enterprise buyers in the United States are unbundling implementation services from software subscriptions, forcing vendors to compete on standalone platform value. This shift is most visible among grocery chains negotiating Azure-native workforce scheduling and demand forecasting tools.
Global Retail Management Systems Software Market Segmentation
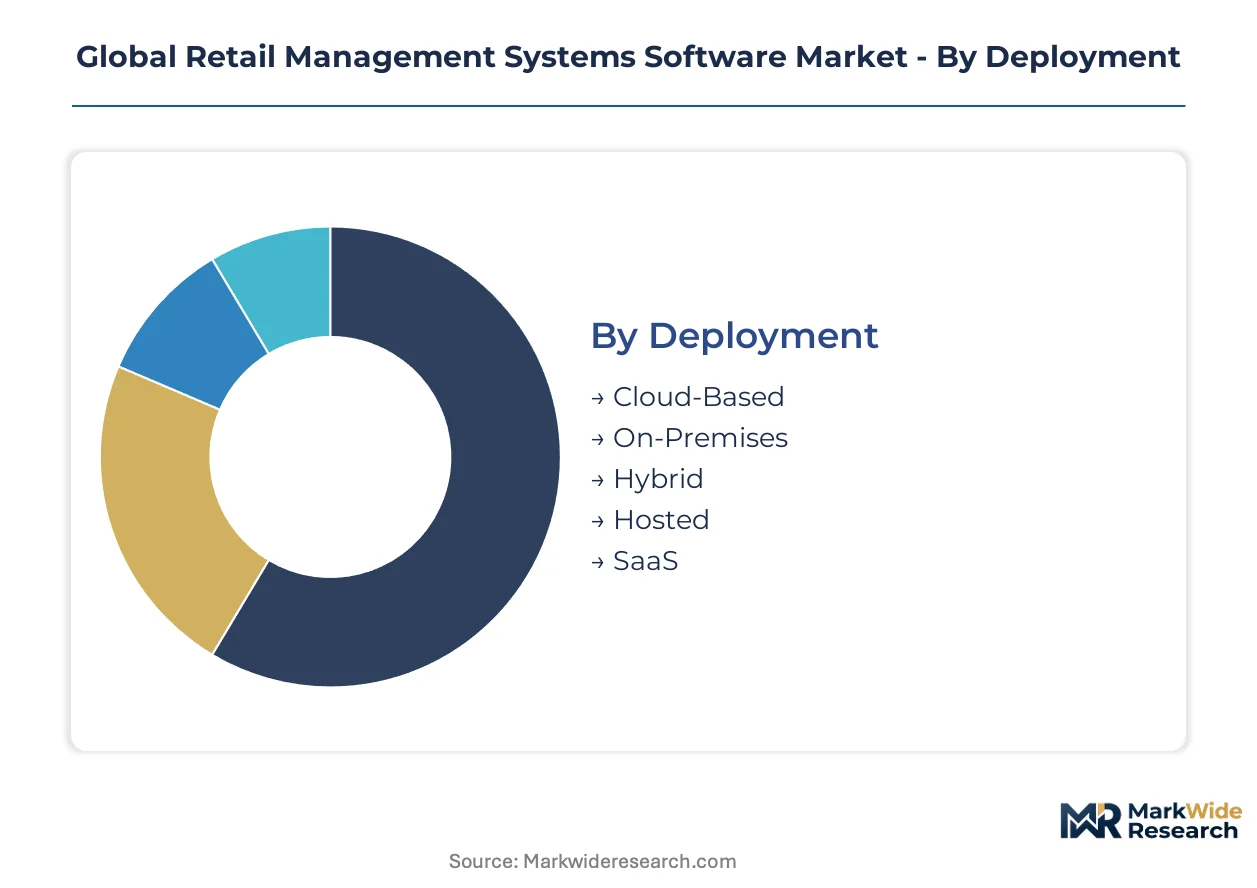
Retail software procurement fractures across four distinct segmentation axes, each revealing divergent margin pools and competitive intensity. Deployment mode determines capital structure and compliance architecture, while solution type governs vendor consolidation timelines.
Deployment:
Cloud-native architectures now dominate volume deployment, yet hybrid configurations capture premium pricing from risk-averse operators.
- Cloud-Based:Multi-tenant SaaS platforms with embedded GDPR data residency modules and automatic patch management. Demand concentrates in German grocery chains seeking EU AI Act compliance without on-premises server maintenance.
- On-Premises:Legacy server estates running Oracle or SQL Server databases with custom API layers. Japanese department store conglomerates retain these configurations where METI incentives have not yet displaced capital budgets.
- Hybrid:Split architectures with sensitive transaction data on local servers and analytics workloads in public cloud. US fashion retailers deploy these during PCI-DSS certification transitions.
- Hosted:Single-tenant private cloud managed by third-party data center operators. Italian mid-market cooperatives favor this model for perceived data sovereignty control.
- SaaS:Pure subscription models with per-terminal or per-store pricing. Spanish independent retailers represent underpenetrated conversion opportunity for POS vendors.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
Point-of-sale systems anchor vendor ecosystems through payment processing integration, while inventory management modules command fastest expansion.
- Point of Sale:Transaction terminals with embedded payment hardware, receipt printing, and customer-facing displays. US grocery chains deploy these with RFID-enabled self-checkout lanes reducing labor costs.
- Inventory Management:Stock monitoring platforms using computer vision and automated replenishment triggers. German electronics stores adopt these to minimize shrinkage in high-value product categories.
- Customer Relationship Management:Unified customer data platforms aggregating purchase history across channels. Japanese fashion outlets integrate these with loyalty programs and personalized recommendation engines.
- Supply Chain Management:Supplier coordination tools with lot-tracking for FDA food traceability compliance. US grocery chains prioritize these for fresh produce sourcing.
- Workforce Management:Scheduling and time-tracking platforms with AI-optimized shift allocation. Azure-native deployments with Copilot integration gain traction among large US retailers.
Point of Sale generates the deepest vendor lock-in. Inventory Management expands most quickly through RFID and vision-based automation.
Application:
Grocery chains drive compliance-heavy procurement, while fashion outlets prioritize customer experience tooling.
- Fashion Outlets:Dynamic pricing and recommendation engines requiring EU AI Act explainability dashboards. European department stores face steepest compliance investment.
- Electronics Stores:High-value inventory tracking with serialized warranty management. German retailers deploy computer vision for real-time stock monitoring.
- Grocery Chains:End-to-end traceability platforms for FDA food safety mandates. US operators consolidate point-of-sale, inventory, and supply chain into unified stacks.
- Specialty Shops:Niche workflow customization with limited standardization. Japanese artisan retailers favor modular SaaS configurations.
- Department Stores:Complex multi-category operations demanding deep ERP integration. SAP-anchored deployments sustain renewal rates across European conglomerates.
Grocery Chains anchor enterprise deal flow. Fashion Outlets represent greenfield cloud conversion.
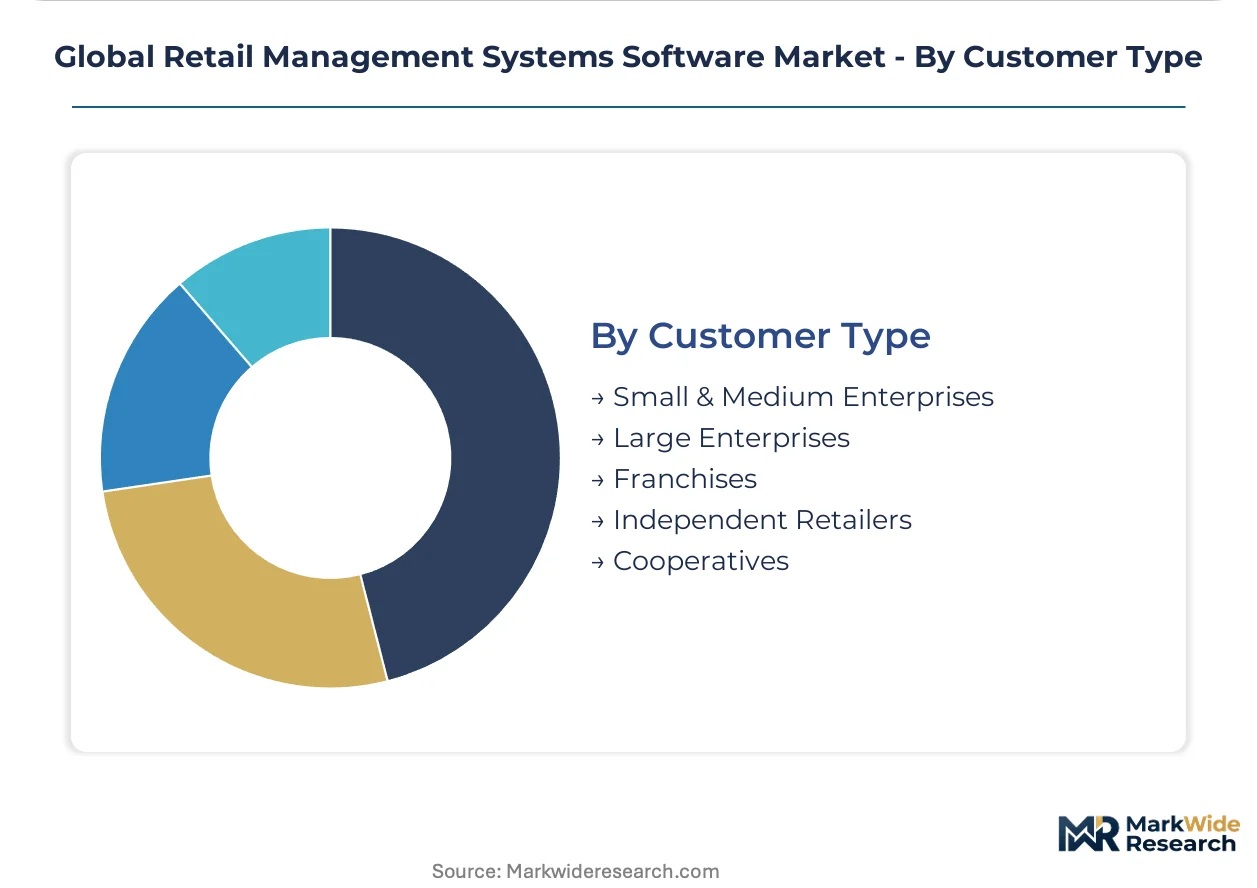
Customer Type:
Large enterprises consolidate vendor relationships, while franchises seek standardized multi-location tooling.
- Small & Medium Enterprises:Price-sensitive operators prioritizing subscription predictability over feature depth. Italian and Spanish fashion retailers remain underpenetrated.
- Large Enterprises:Multi-store operators with dedicated IT procurement teams negotiating unbundled implementation services. US grocery chains drive Azure-native workforce management adoption.
- Franchises:Brand-mandated standardization across independently owned locations. Uniform POS configurations with centralized reporting dominate.
- Independent Retailers:Single-location operators with minimal technical staff. Vendor-managed services at premium pricing fill Kubernetes skill gaps.
- Cooperatives:Member-governed purchasing collectives negotiating group software licenses. German grocery cooperatives leverage collective bargaining for compliance module inclusion.
Large Enterprises command platform roadmap influence. Franchises offer volume scaling without customization burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German grocery conglomerates anchor enterprise procurement velocity for cloud-native retail management systems, with METI incentives and FDA traceability mandates simultaneously reshaping deployment timelines across Japan and the United States.
United States
Large grocery chains drive Azure-native workforce scheduling adoption, unbundling implementation services from software subscriptions. FDA food traceability rules for fresh produce supply chains accelerate lot-tracking module procurement. Chicago-based retail cooperatives negotiate group licenses for compliance-embedded POS stacks.
Germany
Department store conglomerates sustain SAP-anchored ERP renewal rates through deep integration requirements. EU AI Act algorithmic transparency mandates force explainability dashboard upgrades for dynamic pricing engines. Berlin and Munich clusters concentrate cloud migration projects among multi-category operators.
Japan
Retail conglomerates leverage METI digital transformation incentives to displace legacy server estates. Fashion outlets in Tokyo and Osaka integrate customer data platforms with loyalty-driven recommendation engines. Kanto region operators pilot edge-computing architectures for real-time inventory synchronization.
United Kingdom
Fashion retailers face GDPR data residency compliance costs amid divergent EU member state localization interpretations. London-based department stores prioritize subscription predictability over perpetual-license models. Midlands grocery cooperatives explore hybrid deployments during PCI-DSS certification transitions.
Italy
Mid-market fashion retailers in Milan and Rome remain underpenetrated by cloud-native POS solutions, representing greenfield conversion potential. Vendor-managed services fill Kubernetes skill gaps among independent operators. Regional cooperatives favor hosted single-tenant models for perceived data sovereignty control.
Global Retail Management Systems Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors embed compliance modules directly into cloud-native stacks. The vendor base consolidates around three tiers: database-heritage incumbents anchoring enterprise grocery deployments, ERP-integrated suites sustaining European department store renewals, and Azure-native challengers capturing workforce management deal flow. Two competitive vectors define positioning: M&A activity targeting RFID and computer-vision capabilities, and outcome-based contracting displacing perpetual-license structures.
Within the database-heritage tier, Oracle Corporation exemplifies enterprise-grade inventory management anchoring. SAP SE occupies the ERP-integrated position for European conglomerates. Microsoft Corporation represents the cloud-native challenger vector through Azure-retail tooling extension. These three entities collectively illustrate how vendor archetypes map to procurement priorities across grocery, fashion, and department store segments.
| Leading Market Players |
|---|
| Oracle |
| NCR Corporation |
| Microsoft Corporation |
| SAP SE |
| IBM Corporation |
| Blue Yonder Group |
| Epicor Software Corporation |
| LS Retail |
| Retail Pro International |
| Others |
Supply & Pricing Matrix
Containerized cloud-native architectures are collapsing legacy on-premises infrastructure costs while concentrating vendor pricing power among hyperscale platform providers serving multi-store grocery operators across Germany, Japan, and the United States.
Pricing Analysis
Input-cost pass-through from embedded compliance modules and payment processor certification fees sustains subscription pricing elevation for cloud-native retail stacks. SaaS-tiered pricing stratifies across enterprise, mid-market, and independent retailer tiers based on terminal count and GDPR data residency requirements. Pricing pressure stems from outcome-based contracting displacing perpetual-license models as US grocery chains unbundle implementation services. Independent retailers in Italy and Spain exhibit highest price sensitivity due to minimal technical staffing, while German department store conglomerates absorb premium pricing for SAP-anchored ERP integration.
Supply Chain Analysis
Logistics and freight cost concentration for payment terminal hardware and edge-computing infrastructure feeds from manufacturing clusters in Taiwan, China, and South Korea. Semiconductor components for RFID readers and computer-vision cameras draw from the same East Asian supply base, while cloud infrastructure services center on US and EU hyperscale data center regions. Single-source vulnerability concentrates in specialized payment processor chipsets subject to PCI-DSS certification delays. Distribution runs through vendor-managed service channels for Kubernetes-orchestrated deployments, with direct hardware-software bundles reaching large enterprise grocery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between METI-subsidized cloud migration in Japan and GDPR compliance cost burdens across European Union member states diverging on data localization interpretations.
For Market Incumbents: Hedge against Azure-native challengers by embedding FDA food traceability modules directly into inventory management stacks before regulatory deadlines tighten. Acquire computer-vision specialists to anchor shrinkage-reduction value propositions in German grocery chains. Deepen vertical integration into payment processor certification pipelines to compress 8-14 month PCI-DSS validation timelines. For New Entrants and Emerging Players: Capture greenfield conversion among Italian and Spanish mid-market fashion retailers where cloud-native POS penetration remains underdeveloped. Target vendor-managed service models that fill Kubernetes skill gaps among independent operators without internal platform engineering capacity. Lead with subscription predictability messaging against perpetual-license incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among hosted single-tenant private cloud operators serving data-sovereignty-sensitive cooperatives in Southern Europe. Long-term viability hinges on regulatory compliance automation capabilities across the FDA-EU AI Act-GDPR enforcement triangle. Watch for FDA food traceability rule finalization as demand inflection signal for lot-tracking module vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Computer-Vision Specialist | RFID-enabled shrinkage reduction anchors enterprise grocery renewal rates in Germany. |
| Embedded Compliance Module Development | EU AI Act explainability dashboards lock out non-compliant vendors from European procurement. |
| Outcome-Based Contracting Transition | Operational expenditure predictability displaces perpetual-license structures among US retailers. |
| Edge-Computing Architecture Pilot | Real-time inventory synchronization enables pop-up retail formats in urban Japan. |
| Payment Processor Certification Pipeline | PCI-DSS validation compression accelerates revenue recognition for hardware-software bundles. |
Research Methodology
Multiple input streams — executive interviews with retail CIOs and procurement directors, technical validation with platform engineers and integration specialists, and secondary reconciliation against SEC filings and hyperscaler capex disclosures — were synthesized through bottom-up and top-down triangulation. Primary fieldwork captured deployment timelines across cloud-native, hybrid, and on-premises configurations. Secondary sources included FDA regulatory dockets, EU AI Act implementation guidance, METI digital transformation incentive documentation, and trade data from customs records.
Historical spending patterns were cross-referenced against panel input from retail software procurement committees to construct analytical frameworks across deployment mode, solution type, application vertical, organization size tier, and regional adoption cluster. CAGRs were derived from segment-level trajectory modeling incorporating compliance investment cycles and cloud migration velocity indicators. Forecast inputs included RFID hardware cost curves, payment processor certification queue lengths, and workforce management AI adoption rates.
Underlying measurement precision varies by segment; cloud-based deployment and point-of-sale solution categories carry tighter precision than specialty shop and cooperative sub-segments where standardization remains limited. Forecasts reflect documented assumptions about regulatory enforcement timelines and hyperscale platform pricing trajectories. Stakeholders should weight assumptions against their own operating context and compliance investment horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Voip Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
France Digital Marketing Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Cursor Reviewer Market
Software & Services
Content Marketing Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Fiber Simulation Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Tag Management Software Market
Software & Services
Photobooth Software Market