
 Fiber Simulation Software Market | 2026-2036
Fiber Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Simulation Software Market Insights
Buyer concentration in the telecommunications sector is expanding as tier-one carriers consolidate vendor relationships around integrated fiber simulation suites. Ansys leverages its multiphysics platform to anchor enterprise contracts across network equipment manufacturers. RP Photonics specializes in laser and fiber physics models that dominate European research institutions. VPIphotonics competes through component-level optical simulation tools tailored to submarine cable designers.
Fiber simulation software encompasses computational platforms that model light propagation, nonlinear effects, and structural mechanics in optical fibers with wavelength precision down to nanometer scales. These tools enable engineers to predict signal degradation, thermal drift, and mechanical failure before physical prototyping across telecommunications and sensing systems. Optical fiber modeling commands the largest revenue pool as submarine and terrestrial cable investments require precise chromatic dispersion prediction. Cloud-based deployment is accelerating fastest among mid-sized component vendors seeking elastic compute for parametric sweeps. Network simulation retains entrenched positions in defense procurement cycles where on-premises security mandates persist.
FCC broadband deployment mandates in the United States and EU Green Deal connectivity targets through the Digital Decade program are elevating simulation accuracy requirements for publicly funded infrastructure projects. ETSI standards for optical network interoperability further compel vendors to validate models against certified reference measurements. Stakeholders must monitor how quantum communication roadmaps in China and South Korea reshape fiber nonlinear optics modeling priorities.
Market Dynamics
Telecommunications carriers are consolidating vendor relationships around integrated fiber simulation suites as 5G backhaul deployment accelerates and EU cybersecurity certification mandates reshape procurement criteria.
Growth Catalysts
- EU Cybersecurity Act certification:European vendors must validate simulation platforms against harmonized standards, creating pull for compliant software suites among network equipment manufacturers.
- 5G backhaul network expansion:Tier-one carriers require precise chromatic dispersion modeling for dense wavelength division multiplexing deployments in urban fiber rings.
- Germany's photonics cluster concentration:Berlin and Munich host dense concentrations of research institutions driving demand for nonlinear optics simulation tools.
Market Restraints
- Specialized talent scarcity:The pool of engineers proficient in both optical physics and computational modeling remains shallow across all major markets.
- High-performance computing infrastructure costs:Parametric sweeps at nanometer-scale wavelength precision demand elastic cloud compute that strains mid-sized vendor budgets.
- Defense procurement security mandates:On-premises deployment requirements for classified projects limit addressable market for SaaS-native platforms.
Strategic Opportunities
- Quantum communication roadmaps:China and South Korea are investing in fiber-based quantum key distribution, requiring new nonlinear optics modeling capabilities.
- Cloud-native deployment models:Mid-sized component vendors seek subscription-based simulation access to replace perpetual license overhead.
- EU Digital Decade connectivity targets:Green Deal-funded infrastructure projects mandate simulation accuracy documentation for public tender compliance.
Industry Challenges
- ETSI interoperability validation timelines:Model certification against reference measurements extends sales cycles by six to twelve months for European deployments.
- Legacy on-premises integration complexity:Defense and intelligence agencies require air-gapped simulation environments that resist API-first architectures.
- Cross-functional physics expertise gaps:Teams must bridge structural mechanics, thermal drift, and electromagnetic propagation domains simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Simulation Software Market |
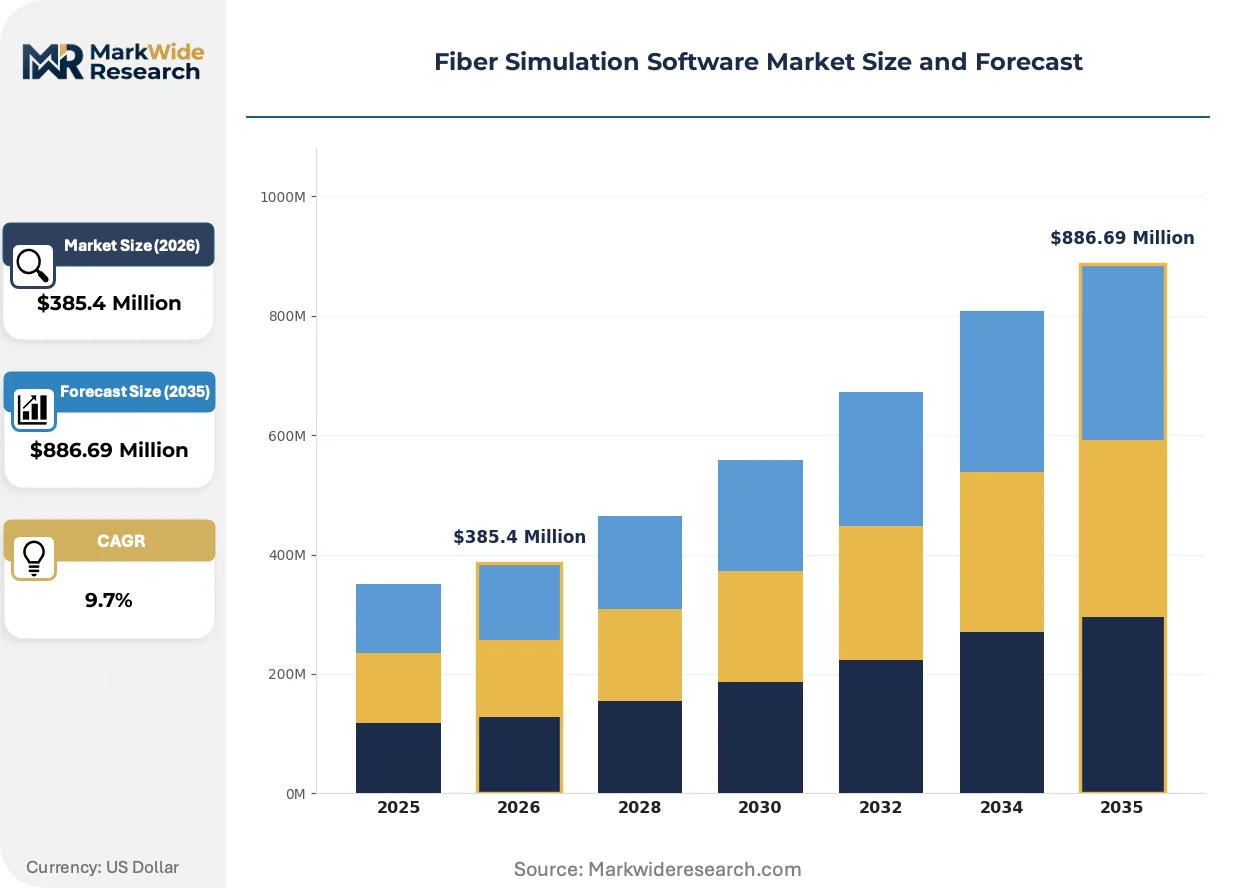
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Simulation, Optical Fiber Modeling, Network Simulation, Waveguide Analysis End User: Telecommunications, Aerospace, Defense, Academia Deployment: On-Premises, Cloud-Based, Hybrid, Desktop Application: Network Design, Performance Analysis, Fault Diagnosis, Testing |
| Companies Covered | RP Photonics, VPIphotonics, Ansys, Optiwave Systems, Photon Design, CodeSeeder, CodeSScientific, Humanetics Group, Synopsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Simulation Software Market Trends and Innovations
Computational photonics is converging with cloud infrastructure and regulatory compliance frameworks, reshaping how optical fiber models are developed, validated, and deployed across telecommunications and sensing applications.
GPU-accelerated wave propagation solvers are decentralizing high-fidelity chromatic dispersion calculations from centralized supercomputing centers to distributed engineering workstations. Submarine cable designers at component manufacturers now run parametric sweeps locally that previously required batch queue access. This capability compression is collapsing iteration cycles for transoceanic link feasibility studies.
ETSI standards for optical network interoperability are mandating model validation against certified reference measurements before procurement authorization. European network operators now require documentation traceability for all simulation parameters used in publicly funded infrastructure bids. Vendors are responding by embedding metrology-grade uncertainty quantification into their solver architectures.
Subscription licensing for elastic compute resources is displacing perpetual seat licenses among mid-sized photonics component vendors. Procurement teams favor operational expenditure models that scale with project pipeline volatility rather than fixed capital commitments. This pattern is most visible in Germany's Mittelstand manufacturing base, where seasonal contract fluctuations make capacity planning unpredictable.
Fiber Simulation Software Market Segmentation
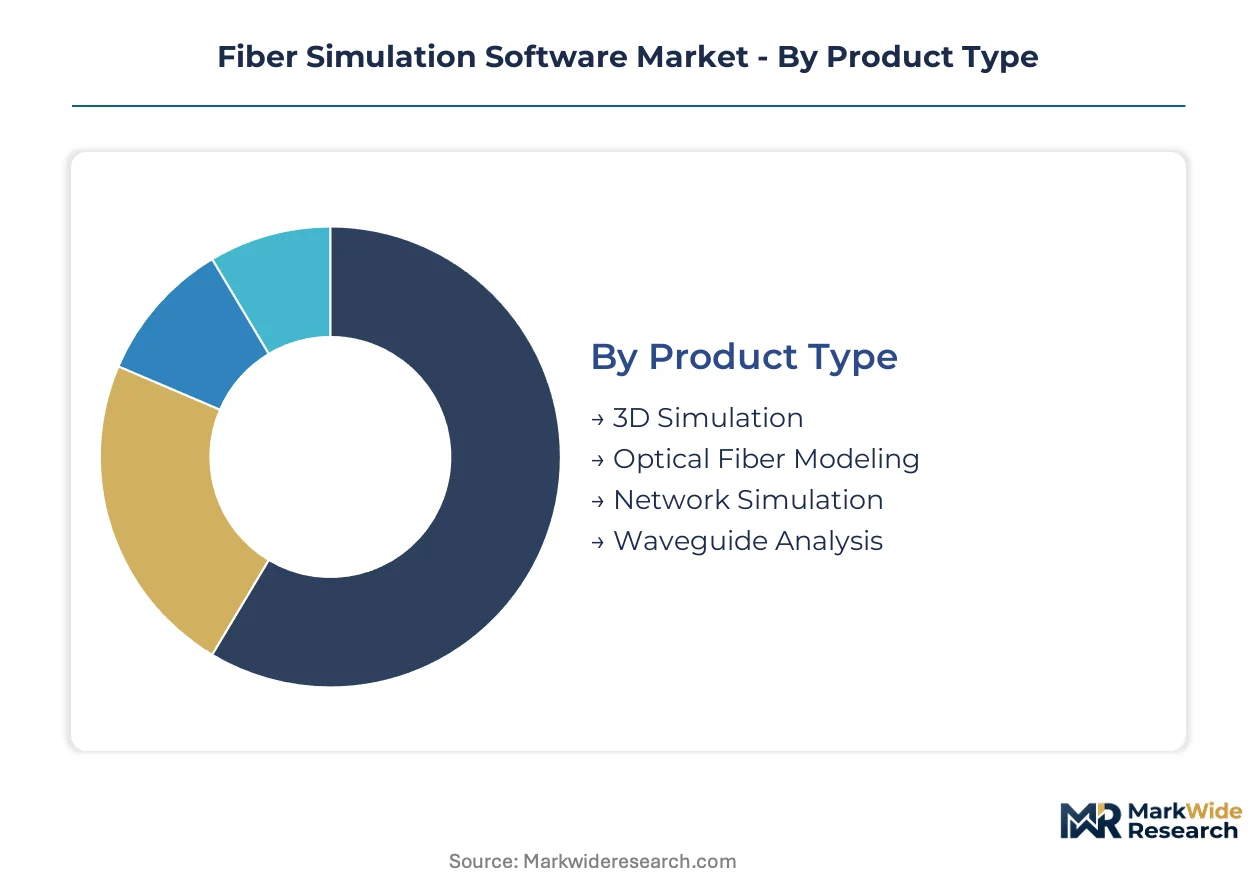
Segmentation in fiber simulation software reveals how technical specifications, security requirements, and computational architectures fragment purchasing decisions across telecommunications infrastructure, defense procurement, and research applications. Understanding these divisions exposes where vendor specialization creates pricing power and where platform consolidation threatens niche players.
Product Type:
Technical sophistication and wavelength precision requirements differentiate product tiers, with nanometer-scale accuracy commanding premium positioning in submarine cable and quantum communication applications.
- Optical Fiber Modeling:Platforms simulate chromatic dispersion, nonlinear effects, and thermal drift in single-mode and multimode fibers with precision down to nanometer scales. Telecommunications carriers in Germany's photonics cluster around Berlin and Munich deploy these tools for dense wavelength division multiplexing feasibility studies in 5G backhaul networks.
- Network Simulation:System-level tools model end-to-end signal propagation across terrestrial and submarine cable topologies, incorporating amplifier chains and routing protocols. EU Cybersecurity Act certification requirements are pushing European network operators toward validated platforms with documented parameter traceability for publicly funded infrastructure tenders.
- 3D Simulation:Structural mechanics solvers predict mechanical failure modes and bending losses in fiber packaging and deployment scenarios.
- Waveguide Analysis:Specialized packages address photonic integrated circuit design for datacenter interconnect applications.
Optical Fiber Modeling leads on scale; Network Simulation leads on momentum.
End User:
Procurement authority concentrates differently across sectors, with defense and telecommunications commanding multi-year enterprise contracts while academia sustains niche specialist vendors through research licensing.
- Telecommunications:Tier-one carriers consolidate vendor relationships around integrated suites spanning component design through network topology optimization. FCC broadband deployment mandates and EU Digital Decade connectivity targets elevate simulation accuracy requirements for infrastructure projects receiving public funding.
- Defense:Classified programs mandate on-premises, air-gapped deployment environments resistant to cloud-native architectures. Procurement cycles extend twelve to eighteen months as agencies validate models against reference measurements and security protocols.
- Aerospace:Satellite and avionics fiber sensing applications demand radiation-hardened fiber characterization tools.
- Academia:Research institutions in Germany and South Korea drive demand for nonlinear optics modeling capabilities supporting quantum communication roadmaps.
Telecommunications dominates contract value; Defense anchors pricing premiums.
Deployment:
Capital expenditure flexibility and data sovereignty requirements create a three-way split between perpetual licensing, elastic cloud consumption, and hybrid architectures bridging both models.
- Cloud-Based:Subscription models provide elastic compute for parametric sweeps without supercomputing center queue access. Germany's Mittelstand component manufacturers favor operational expenditure structures that scale with seasonal contract volatility.
- On-Premises:Air-gapped installations satisfy defense and intelligence agency security mandates for classified simulation work. High-performance computing infrastructure costs strain mid-sized vendor budgets when scaling to nanometer-precision wavelength sweeps.
- Hybrid:Mixed architectures allow sensitive model development on-premises with burst compute to cloud for large parameter studies.
- Desktop:GPU-accelerated solvers now enable workstation-level chromatic dispersion calculations previously requiring centralized resources.
On-Premises retains the highest contract values; Cloud-Based gains share fastest.
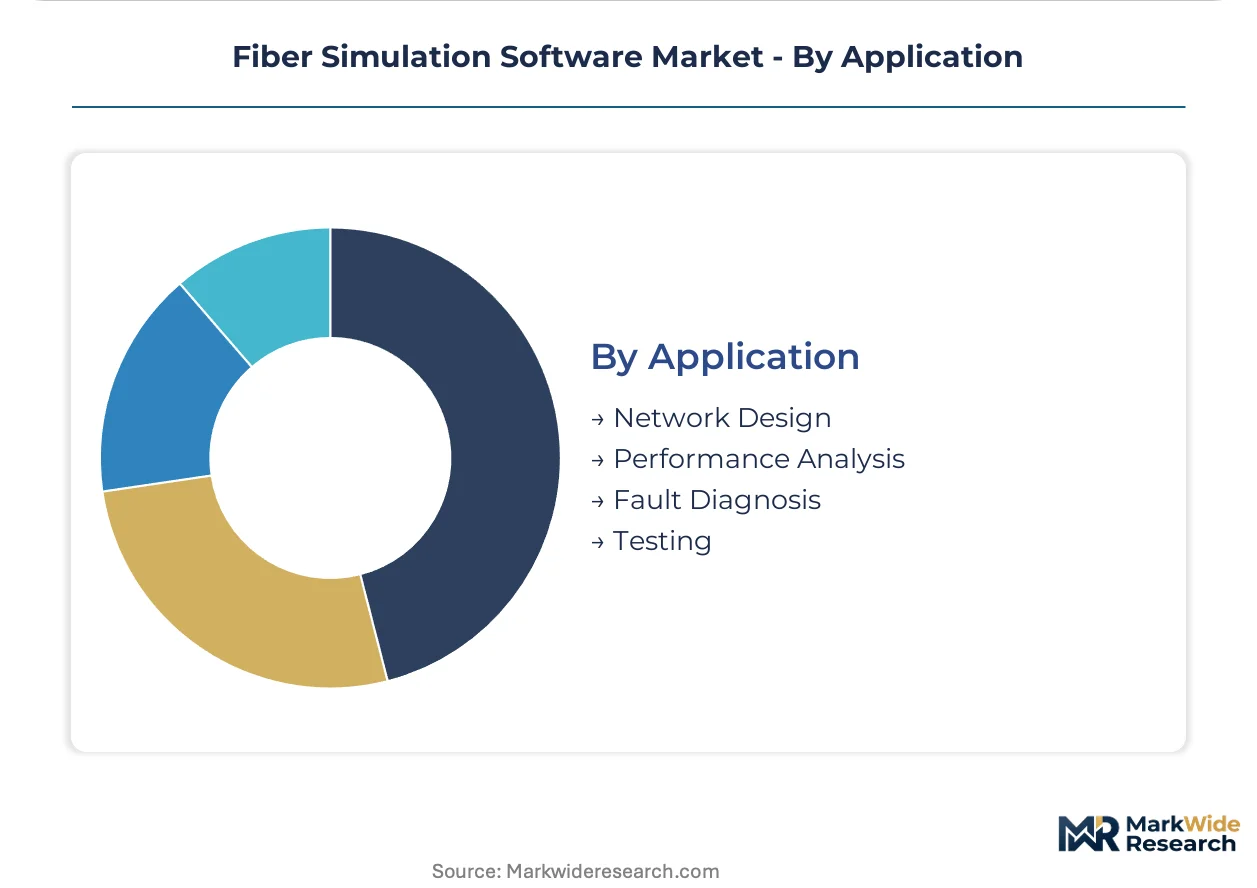
Application:
Use case complexity spans predictive design, real-time monitoring, and forensic analysis, with each imposing distinct computational and validation requirements on solver architectures.
- Network Design:Topology optimization tools model amplifier placement, dispersion compensation, and route diversity for transoceanic and metropolitan fiber rings. ETSI interoperability standards mandate model validation against certified reference measurements, extending European sales cycles.
- Performance Analysis:Signal quality prediction under varying load and environmental conditions supports capacity planning and upgrade scheduling.
- Fault Diagnosis:Root-cause analysis tools correlate measured impairments with modeled degradation mechanisms.
- Testing:Automated test case generation validates hardware prototypes against simulation predictions prior to field deployment.
Network Design captures the largest project budgets; Performance Analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's photonics cluster concentration contrasts with the United States' defense-driven procurement patterns, while South Korea's quantum communication investments and China's infrastructure scale create distinct demand profiles across major markets.
United States
FCC broadband deployment mandates and defense procurement cycles anchor demand for validated simulation platforms. Tier-one carriers consolidate vendor relationships around integrated suites for 5G backhaul optimization. Greater Boston and Silicon Valley host dense concentrations of network equipment manufacturers deploying chromatic dispersion modeling tools.
Germany
EU Cybersecurity Act certification requirements reshape procurement criteria for network operators. The Digital Decade connectivity targets elevate simulation accuracy documentation requirements for publicly funded tenders. Berlin and Munich photonics clusters drive concentrated demand for nonlinear optics modeling capabilities among research institutions and component vendors.
China
National quantum communication roadmaps and submarine cable expansion programs require advanced fiber nonlinear optics modeling. MIIT standards for optical network interoperability compel model validation against certified reference measurements. Yangtze River Delta manufacturing bases deploy simulation tools for dense wavelength division multiplexing feasibility studies.
South Korea
Government-backed quantum key distribution investments create demand for specialized nonlinear optics simulation capabilities. MFDS-aligned research programs fund fiber characterization tool development at national laboratories. Seoul Capital Area concentrations of telecommunications equipment manufacturers anchor enterprise contract values.
Japan
METI-supported photonics initiatives and datacenter interconnect investments drive waveguide analysis tool adoption. JIS standards compliance requirements extend validation timelines for European and American software vendors. Kanto region technology clusters concentrate procurement authority for multi-year simulation platform contracts.
Fiber Simulation Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated market structure where scale advantages clash with domain depth. Tier-one carriers favor integrated multiphysics platforms that span component design through network topology optimization. Research institutions and mid-sized component vendors gravitate toward specialized tools with nanometer-scale wavelength precision. Consolidation pressures intensify as defense procurement security mandates and EU certification requirements raise barriers to market entry.
Within the specialized physics modeling tier, RP Photonics and VPIphotonics exemplify divergent specialization strategies. RP Photonics occupies a position anchored in European research licensing structures, while VPIphotonics represents component-level optical simulation approaches tailored to submarine cable design workflows. Ansys sits within the diversified platform archetype, leveraging multiphysics breadth to anchor enterprise contracts across network equipment manufacturers.
| Leading Market Players |
|---|
| RP Photonics |
| VPIphotonics |
| Ansys |
| Optiwave Systems |
| Photon Design |
| CodeSeeder |
| CodeSScientific |
| Humanetics Group |
| Synopsys |
| Others |
Pricing and Supply Chain Analysis
Tier-one telecommunications carriers consolidating vendor relationships around integrated fiber simulation suites command substantial pricing leverage through multi-year enterprise contracts. Subscription licensing models displace perpetual seat licenses as procurement teams favor operational expenditure structures that scale with project pipeline volatility.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for elastic compute resources used in parametric wavelength sweeps. Pricing stratifies across nanometer-precision premium tiers for submarine cable designers, validated certification tiers for EU Cybersecurity Act compliance, and standard desktop tiers for mid-sized component vendors. Cost compression in cloud-native deployment is intensifying because GPU-accelerated solvers decentralize high-fidelity calculations from centralized supercomputing centers. Mid-sized photonics component manufacturers in Germany's Mittelstand exhibit highest price sensitivity, while defense procurement programs anchor premium pricing through air-gapped security mandates.
Supply Chain Analysis
EU Cybersecurity Act certification requirements and domestic-content preferences in South Korea's quantum communication programs are reshaping sourcing patterns for validated simulation platforms. Software development concentrates in Germany, the United States, and Japan, drawing from specialized optical physics expertise pools, high-performance computing infrastructure, and metrology-grade reference measurement datasets. Single-source vulnerability runs through concentrated photonics research clusters in Berlin and Munich. Distribution runs through direct enterprise sales for tier-one carriers and value-added resellers serving mid-sized component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU Digital Decade connectivity targets and FCC broadband mandates shift procurement toward simulation accuracy documentation and certified validation tiers.
For Market Incumbents: Anchor enterprise contract renewals through embedded multiphysics platform integration spanning component design through network topology optimization. Deepen backward integration into GPU-accelerated solver architectures to defend against cloud-native entrants. Prioritize ETSI interoperability certification investments to extend procurement moats as European sales cycles lengthen.
For New Entrants and Emerging Players: Quantum communication nonlinear optics modeling capabilities represent the most penetrable white-space wedge for specialized physics-first entrants. Target South Korea's government-backed quantum key distribution investments and China's national quantum roadmaps where incumbent platforms lack domain depth. Pursue research licensing structures with European photonics clusters as the primary go-to-market angle.
For Investors and Strategic Acquirers: Diversified multiphysics platform vendors are the most active acquirer in this space, consolidating specialized fiber physics capabilities to fill portfolio gaps. Acquisition target archetypes include pure-play nonlinear optics specialists with nanometer-scale wavelength precision and established European research licensing revenue streams. Monitor quantum communication procurement authorization timelines as the critical inflection signal for specialized modeling demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Ansys anchors enterprise contracts across network equipment manufacturers through multiphysics breadth. |
| Acquisition of Specialist Firm | Consolidation pressures intensify as EU Cybersecurity Act certification raises barriers to organic entry. |
| Product Launch | GPU-accelerated wave propagation solvers collapse iteration cycles for transoceanic link feasibility studies. |
| Strategic Partnership | Research institutions in Germany's photonics cluster sustain niche specialist vendors through licensing structures. |
| Geographic Expansion | Mid-sized component vendors in Germany's Mittelstand seek subscription-based simulation access for seasonal flexibility. |
Research Methodology
Bottom-up telecommunications carrier procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with network design engineers, defense procurement officers, photonics research directors, and simulation software product managers combined with secondary validation from ETSI standards documentation, FCC broadband deployment filings, EU Digital Decade program tenders, and hyperscaler capex disclosures. Top-down triangulation against installed base estimates and perpetual-to-subscription license conversion rates anchored volume projections.
Historical trendline analysis of optical fiber modeling tool adoption patterns across submarine cable, terrestrial telecommunications, and quantum communication applications informed growth trajectory assumptions. Segmentation dimensions modeled include product type precision tier, deployment architecture, end-user procurement authority, and regional regulatory cluster. CAGRs derived from elasticity-adjusted price-volume relationships and technology substitution curves. Industry-specific forecast inputs incorporate ETSI interoperability validation timeline extensions and quantum communication roadmap authorization schedules.
The model holds under stable EU Cybersecurity Act certification timelines and continued FCC broadband deployment funding; deviation in defense procurement security mandate stringency or quantum communication program acceleration would shift demand composition across deployment architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Decision Making Software Market
Software & Services
Global IVR Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
North America Automotive Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Construction Estimating Software Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Global Content Management Software Market
Software & Services
Harbor and Marina Management Software Market
Software & Services
PAC Programming Software Market
Software & Services
Mining Simulation Software Market
Software & Services
Salon Booking Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Global Idea Management Software Market
Software & Services
System Infrastructure Software Market