
 United Arab Emirates Portable Air Conditioning Market | 2026-2036
United Arab Emirates Portable Air Conditioning Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Portable Air Conditioning Market Insights
E-commerce fulfillment networks are reshaping how portable air conditioners reach UAE households. Gree leverages direct-to-consumer platforms to bypass traditional retail markups in Dubai and Abu Dhabi. LG sustains premium positioning through service partnerships with local installation contractors. Haier competes aggressively on seasonal promotional cycles tied to Ramadan and summer peak demand.
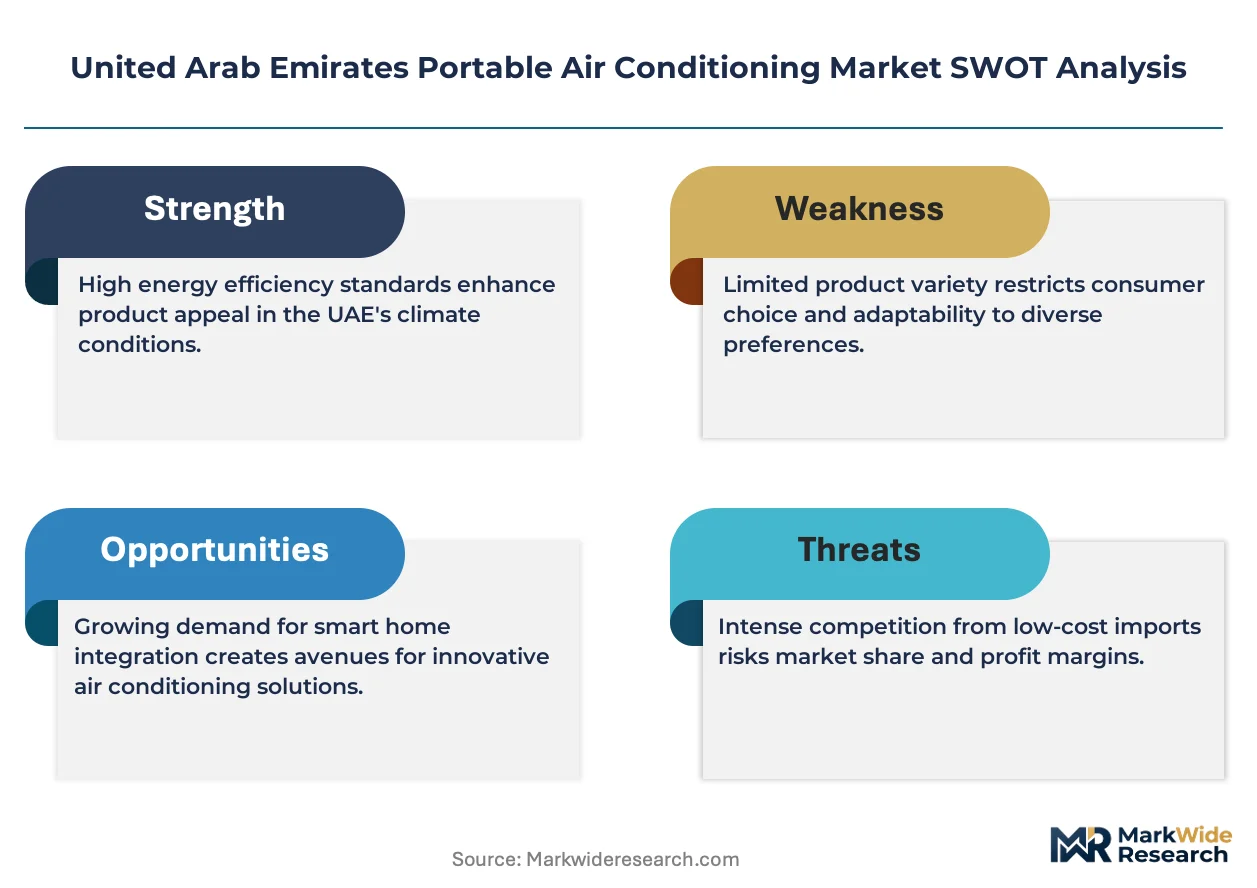
Portable air conditioning units are self-contained cooling systems, typically rated between 8,000 and 14,000 BTU per hour, using vapor-compression refrigeration with single-duct or dual-duct exhaust configurations designed for spaces lacking permanent HVAC infrastructure. The residential end user segment anchors volume demand as expatriate renters prioritize mobility over fixed installations. Smart control systems represent the fastest-growing interface category as Wi-Fi-enabled units gain traction among tech-savvy consumers in Dubai's apartment market. Energy Star Rated products command margin premiums despite higher upfront cost, reflecting electricity tariff sensitivity across UAE emirates.
MOHAP mandates energy efficiency labeling for all cooling appliances sold in the UAE, while Emirates Authority for Standardization and Metrology enforces ESMA compliance certification before market entry. These frameworks elevate compliance costs for new entrants but simultaneously filter out low-efficiency imports, tightening competitive pressure on non-inverter inventory. Stakeholders must monitor how Dubai's building retrofit mandates and Abu Dhabi's green building codes redirect demand toward portable solutions during construction-phase cooling gaps.
Market Dynamics
MOHAP efficiency labeling mandates are compressing demand toward inverter-based portable systems, forcing inventory turnover across Dubai and Sharjah distribution channels while rental housing operators accelerate replacement cycles.
Growth Catalysts
- Hospitality Refurbishment Cycles:Dubai's hotel upgrade wave generates temporary cooling gaps during HVAC infrastructure replacement, creating sustained procurement windows for portable units.
- MOHAP Labeling Mandates:The Ministry of Health and Prevention's energy efficiency requirements filter low-performance imports, elevating average selling prices for compliant inventory.
- Tenant Mobility Patterns:Expatriate renters in Sharjah's mid-density districts prioritize deployable cooling over fixed installations, anchoring residential volume demand.
Market Restraints
- Copper-Aluminum Input Volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margins for manufacturers without long-term supply agreements.
- Single-Duct Technical Limitation:Negative pressure effects in conventional exhaust configurations reduce cooling efficiency in high-humidity coastal zones, constraining performance claims.
- ESMA Certification Friction:Emirates Authority for Standardization and Metrology testing timelines extend market entry by 8-14 weeks for new product variants.
Strategic Opportunities
- Abu Dhabi Green Building Codes:Construction-phase cooling mandates during retrofit projects create portable AC deployment windows in commercial and residential towers.
- Wi-Fi Control Convergence:Integration of smart home protocols with vapor-compression systems opens premium pricing tiers among Dubai's tech-forward apartment segments.
- Direct-to-Consumer Channels:E-commerce fulfillment networks bypass traditional retail markups, capturing margin recovery from logistics infrastructure investments.
Industry Challenges
- Refrigerant Handling Certification:Technician licensing requirements for R32 and R410A systems constrain installation capacity during seasonal demand spikes.
- Legacy HVAC Integration Complexity:Portable units must interface with existing building management systems in commercial deployments, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Portable Air Conditioning Market |
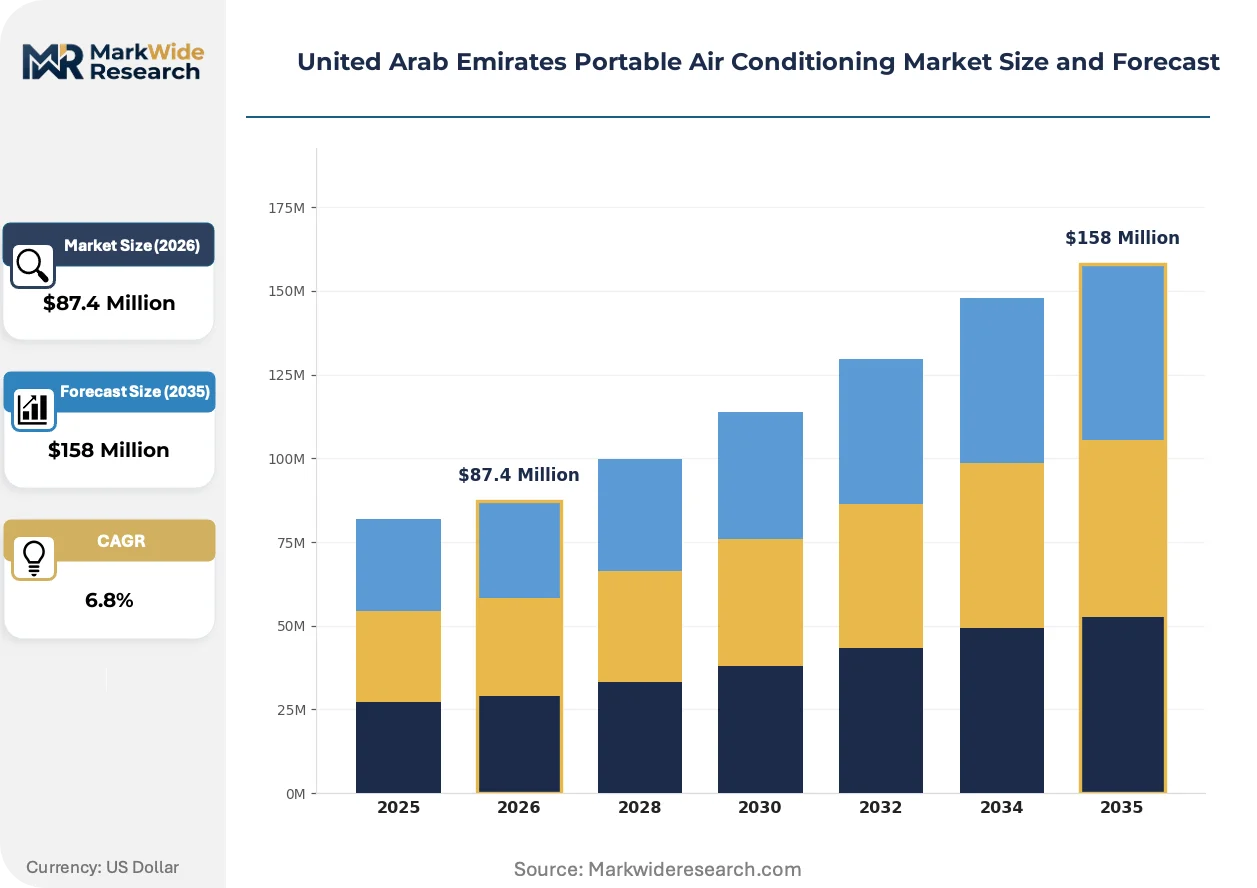
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window ACs, Split ACs, Portable ACs, Hybrid ACs Control Type: Remote Control, Smart Control, Manual Control, Touch Control Energy Efficiency: Inverter, Non-Inverter, Energy Star Rated, Standard End User: Residential, Commercial, Industrial, Retail |
| Companies Covered | Gree, Evvoli, Super General, AUX, Crownline, DeLonghi, LG, Haier, Whirlpool, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Portable Air Conditioning Market Trends and Innovations
Digital control architectures and regulatory efficiency mandates are restructuring product development priorities across UAE portable AC supply chains, with smart interfaces and inverter compressors dominating R&D allocation.
Variable-speed inverter compressors are virtualizing fixed-speed mechanical systems by enabling precise load matching rather than binary on-off cycling. Dubai hospitality operators specify these units for banquet halls and temporary event spaces where cooling loads fluctuate hourly. The technology is virtualizing traditional capacity-oversizing practices, allowing smaller-rated units to replace larger fixed-speed predecessors through continuous modulation.
MOHAP's mandatory energy efficiency labeling framework tightens allowable power consumption thresholds for cooling appliances sold across all seven emirates. Suppliers must submit third-party test reports demonstrating seasonal energy efficiency ratios before obtaining distribution permits. Inventory non-compliance risks market withdrawal, concentrating procurement decisions among distributors with established ESMA certification relationships.
Rental housing operators now unbundle cooling equipment from base lease agreements, transferring procurement responsibility to tenants while retaining maintenance obligations. This model displaces landlord-provided fixed installations in Dubai's annual-lease apartment market, where turnover exceeds forty percent. Sharjah's mid-income districts exhibit the fastest behavioral transition, with tenants prioritizing portability over cooling capacity ratings.
United Arab Emirates Portable Air Conditioning Market Segmentation
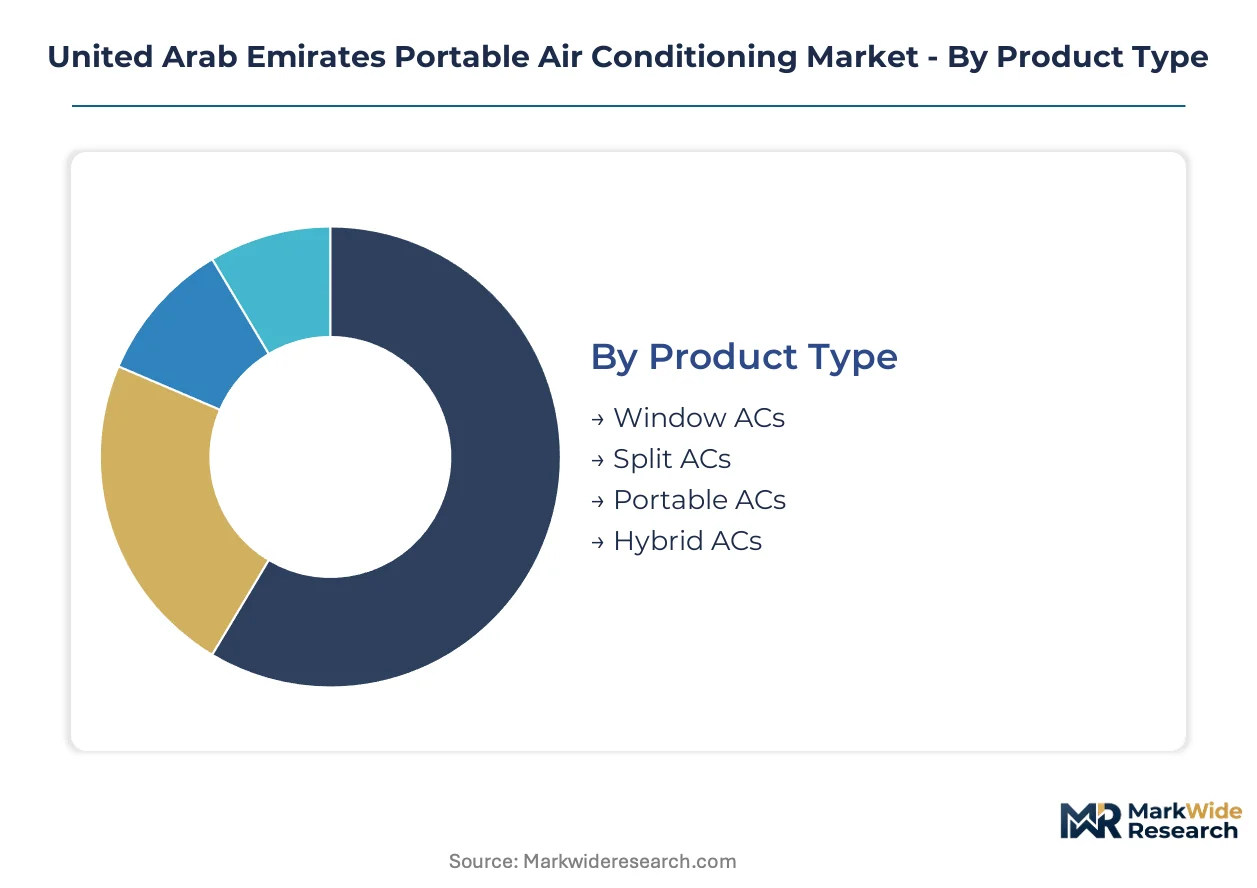
Portable air conditioning procurement patterns across the UAE diverge sharply by deployment context, control interface, efficiency compliance, and end-use infrastructure requirements. Understanding these fault lines clarifies why inverter systems command premium positioning in Dubai's hospitality sector while basic manual units persist in Sharjah's rental corridors.
Product Type:
The use-case spectrum spans permanent installation alternatives to fully mobile cooling solutions, with each configuration addressing distinct spatial constraints and tenure expectations.
- Portable ACs:Self-contained vapor-compression units rated 8,000-14,000 BTU/hour with single-duct or dual-duct exhaust configurations. Demand concentrates in Dubai's hospitality refurbishment sector where temporary cooling gaps during HVAC infrastructure replacement drive procurement cycles.
- Split ACs:Two-component systems separating compressor-condenser from evaporator units via refrigerant lines. Sharjah's mid-density rental districts favor these for semi-permanent installation where tenant turnover exceeds forty percent annually.
- Window ACs:Through-wall packaged units with fixed chassis dimensions. Legacy stock persists in Abu Dhabi's older residential towers pending green building retrofit mandates.
- Hybrid ACs:Dual-mode systems switching between vapor-compression and evaporative cooling. Emerging specification for coastal zones with high humidity variability.
The dominant share belongs to Portable ACs, while Split ACs is closing the gap fastest.
Control Type:
Interface sophistication tracks directly with tenant demographics and building automation maturity across emirate-level housing markets.
- Smart Control:Wi-Fi-enabled architectures integrating with home automation protocols. Dubai's tech-forward apartment segments specify these for remote scheduling and energy monitoring.
- Remote Control:Infrared handheld transmitters with basic temperature and timer functions. Standard specification for Sharjah's mid-income rental inventory.
- Touch Control:Capacitive panel interfaces with LED feedback. Hospitality operators in Abu Dhabi favor these for guest-facing aesthetics.
- Manual Control:Mechanical dial or slider mechanisms without electronic components. Lowest-cost tier serving temporary labor accommodation.
Smart Control systems capture the steepest expansion trajectory as MOHAP efficiency mandates drive demand for programmable load management.
Energy Efficiency:
Regulatory compliance tiers now structure procurement decisions more than upfront cost considerations across UAE distribution channels.
- Inverter:Variable-speed compressor systems enabling continuous modulation rather than binary cycling. MOHAP labeling mandates filter non-compliant inventory, elevating average selling prices for certified units.
- Energy Star Rated:Third-party verified seasonal efficiency performance. Command margin premiums in Dubai despite higher upfront cost, reflecting electricity tariff sensitivity.
- Non-Inverter:Fixed-speed mechanical compression with on-off operation. Market share compressing under ESMA certification timelines and efficiency threshold enforcement.
- Standard:Baseline compliance without premium efficiency certification. Surviving only in price-sensitive temporary deployment contexts.
Inverter technology holds the dominant position, with Energy Star Rated products gaining share fastest among quality-sensitive segments.
End User:
Customer archetypes separate by tenure length, infrastructure ownership, and cooling load predictability.
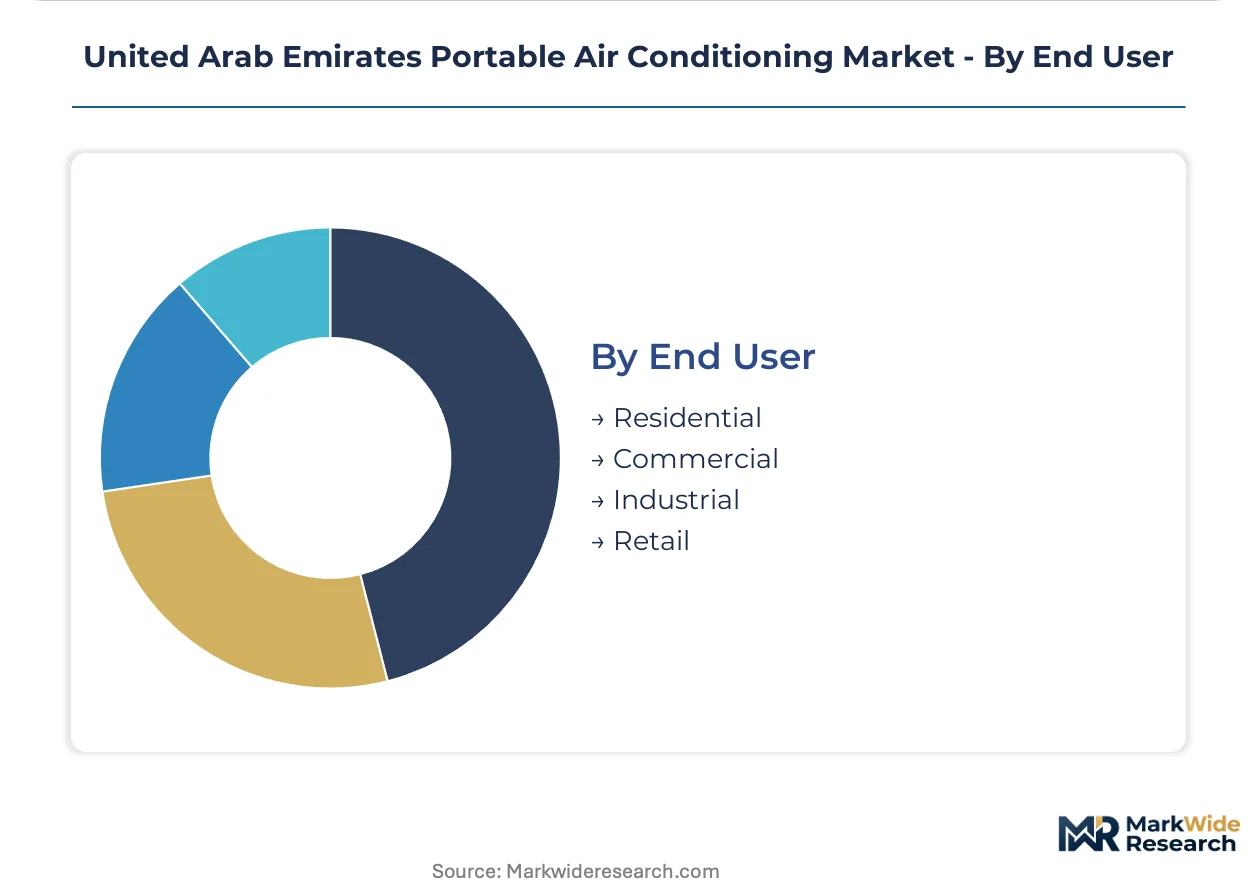
- Residential:Expatriate renters prioritizing mobility over fixed installations. Volume anchors in Dubai and Sharjah annual-lease markets where cooling equipment unbundles from base rent.
- Commercial:Office fit-outs and retail spaces requiring temporary climate control during construction-phase gaps. Abu Dhabi green building codes redirect demand toward portable solutions during retrofits.
- Hospitality:Hotel banquet halls and event spaces with fluctuating hourly cooling loads. Variable-speed inverter specifications dominate this segment.
- Industrial:Workshop and warehouse cooling with tolerance for higher noise levels and lower precision control. Single-duct configurations persist despite negative pressure efficiency penalties.
Residential demand commands the dominant volume position, while Commercial applications are expanding most quickly on construction-phase cooling mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput underwrites Dubai's dominance in UAE portable air conditioning distribution, channeling inverter-compressor inventory through bonded warehousing zones before inland transfer to Sharjah and Northern Emirates markets.
Dubai
Hospitality refurbishment cycles generate temporary cooling gaps during HVAC infrastructure replacement, with hotel operators procuring dual-duct portable units for banquet halls. MOHAP efficiency labeling mandates filter non-compliant inventory through ESMA certification checkpoints at Jebel Ali Free Zone. Dubai Design District clusters specify Wi-Fi-enabled smart control systems for tech-forward apartment developments.
Abu Dhabi
Green building retrofit mandates redirect demand toward portable solutions during construction-phase cooling gaps in commercial and residential towers. The emirate's building codes require temporary climate control during facade upgrades and MEP replacements. Masdar City developments anchor specification of Energy Star Rated products for sustainability-compliant leasing.
Sharjah
Mid-density rental districts exhibit tenant turnover exceeding forty percent annually, driving unbundled cooling procurement where renters prioritize portability over fixed installations. Sharjah Electricity and Water Authority tariff structures elevate electricity cost sensitivity among expatriate households. Industrial zones in Al Saja'a concentrate demand for single-duct units in workshop cooling applications.
Northern Emirates
Ras Al Khaimah and Fujairah hospitality developments along the eastern coast generate seasonal procurement spikes for temporary event cooling. Construction-phase mandates in new resort projects specify inverter-based portable systems pending permanent HVAC commissioning. Fujairah Port's expanding container capacity is reducing lead times for imported cooling equipment.
United Arab Emirates Portable Air Conditioning Market Competitive Landscape
On the supply side, the industry is tiered between premium inverter specialists and volume-driven standard-efficiency suppliers, with distribution partnerships determining effective market access more than manufacturing scale alone. Three strategic archetypes dominate: global appliance conglomerates leveraging brand equity, regional distributors with ESMA certification relationships, and direct-to-consumer platforms bypassing retail markups. Competitive moves center on seasonal promotional cycles tied to Ramadan demand peaks and service partnerships with local installation contractors.
Within the global appliance tier, Gree and LG exemplify divergent positioning strategies—Gree representing direct-to-consumer channel penetration while LG anchors premium service-network differentiation. Haier occupies a position between these vectors, competing aggressively on seasonal promotional timing. These three companies illustrate how geographic origin and distribution architecture shape effective market presence without requiring identical product specifications or pricing structures.
| Leading Market Players |
|---|
| Gree |
| Evvoli |
| Super General |
| AUX |
| Crownline |
| DeLonghi |
| LG |
| Haier |
| Whirlpool |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali Port's container throughput dynamics compress logistics costs for bulk inverter-compressor imports while amplifying price differentiation between ESMA-certified inventory and non-compliant alternatives. Copper-aluminum heat exchanger feedstock volatility transmits directly through Sharjah distribution channels, forcing procurement managers to balance spot-market exposure against long-term supplier contracts.
Pricing Analysis
Volume-discount tiering separates hospitality bulk procurement from single-unit retail transactions across Dubai's distribution network. Price differentiation hinges on MOHAP efficiency certification grade and after-sales service bundling with local installation contractors. Pricing pressure intensifies in Sharjah's rental corridors as tenant turnover accelerates replacement-cycle negotiations. Residential end-users exhibit highest price sensitivity, while Abu Dhabi commercial retrofit projects prioritize Energy Star compliance over upfront cost.
Supply Chain Analysis
Copper coil and aluminum finstock feedstock markets in China, South Korea, and Japan anchor compressor manufacturing cost structures for UAE-bound inventory. Component sourcing draws from Taiwanese semiconductor fabs for inverter control modules and German sensor suppliers for smart-home integration chipsets. Single-source vulnerability concentrates in Jebel Ali Free Zone bonded warehousing, where ESMA certification delays create inventory chokepoints. Distribution runs through Sharjah's mid-density retail clusters and Dubai's hospitality procurement channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dubai's hospitality procurement consortia, fragmenting the downstream customer base while elevating volume-discount leverage in annual contract negotiations.
For Market Incumbents: Build certification-relationship moats by deepening ESMA testing partnerships and pre-positioning inventory in Jebel Ali Free Zone ahead of seasonal demand spikes. Defend against Gree's direct-to-consumer platform encroachment by securing exclusive service partnerships with Sharjah installation contractors. Prioritize inverter-compressor R&D allocation to maintain MOHAP compliance lead over fixed-speed alternatives. For New Entrants and Emerging Players: Ras Al Khaimah's hospitality development pipeline offers the most penetrable white-space, with construction-phase cooling mandates creating procurement windows before permanent HVAC commissioning. Target Fujairah Port's expanding container capacity to reduce lead-time disadvantages against Jebel Ali-incumbent rivals. Enter through seasonal promotional cycles tied to Ramadan demand peaks, mirroring Haier's established timing without matching its scale. For Investors and Strategic Acquirers: Regional distributors with established ESMA certification relationships and bonded warehousing access represent the priority acquisition archetype for portfolio exposure to UAE cooling equipment demand. Monitor MOHAP efficiency threshold tightening announcements as the critical inflection signal for inventory obsolescence risk and replacement-cycle acceleration. Long-term viability rests on regulatory compliance infrastructure rather than manufacturing scale alone.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Certification Pre-Positioning | Accelerates market entry timelines by 8-14 weeks for new product variants. |
| Direct-to-Consumer Platform Launch | Bypasses traditional retail markups in Dubai and Abu Dhabi apartment markets. |
| Inverter Compressor R&D Investment | Aligns product portfolios with MOHAP efficiency labeling mandates. |
| Installation Contractor Partnership | Secures service-network differentiation against platform-only competitors. |
| Seasonal Promotional Cycle Optimization | Captures Ramadan and summer peak demand windows in Sharjah corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement directors, Sharjah rental housing operators, ESMA certification consultants, Jebel Ali Free Zone logistics managers, and inverter-compressor manufacturing executives. Secondary validation drew from MOHAP regulatory filings, ESMA compliance databases, UAE customs trade records, and hospitality sector capex disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, control interface, efficiency tier, and end-user segmentation dimensions.
Calibration anchored volume projections to historical seasonal patterns, rental turnover rates, and hospitality refurbishment cycle frequencies across the analysis window. Modeled segmentation spanned product configuration, control sophistication, regulatory compliance tier, and deployment context. CAGRs were derived from slope-stability testing across multiple baseline assumptions. Forecast inputs incorporated copper-aluminum commodity price trajectories and MOHAP threshold evolution scenarios.
Practitioners should monitor ESMA certification timeline extensions and MOHAP efficiency threshold announcements for early signals requiring forecast revision. Cross-checking against UAE hospitality sector capex survey data and Sharjah Electricity and Water Authority tariff filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Smart Cooling Systems Market