
 Advanced Server Energy Monitoring Tools Market | 2026-2036
Advanced Server Energy Monitoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Server Energy Monitoring Tools Market Intelligence
The bundling of hardware sensors with cloud-based software subscriptions is realigning buyer preferences away from standalone, perpetual licenses. Schneider Electric leverages its EcoStruxure IT platform to offer integrated solutions for data center infrastructure management. Vertiv Holdings specializes in thermal management and power systems, embedding monitoring tools directly into its core infrastructure products. In contrast, IBM positions its software capabilities to manage energy consumption across complex, hybrid cloud environments.
Advanced server energy monitoring tools are systems of hardware and software that measure and analyze power consumption at the server, rack, or PDU level. They deliver real-time data on metrics like kilowatt-hours and thermal conditions to optimize data center operations. While Hardware Monitors are a mature segment, Software Solutions and Cloud-Based Tools represent the fastest-growing product types. Demand from Cloud Service Operators for AI Integration within their analytics platforms is a significant technical driver.
Energy efficiency mandates and sustainability reporting requirements are critical market drivers. Frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) and standards from ASHRAE in the United States compel organizations to track and disclose energy usage and carbon footprints. Consequently, vendors must decide whether to focus on compliance-driven reporting features or advanced AI-powered optimization capabilities to differentiate their offerings.
Market Dynamics
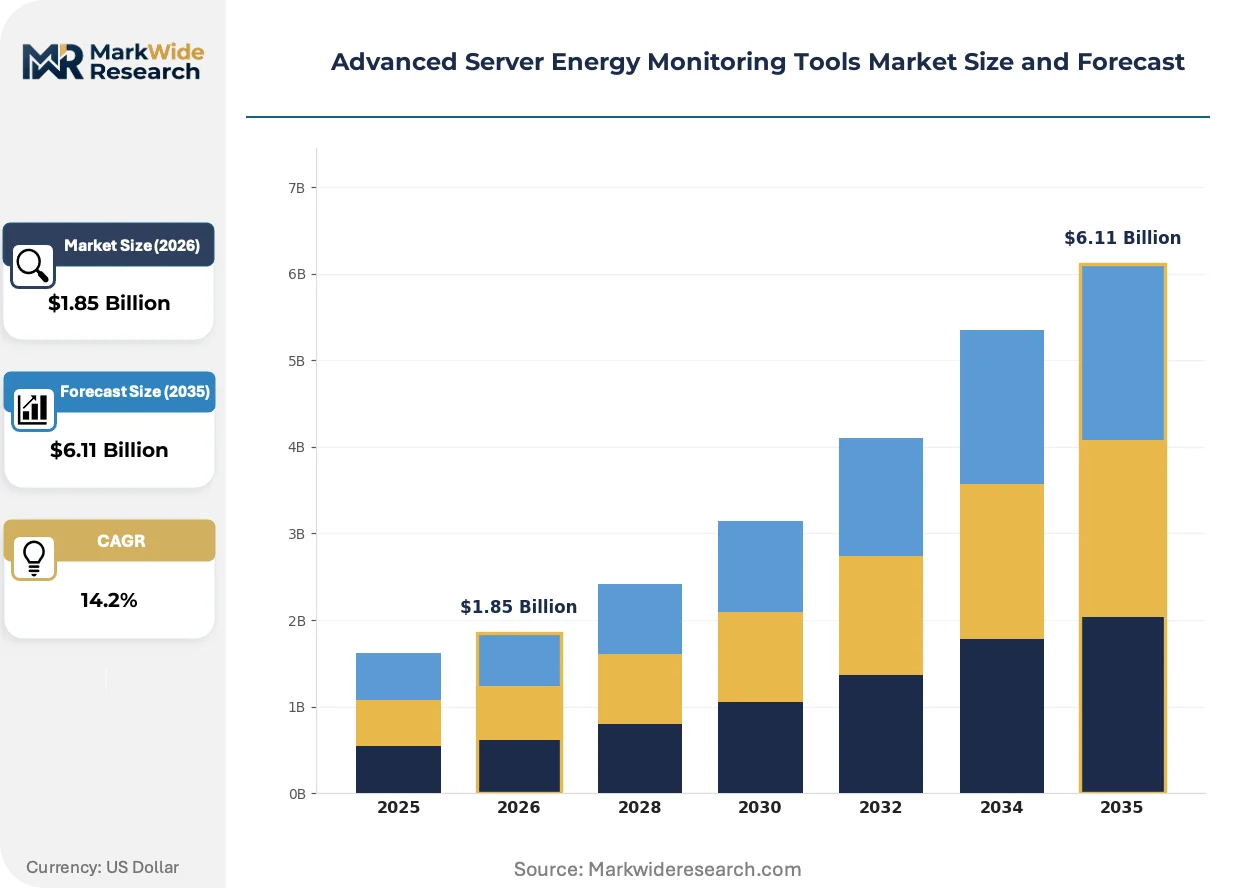
The convergence of stringent sustainability regulations and the operational imperative for cost efficiency within hyperscale data centers is the central force shaping the market. This dual pressure compels operators to adopt granular monitoring tools for both compliance and competitive advantage.
Growth Catalysts
- Regulatory Mandates:Directives such as the EU's Corporate Sustainability Reporting Directive (CSRD) and standards from ASHRAE in the United States require verifiable, detailed energy consumption data, directly fueling demand for advanced monitoring solutions.
- AI Integration:The incorporation of artificial intelligence and machine learning into analytics platforms enables predictive maintenance and dynamic resource allocation, attracting Cloud Service Operators seeking to optimize performance and reduce operational expenditures.
- Hyperscale Expansion:Continued infrastructure investment by cloud providers in major data center clusters like Ashburn, Frankfurt, and Singapore necessitates sophisticated energy management tools to maintain efficiency at an unprecedented scale.
Market Restraints
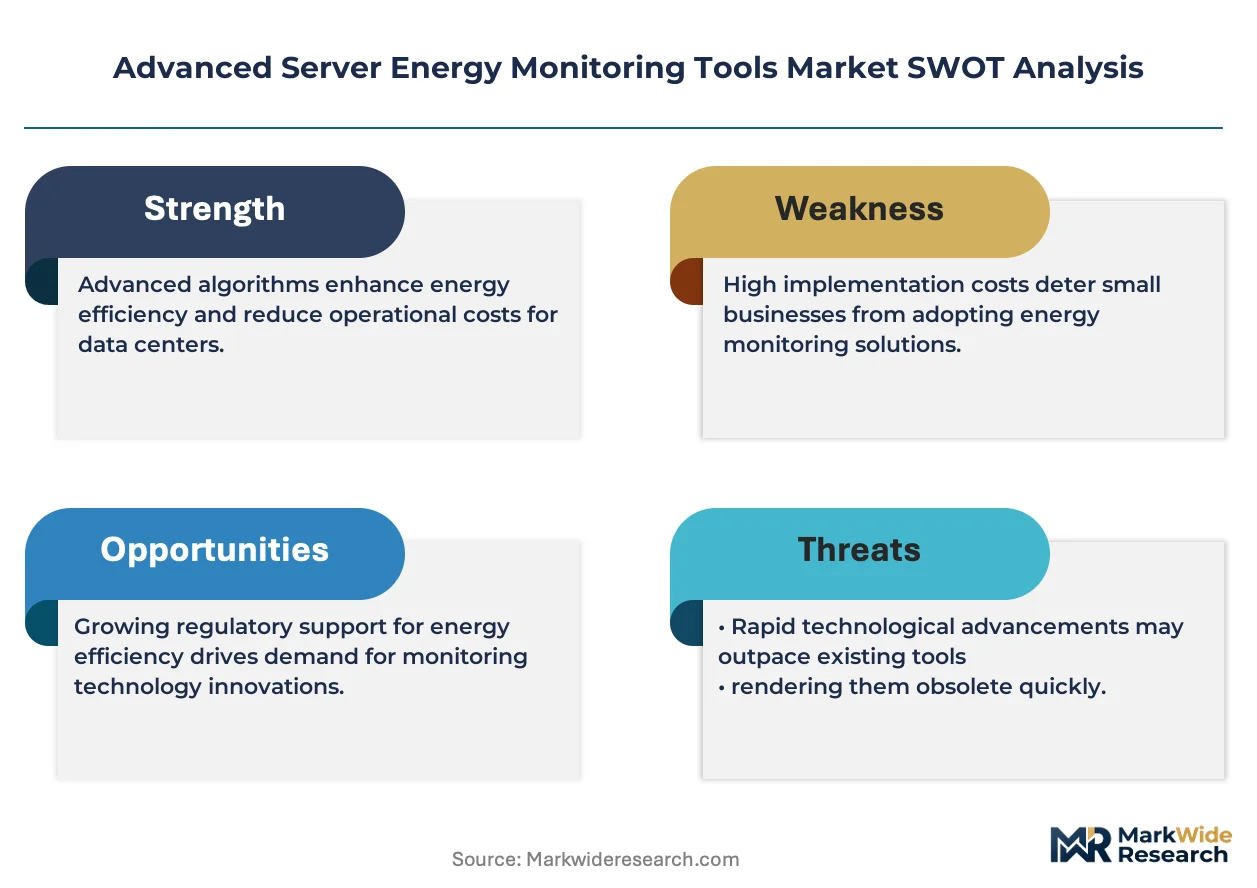
- High Retrofit Costs:The significant capital investment required to deploy comprehensive sensor networks and software in older, legacy data centers acts as a major barrier to adoption for some enterprise operators.
- Interoperability Issues:A lack of universal communication standards between hardware from different vendors, such as power distribution units and environmental sensors, complicates integration with centralized software platforms.
- Substitution from Basic Tools:In smaller or less critical enterprise environments, the continued reliance on facility-level power monitoring or basic DCIM functions presents a substitution threat to more advanced, server-level systems.
Strategic Opportunities
- Emerging Market Penetration:Data center construction in developing regions, particularly in Southeast Asia and Latin America, offers a greenfield opportunity to install advanced monitoring systems from the outset, bypassing legacy constraints.
- Edge Computing Specialization:Developing monitoring tools tailored for the unique power and thermal constraints of distributed edge computing sites creates a new market segment beyond traditional, centralized data centers.
- Holistic Sustainability Platforms:Integrating energy monitoring with water usage effectiveness (WUE) and carbon accounting software allows vendors to offer a single, comprehensive dashboard for environmental, social, and governance (ESG) reporting.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals with hybrid expertise in data center engineering, power systems, and data analytics limits the ability of organizations to fully leverage advanced monitoring tools. -
- Legacy System Integration:The technical complexity of integrating modern monitoring tools with existing, often proprietary, Data Center Infrastructure Management (DCIM) platforms without causing downtime is a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Server Energy Monitoring Tools Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Monitors, Software Solutions, Hybrid Systems, Cloud-Based Tools, Embedded Sensors Technology: Power Usage Effectiveness, Real-Time Analytics, Predictive Modelling, AI Integration, IoT Connectivity Application: Data Center Management, IT Asset Optimization, Energy Compliance, Carbon Footprint Tracking, Capacity Planning End User: Enterprise IT Departments, Managed Service Providers, Colocation Facilities, Cloud Service Operators, Telecommunications Firms |
| Companies Covered | Dell, ABB, HP, Vertiv Holdings, Schneider Electric, IBM, Siemens, Eaton Corporation, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Server Energy Monitoring Tools Market Strategic Shifts & Innovations
Software-defined power management is fundamentally altering the market's trajectory, shifting the focus from passive data collection to active, automated optimization. This evolution prioritizes intelligent control over energy consumption, driven by advancements in analytics and changing procurement models.
AI-Powered Predictive Optimization
AI-powered analytics platforms utilize machine learning algorithms to forecast energy demand and identify potential thermal anomalies before they occur. Cloud Service Operators are the primary adopters, embedding these predictive capabilities into their large-scale infrastructure management frameworks. This evolution from reactive alerting to proactive control is rewriting the value proposition from simple energy measurement to automated operational efficiency and resilience.
Granular Reporting for Regulatory Compliance
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory driver. It mandates that large companies provide auditable, granular disclosures on energy usage and related carbon footprints, making facility-level estimates insufficient. Data center operators with a presence in Europe are most directly impacted, accelerating their investment in tools that provide server- and rack-level data to meet these stringent reporting obligations.
Subscription Models Displace Perpetual Licenses
A clear behavioral shift is occurring as customers increasingly favor integrated hardware and software-as-a-service (SaaS) subscriptions over traditional, one-time perpetual license purchases. This opex-based model replaces the large upfront capital expenditure of standalone software, offering continuous updates and scalable management. The trend is most visible among hyperscale and colocation providers who prioritize flexibility and alignment with cloud-native operational philosophies.
Advanced Server Energy Monitoring Tools Market Segmentation
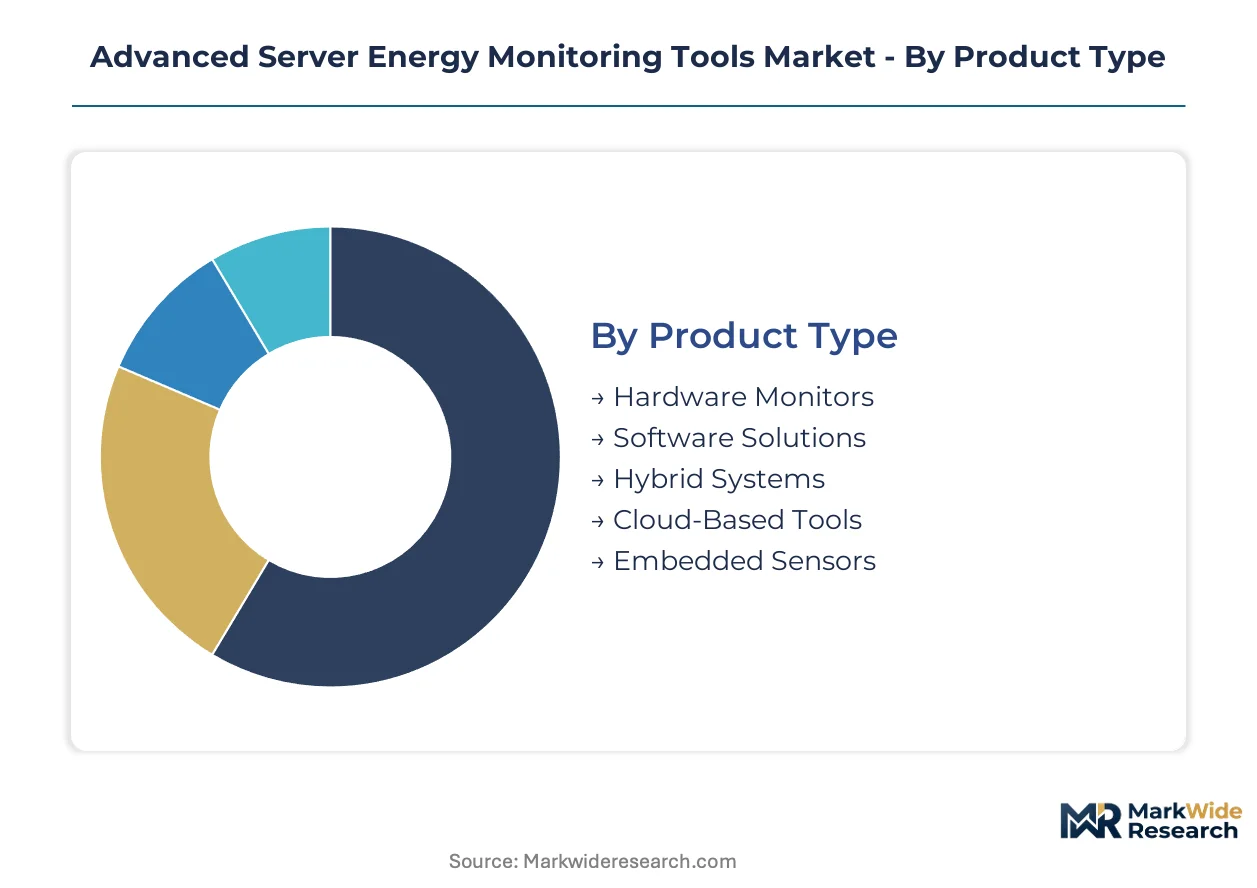
Market segmentation provides a critical framework for understanding the diverse requirements and investment priorities within the advanced server energy monitoring tools sector. Analyzing distinct product types, technologies, applications, and end users reveals varied adoption patterns and commercial opportunities.
Product Type:
The initial capital outlay significantly influences adoption across product types, with hardware-centric solutions often requiring more upfront investment than software-only offerings.
- Hardware Monitors:These physical devices measure power consumption directly at the server, rack, or PDU level, providing foundational data for energy management. Demand remains consistent in established data centers seeking to upgrade existing infrastructure without full overhauls.
- Software Solutions:These platforms analyze data from various sources, offering dashboards, reporting, and analytics for data center operations. Cloud Service Operators increasingly prioritize software-defined power management for dynamic resource allocation.
- Hybrid Systems:These integrated solutions combine physical sensors with sophisticated software platforms, delivering comprehensive monitoring and control capabilities. Enterprise IT departments often adopt hybrid systems for balanced hardware and software functionality.
- Cloud-Based Tools:Hosted on remote servers, these tools offer scalable, subscription-based monitoring and analytics accessible from any location. Hyperscale providers and colocation facilities favor cloud platforms for their flexibility and reduced on-premises IT burden.
- Embedded Sensors:Integrated directly into server components or power infrastructure, these sensors provide highly granular, real-time data from the source. Manufacturers embed these for precise thermal and power profiling.
Most installed capacity flows through Hardware Monitors. Expansion is steepest in Cloud-Based Tools.
Technology:
Operational impact and data utility differentiate technology segments, with advanced analytics driving predictive capabilities and strategic decision-making for data center operators.
- Power Usage Effectiveness:This metric quantifies the energy efficiency of a data center, providing a standardized benchmark for operational performance. Data center managers utilize PUE to track and report efficiency improvements.
- Real-Time Analytics:These systems process and display energy consumption data instantaneously, enabling immediate responses to operational anomalies. Hyperscale environments depend on real-time data for continuous optimization.
- Predictive Modelling:Utilizing historical data and algorithms, this technology forecasts future energy demands and potential thermal issues within data centers. Cloud Service Operators leverage predictive models for proactive resource planning.
- AI Integration:Artificial intelligence and machine learning algorithms enhance monitoring tools by identifying complex patterns, optimizing resource allocation, and automating responses. Demand from Cloud Service Operators for AI integration is a significant technical driver.
- IoT Connectivity:This enables various sensors and devices across a data center to communicate and share data with a central monitoring platform. Smart data center initiatives widely incorporate IoT for comprehensive environmental awareness.
The integration of AI Integration drives operational efficiency, while Real-Time Analytics enables strategic decision-making.
Application:
Regulatory pressures and efficiency gains shape application priorities, compelling organizations to adopt monitoring solutions that address both compliance and cost reduction objectives.
- Data Center Management:This application encompasses overall operational oversight, including power, cooling, and space utilization within the data center environment. Colocation facilities rely on these tools for efficient resource allocation.
- IT Asset Optimization:Tools in this segment help identify underutilized servers and optimize workload placement to reduce energy consumption. Enterprise IT departments use these for better capital expenditure planning.
- Energy Compliance:This application focuses on generating verifiable data and reports to meet regulatory mandates for energy consumption and carbon emissions. European data centers specifically invest in tools for CSRD reporting.
- Carbon Footprint Tracking:These applications calculate and report the greenhouse gas emissions associated with data center operations. Organizations with sustainability goals prioritize robust carbon accounting features.
- Capacity Planning:This involves analyzing current and projected energy usage to ensure sufficient power and cooling infrastructure for future growth. Hyperscale providers use these tools for strategic build-out decisions.
Demand for Data Center Management remains foundational, with Energy Compliance experiencing accelerated uptake due to compliance needs.
End User:
The scale and operational models of end-user segments dictate their monitoring tool requirements, ranging from granular server-level data to overarching facility-wide insights.
- Enterprise IT Departments:These in-house teams manage data centers for their own organizations, often seeking solutions that integrate with existing IT infrastructure. They prioritize cost efficiency and operational stability.
- Managed Service Providers:These companies offer IT services and data center management to multiple clients, requiring scalable and multi-tenant monitoring solutions. They focus on service level agreement (SLA) adherence.
- Colocation Facilities:These providers offer shared data center space and infrastructure to multiple tenants, needing robust tools for billing, resource allocation, and tenant-specific reporting. They manage diverse client requirements.
- Cloud Service Operators:These hyperscale entities operate vast, distributed data centers to deliver cloud computing services, demanding highly automated and AI-driven monitoring for massive scale. They prioritize energy efficiency for competitive advantage.
- Telecommunications Firms:These companies manage extensive networks and data centers to support communication services, requiring monitoring tools that can handle geographically dispersed infrastructure. Network reliability is paramount for these operators.
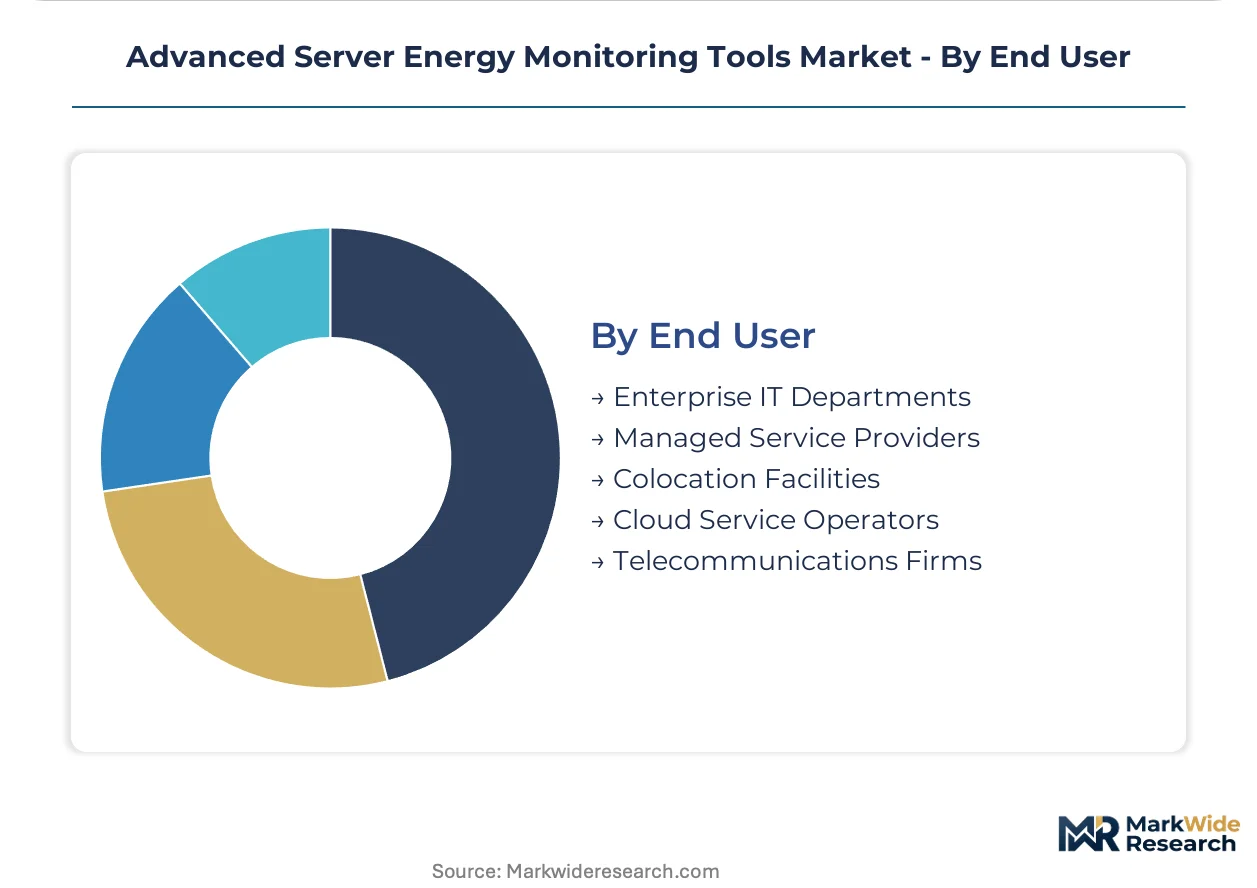
Cloud Service Operators represent the fastest-growing trajectory for adoption, while Enterprise IT Departments maintain a broad installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The advanced server energy monitoring tools market initially scaled in regions pioneering hyperscale data center development and cloud computing services. Early and sustained investment in large-scale digital infrastructure, particularly in the United States, established foundational demand for granular energy management solutions.
United States
Hyperscale expansion and the integration of AI within data center operations drive significant demand for advanced monitoring tools in the United States. ASHRAE standards for thermal management and energy efficiency compel operators to adopt sophisticated solutions. Major data center clusters like Ashburn, Virginia, continue to expand, requiring advanced tools for optimal performance and resource allocation.
Germany
Stringent regulatory mandates, including the EU's Corporate Sustainability Reporting Directive (CSRD), accelerate the adoption of energy monitoring tools in Germany. The EU Green Deal further emphasizes the need for transparent energy consumption reporting and carbon footprint reduction. The Frankfurt data center hub represents a key concentration of demand, where operators prioritize compliance and operational efficiency.
Singapore
Continued hyperscale infrastructure investment and ambitious national sustainability goals propel the market for advanced energy monitoring in Singapore. The country's Green Mark certification scheme encourages data centers to implement energy-efficient technologies. Major data center developments, such as those in the Jurong Innovation District, integrate advanced monitoring from their inception to meet efficiency targets.
China
Rapid data center construction and the nation's digital transformation initiatives fuel the need for advanced server energy monitoring tools in China. The government's dual carbon goals push enterprises and cloud providers to track and reduce energy consumption. Significant data center clusters in Beijing and Shanghai are deploying these systems to manage massive power loads and improve operational transparency.
Advanced Server Energy Monitoring Tools Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and service integration within the advanced server energy monitoring tools market. The market exhibits a tiered structure, with integrated solution providers, specialized infrastructure vendors, and software-centric platforms forming distinct archetypes. Strategic partnerships and portfolio diversification represent dominant competitive moves among market participants.
Integrated solution providers, such as Schneider Electric, exemplify the trend towards comprehensive data center infrastructure management platforms, offering both hardware and cloud-based software. Vertiv Holdings, a specialized infrastructure vendor, anchors its competitive positioning through thermal management and power systems with embedded monitoring capabilities. IBM represents software-focused capabilities, leveraging its expertise to manage energy consumption across complex, hybrid cloud environments for large enterprises.
| Leading Market Players |
|---|
| Dell |
| ABB |
| HP |
| Vertiv Holdings |
| Schneider Electric |
| IBM |
| Siemens |
| Eaton Corporation |
| Cisco Systems |
Cost & Logistics Intelligence
Specialized sensor component costs, particularly for highly integrated embedded sensors, directly influence the final price points of advanced monitoring solutions offered to data center operators. This cost structure then flows into subscription-based software bundles.
Pricing Analysis
Subscription-based SaaS models represent the dominant pricing structure for advanced server energy monitoring tools. Price differentiation stems from the level of AI-powered analytics offered and the comprehensiveness of after-sales support. Pricing pressure stems from increased competition among software providers and the commoditization of basic hardware monitors. Cloud Service Operators, prioritizing advanced features for efficiency, exhibit lower price sensitivity compared to smaller enterprise IT departments.
Supply Chain Analysis
Reverse logistics for electronic components, including sensor returns and module refurbishment, pose a challenge within the supply chain. Geographic supply concentration for critical components like specialized integrated circuits and printed circuit boards largely resides in East Asia, particularly China and Taiwan. Single-source vulnerability for specific high-performance sensor arrays represents a structural risk. Distribution runs primarily through direct sales channels to hyperscale operators and through value-added resellers for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant margin-expansion story, particularly driven by the shift towards advanced AI-powered optimization capabilities. This premium-tier shift allows vendors to capture higher value for enhanced operational intelligence.
For Market Incumbents: Deepen AI integration within existing platforms to offer predictive optimization and automated resource management. Expand geographic presence in emerging data center hubs like Southeast Asia to capture greenfield opportunities, mitigating the threat from specialized software startups. Focus R&D efforts on seamless integration with diverse legacy DCIM systems, a key lever for enterprise adoption.
For New Entrants and Emerging Players: Smaller enterprise data centers, particularly those in regulated European markets, represent an underserved buyer archetype for compliance-driven reporting features. Target edge computing sites with tailored monitoring solutions addressing unique power and thermal constraints. A SaaS-only go-to-market angle focusing on rapid deployment and flexible subscription tiers can attract cost-conscious operators.
For Investors and Strategic Acquirers: Consolidation pressure builds where comprehensive integration capabilities and advanced analytics platforms offer significant competitive advantage. Long-term viability over the next 5-10 years favors vendors with strong intellectual property in AI-driven optimization and robust hardware-software integration. Target specialized software firms with proven AI algorithms or niche hardware providers offering highly granular embedded sensors. Watch for large cloud provider acquisitions of monitoring technology firms as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Predictive Optimization | Enhances operational efficiency and reduces downtime for hyperscale data centers. |
| Expand Cloud-Based SaaS Offerings | Aligns with buyer preference for opex models and scalable management for colocation facilities. |
| Develop Edge Computing Solutions | Addresses the unique power and thermal constraints of distributed infrastructure sites. |
| Enhance Regulatory Reporting Features | Supports European data centers in meeting stringent CSRD compliance obligations. |
| Form Strategic Partnerships | Expands market reach and integrates diverse hardware components for comprehensive solutions. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region to capture diverse market dynamics. Primary research involved in-depth interviews with data center operations managers, IT procurement officers, and sustainability leads across various end-user segments. Secondary validation drew from publicly available financial reports, industry association publications, and government energy statistics. This approach combined bottom-up market sizing with top-down validation for robust data integrity.
The rate-of-change decomposition framing structured the market forecast across the analysis window, modeling shifts in demand and supply. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected future trends, considering factors like data center build-out rates and evolving energy efficiency mandates.
Inputs from industry reports and primary interviews were available through the study window; gaps in specific country-level deployment data introduce uncertainty bands. Forecasts reflect assumptions regarding technological adoption and policy stability. Practitioners should monitor hyperscale investment cycles and evolving sustainability regulations for early signals of market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
North America Residential Lighting Control System Market