
 Audio DSP Market | 2026-2036
Audio DSP Market Size, Share, and Industry Trends Forecast 2026-2036
Audio DSP Market Analysis
CE marking under the EU Radio Equipment Directive is rotating the competitive landscape for audio DSP suppliers seeking European market access. NXP Semiconductors leverages its automotive-qualified portfolio to anchor supply relationships with tier-one infotainment integrators. Texas Instruments Incorporated sustains R&D intensity in low-power audio codecs, while Analog Devices Inc. specializes in high-fidelity converters for professional broadcast chains.
Audio digital signal processing encompasses real-time mathematical manipulation of acoustic waveforms through dedicated algorithms executing on programmable hardware, typically achieving sub-10 millisecond latency for live applications. The technology enables noise cancellation, spatial audio rendering, and adaptive equalization across consumer electronics and industrial communication systems. Integrated Circuits and Hardware Processors capture the dominant share of value as silicon complexity rises, while Machine Learning and Cloud-Based Solutions represent the fastest-expanding technology layers as edge inference migrates into earbuds and automotive cabins. Software segments retain margin concentration in licensing models for post-production and broadcast workflows.
FCC equipment authorization rules govern RF-emitting audio DSP devices in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor packaging and assembly. China's MIIT enforces GB standards for electromagnetic compatibility that condition market entry for imported and locally fabricated chips. Stakeholders must monitor how fragmented certification timelines across these jurisdictions affect product roadmaps and inventory positioning.
Market Dynamics
Automotive electrification is compressing development cycles for cabin audio systems, forcing DSP suppliers to synchronize roadmaps with electric vehicle platform launches and smart cockpit integration timelines.
Growth Catalysts
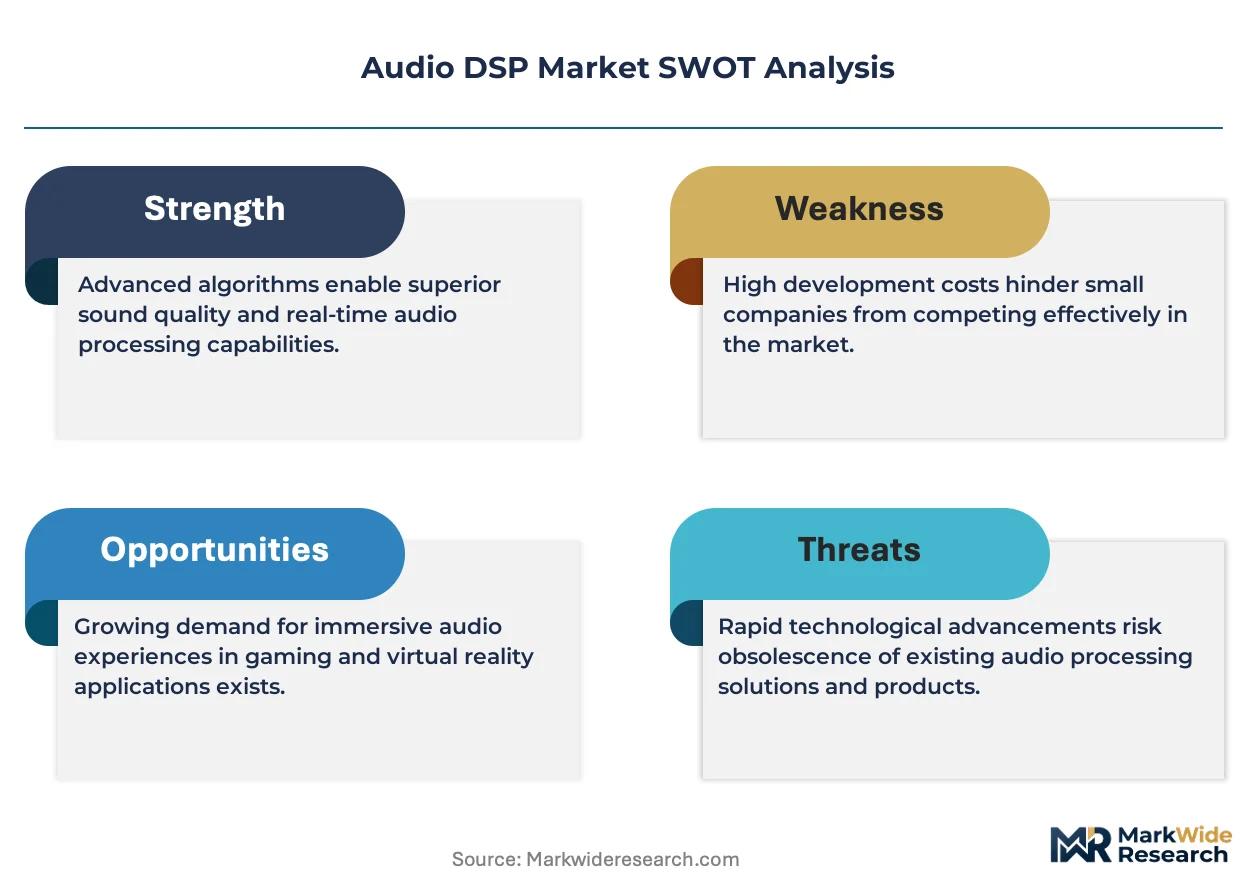
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in manufacturing processes is accelerating transition to lead-free solder and advanced packaging for audio DSP semiconductors.
- Edge ML inference:On-device neural processing for noise cancellation and spatial audio is expanding addressable silicon content in earbuds and automotive head units.
- China EV procurement:Domestic OEMs and tier-one suppliers are scaling local DSP sourcing for smart cabin platforms, creating concentrated demand pull from Shenzhen and Shanghai design centers.
Market Restraints
- Advanced node access:Foundry capacity at 7nm and below for high-performance audio DSPs concentrates in Taiwan, creating geographic supply risk for fabless designers.
- RoHS substance restrictions:European REACH and RoHS frameworks limit cadmium and lead content in semiconductor packaging, forcing reformulation of legacy alloy compositions.
- RF coexistence complexity:Dense antenna integration in smartphones and vehicles degrades analog signal integrity, requiring costly shielding and isolation engineering.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting DSP packaging and testing investments to Noida and Bengaluru corridors.
- Over-the-air audio tuning:Cloud-connected DSP firmware updates enable recurring revenue models from automotive OEMs previously served through one-time hardware sales.
- Ambient computing convergence:Voice-first interfaces in smart home and industrial settings are merging audio DSP requirements with sensor fusion and low-power wake-word detection.
Industry Challenges
- Multi-jurisdiction certification:Simultaneous FCC, CE marking, and MIIT GB standard approvals create timeline misalignment between US, European, and Chinese product launches.
- Acoustic engineering talent:Shortage of specialists combining psychoacoustics, embedded systems, and machine learning optimization constrains R&D velocity at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio DSP Market |
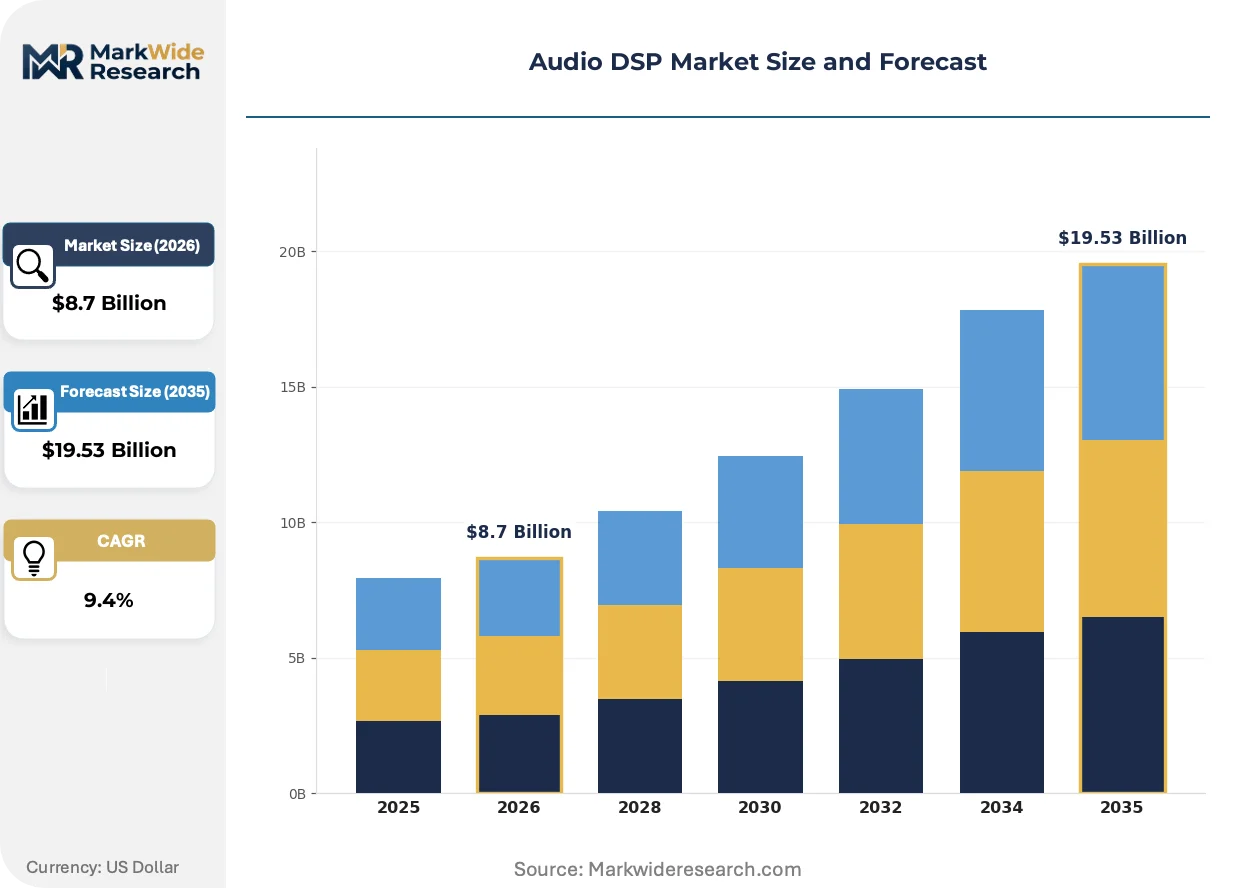
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Integrated Circuits, Development Kits, Hardware Processors Application: Live Sound, Broadcast, Recording, Communication End User: Consumers, Professional Audio, Entertainment, Corporate Technology: Analog Signal Processing, Digital Signal Processing, Machine Learning, Cloud-Based Solutions |
| Companies Covered | NXP Semiconductors, Broadcom Inc., Texas Instruments Incorporated, Qualcomm Technologies Inc., Cirrus Logic, Inc., Analog Devices Inc., STMicroelectronics, ON Semiconductor, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio DSP Market Emerging Trajectories
Algorithm-hardware co-design is replacing discrete component sourcing as the primary competitive axis, with automotive and consumer audio segments diverging in their latency and power requirements.
Neural audio codecs are fragmenting traditional compression architectures by replacing fixed psychoacoustic models with learned representations. Smartphone OEMs and streaming platforms are adopting these codecs for voice and music transmission. This compression of legacy standards is fragmenting licensing revenue pools among incumbent patent holders.
China's MIIT GB standards for electromagnetic compatibility are tightening test protocols for RF-emitting audio devices. Domestic certification bodies are expanding testing capacity in Shenzhen and Suzhou. Automotive tier-one suppliers are redesigning module layouts to satisfy these requirements ahead of export and local sales.
Automotive OEMs are consolidating DSP procurement under single-source platform contracts rather than discrete chip purchasing. Tier-one integrators are absorbing subsystem design responsibility from vehicle manufacturers. This concentration is most visible in Germany and Japan, where premium brands are vertically integrating acoustic tuning expertise.
Audio DSP Market Segmentation
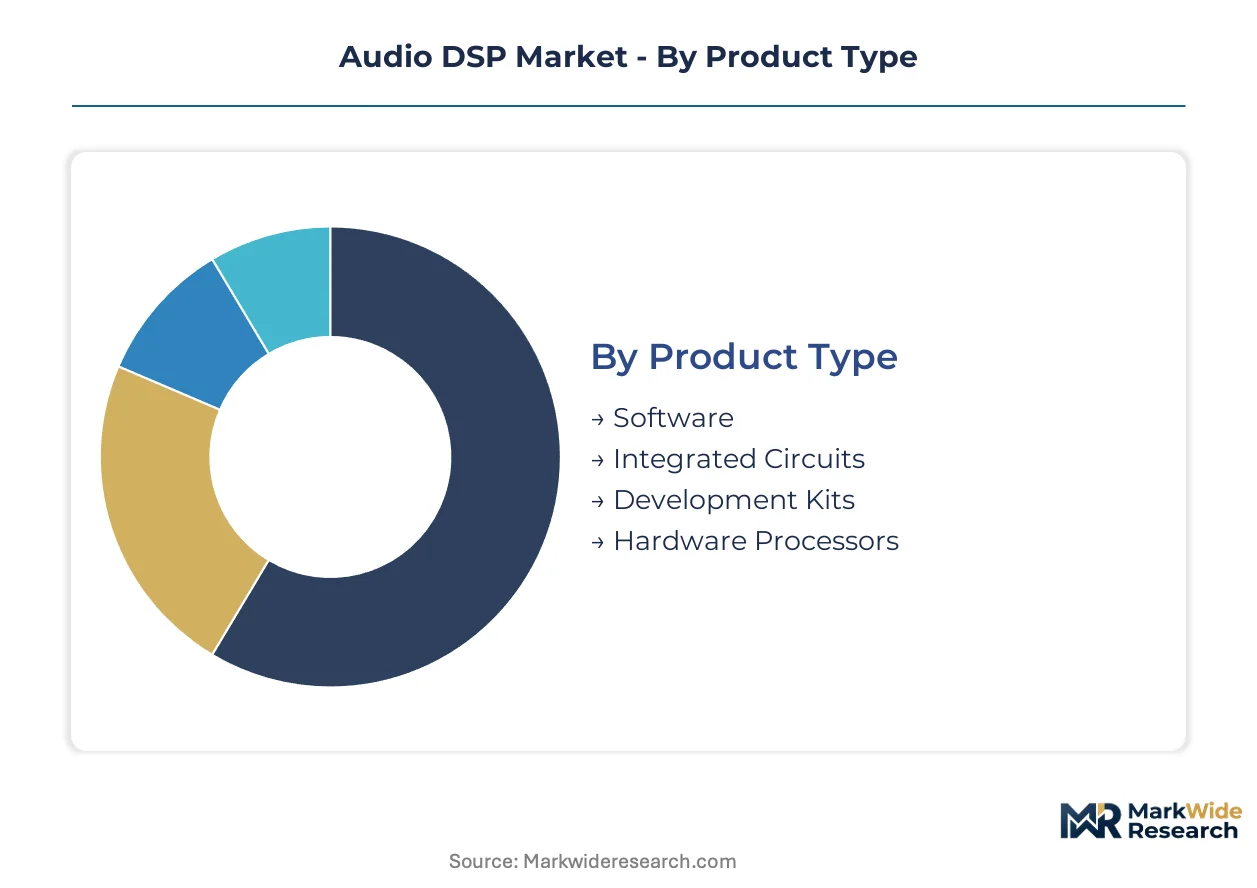
Audio DSP segmentation reveals divergent margin structures across silicon, software, and services. Hardware complexity concentrates value in automotive and broadcast tiers, while licensing models dominate post-production workflows.
Product Type:
Margin pools concentrate in silicon where automotive qualification cycles and node migration create pricing power.
- Integrated Circuits:Automotive-qualified DSPs execute real-time acoustic algorithms with sub-10 millisecond latency. Tier-one infotainment integrators in Germany and Japan are consolidating procurement under single-source platform contracts for electric vehicle cabins.
- Hardware Processors:Dedicated silicon for spatial audio rendering and adaptive equalization commands premium positioning. Foundry capacity at advanced nodes concentrates in Taiwan, creating geographic supply risk for fabless designers serving smartphone and earbud OEMs.
- Software:Licensing models for post-production and broadcast workflows retain recurring revenue concentration. Cloud-connected firmware updates enable subscription transitions from one-time hardware sales.
- Development Kits:Reference designs and evaluation platforms accelerate time-to-market for mid-tier suppliers entering automotive and professional audio segments.
Integrated Circuits hold installed capacity. Hardware Processors is rotating up the share rankings.
Application:
Application tiering separates mission-critical broadcast infrastructure from volume consumer electronics.
- Broadcast:High-fidelity converters for professional transmission chains require precision analog-to-digital architectures. European REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging, forcing reformulation of legacy alloy compositions for gear deployed across EMEA transmission networks.
- Live Sound:Real-time processing for concert and event production demands sub-10 millisecond latency. Rental and touring companies in the United States and United Kingdom are refreshing inventories to support immersive audio formats.
- Recording:Studio environments prioritize bit-depth and dynamic range over power constraints. Home studio proliferation during remote production trends has expanded addressable equipment sales.
- Communication:Voice-first interfaces in enterprise and industrial settings merge DSP requirements with sensor fusion and low-power wake-word detection.
Broadcast maintains premium pricing. Live Sound is climbing the fastest as touring activity normalizes.
End User:
Customer type determines whether procurement flows through retail channels or direct B2B negotiation.
- Professional Audio:Post-production houses and broadcast facilities specify equipment through technical procurement with extended support contracts. Japan's METI standards and Germany's KBA automotive certification requirements condition vendor selection for integrated cabin systems.
- Entertainment:Streaming platforms and content studios drive neural audio codec adoption, fragmenting traditional compression licensing pools. On-device machine learning for noise cancellation expands silicon content in production monitoring gear.
- Consumers:Earbud and smartphone OEMs absorb DSP modules through high-volume supply agreements with aggressive cost-down schedules.
- Corporate:Enterprise communication systems prioritize RF coexistence engineering for dense antenna integration in unified communications hardware.
Professional Audio commands specification authority. Entertainment is gaining share fastest through streaming platform procurement.
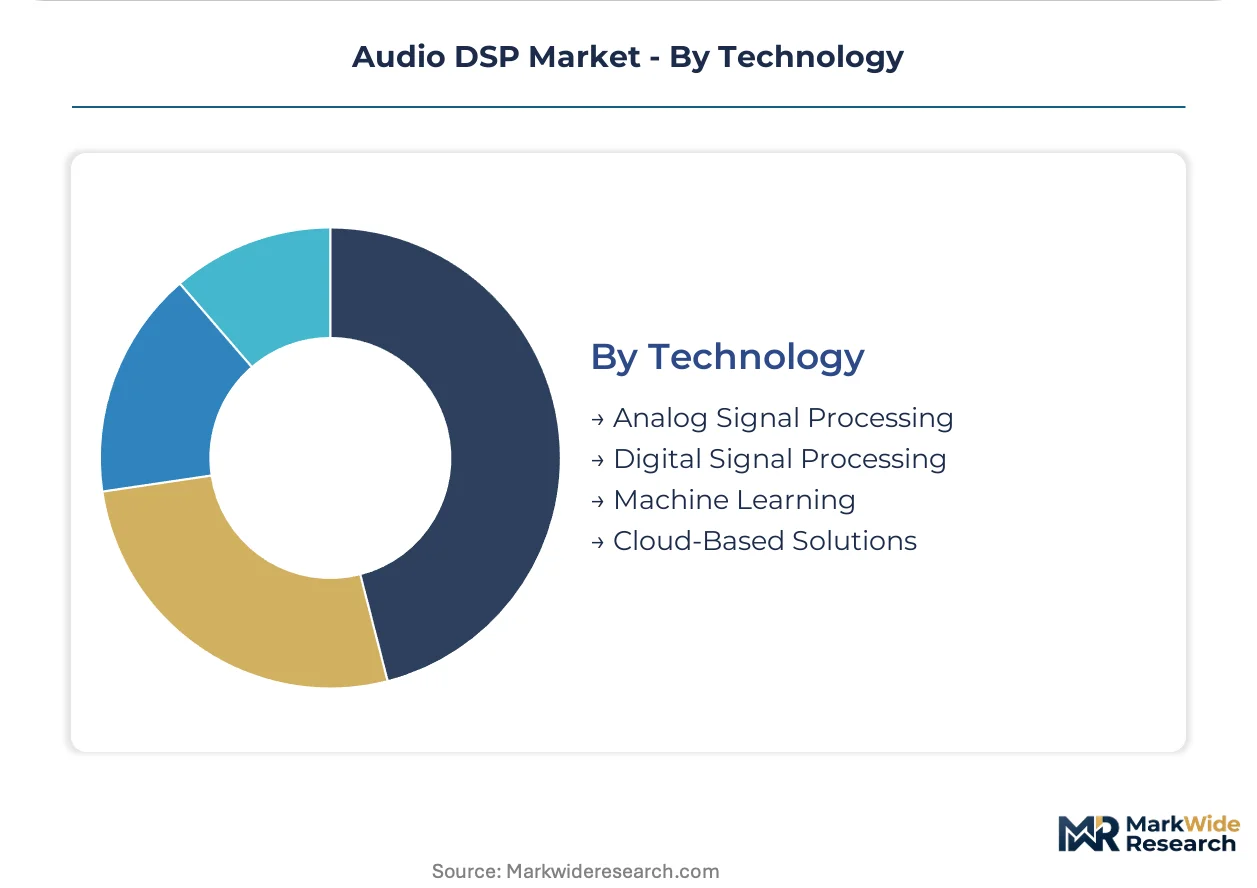
Technology:
Technology layers stack from legacy analog through edge inference, with cloud connectivity enabling recurring revenue attachment.
- Machine Learning:Neural processing for noise cancellation and spatial audio executes on-device in earbuds and automotive head units. Edge inference migration is expanding addressable silicon content while compressing power budgets.
- Cloud-Based Solutions:Over-the-air audio tuning and firmware updates enable subscription revenue models from automotive OEMs. China's MIIT enforces GB standards for electromagnetic compatibility that condition cloud-connected device market entry.
- Digital Signal Processing:Programmable hardware executing real-time mathematical manipulation of acoustic waveforms remains the foundational layer across all applications.
- Analog Signal Processing:Legacy architectures persist in cost-sensitive applications and specialized high-fidelity niches where digital conversion introduces unacceptable latency or artifacts.
Digital Signal Processing holds installed base. Machine Learning is rotating up the share rankings fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentives and emissions regulations are redirecting manufacturing investment toward India and reshaping supply chain configurations across major economies. Procurement patterns now cluster around EV platform launches and smart cabin integration timelines in automotive hubs.
China
Domestic OEMs and tier-one suppliers are scaling local DSP sourcing for electric vehicles and smart cabin platforms, creating concentrated demand pull from Shenzhen and Shanghai design centers. MIIT enforces GB standards for electromagnetic compatibility that condition market entry for imported and locally fabricated chips. The Yangtze River Delta and Pearl River Delta regions host expanding certification body capacity in Suzhou and Shenzhen to satisfy tightening test protocols.
United States
Automotive electrification is compressing development cycles for cabin audio systems, forcing DSP suppliers to synchronize roadmaps with electric vehicle platform launches. FCC equipment authorization rules govern RF-emitting audio DSP devices nationwide. Design activity concentrates in California and Texas, where fabless semiconductor firms cluster near major foundry customer support centers.
Germany
Premium automotive brands are vertically integrating acoustic tuning expertise and consolidating DSP procurement under single-source platform contracts. KBA automotive certification requirements condition vendor selection for integrated cabin systems. Bavaria and Baden-Württemberg anchor development partnerships between tier-one infotainment integrators and semiconductor suppliers.
India
The PLI scheme for electronics manufacturing is attracting DSP packaging and testing investments to Noida and Bengaluru corridors. BIS standards for electronic equipment create compliance pathways for both export-oriented and domestic-market production. Karnataka and Telangana are emerging as design centers where mid-tier suppliers establish development kit distribution channels.
Japan
METI standards and automotive certification frameworks shape procurement specifications for integrated cabin systems among domestic OEMs. Tier-one integrators absorb subsystem design responsibility from vehicle manufacturers. The Kanto and Chubu regions maintain concentration in precision analog-to-digital converter development for professional broadcast and automotive applications.
Audio DSP Market Vendor Landscape
Player mix skews toward diversified semiconductor conglomerates with automotive qualification capabilities, creating a tiered structure where scale-driven portfolios coexist with specialized converter architects. The competitive landscape separates into three strategic archetypes: broad-line suppliers with automotive-qualified portfolios, precision analog specialists serving broadcast chains, and fabless designers targeting consumer earbuds and smartphones. Dominant competitive moves include algorithm-hardware co-design investments and geographic expansion of certification capacity to compress multi-jurisdiction approval timelines.
Within the diversified semiconductor tier, NXP Semiconductors N.V. and Texas Instruments Incorporated exemplify scale-driven positions anchored by automotive customer relationships. Analog Devices Inc. occupies a specialist position in high-fidelity signal conversion. These three entities collectively represent the spectrum from broad-line programmable hardware to precision analog architectures that define competitive positioning across infotainment and professional audio segments.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Broadcom Inc. |
| Texas Instruments Incorporated |
| Qualcomm Technologies Inc. |
| Cirrus Logic, Inc. |
| Analog Devices Inc. |
| STMicroelectronics |
| ON Semiconductor |
| Infineon Technologies AG |
| Others |
Supply Flow & Price Mechanics
Foundry utilization rates at advanced nodes in Taiwan anchor cost structures for fabless audio DSP designers, compressing margin buffers for automotive-qualified silicon while amplifying pricing power for integrated device manufacturers with captive capacity. This scale asymmetry stratifies procurement negotiations between tier-one infotainment integrators and mid-tier suppliers.
Pricing Analysis
Certification level (CE marking, FCC authorization, MIIT GB compliance) creates the primary spread between automotive-grade and consumer-tier DSP modules. The dominant pricing structure runs through contract-based long-term offtake agreements with volume-scaled discounts, while customization for cabin-specific acoustic tuning commands premium positioning. Cost compression in earbud and smartphone tiers is intensifying because Chinese OEMs are consolidating procurement under platform contracts. Professional audio and broadcast segments exhibit the least price sensitivity due to specification-driven procurement cycles.
Supply Chain Analysis
Inventory buffers for automotive-qualified DSPs stretch to 26-32 weeks as tier-one integrators pre-position silicon ahead of EV platform launches. Manufacturing concentration clusters in Taiwan for advanced node wafer fabrication, South Korea for memory-integrated packaging, and China for module assembly and testing. Silicon wafers, specialized analog IP cores, and advanced substrate materials constitute critical input dependencies. Single-source vulnerability at 7nm and below foundry capacity constitutes the dominant structural risk. Distribution runs through direct B2B negotiation with automotive tier-ones and consumer OEMs rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Audio DSP adoption sits in early-cycle expansion as edge ML inference migrates into earbuds and automotive cabins, compressing development timelines for noise cancellation and spatial audio algorithms.
For Market Incumbents: Shield automotive platform relationships by deepening backward integration into acoustic tuning software and securing multi-year foundry capacity reservations at advanced nodes. Emerging fabless competitors from Shenzhen threaten tier-one supply positions through aggressive cost positioning. Certification investment in MIIT GB and CE marking pathways reinforces procurement stickiness with German and Chinese OEMs. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Bavaria and Baden-Württemberg accelerates European market entry ahead of full FCC authorization cycles. White-space targets cluster in India's PLI scheme corridors for packaging and testing investments, plus over-the-air audio tuning subscriptions for mid-tier automotive OEMs. A development kit-led go-to-market angle penetrates mid-tier suppliers lacking in-house acoustic engineering talent. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision analog specialists with broadcast chain relationships and automotive-qualified programmable hardware portfolios. Long-term viability hinges on algorithm-hardware co-design capabilities spanning neural audio codecs and edge inference silicon. Watch for inflection signals in consolidation of DSP procurement under single-source platform contracts among premium German and Japanese automotive brands.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Hardware Co-Design Investment | Enables sub-10 millisecond latency for automotive cabin applications while compressing power budgets. |
| CE Marking and MIIT GB Certification Expansion | Compresses multi-jurisdiction approval timelines for European and Chinese market entry. |
| Over-the-Air Firmware Platform Launch | Transitions automotive OEM relationships from one-time hardware sales to recurring subscription revenue. |
| India PLI Scheme Manufacturing Footprint | Positions packaging and testing capacity for export-oriented and domestic-market production. |
| Neural Audio Codec Patent Portfolio Buildout | Captures licensing value as streaming platforms displace legacy psychoacoustic compression standards. |
Methodological Framework
A standing panel of automotive platform engineers, tier-one infotainment procurement leads, acoustic algorithm specialists, and semiconductor foundry customer support managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization filings, MIIT GB standard publications, EU F-Gas Regulation impact assessments, and SEC 10-K disclosures from diversified semiconductor suppliers. Bottom-up segment sizing triangulated against top-down market envelope checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type (silicon, software, services), application tier (automotive, broadcast, consumer), technology layer (edge ML, cloud-connected, legacy DSP), and regional regulatory cluster. CAGRs derived from regression analysis of historical adoption curves and penetration saturation limits, with specific inputs including EV platform launch schedules and smart cabin integration timelines.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification and edge ML migration; material deviation in foundry capacity allocation or regulatory timeline compression would warrant model refresh. Specific risk factors include multi-jurisdiction certification misalignment and acoustic engineering talent scarcity constraining R&D velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Flexible Heater Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Microspeaker Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Switch Diode Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
RAID Controller Card Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Impulse Relays Market
Electronic Components
Lowpass Filters Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
Chip Ferrite Beads Market