
 Event Camera Market | 2026-2036
Event Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Event Camera Market Insights
ISO 26262 functional safety certification is bifurcating the competitive landscape into automotive-qualified and non-automotive tiers. Prophesee leverages its proprietary event-based sensor IP to dominate high-speed industrial vision applications. Samsung anchors consumer electronics integration with its advanced CMOS foundry capabilities. Texas Instruments competes through embedded processor-event sensor fusion platforms for edge robotics.
An event camera asynchronously detects per-pixel brightness changes rather than capturing conventional frame-based images, achieving microsecond temporal resolution with minimal motion blur and substantially lower bandwidth than standard imagers. Industrial automation and robotics applications lead current volume deployment, while sports analysis represents the fastest-growing segment as broadcasters adopt sub-millisecond motion tracking. Monochrome cameras retain the largest installed base due to superior low-light sensitivity and simpler signal processing, though color event sensors are narrowing the performance gap through advanced demosaicing algorithms.
FDA scrutiny of vision-based medical devices and FCC emission rules for wireless sensor modules shape product development timelines in the United States. Europe's CE marking under the EU AI Act and MDR frameworks governs autonomous system deployments. The EU Green Deal's energy efficiency mandates favor event cameras' inherent low-power advantage over frame-based alternatives. Stakeholders must monitor how automotive OEM qualification cycles synchronize with next-generation sensor fusion architectures.
Market Dynamics
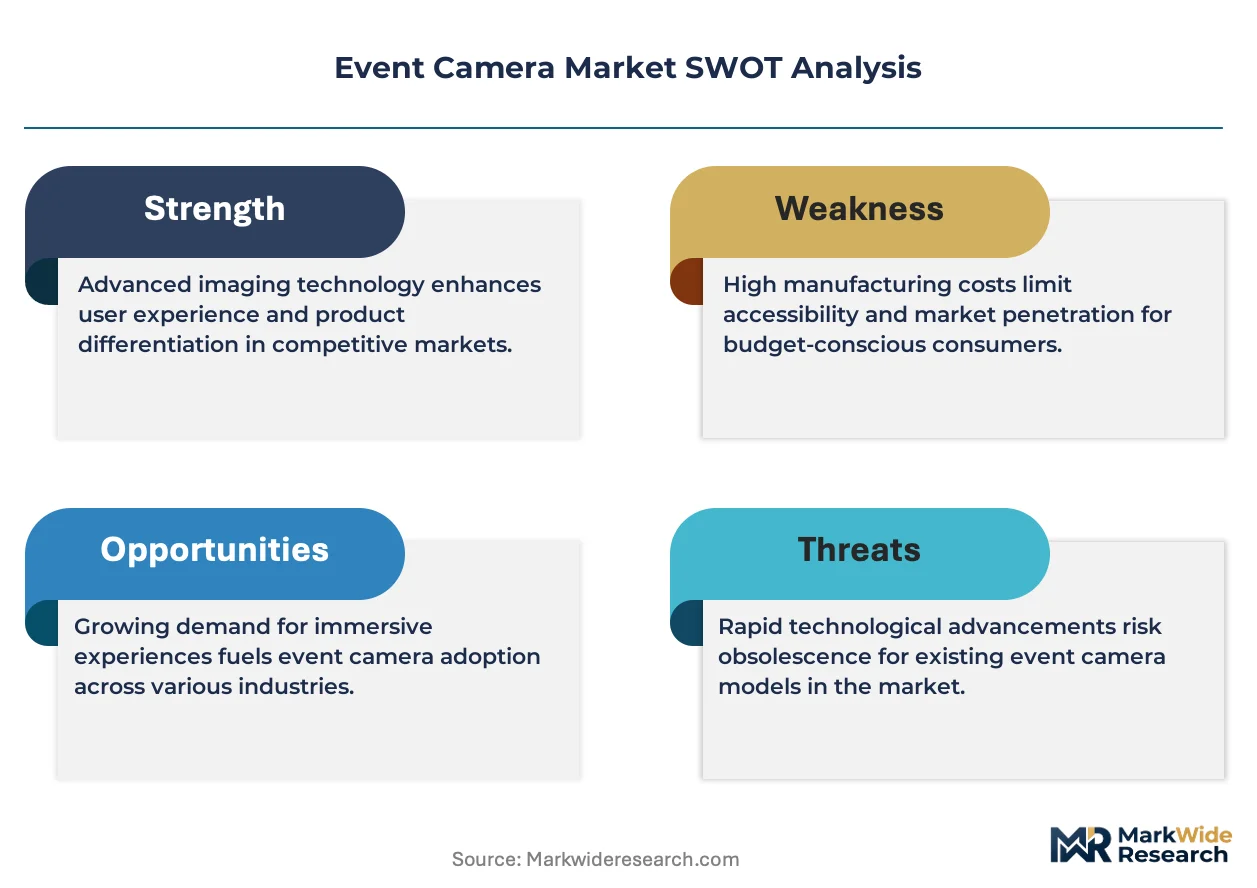
ISO 26262 functional safety certification is bifurcating the competitive landscape into automotive-qualified and non-automotive tiers, forcing suppliers to duplicate development tracks or abandon high-ASP vehicle perception contracts entirely.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-global-warming-potential refrigerants in industrial cooling systems accelerates migration toward solid-state, low-power sensor architectures in precision manufacturing environments.
- Stuttgart-Munich automotive cluster:Germany's concentrated OEM and Tier-1 engineering presence creates dense qualification feedback loops that compress event camera validation cycles for autonomous vehicle programs.
- Sub-millisecond motion tracking:Broadcast sports production demands for ultra-high-speed athlete biomechanics analysis pull event camera deployment into live entertainment infrastructure.
Market Restraints
- CMOS foundry concentration:Advanced stacked-die sensor fabrication depends on Taiwan-based capacity, exposing supply continuity to geopolitical friction and export control volatility.
- Demosaicing algorithm complexity:Color event sensors require computationally intensive reconstruction pipelines that inflate edge-processor requirements and system bill-of-materials costs.
- Frame-based incumbent substitution:High-frame-rate CMOS imagers with global shutter and HDR stacking narrow the performance gap in cost-sensitive industrial inspection applications.
Strategic Opportunities
- EU AI Act compliance services:CE marking requirements for autonomous system transparency and auditability create attach-rate potential for embedded event-camera analytics with explainable output logging.
- India PLI scheme:Production-linked incentives for electronics manufacturing attract module assembly investment serving domestic robotics and drone perception demand.
- Neuromorphic processor convergence:Pairing event sensors with spiking neural network accelerators unlocks sub-milliwatt always-on vision for battery-constrained edge devices.
Industry Challenges
- ISO 26262 ASIL-D certification timelines:Automotive functional safety qualification cycles extend 24-36 months, locking engineering resources before revenue recognition and straining startup cash positions.
- Legacy frame-based software stacks:Computer vision algorithm libraries and training datasets optimized for conventional imagers require expensive retooling for asynchronous event data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Camera Market |
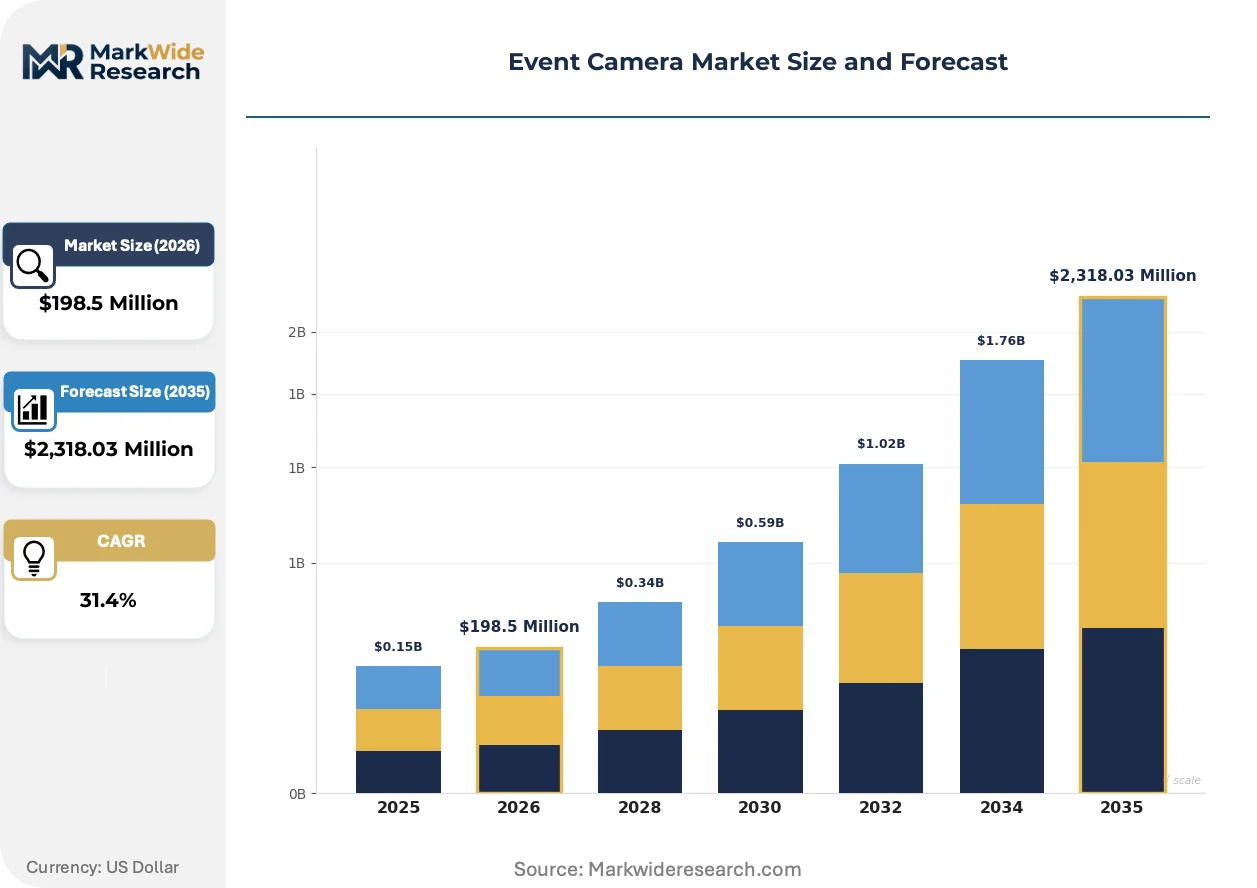
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $2,318.03 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochrome Cameras, Color Cameras, Thermal Cameras, 3D Cameras Application: Industrial Automation, Robotics, Surveillance, Sports Analysis End User: Manufacturers, Researchers, Security Firms, Sports Organizations Technology: Optical Sensors, Infrared Sensors, CMOS Technology, Lidar |
| Companies Covered | Samsung, Qualcomm, Prophesee, CEVA, Ambarella, IniVation, Texas Instruments, Intel, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Camera Market Trends and Innovations
Three converging forces—silicon photonics integration, regulatory energy-efficiency mandates, and buyer consolidation around qualified automotive suppliers—are compressing the viable competitive set and elevating capital requirements for market participation.
Stacked backside-illuminated event sensors with in-pixel memory is bifurcating the technology roadmap between cost-optimized consumer-grade devices and radiation-hardened space-qualified variants. Satellite Earth-observation programs and lunar rover navigation systems adopt the high-reliability branch, while smartphone gesture interfaces drive volume scaling on the commercial branch. The structural consequence is collapsing R&D amortization across divergent reliability specifications.
Europe's F-Gas Regulation and the EU Green Deal's energy efficiency mandates are accelerating industrial vision system refresh cycles toward sub-100-milliwatt sensor alternatives. Factory automation buyers in Germany, France, and the Netherlands now specify event cameras in new line-build tenders to meet Scope 2 emission reduction commitments. Equipment OEMs respond by bundling power-consumption telemetry with warranty terms.
Broadcast sports leagues are consolidating camera procurement around integrated tracking-data service contracts rather than discrete hardware purchases. Rights-holders in North American and European markets now demand bundled athlete-biometrics output, forcing camera vendors to acquire or partner with AI analytics providers. The shift compresses hardware margins while extending customer lifetime value through recurring data-licensing revenue.
Event Camera Market Segmentation
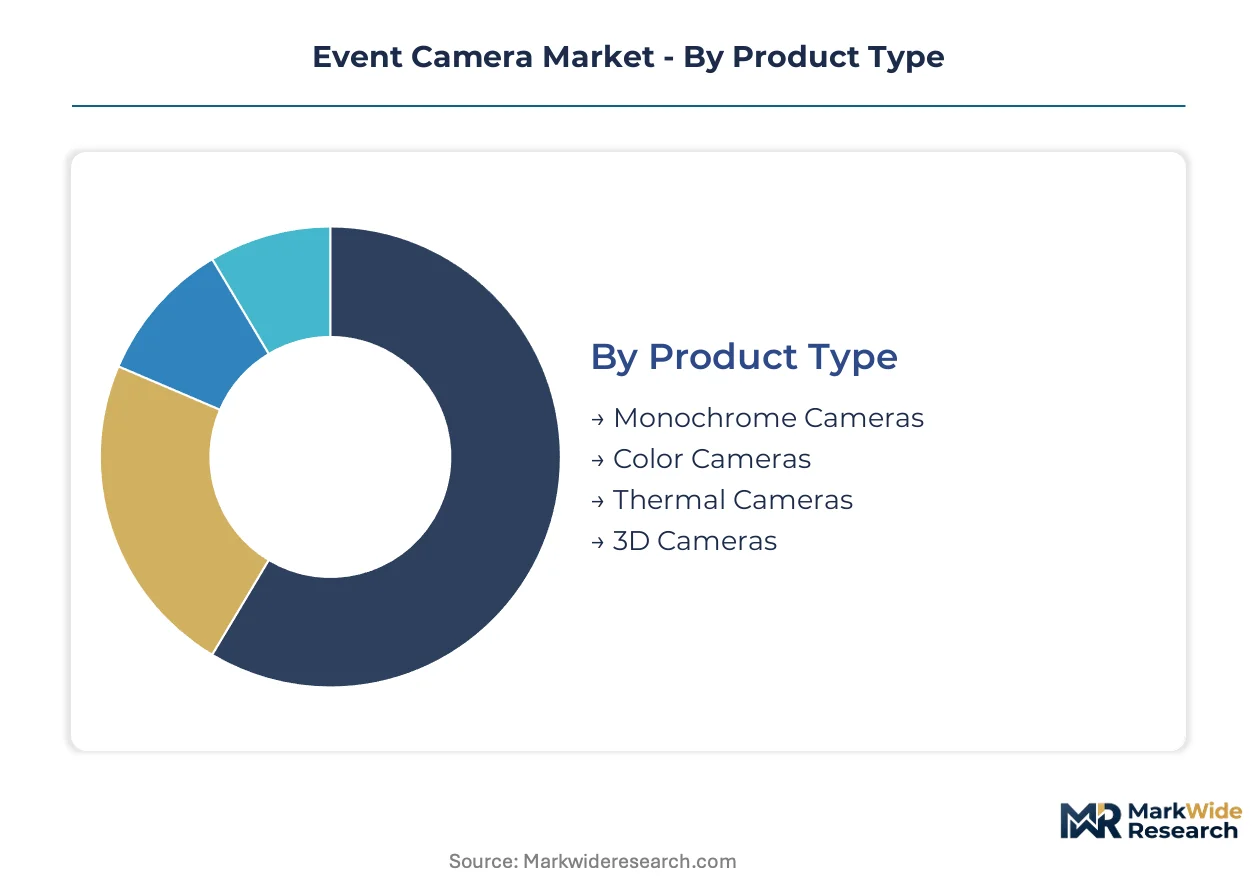
Event camera segmentation reveals how asynchronous imaging technology fragments across divergent performance requirements and buyer sophistication. Product architecture, application intensity, and end-user technical maturity each create distinct margin architectures that suppliers must navigate simultaneously.
Product Type:
Margin pools concentrate in specialized sensor architectures where low-light performance or spectral discrimination commands premium positioning.
- Monochrome Cameras:Single-channel photodiode arrays eliminate Bayer filter attenuation, delivering superior quantum efficiency in sub-lux conditions. Germany's automotive vision cluster around Stuttgart sources monochrome units for autonomous vehicle perception validation, constrained by ISO 26262 ASIL-D qualification timelines that extend 24-36 months.
- Color Cameras:Demosaicing algorithms reconstruct RGB channels from sparse event streams, demanding 3-5x higher edge-processor throughput than monochrome equivalents. Broadcast sports production in North America and Europe pulls color deployment for athlete-biometrics output, though computational overhead inflates system bill-of-materials costs.
- Thermal Cameras:Uncooled microbolometer fusion with event-based detection enables through-smoke and through-fog operation for firefighting robotics.
- 3D Cameras:Stereoscopic event sensor pairs or time-of-flight correlation modules deliver depth-aware asynchronous vision for warehouse automation.
The dominant share belongs to Monochrome Cameras, while Color Cameras is closing the gap fastest.
Application:
Volume deployment patterns track manufacturing capital expenditure cycles and live entertainment infrastructure refresh timelines.
- Industrial Automation:High-speed defect inspection on semiconductor and pharmaceutical packaging lines exploits microsecond temporal resolution. Factory automation buyers in Germany, France, and the Netherlands specify event cameras in new line-build tenders to meet EU Green Deal Scope 2 emission reduction commitments.
- Robotics:Edge-robotics platforms fuse event streams with proprioceptive data for collision avoidance and grasp planning. Texas Instruments competes through embedded processor-event sensor fusion platforms serving warehouse and last-mile delivery autonomy.
- Surveillance:Low-light perimeter monitoring with minimal data bandwidth suits remote infrastructure protection.
- Sports Analysis:Sub-millisecond motion tracking for athlete biomechanics analysis is expanding most quickly as broadcasters adopt live entertainment infrastructure with bundled tracking-data service contracts.
Industrial Automation retains the largest installed base, though Sports Analysis demonstrates the steepest expansion trajectory.
End User:
Procurement sophistication bifurcates between specification-driven engineering organizations and cost-constrained operational buyers.
- Manufacturers:Automotive OEMs and Tier-1 suppliers in Germany's Stuttgart-Munich cluster drive qualification feedback loops that compress validation cycles. These buyers demand ISO 26262 functional safety certification, forcing suppliers to duplicate development tracks or abandon high-ASP vehicle perception contracts.
- Researchers:Academic and government laboratory procurement emphasizes sensor characterization data and open-source driver support over volume pricing.
- Security Firms:Physical security integrators prioritize interoperability with existing video management software and cybersecurity hardening.
- Sports Organizations:League rights-holders and broadcast consortiums now procure integrated tracking-data services rather than discrete hardware, compressing camera margins while extending vendor customer lifetime value through recurring data-licensing revenue.
Manufacturers command the dominant procurement volume, while Sports Organizations is gaining share fastest through bundled service contracting.
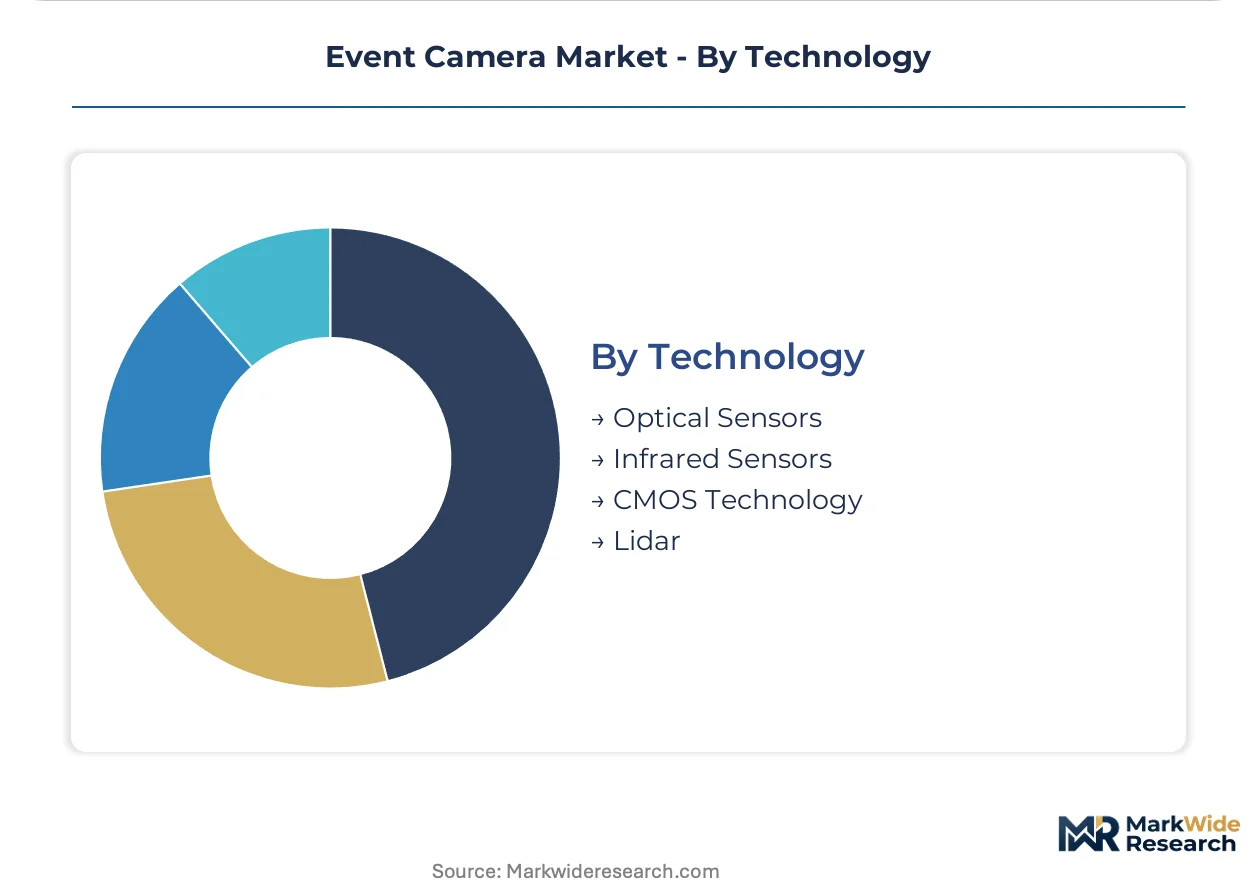
Technology:
Sensor physics and semiconductor process node choices determine performance ceilings and supply chain exposure.
- Optical Sensors:Silicon photodiode-based event detection achieves highest temporal resolution with lowest power consumption. Stacked backside-illuminated architectures with in-pixel memory bifurcate between cost-optimized consumer-grade devices and radiation-hardened space-qualified variants for satellite Earth-observation programs.
- Infrared Sensors:Short-wave and near-infrared event detection extends operational spectral range for agricultural monitoring and medical imaging applications.
- CMOS Technology:Advanced stacked-die sensor fabrication depends on Taiwan-based foundry capacity, exposing supply continuity to geopolitical friction and export control volatility.
- Lidar:Time-of-flight correlation with event-based detection enables high-resolution depth mapping for autonomous navigation.
CMOS Technology anchors the largest technology investment base, while Optical Sensors is climbing the fastest on neuromorphic processor convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives and regulatory mandates are redrawing competitive maps as suppliers chase qualification contracts and energy-efficiency tenders across concentrated industrial clusters.
United States
FDA scrutiny of vision-based medical devices and FCC emission rules for wireless sensor modules compress product development timelines. NHTSA autonomous vehicle guidance shapes perception system requirements for domestic automotive programs. Austin and Detroit engineering centers host validation labs serving Tier-1 supplier qualification cycles.
Germany
Stuttgart-Munich automotive cluster density creates feedback loops that compress event camera validation cycles for autonomous vehicle programs. EU F-Gas Regulation accelerates migration toward solid-state, low-power sensor architectures in precision manufacturing. Factory automation buyers in Baden-Württemberg specify event cameras in new line-build tenders to meet EU Green Deal Scope 2 commitments.
China
MIIT industrial robot deployment targets pull event sensor integration into warehouse automation and last-mile delivery platforms. Dual carbon goals favor low-power vision alternatives in smart manufacturing tenders. Yangtze River Delta electronics manufacturing bases concentrate module assembly capacity serving domestic robotics demand.
Japan
METI robotics and autonomous systems roadmaps prioritize high-speed perception for industrial and service robot applications. JIS standards development for event-based imaging interfaces shapes interoperability requirements. Kanto region precision equipment manufacturers anchor sensor characterization and integration engineering.
South Korea
MFDS medical device software guidance and national AI semiconductor initiatives channel R&D investment toward edge-vision processing. Seoul Capital Area foundry and packaging infrastructure supports stacked-die sensor fabrication for consumer electronics integration. Busan-Ulsan industrial automation corridors drive qualification programs for factory floor deployment.
Event Camera Market Competitive Landscape
Listed leaders compete with private specialists across automotive qualification and industrial customization dimensions. The competitive set stratifies into automotive-qualified Tier-1 suppliers, high-speed industrial vision specialists, and consumer electronics integrators with captive foundry access. Three archetypes dominate: functional safety certifiers pursuing ISO 26262 ASIL-D compliance, neuromorphic sensor purists leveraging proprietary asynchronous architectures, and CMOS foundry operators embedding event pixels into mainstream mobile platforms. Dominant competitive moves include strategic partnerships for sensor-processor fusion platforms and geographic expansion into India PLI scheme electronics manufacturing zones.
Within the automotive-qualified tier, Prophesee and Texas Instruments exemplify divergent approaches to event-based perception integration. Samsung anchors the consumer electronics integration archetype through advanced CMOS foundry capabilities. These three entities represent the primary competitive anchors around which specialist module vendors and analytics software providers orbit.
| Leading Market Players |
|---|
| Samsung |
| Qualcomm |
| Prophesee |
| CEVA |
| Ambarella |
| IniVation |
| Texas Instruments |
| Intel |
| Sony |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with Taiwan-based foundries lock in wafer supply for automotive-qualified event sensors while fixing unit economics across 24-36 month ISO 26262 certification cycles. These contracts bundle die allocation with price visibility, compressing margin volatility for qualified Tier-1 suppliers while exposing non-automotive tier vendors to spot-market wafer pricing.
Pricing Analysis
Certification level creates the primary spread, with ISO 26262 ASIL-D qualified modules commanding substantial premiums over industrial-grade alternatives. Three-tier pricing structure across automotive-qualified, industrial-performance, and consumer-economy levels reflects validation burden and liability exposure. Cost compression in consumer-tier sensors intensifies as smartphone gesture interfaces scale volume, while automotive buyers show lowest price sensitivity due to qualification lock-in effects and safety-critical liability thresholds.
Supply Chain Analysis
Strategic stockpiling of advanced CMOS wafers dominates inventory strategy as buyers buffer against Taiwan foundry concentration and export control volatility. Stacked backside-illuminated sensor fabrication draws from Taiwan, South Korea, and Japan for lithography equipment, specialty gases, and advanced packaging substrates. Single-source vulnerability in EUV scanner availability feeds from ASML capacity constraints, while distribution runs through German automotive vision clusters and Yangtze River Delta electronics manufacturing bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as ISO 26262 bifurcation splits demand between automotive-qualified and industrial-grade tiers, creating distinct procurement ecosystems with divergent margin architectures. Sports analytics bundling and neuromorphic processor convergence further segment addressable niches.
For Market Incumbents: Shield automotive qualification positions by accelerating ASIL-D certification pipelines before competitor catch-up closes the 24-36 month window. Deepen backward integration into stacked-die sensor fabrication through captive Taiwan foundry partnerships or Japan packaging joint ventures to secure wafer allocation against export control volatility. For New Entrants and Emerging Players: Lead with sports analytics data-licensing contracts rather than hardware sales, exploiting broadcasters' shift toward bundled athlete-biometrics services. Target India's PLI scheme electronics manufacturing zones for module assembly serving domestic robotics demand, leveraging production-linked incentives to compress landed cost versus established suppliers. For Investors and Strategic Acquirers: Neuromorphic sensor purists with proprietary asynchronous architectures and spiking neural network accelerator partnerships represent the highest-conviction acquisition archetype for long-term positioning. Watch for FDA breakthrough device designations in vision-based medical applications as inflection signals for regulatory de-risking and reimbursement pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 ASIL-D Certification Investment | Locks in automotive OEM qualification cycles and excludes non-compliant competitors from high-ASP contracts. |
| Neuromorphic Processor Platform Partnership | Pairs event sensors with spiking neural network accelerators for sub-milliwatt always-on edge vision. |
| Sports Analytics Data-Licensing Acquisition | Captures recurring revenue from bundled athlete-biometrics contracts replacing discrete hardware procurement. |
| India PLI Scheme Manufacturing Footprint | Accesses production-linked incentives serving domestic robotics and drone perception demand growth. |
| EU AI Act Compliance Service Bundling | Attaches explainable output logging to embedded event-camera analytics for CE marking requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sensor platform engineers, automotive Tier-1 procurement leads, broadcast technology directors, and factory automation specification managers; and secondary validation through SEC semiconductor filings, MIIT industrial robot deployment statistics, EU F-Gas Regulation implementation timelines, and FDA 510(k) vision device clearances. Bottom-up unit economics triangulated against top-down market sizing across product architecture, application intensity, and end-user maturity segments.
Across the projection horizon, the analytical framework modeled volume and value trajectories by sensor type, certification tier, and regional regulatory cluster. CAGRs derived from segment-level adoption curves, OEM platform rollout schedules, and energy-efficiency tender specifications. Forecast inputs included EU Green Deal Scope 2 emission reduction commitments, MIIT dual carbon manufacturing targets, and broadcast rights-holder infrastructure refresh cycles.
Forecasts assume regulatory continuity in EU CE marking under MDR and AI Act frameworks, FDA medical device software guidance, and MIIT industrial automation mandates; material policy shifts would require re-modeling demand elasticity and qualification timeline assumptions. Practitioners should keep alternative scenarios live as semiconductor export control regimes and automotive OEM platform consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
LCD Digital Microscope Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
PET Imaging Systems Market
Imaging
Digitizer Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Industrial Camera Market
Imaging
Infrared Imaging Market
Imaging
Thermal Camera Market
Imaging
Camera Accessories Market
Imaging
Global 3D Imaging Market
Imaging
Widefield Imaging Systems Market
Imaging
X-Ray Systems Market
Imaging
Global Camera Module Market
Imaging
Global Digital Photo Frame Market
Imaging
Photoacoustic Tomography Market