
 Ceiling Microphone Market | 2026-2036
Ceiling Microphone Market Size, Share, and Industry Trends Forecast 2026-2036
Ceiling Microphone Market Analysis
Beamforming and Dante audio-over-IP integration is reshaping how ceiling microphones capture, process, and distribute speech across enterprise environments. Shure leverages its wireless ecosystem dominance to bundle networked ceiling arrays with DSP hardware, locking in installed-base loyalty across Fortune 500 conference rooms. Sennheiser sustains R&D intensity in TeamConnect ceiling systems, competing on acoustic beam-steering precision for open-plan huddle spaces. Biamp anchors its position through vertical integration into DSP and loudspeaker lines, controlling full signal-chain margins in government and education bids.
Ceiling microphones are permanently installed transducer systems designed for overhead capture of speech in fixed architectural environments, typically employing electret condenser capsules with cardioid or array-configured polar patterns and frequency responses optimized for 80 Hz to 20 kHz intelligibility. Array microphone configurations now lead product development pipelines as beam-steering replaces passive omnidirectional pickup in mid-to-large conference rooms. Digital microphone segments are expanding fastest where USB and Dante connectivity displace analog XLR infrastructure, though analog variants still occupy price-sensitive retrofit channels. Corporate offices and educational institutions represent the deepest end-user demand pools, with broadcast studios commanding premium-margin flush-mount installations requiring recessed ceiling integration.
FCC equipment authorization governs wireless transmission modules in US-sold ceiling microphones, while CE marking under the EU Radio Equipment Directive regulates RF emissions and interoperability for European deployments. OSHA acoustic exposure guidelines indirectly shape corporate procurement by mandating intelligibility standards in meeting spaces where ceiling microphones replace wearable alternatives. Procurement teams must weigh IP-network security protocols against analog simplicity as IT governance tightens around AV device onboarding.
Market Dynamics
Beamforming algorithms and Dante audio-over-IP networking are compressing product lifecycles as enterprise AV infrastructure migrates from analog XLR to networked digital architectures. Procurement teams now prioritize IT-governed device onboarding over traditional AV contractor specifications.
Growth Catalysts
- OSHA Intelligibility Mandates:Corporate meeting room acoustic standards under US workplace safety guidelines are accelerating replacement of wearable microphones with overhead array systems.
- Hybrid Work Infrastructure:Corporate real estate teams in the United States, Germany, and Japan are retrofitting conference rooms with permanent ceiling installations to standardize remote participant audio equity.
- Dante Audio Networking:Audinate's ecosystem dominance in professional AV is pulling ceiling microphone procurement toward IP-based signal distribution and centralized DSP management.
Market Restraints
- MEMS Capsule Supply Concentration:Electret condenser manufacturing clusters in East Asian foundries create single-source vulnerability for array microphone producers.
- Retrofit Installation Costs:Recessed ceiling integration requires structural modification and specialized labor, pricing analog-to-digital upgrades out of budget-constrained education districts.
- Wireless Spectrum Scarcity:FCC equipment authorization constraints on 2.4 GHz and 5 GHz bands limit channel density in multi-room corporate deployments.
Strategic Opportunities
- EU Green Deal Building Retrofits:Energy-efficient building renovation subsidies in Germany and France are bundling AV infrastructure upgrades with HVAC and lighting modernization.
- AI-Enhanced Noise Cancellation:Convergence of edge DSP processing with machine learning inference is opening premium pricing tiers for open-plan huddle space applications.
- Cloud-Managed AV Platforms:SaaS-based device provisioning and remote diagnostics are creating recurring revenue attachments for hardware manufacturers serving distributed enterprise footprints.
Industry Challenges
- Dante Certification Bottlenecks:Audinate's interoperability testing queue extends product launch timelines by six to nine months for networked ceiling array releases.
- Legacy Analog Integration Complexity:Hybrid signal environments requiring simultaneous XLR and Dante outputs strain firmware development resources and field commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceiling Microphone Market |
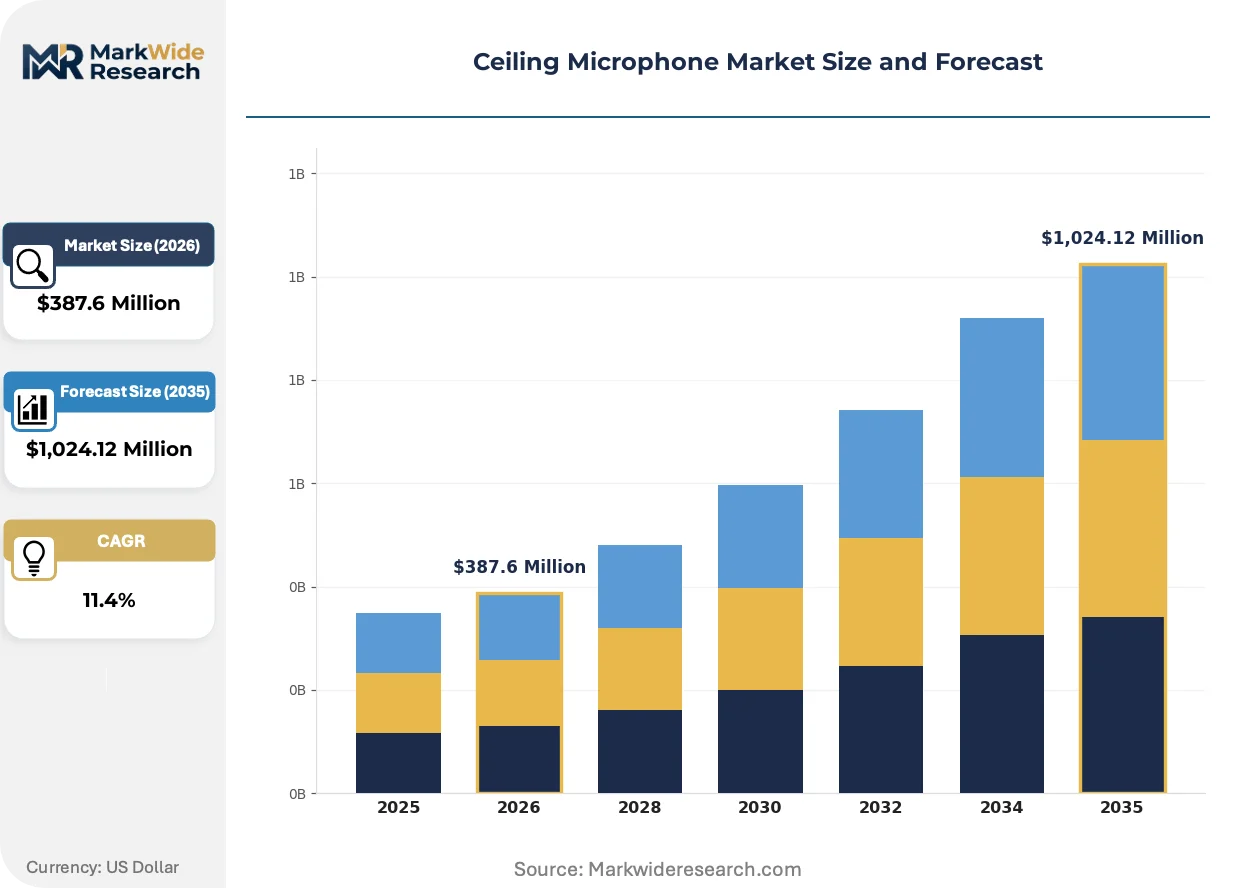
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Microphones, Digital Microphones, Array Microphones, Capacitor Microphones Technology: Omnidirectional, Directional, USB, Wireless End User: Corporate Offices, Educational Institutions, Broadcast Studios, Government Facilities Installation Type: Flush Mount, Pendant Mount, Recessed Mount, Surface Mount |
| Companies Covered | Beyerdynamic, Biamp, Shure, TOA Electronics, AKG, Sennheiser, ClearOne, MXL, Audio-Technica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceiling Microphone Market Emerging Trajectories
Audio capture architectures are pivoting from passive transduction to software-defined beam-steering, compressing hardware differentiation cycles and elevating firmware and algorithmic IP as primary competitive moats.
Steerable array configurations with adaptive beamforming is rendering obsolete fixed-polar-pattern ceiling microphones in mid-to-large conference rooms. Corporate AV managers in Fortune 500 technology and financial services sectors are specifying steerable arrays for all new construction and major renovation projects. The shift is rendering obsolete the installed base of omnidirectional and cardioid ceiling microphones installed during the 2015-2020 office construction wave.
CE marking under the EU Radio Equipment Directive is tightening RF emissions testing protocols for networked ceiling microphones sold into European Union member states. Manufacturers must now demonstrate interoperability compliance across multi-vendor Dante ecosystems before market authorization. German and French system integrators are prioritizing pre-certified hardware to avoid project timeline risk, compressing vendor selection pools to established networked audio specialists.
Enterprise IT governance teams are asserting procurement authority over AV device selection, displacing traditional facilities management ownership of conference room technology. Standardized security protocols and automated network onboarding are becoming mandatory evaluation criteria, favoring manufacturers with mature device management platforms. This pattern is most pronounced in United States technology sector headquarters and co-working space chains with centralized IT operations.
Ceiling Microphone Market Segmentation
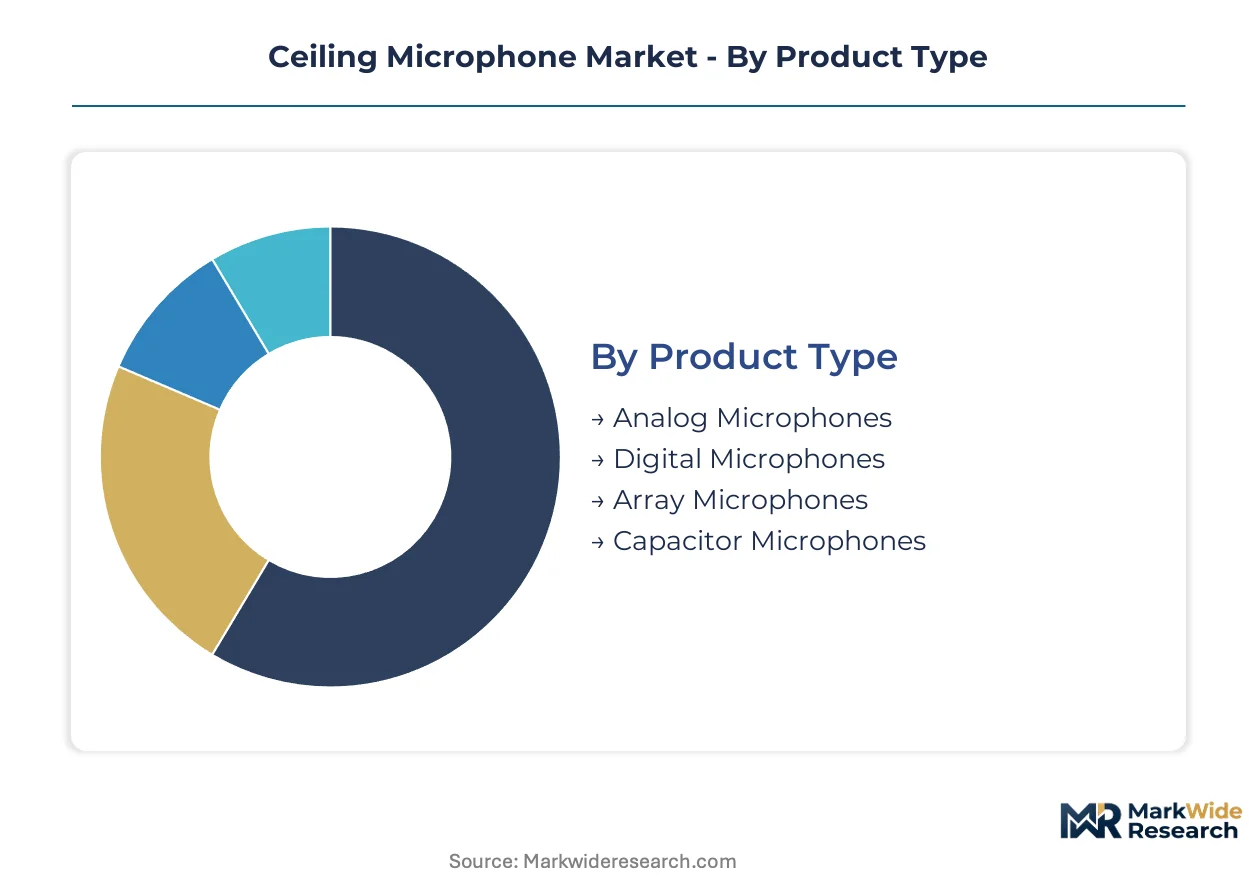
Ceiling microphone procurement diverges sharply across deployment contexts, from Fortune 500 boardrooms requiring steerable array precision to budget-constrained school districts prioritizing analog retrofit compatibility. Segmentation reveals how technical specifications, installation constraints, and end-user governance structures reshape vendor selection criteria and margin architecture.
Product Type:
Use-case spectrum spans passive transduction for legacy infrastructure to software-defined beamforming for new construction, with connectivity architecture determining IT governance compatibility and total cost of ownership.
- Array Microphones:Electret condenser capsules arranged in steerable configurations with adaptive beam-steering algorithms. Demand concentrates in United States corporate headquarters and German automotive boardrooms where hybrid meeting equity mandates justify premium installation spend.
- Digital Microphones:Dante audio-over-IP and USB connectivity displace analog XLR infrastructure in mid-to-large conference rooms. Adoption accelerates where IT departments assert procurement authority over AV device onboarding and network security protocols.
- Analog Microphones:XLR output electret condenser systems optimized for 80 Hz to 20 kHz speech intelligibility. Price-sensitive education districts in Japan and retrofit channels sustain residual demand despite digital migration pressure.
- Capacitor Microphones:Flush-mount electret designs requiring recessed ceiling integration. Broadcast studios in United States media markets command premium-margin installations with architectural concealment requirements.
Established volume favors Analog Microphones; emerging adoption favors Array Microphones.
Technology:
Cost tier stratification separates legacy omnidirectional pickup from precision beam-steering, with connectivity protocol determining network governance overhead and channel density limits.
- Directional:Cardioid polar patterns with fixed acoustic lobes for targeted speech capture. Corporate offices in Germany specify directional arrays for open-plan huddle spaces where ambient noise rejection outweighs steerability requirements.
- Wireless:2.4 GHz and 5 GHz transmission modules subject to FCC equipment authorization constraints. United States multi-room deployments face channel density scarcity that limits scalable enterprise rollout.
- USB:Plug-and-play digital connectivity for software-defined conferencing platforms. Educational institutions in Japan prioritize USB simplicity where IT support bandwidth constrains Dante network administration.
- Omnidirectional:Passive 360-degree pickup with no beam-steering capability. Remnant demand persists in small meeting rooms and price-sensitive retrofit installations.
Volume leadership sits with Directional; steepest expansion trajectory belongs to Wireless.
End User:
Customer type determines specification rigor, with governance complexity escalating from education procurement to federal security protocols.
- Corporate Offices:Hybrid work infrastructure mandates drive array microphone deployment across Fortune 500 technology and financial services headquarters. OSHA intelligibility standards accelerate replacement of wearable alternatives with permanent overhead installations.
- Educational Institutions:Budget-constrained K-12 districts and universities prioritize analog retrofit compatibility over Dante networking. Recessed installation costs price premium array systems out of public procurement cycles.
- Broadcast Studios:Flush-mount capacitor designs with recessed ceiling integration command premium-margin specifications. Acoustic precision requirements exceed standard enterprise conference room tolerances.
- Government Facilities:Security-cleared installation protocols and classified network isolation shape procurement around IT-governed device onboarding. Biamp and Sennheiser maintain entrenched positions through cleared contractor relationships.
Procurement scale favors Corporate Offices; security-driven premiumization favors Government Facilities.
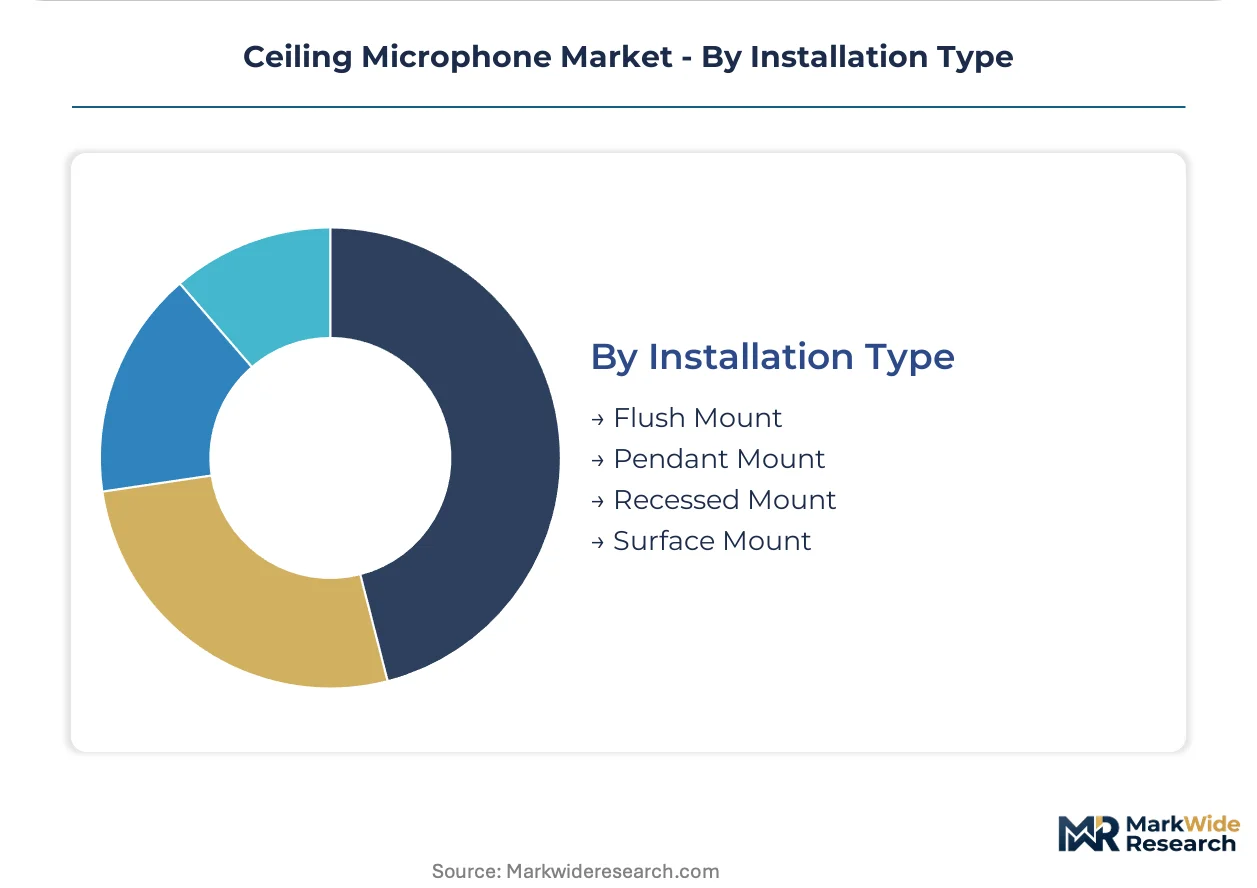
Installation Type:
Mounting geometry dictates labor specialization requirements and structural modification scope, with architectural integration depth correlating to project timeline risk and margin capture.
- Flush Mount:Recessed ceiling integration with visible grille only, requiring structural modification and specialized electrical contractor labor. Broadcast studios and premium corporate boardrooms in United States and Japan specify flush mount for architectural concealment.
- Recessed Mount:Partial ceiling penetration with baffle-mounted transducer housing. German system integrators prioritize pre-certified recessed hardware to avoid EU Radio Equipment Directive compliance delays.
- Pendant Mount:Suspended cable deployment for high-ceiling atrium spaces and historic building retrofits where structural ceiling modification is prohibited.
- Surface Mount:Exposed housing attachment to finished ceiling planes. Lowest-cost installation path sustains analog microphone deployment in education and small meeting room retrofits.
Margin concentration favors Flush Mount; volume accessibility favors Surface Mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ceiling microphone manufacturers export networked array systems to corporate buyers in the United States and Japan, establishing the primary transatlantic and transpacific trade corridors for premium AV infrastructure.
United States
Fortune 500 technology and financial services headquarters in Silicon Valley and Manhattan drive array microphone procurement for hybrid meeting equity. FCC equipment authorization governs wireless transmission modules under Part 15 rules, constraining 2.4 GHz and 5 GHz channel density in multi-room deployments. Corporate real estate teams in Austin and Seattle are retrofitting conference rooms with Dante-networked ceiling installations.
Germany
Automotive boardrooms in Stuttgart and Munich specify precision beam-steering arrays for executive conferencing suites. CE marking under the EU Radio Equipment Directive mandates RF emissions testing and multi-vendor Dante interoperability compliance. System integrators in Frankfurt prioritize pre-certified hardware to avoid project timeline delays from certification bottlenecks.
Japan
Educational institutions in Tokyo and Osaka prioritize USB-connected ceiling microphones where IT support bandwidth limits Dante network administration. METI industrial standards shape procurement specifications for public sector AV infrastructure. Broadcast studios in the Kanto region command premium-margin flush-mount installations with architectural concealment requirements.
United Kingdom
Co-working space chains with centralized IT operations in London specify IT-governed device onboarding and automated network security protocols. GDPR data protection requirements influence cloud-managed AV platform selection for distributed enterprise footprints. System integrators in Manchester and Birmingham are bundling ceiling microphone upgrades with commercial building modernization projects.
France
EU Green Deal building renovation subsidies in Paris and Lyon are bundling AV infrastructure upgrades with HVAC and lighting modernization. ANSM and CNIL guidance shapes procurement around network security for government facility installations. Corporate headquarters in Île-de-France are accelerating Dante audio networking migration from legacy analog XLR infrastructure.
Ceiling Microphone Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: diversified audio conglomerates with wireless ecosystem dominance, precision acoustic specialists with beam-steering R&D intensity, and vertically integrated signal-chain providers capturing full-margin government and education bids. Dominant competitive moves include backward integration into DSP hardware and loudspeaker lines, plus strategic partnerships for Dante certification acceleration.
Within the diversified audio conglomerate tier, Shure and Sennheiser exemplify contrasting approaches to ecosystem lock-in versus acoustic precision specialization. Biamp anchors the vertically integrated archetype through captive supply of DSP and loudspeaker components. Beyerdynamic and Audio-Technica occupy positions between these poles, representing mid-scale fabricators with established installed-base relationships in European and Asia-Pacific markets. ClearOne and MXL exemplify product-specialist players competing on price-accessible USB and analog retrofit compatibility for budget-constrained education procurement.
| Leading Market Players |
|---|
| Beyerdynamic |
| Biamp |
| Shure |
| TOA Electronics |
| AKG |
| Sennheiser |
| ClearOne |
| MXL |
| Audio-Technica |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors from East Asian component hubs to US distribution centers transmit cost volatility directly into ceiling microphone pricing tiers, amplifying the spread between premium array systems and economy analog units as MEMS capsule supply concentrates in Taiwan and South Korean foundries.
Pricing Analysis
Next-generation beamforming array systems command substantial premiums over legacy omnidirectional units and transitional digital models. Three-tier pricing structure across premium, standard, and economy levels separates Dante-certified networked arrays from USB-connected mid-tier products and XLR-only retrofit microphones. Price differentiation rests on certification grade and IT governance compatibility, with OSHA-mandated intelligibility standards compressing margins at the economy tier. Educational institutions exhibit highest price sensitivity due to recessed installation labor costs, while Fortune 500 corporate buyers prioritize performance over unit economics.
Supply Chain Analysis
Contract manufacturing capacity for electret condenser capsules concentrates in Foxconn and Pegatron facilities across Taiwan, with secondary assembly nodes in Dongguan and Penang. Raw material dependencies span neodymium magnets from Chinese rare earth processors, copper voice coils from Chilean smelters, and PCB substrates from South Korean laminators. Single-source vulnerability in MEMS foundry capacity creates procurement risk for array microphone producers. Distribution runs through AV integrators and direct enterprise sales channels, with cloud-managed platforms enabling SaaS-style recurring attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where Dante certification entrenchment and installed-base switching costs protect incumbent positions against price-based challengers.
For Market Incumbents: Harden ecosystem lock-in through captive DSP hardware bundling and accelerated Dante interoperability pre-certification. MEMS capsule supply concentration threatens margin stability; backward integration into transducer manufacturing or long-term offtake agreements with Taiwan foundries secures component access. Channel control via certified installer networks reinforces pricing power against USB-only entrants. For New Entrants and Emerging Players: Build out white-space positions in pendant-mount retrofits for historic building AV upgrades and AI-enhanced noise cancellation modules for open-plan huddle spaces. Japan's education sector presents the most penetrable geography given IT support bandwidth constraints favoring plug-and-play USB simplicity over networked complexity. Direct-to-institution digital marketing bypasses entrenched integrator relationships. For Investors and Strategic Acquirers: CE marking tightening under EU Radio Equipment Directive reshapes the acquisition landscape toward pre-certified hardware specialists with established European system integrator relationships. Long-term viability centers on firmware-defined differentiation rather than transducer commoditization. Target acquisition archetype: edge-Audio DSP startups with machine learning inference capabilities. The signal to monitor is Audinate's certification queue length as a leading indicator of product launch velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Dante Certification Pre-Investment | Accelerates product launch timelines by bypassing Audinate's six-to-nine month testing queue. |
| AI Noise Cancellation Module Development | Opens premium pricing tiers for open-plan huddle space applications in Fortune 500 campuses. |
| Cloud-Managed AV Platform Launch | Creates recurring revenue streams through SaaS-based device provisioning and remote diagnostics. |
| MEMS Foundry Partnership Agreement | Secures electret condenser capsule supply against single-source vulnerability in Taiwan manufacturing clusters. |
| EU Green Deal Retrofit Bundling | Captures German and French building modernization subsidies by packaging ceiling microphones with HVAC upgrades. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with AV system integrators, corporate real estate technology directors, educational procurement officers, and Dante network administrators. Secondary validation drew from FCC equipment authorization databases, CE marking registries under EU Radio Equipment Directive, Audinate ecosystem compatibility listings, and commercial construction permit filings. Bottom-up unit shipment estimates triangulated against top-down enterprise IT spending allocations across the analysis window.
Calibration against historical Dante adoption curves and OSHA workplace acoustic standard implementation timelines anchored the projection framework. Segmentation dimensions spanned product architecture, connectivity protocol, end-user governance complexity, and installation type across the modeling period. CAGRs were derived from regression analysis of technology substitution rates and infrastructure replacement cycles. Forecast inputs incorporated hybrid work permanence assumptions and EU Green Deal building retrofit subsidy trajectories.
Stress conditions across MEMS supply disruption severity, wireless spectrum allocation changes, and corporate real estate budget contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology migration pace and regulatory enforcement intensity. Quarterly review of Dante certification queue lengths, commercial construction starts in target metropolitan clusters, and educational district bond issuance volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Dual Relay Board Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Microspeaker Market
Electronic Components
SAW Filters Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Audio CODEC Market
Electronic Components
High Density Interconnect (HDI) PCB Market