
 Rotary Encoders Market | 2026-2036
Rotary Encoders Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Encoders Market Analytics
Optical sensing elements are restructuring cost structures across precision feedback systems as magnetic alternatives gain traction in harsh-environment applications. DR. Johannes Heidenhain GmbH anchors its position through ultra-high-resolution optical scale manufacturing in Germany. Pepperl+Fuchs SE differentiates via robust magnetic encoder portfolios for heavy-industrial settings. Broadcom Inc. leverages semiconductor integration capabilities to compete in compact, high-volume sensor modules.
A rotary encoder converts angular position or rotational speed into electrical signals through optical, magnetic, capacitive, or inductive sensing principles, typically achieving resolutions from 1 to 65,536 pulses per revolution depending on the technology employed. These devices serve as critical feedback elements in closed-loop motion control systems across factory automation, robotics, and precision machining. Absolute encoders dominate applications requiring position retention during power loss, while incremental variants capture the fastest growth in cost-sensitive automation lines. Digital output interfaces now command premium positioning over legacy analog formats as Industry 4.0 architectures demand direct controller connectivity.
The EU Machinery Directive and ISO 13849 functional safety standards are elevating certification requirements for encoders deployed in human-collaborative robot cells. Japan's METI energy-efficiency guidelines and the US OSHA machine-guarding regulations are similarly tightening specifications for feedback devices in automated equipment. Stakeholders must weigh magnetic versus optical technology commitments against evolving safety integrity level demands and regional compliance timelines.
Market Dynamics
Industrial automation in automotive assembly lines is accelerating encoder deployment as closed-loop motion control becomes mandatory for precision manufacturing. The EU Machinery Directive's tightening safety-rated feedback requirements are forcing rapid technology transitions across European factory floors.
Growth Catalysts
- EU Machinery Directive compliance mandates:Safety integrity level certifications now required for encoders in human-collaborative robot cells are expanding addressable market for certified feedback devices.
- Automotive EV powertrain manufacturing:Battery assembly lines in China and Germany require sub-micron positioning accuracy that only high-resolution optical encoders deliver.
- Magnetic sensing advancement:Improved magnetic encoder durability in heavy-industrial settings is opening applications previously dominated by optical alternatives.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings directly compress margins for magnetic encoder manufacturers dependent on Chinese supply.
- Optical component supply concentration:Precision glass scale manufacturing clusters in southern Germany create single-point vulnerability for high-resolution encoder supply chains.
- Functional safety certification timelines:ISO 13849 compliance testing extends product development cycles by 8-14 months for new encoder platforms.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for industrial automation equipment are creating first-mover advantage for encoder vendors establishing local assembly.
- Wireless encoder protocols:Integration of IO-Link Wireless and Bluetooth LE is eliminating cable maintenance costs in rotating machinery applications.
- US IRA clean energy manufacturing:Domestic content requirements for wind turbine and solar tracker production are reshoring demand for precision feedback systems.
Industry Challenges
- Embedded firmware security expertise:IEC 62443 cybersecurity standards for industrial automation require encoder manufacturers to build in-house secure coding capabilities.
- Legacy analog system integration:Retrofitting 4-20mA and SSI interfaces into Industry 4.0 architectures demands custom gateway development that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Encoders Market |
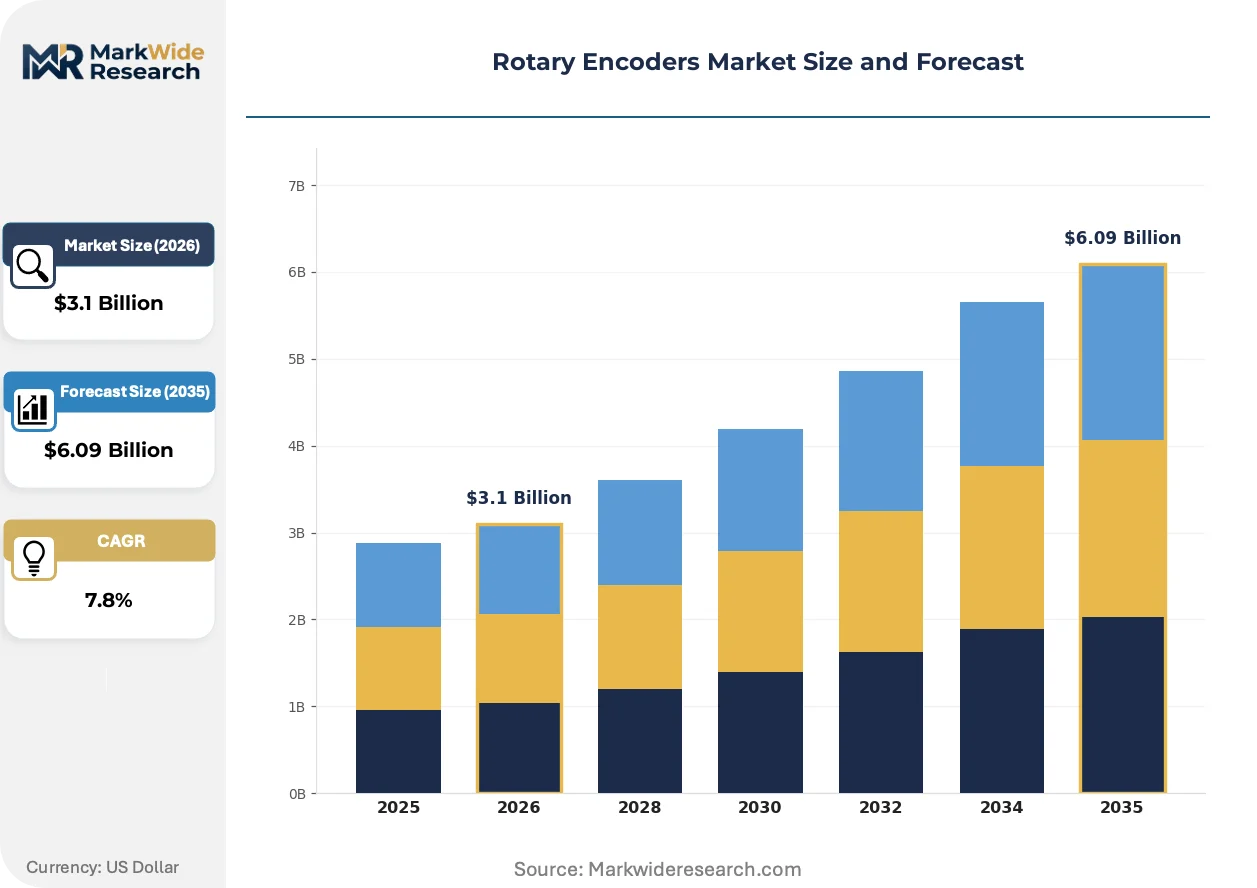
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Absolute, Incremental, Optical, Magnetic Technology: Analog, Digital, Capacitive, Inductive Application: Automation, Robotics, Aerospace, Automotive End User: Manufacturing, Telecommunications, Consumer Electronics, Medical |
| Companies Covered | Broadcom Inc., Kübler GmbH, DR. Johannes Heidenhain GmbH, Renishaw PLC, Dynapar Corporation, Pepperl+Fuchs SE, Bourns Inc., Baumer Group, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Encoders Market Evolving Landscape
Encoder technology is bifurcating between ultra-high precision optical systems and ruggedized magnetic alternatives, with interface standardization determining competitive positioning. This divergence is reshaping R&D allocation and partnership strategies across component suppliers.
Capacitive sensing is absorbing market share in semiconductor manufacturing equipment where optical contamination risks and magnetic interference coexist. Wafer handling robot OEMs in Japan and Taiwan are adopting capacitive encoders at triple-digit annual growth rates. The technology is absorbing applications that previously required dual-sensor redundancy, collapsing bill-of-materials complexity.
REACH restrictions on perfluorinated compounds are compelling encoder manufacturers to reformulate lubricants and sealing materials used in precision bearings. The industrial consequence is a 12-18 month qualification cycle for new material stacks. Automotive powertrain applications in Germany face the tightest compliance deadlines, pushing suppliers toward fluorine-free alternatives ahead of other regions.
Direct-to-controller digital interfaces are displacing analog signal conditioning in new machine designs. Machine builders in China's Yangtze River Delta are specifying EtherCAT and PROFINET encoder modules as standard, bypassing traditional distributor channels for technical specification. This pattern is most visible in packaging machinery and electronics assembly, where controller-encoder integration determines system commissioning speed.
Rotary Encoders Market Segmentation
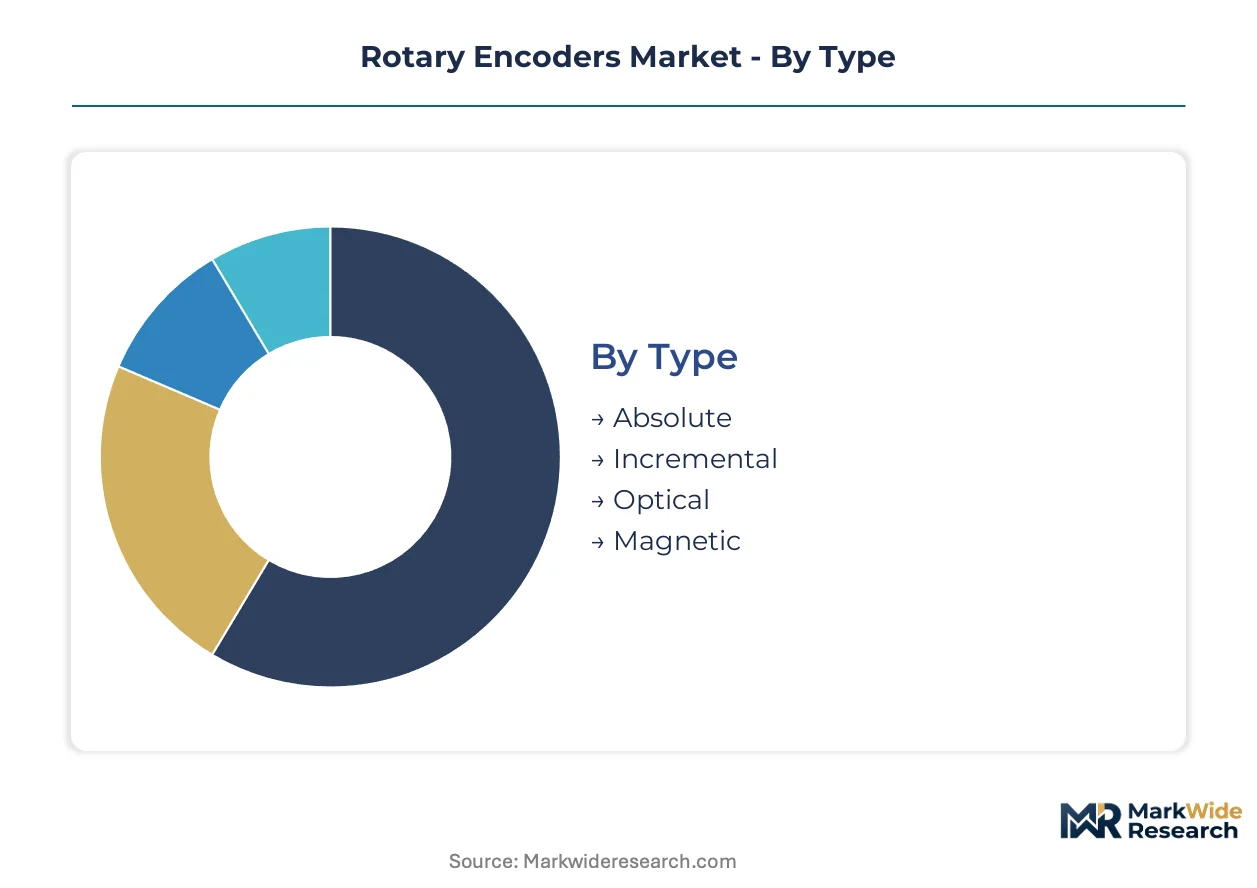
Rotary encoder procurement patterns diverge sharply across motion control architectures. Buyers select encoder categories based on power-loss tolerance, environmental exposure, and controller interface requirements rather than unit cost alone.
Type:
Cost tier separates specification-driven buyers from maintenance-focused purchasers.
- Absolute:These encoders retain position data during power interruptions through battery-backed or gear-based multi-turn tracking. Automotive battery assembly lines in Germany specify absolute encoders for safety-critical axis homing elimination. The EU Machinery Directive's safety integrity mandates are accelerating displacement of incremental alternatives in collaborative robot cells.
- Incremental:Optical disk interruption generates pulse trains requiring external reference for position calculation. Packaging machinery OEMs in China's Yangtze River Delta specify incremental encoders for cost-sensitive high-speed lines. Volume concentrates here; magnetic variants are gaining share fastest in heavy-industrial settings.
- Optical:Glass or metal scale interpolation achieves sub-micron resolution for precision machining.
- Magnetic:Hall-effect or magnetoresistive sensing withstands contamination and vibration in mining equipment.
Volume sits with Incremental; growth tilts toward Absolute.
Technology:
Interface maturity determines integration speed with Industry 4.0 controller architectures.
- Analog:Sine-cosine or 4-20mA outputs persist in legacy retrofit applications. Wind turbine pitch control systems in the US retain analog encoders for compatibility with existing safety PLCs. Maintenance departments face 12-18 month gateway development cycles for digital migration.
- Digital:EtherCAT, PROFINET, and BiSS-C protocols enable direct controller connectivity without signal conditioning. Machine builders specify digital encoders to compress commissioning timelines. Expansion is steepest here as IO-Link Wireless eliminates rotary joint cabling.
- Capacitive:Electric field variation sensing operates in semiconductor cleanrooms where optical contamination risks exist.
- Inductive:Eddy-current principles deliver encoder functionality through metal barriers in harsh environments.
Installed base favors Analog; specification momentum belongs to Digital.
Application:
Precision requirements and duty cycle intensity shape technology selection across verticals.
- Automation:Factory motion control demands span from conveyor feedback to multi-axis synchronized positioning. Automotive powertrain lines in Germany and China absorb the highest encoder density per square meter of manufacturing space. Battery cell stacking operations require sub-micron repeatability.
- Robotics:Collaborative robot joints specify safety-rated encoders with SIL 2/PL d certification minimum. Joint torque sensing integration is collapsing separate encoder and sensor bills of materials.
- Aerospace:Flight control surface position feedback demands extended temperature range and radiation tolerance.
- Automotive:Steering angle and motor position sensing in EV powertrains specify automotive-grade AEC-Q100 qualified devices.
Revenue concentrates in Automation; Robotics exhibits the steepest specification escalation.
End User:
Certification burden and volume scale create divergent procurement economics across sectors.
- Manufacturing:Discrete and process automation lines generate encoder demand proportional to axis count. German automotive suppliers and Chinese electronics assemblers represent the highest absolute consumption. REACH fluorinated compound restrictions are forcing 12-18 month lubricant qualification cycles.
- Telecommunications:Antenna positioning systems and satellite tracking drives specify encoders for azimuth and elevation feedback. 5G beam-steering infrastructure is creating new rotary joint encoder specifications.
- Consumer Electronics:Haptic feedback motors and camera gimbals absorb compact magnetic encoders in high volumes.
- Medical:Imaging equipment and surgical robots require ISO 13485 quality system traceability and EMC immunity certification.
Manufacturing dominates volume; Medical commands the highest unit premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and Japan concentrate demand for precision motion control systems. Automotive battery assembly lines and industrial automation investments drive encoder procurement across these manufacturing powerhouses.
China
EV powertrain manufacturing absorbs high-resolution optical encoders for battery cell stacking operations. MIIT industrial upgrading guidelines mandate smart factory equipment adoption by 2027. The Yangtze River Delta machine builder ecosystem specifies EtherCAT encoder modules as standard for packaging machinery.
Germany
Automotive assembly lines generate the highest encoder density per square meter of manufacturing space globally. The EU Machinery Directive's SIL 2/PL d certification requirements force rapid technology transitions across Bavarian and Baden-Württemberg factory floors. Precision glass scale manufacturing clusters in southern Germany create supply chain concentration for ultra-high-resolution devices.
Japan
Collaborative robot OEMs in the Kanto region specify safety-rated encoders with integrated torque sensing. METI energy-efficiency guidelines tighten specifications for feedback devices in automated equipment. Wafer handling robot manufacturers in Tokyo and Nagoya are adopting capacitive encoders at accelerated rates for semiconductor cleanrooms.
United States
Wind turbine pitch control and solar tracker production drive encoder demand under IRA domestic content requirements. OSHA machine-guarding regulations tighten feedback device specifications for automated equipment. The Midwest manufacturing belt and Texas energy corridor are reshoring precision feedback system assembly.
India
PLI scheme incentives for industrial automation equipment create first-mover opportunities for encoder vendors establishing local assembly. BIS standards alignment with IEC 61508 functional safety protocols is elevating certification requirements. The Maharashtra and Gujarat industrial corridors are absorbing incremental encoders for cost-sensitive high-speed packaging lines.
Rotary Encoders Market Competitive Landscape
Technology licensing agreements dominate the current landscape as magnetic sensing advancement accelerates. The vendor base organizes around three tiers: integrated semiconductor suppliers, specialized precision sensor manufacturers, and regional automation component distributors. Two strategic archetypes prevail—optical scale specialists anchored in German precision engineering clusters, and magnetic encoder developers targeting heavy-industrial durability requirements. M&A activity and strategic partnerships represent the primary competitive vectors as players seek complementary interface protocol capabilities.
Within the precision optical tier, DR. Johannes Heidenhain GmbH and Renishaw PLC exemplify German and British engineering heritage respectively. Pepperl+Fuchs SE occupies a position among robust magnetic encoder developers serving heavy-industrial applications. Broadcom Inc. represents semiconductor-integrated suppliers competing in compact, high-volume sensor modules. These three anchors illustrate the technology bifurcation between ultra-high-resolution optical systems and ruggedized magnetic alternatives reshaping competitive positioning.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Kübler GmbH |
| DR. Johannes Heidenhain GmbH |
| Renishaw PLC |
| Dynapar Corporation |
| Pepperl+Fuchs SE |
| Bourns Inc. |
| Baumer Group |
| Omron Corporation |
| Others |
Value Network & Pricing Analysis
Neodymium and dysprosium price swings cascade through magnetic encoder manufacturing tiers, with rare earth magnet cost volatility compressing margins for vendors dependent on Chinese supply while optical scale specialists in southern Germany command premium positioning through precision glass manufacturing concentration.
Pricing Analysis
Volume concentrates with incremental encoders in cost-sensitive packaging machinery across China's Yangtze River Delta, while absolute encoders with SIL 2/PL d certification capture margin premiums in German automotive battery assembly. Price differentiation hinges on functional safety certification grade and optical resolution tier. Pricing pressure stems from REACH fluorinated compound restrictions forcing 12-18 month lubricant qualification cycles. Maintenance-focused purchasers in legacy wind turbine retrofits exhibit highest price sensitivity; safety-critical EV powertrain OEMs in Germany show lowest.
Supply Chain Analysis
Single-source vulnerability sits with precision glass scale manufacturing clusters in southern Germany, where DR. Johannes Heidenhain GmbH and concentrated optical component suppliers anchor ultra-high-resolution encoder supply. Raw material dependencies span rare earth magnets from China, precision bearings from Japan, and semiconductor dies from Taiwan. Tariff exposure on Chinese magnet supply creates structural risk for magnetic encoder portfolios. Distribution runs through regional automation component distributors and direct machine builder specifications in industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive's SIL 2/PL d certification mandates have erected a cost-of-compliance barrier that favors incumbent precision sensor manufacturers with established safety engineering capabilities, locking out unqualified entrants from collaborative robot and automotive safety-critical applications.
For Market Incumbents: Cement certification leadership by accelerating ISO 13849 compliance testing infrastructure investment ahead of EU enforcement timelines. Acquire magnetic sensing specialists in heavy-industrial segments to defend against optical-to-magnetic technology substitution in mining and material handling equipment.
For New Entrants and Emerging Players: The premium-to-economy price gap in incremental encoders for India's PLI-subsidized packaging machinery offers white-space entry with locally assembled, BIS-certified alternatives. Target Maharashtra and Gujarat industrial corridors with cost-optimized EtherCAT modules. Pursue wireless encoder protocol differentiation via IO-Link Wireless integration to bypass established cable-dependent incumbents.
For Investors and Strategic Acquirers: Accelerated capacitive encoder adoption by Tokyo and Nagoya wafer handling robot OEMs is the leading indicator that semiconductor manufacturing equipment feedback systems are decoupling from optical-magnetic duopoly. Target mid-cap inductive and capacitive sensing specialists with cleanroom-qualified portfolios. Watch for MIIT smart factory equipment mandates triggering consolidation among Yangtze River Delta encoder distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | ISO 13849 SIL 2/PL d compliance unlocks EU collaborative robot cell specifications. |
| Magnetic Encoder Portfolio Expansion | Hall-effect and magnetoresistive sensing captures mining equipment applications from optical alternatives. |
| Wireless Protocol Integration | IO-Link Wireless eliminates rotary joint cabling costs in wind turbine pitch control systems. |
| India Local Assembly Establishment | PLI scheme incentives for industrial automation equipment create first-mover manufacturing advantage. |
| Capacitive Sensing Technology Acquisition | Cleanroom-qualified electric field encoders absorb semiconductor wafer handling robot demand. |
Research Methodology
Document review covered SEC filings from Broadcom Inc. and Renishaw PLC, EU Machinery Directive implementation guidance, METI energy-efficiency guidelines, and MIIT industrial upgrading protocols, complemented by interviews with plant engineers at German automotive OEMs, procurement leads at Chinese packaging machinery OEMs, maintenance directors at US wind farm operators, and technical R&D directors at Japanese collaborative robot manufacturers. Secondary validation drew from customs trade data, IEC 61508 certification registries, and REACH restriction documentation. Bottom-up encoder shipment estimates triangulated against top-down industrial automation capex forecasts.
Historical encoder adoption patterns in automotive powertrain and semiconductor manufacturing equipment were cross-referenced against panel input from motion control system integrators. Segmentation modeling spanned encoder type, technology interface, application vertical, and end-user industry across the projection horizon. CAGRs were derived from regression analysis of industrial robot density trends and EV battery assembly line investment flows. Forecast inputs included BIS standards alignment timelines and OSHA machine-guarding regulatory update schedules.
Inputs from German precision glass scale manufacturers and Chinese rare earth magnet suppliers were available through the study window; gaps in India PLI scheme disbursement timing and REACH fluorinated compound substitution qualification data introduce uncertainty bands around regional growth trajectories. Forecasts reflect assumptions regarding EU Machinery Directive enforcement consistency and MIIT smart factory mandate adherence. Deviation in neodymium supply chain disruption severity or ISO 13849 certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market