
 Absolute Encoders Market | 2026-2036
Absolute Encoders Market Size, Share, and Industry Trends Forecast 2026-2036
Absolute Encoders Market Outlook
German precision component manufacturers are pivoting toward captive production of optical scale substrates and magnetic sensing elements. HEIDENHAIN leverages its in-house graduation and scanning technology to dominate high-end machine tool applications. Renishaw sustains technology leadership through advanced interferometric and optical encoder architectures for semiconductor lithography. POSITAL FRABA competes aggressively on magnetic encoder cost structures while extending its hollow shaft and kit encoder formats for motor-integrated designs.
Absolute encoders are electromechanical devices that output a unique digital position code for every shaft or linear displacement, typically resolving to 16–25 bits per revolution without requiring a homing reference cycle. They employ optical gratings, magnetic pole arrays, or capacitive/inductive sensing elements to translate mechanical motion into deterministic digital data for closed-loop motion control systems. Rotary encoders remain the volume backbone across factory automation, yet multi-turn encoders are capturing disproportionate margin growth as battery-free Wiegand-effect and geared counting designs displace traditional battery-backed solutions in wind turbines and mobile machinery. Magnetic technology is accelerating fastest in cost-sensitive robotics and automotive auxiliary positioning where optical contamination risks dominate, while inductive encoders carve defensive specialist positions in extreme temperature and high-vibration environments.
CE marking under the EU Machinery Directive and functional safety certifications per ISO 13849 and IEC 61508 are tightening product validation requirements for encoder suppliers targeting European OEM channels. China's SAMR enforces GB standards for measurement accuracy and electromagnetic compatibility that condition market access for imported encoder platforms. FDA device regulations and FAA airworthiness criteria constrain encoder architectures in medical imaging and aerospace flight control applications. Stakeholders must monitor how regional certification divergence affects platform standardization strategies and whether magnetic encoders can close the resolution gap with optical alternatives in precision metrology segments.
Market Dynamics
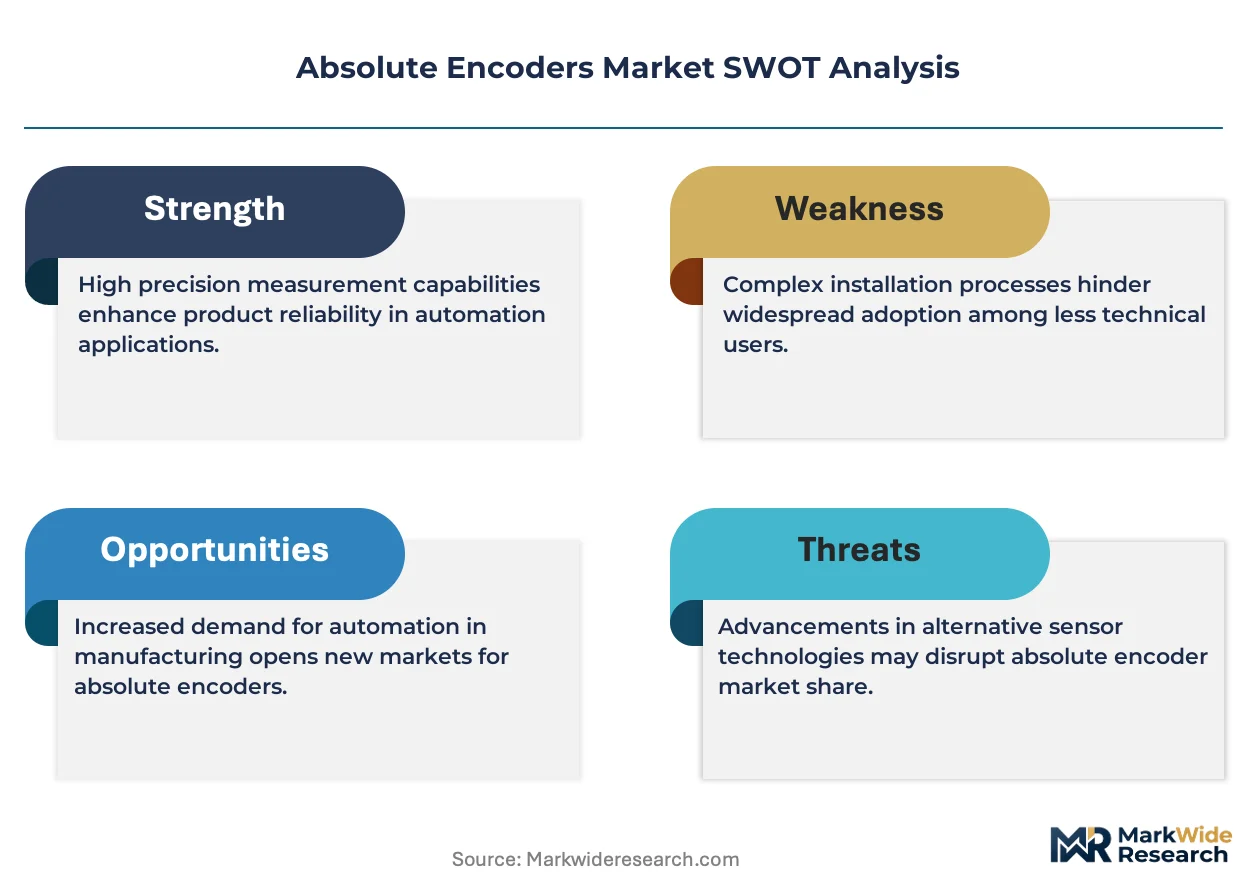
Magnetic encoder technology is absorbing volume from optical platforms as robotics OEMs prioritize contamination resilience over absolute resolution, while CE marking and functional safety certifications per ISO 13849 reshape supplier qualification requirements across European industrial channels.
Growth Catalysts
- Battery-free multi-turn designs:Wiegand-effect and geared counting architectures eliminate battery maintenance in wind turbines and mobile machinery, displacing traditional battery-backed absolute encoders in remote installations.
- EU machinery safety directives:Stricter CE marking requirements under the EU Machinery Directive compel OEMs to specify certified encoders with SIL-rated functional safety, expanding addressable premium segments.
- China's eastern manufacturing corridor:Robotics integrators in Shanghai, Suzhou, and Shenzhen require multi-turn absolute positioning for precision assembly lines, concentrating demand for high-resolution magnetic and optical platforms.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and samarium-cobalt price swings compress margins for magnetic encoder suppliers dependent on Chinese rare earth processing concentration.
- Optical contamination vulnerability:Dust, oil, and coolant exposure in metalworking environments limits optical encoder deployment, forcing costly sealed housing designs or technology switching.
- Resolution ceiling in magnetic sensing:Magnetic pole pitch constraints and hysteresis effects cap practical resolution below optical interferometric alternatives, excluding magnetic platforms from semiconductor lithography and precision metrology.
Strategic Opportunities
- Inductive encoder white space:Extreme temperature and high-vibration environments in steel mills, mining equipment, and aerospace actuators remain underpenetrated by traditional optical and magnetic technologies.
- Kit encoder motor integration:Hollow shaft and bearingless encoder formats enable direct mounting inside servo motors and direct-drive torque motors, capturing value from motor-integrated motion control architectures.
- CSRD supply chain disclosure:EU Corporate Sustainability Reporting Directive mandates encoder suppliers document material sourcing and carbon footprint, creating differentiation for transparent manufacturers.
Industry Challenges
- Functional safety certification timelines:SIL and PL validation per IEC 61508 and ISO 13849 requires 12-18 month third-party assessment cycles, delaying new product launches and freezing engineering resources.
- Legacy fieldbus integration complexity:Proprietary serial protocols and aging SSI/BISS interfaces persist in installed machine tool bases, forcing dual-interface encoder designs or costly retrofit engineering.
- Optical scale substrate supply concentration:Precision glass and steel graduation manufacturing concentrates among German and Japanese specialists, creating single-source vulnerability for high-end encoder producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absolute Encoders Market |
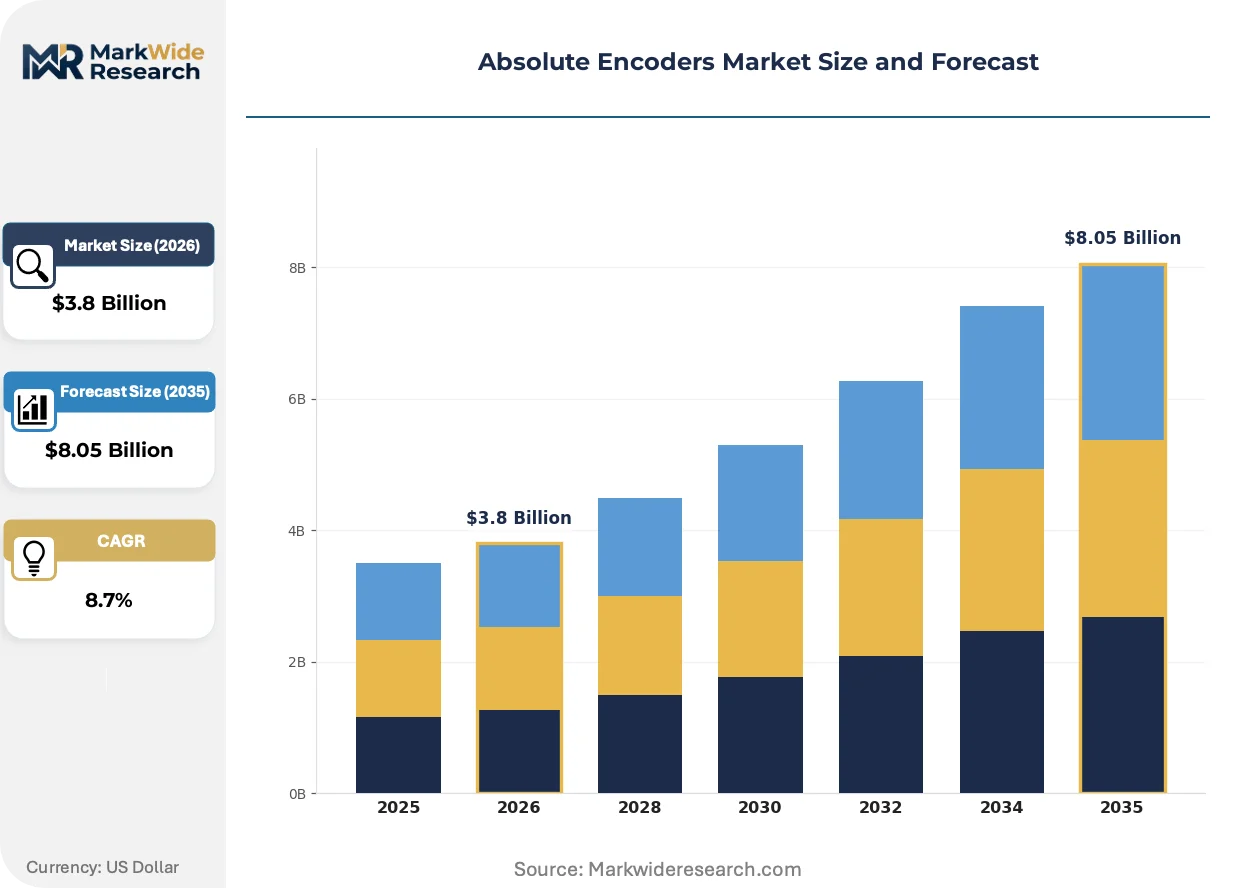
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
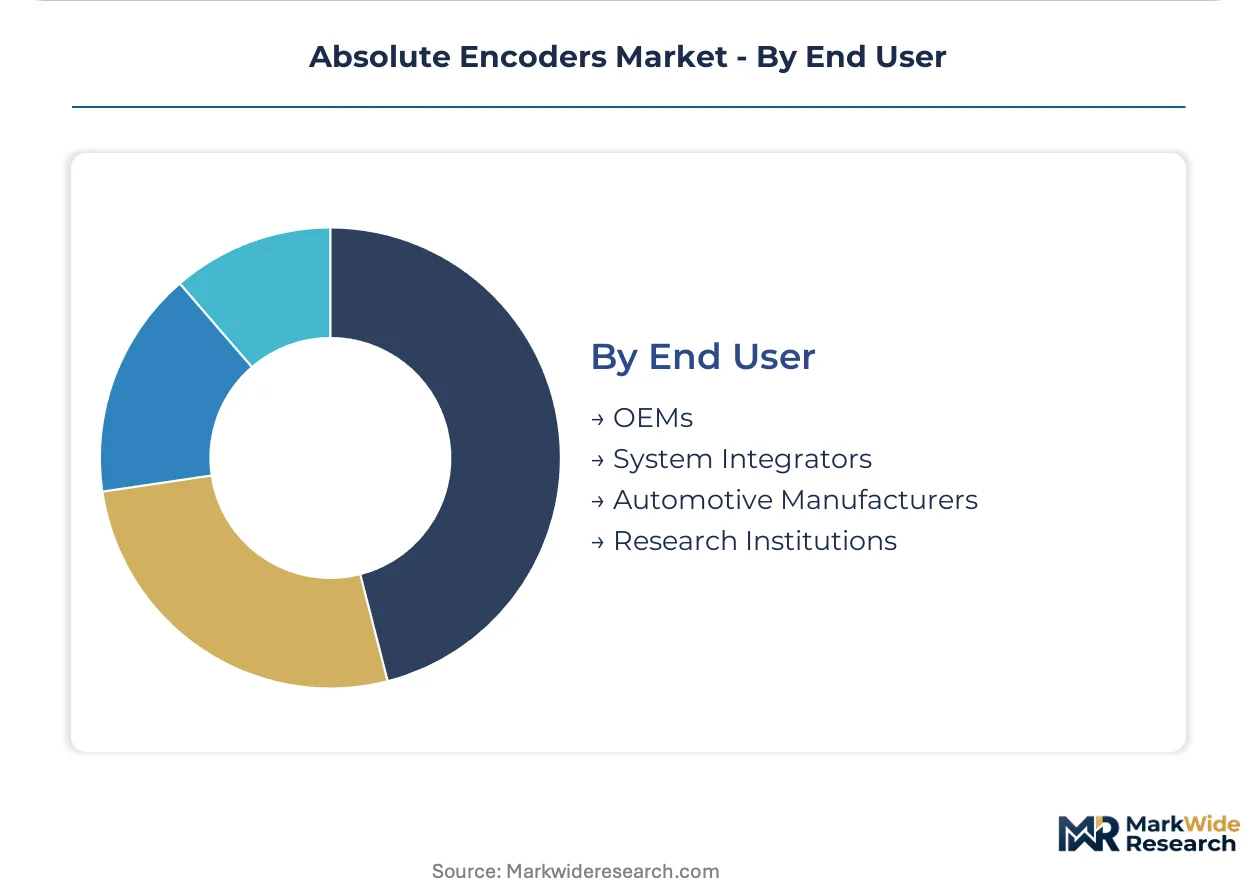
| Segmentation | Product Type: Rotary Encoders, Linear Encoders, Hollow Shaft Encoders, Multi-Turn Encoders Technology: Optical, Magnetic, Capacitive, Inductive Application: Industrial Automation, Robotics, Aerospace, Consumer Electronics End User: OEMs, System Integrators, Automotive Manufacturers, Research Institutions |
| Companies Covered | HEIDENHAIN, Renishaw, Baumer Group, SICK AG, Sensata Technologies, Rockwell Automation, Dynapar Corporation, TE Connectivity, POSITAL FRABA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absolute Encoders Market Strategic Shifts
Encoder architectures are bifurcating between cost-optimized magnetic platforms for robotics and automotive auxiliary positioning, and interferometric optical systems defending precision metrology strongholds, with certification requirements increasingly dictating technology selection criteria.
Magnetic sensing with 23-bit resolution is absorbing demand from mid-precision factory automation applications where optical contamination risks dominate. Automotive tier-one suppliers and collaborative robot manufacturers specify magnetic encoders for joint actuators and steering column positioning, compressing the viable addressable market for entry-level optical alternatives and forcing graduation technology suppliers to defend premium lithography and machine tool segments.
CE marking under the EU Machinery Directive and functional safety mandates per ISO 13849 are tightening product validation requirements for encoder suppliers targeting European OEM channels. Industrial automation integrators now require SIL 2/3 or PL d/e certification documentation as standard procurement pre-qualification, compelling suppliers to maintain dual development tracks for certified and uncertified product variants and extending time-to-revenue for new platform introductions.
Chinese robotics integrators are consolidating supplier relationships around domestic encoder platforms with localized certification support. Procurement teams in Shenzhen and Suzhou prioritize SAMR GB standard compliance and rapid technical response over legacy brand recognition, enabling domestic magnetic encoder specialists to capture share in collaborative robot and precision assembly line deployments previously dominated by imported platforms.
Absolute Encoders Market Segmentation
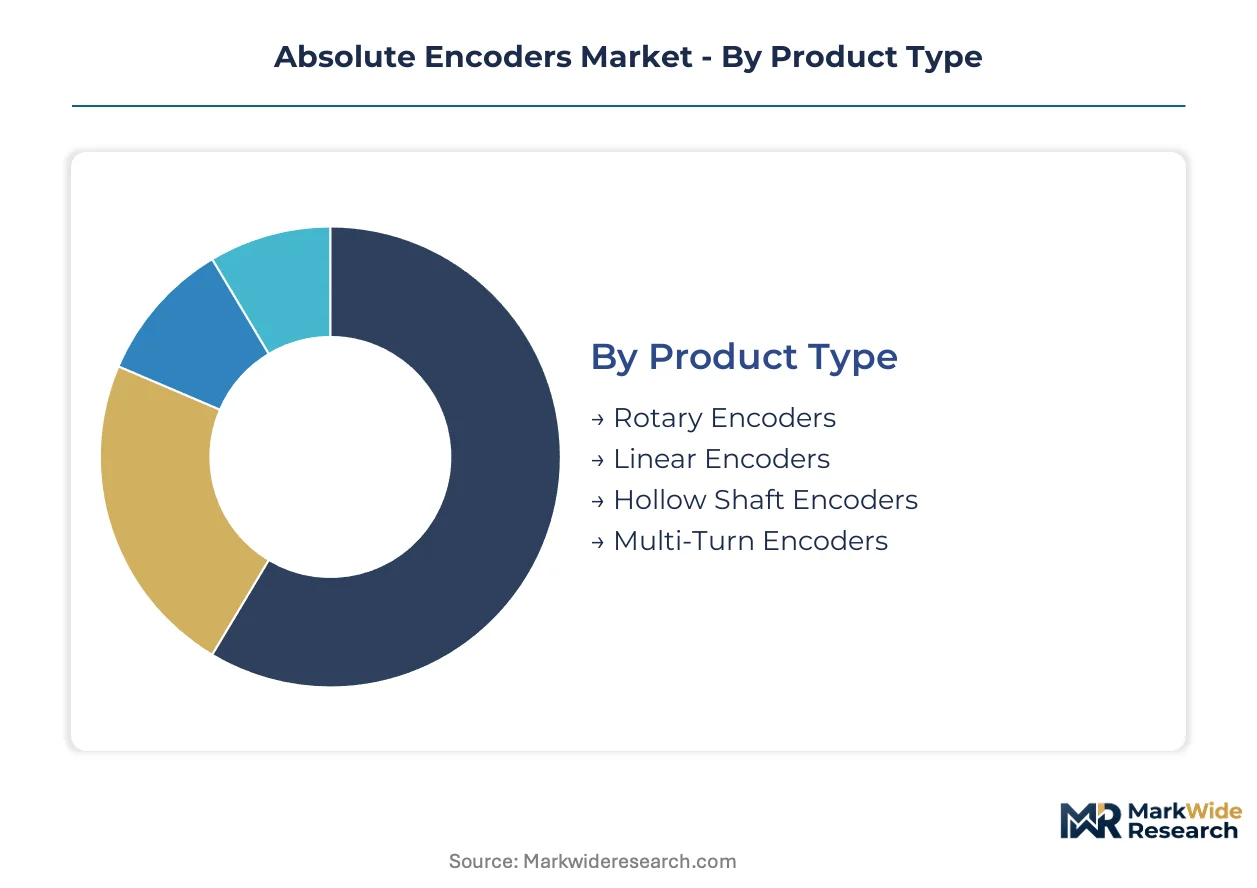
Absolute encoder procurement patterns diverge sharply across product architectures, sensing technologies, and end-use verticals. Understanding these segment boundaries clarifies where magnetic platforms displace optical alternatives and where functional safety certifications command premium positioning.
Product Type:
Supply concentration in precision graduation manufacturing favors established rotary and multi-turn specialists over emerging hollow shaft formats.
- Rotary Encoders:These shaft-mounted devices resolve angular position through optical gratings or magnetic pole arrays, delivering 16–25 bit resolution per revolution. Demand clusters in German and Japanese machine tool OEMs requiring deterministic feedback for five-axis machining centers and direct-drive rotary tables. CE marking and ISO 13849 functional safety mandates compel suppliers to maintain SIL-rated variants alongside standard offerings.
- Multi-Turn Encoders:Battery-free Wiegand-effect and geared counting architectures track position across thousands of revolutions without homing cycles. Wind turbine nacelle manufacturers and mobile machinery builders in China's eastern manufacturing corridor specify these for pitch control and boom positioning where battery maintenance proves impractical.
- Linear Encoders:Scale-based position sensing for gantry systems and precision stages, dominated by interferometric and optical grating technologies in semiconductor lithography.
- Hollow Shaft Encoders:Bearingless formats enabling direct motor integration, capturing value from servo motor-integrated motion control architectures in robotics and packaging automation.
Today's leader: Rotary Encoders. Tomorrow's challenger: Multi-Turn Encoders.
Technology:
Cost tier stratification separates contamination-resilient magnetic platforms from precision optical systems defending metrology strongholds.
- Optical:Interferometric and grating-based architectures achieve sub-micron resolution through precision glass or steel graduation substrates. Semiconductor lithography equipment manufacturers and coordinate measuring machine builders specify these where magnetic hysteresis effects exclude alternative technologies. Supply concentration in German and Japanese graduation specialists creates single-source vulnerability.
- Magnetic:Hall-effect and magnetoresistive sensing translates pole pitch variations into position data, achieving 23-bit resolution at significantly lower cost structures. Collaborative robot joint actuators and automotive steering column positioning absorb volume fastest as contamination resilience outweighs absolute precision requirements.
- Capacitive:Electrode array sensing for cleanroom and vacuum environments where particulate generation must be minimized.
- Inductive:Eddy-current and resolver-style architectures penetrate extreme temperature steel mill applications and aerospace actuator systems where optical contamination and magnetic demagnetization risks converge.
Optical platforms defend precision applications; magnetic technologies are expanding most quickly in cost-sensitive robotics and automotive auxiliary positioning.
Application:
Customer type concentration around robotics integrators and aerospace tier-ones reshapes technology qualification requirements.
- Industrial Automation:Factory floor motion control systems including CNC machine tools, packaging lines, and material handling equipment. German precision component manufacturers specify certified encoders with PL d/e ratings under EU Machinery Directive requirements.
- Robotics:Collaborative robot joint actuators and precision assembly systems demanding multi-turn absolute positioning. Procurement teams in Shanghai, Suzhou, and Shenzhen prioritize SAMR GB standard compliance and rapid technical response.
- Aerospace:Flight control surface actuators and landing gear positioning systems constrained by FAA airworthiness criteria and extreme environment specifications.
- Consumer Electronics:Camera stabilization gimbals and precision focus mechanisms where compact magnetic encoders displace potentiometer alternatives.
Industrial Automation anchors current volume; Robotics is gaining share fastest as collaborative platforms proliferate.
End User:
Procurement authority concentration in system integrators and automotive tier-ones compresses qualification timelines and forces dual-interface encoder designs.
- OEMs:Original equipment manufacturers in machine tools, robotics, and packaging machinery specifying encoders at the design stage. Stricter CE marking requirements compel SIL-rated functional safety documentation as standard procurement pre-qualification.
- System Integrators:Robotics and automation specialists in China's eastern manufacturing corridor consolidating supplier relationships around platforms with localized certification support and rapid technical response.
- Automotive Manufacturers:Tier-one suppliers integrating encoders into electric power steering, transmission actuators, and chassis positioning systems.
- Research Institutions:National laboratories and university precision engineering groups specifying interferometric encoders for metrology and scientific instrumentation.
System Integrators drive specification authority today; Automotive Manufacturers represent the steepest expansion trajectory as electric vehicle architectures multiply encoder count per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between CE marking requirements in Europe and SAMR GB standards in China creates cost-of-compliance arbitrage, pushing encoder suppliers toward localized production footprints that minimize certification duplication while capturing regional procurement authority.
Germany
Machine tool OEMs in Bavaria and Baden-Württemberg specify SIL-rated encoders under EU Machinery Directive mandates for five-axis machining centers. CE marking and ISO 13849 functional safety certifications condition supplier qualification for European industrial channels. Stuttgart and Munich manufacturing clusters drive demand for high-resolution optical platforms in precision component fabrication.
China
Robotics integrators in Shanghai, Suzhou, and Shenzhen require multi-turn absolute positioning for precision assembly lines, concentrating procurement of magnetic and optical encoder platforms. SAMR enforces GB standards for measurement accuracy and electromagnetic compatibility that condition market access for imported encoder platforms. The Yangtze River Delta manufacturing corridor anchors domestic encoder production expansion.
Japan
Industrial automation OEMs expand procurement of magnetic and optical encoder platforms for semiconductor equipment and precision machinery applications. METI industrial standards and JIS certification requirements shape supplier qualification protocols. Nagoya and Osaka industrial clusters sustain demand for high-end machine tool feedback systems.
United States
Aerospace tier-one suppliers and automotive manufacturers specify encoders for flight control actuators and electric power steering systems under FAA airworthiness criteria and NHTSA safety mandates. The Midwest manufacturing belt and Southeast automotive corridor concentrate demand for motor-integrated encoder designs. FDA device regulations constrain encoder architectures in medical imaging equipment.
South Korea
Display equipment manufacturers and robotics specialists in the Seoul Capital Area and Busan-Ulsan corridor specify high-resolution encoders for precision positioning systems. MFDS and KOSHA safety standards influence industrial automation procurement criteria. The Daejeon-Sejong technology cluster drives R&D partnerships for next-generation sensing architectures.
Absolute Encoders Market Competitive Environment
German producers anchor the premium optical tier; Japanese specialists hold precision graduation manufacturing capabilities; Chinese fabricators compete on magnetic platform cost structures. The vendor base concentrates around three strategic archetypes: vertically integrated graduation technology owners, magnetic sensing cost optimizers, and functional safety certification specialists. Dominant competitive moves include captive production of optical scale substrates and magnetic sensing elements, plus geographic expansion through localized certification support teams.
Within the graduation-technology tier, HEIDENHAIN and Renishaw occupy positions defined by in-house manufacturing of precision substrates and interferometric architectures. POSITAL FRABA sits within the magnetic encoder cost-optimization segment, competing on hollow shaft and kit encoder formats for motor-integrated designs. These three companies exemplify how technology specialization and geographic origin shape competitive positioning across premium and cost-sensitive market tiers.
| Leading Market Players |
|---|
| HEIDENHAIN |
| Renishaw |
| Baumer Group |
| SICK AG |
| Sensata Technologies |
| Rockwell Automation |
| Dynapar Corporation |
| TE Connectivity |
| POSITAL FRABA |
| Others |
Value Chain & Pricing Dynamics
Precision glass graduation specialists concentrated in Bavaria and Thuringia command wage premiums that widen pricing spreads between certified optical platforms and commodity magnetic alternatives. Labor-cost differentials between German substrate engineers and Chinese magnetic sensing fabricators translate into three-tier pricing stratification across premium, standard, and economy encoder levels.
Pricing Analysis
Distributor margins of 15-25% on optical encoders compress to 8-12% on magnetic platforms as direct-to-OEM procurement expands. Price differentiation hinges on SIL certification tier and graduation substrate origin, with CE-marked functional safety variants commanding 40-60% premiums over uncertified equivalents. Pricing pressure stems from rare earth magnet cost volatility and Chinese domestic supplier price aggression in robotics channels. System integrators in China's eastern manufacturing corridor exhibit highest price sensitivity, while semiconductor lithography equipment builders demonstrate lowest elasticity due to resolution requirements.
Supply Chain Analysis
Precision glass and steel graduation manufacturing rests on German and Japanese specialty producers, with HEIDENHAIN and Nikon maintaining captive substrate capabilities. Rare earth magnet processing draws from Chinese separation facilities, while Hall-effect sensor die fabrication sources from Taiwan and South Korean foundries. Single-source vulnerability in interferometric grating supply creates chokepoint exposure for high-end optical encoder producers. Distribution runs through industrial automation distributors in Europe, direct OEM relationships in automotive, and robotics integrator channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absolute encoders market functions as a stable compounder anchored by irreversible industrial automation penetration and functional safety regulatory expansion. Battery-free multi-turn architectures and motor-integrated kit formats sustain replacement cycles and content-per-machine growth.
For Market Incumbents: Acquire magnetic sensing element fabrication capabilities to insulate margin structures from rare earth price volatility. Deepen certification investment in SIL 3 and PL e variants to defend premium positioning against emerging Chinese competitors with SAMR GB compliance. Consolidate relationships with German machine tool OEMs through localized application engineering teams. For New Entrants and Emerging Players: Capture inductive encoder white space in steel mill and aerospace actuator applications where optical contamination and magnetic demagnetization risks converge. Target South Korean display equipment manufacturers and mining equipment builders in Australia with extreme-temperature-rated platforms. Lead with rapid technical response and customized hollow shaft geometries rather than price competition. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking functional safety certification capabilities and graduation technology IP. The market supports 5-10 year compound growth trajectories driven by robotics encoder content expansion and electric vehicle actuator proliferation. Monitor Chinese domestic encoder market share gains in collaborative robotics as the signal for optical-magnetic technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | SIL 2/3 and PL d/e ratings unlock European OEM procurement qualification under EU Machinery Directive mandates. |
| Magnetic Sensing Element Backward Integration | Captive rare earth magnet processing mitigates Chinese supply concentration and price volatility exposure. |
| Kit Encoder Motor Integration | Hollow shaft and bearingless formats capture value from servo motor-integrated motion control architectures in robotics. |
| Localized Certification Support Teams | SAMR GB standard compliance and rapid technical response win procurement decisions from Shenzhen and Suzhou integrators. |
| Battery-Free Multi-Turn Architecture Development | Wiegand-effect and geared counting designs displace battery-backed solutions in wind turbine pitch control applications. |
Study Parameters
Bottom-up robotics and machine tool OEM modeling reconciled against top-down graduation substrate and magnetic sensing element production tracking forms the analytical core. Primary interviews with encoder product managers, industrial automation procurement directors, robotics integrator technical leads, and functional safety certification engineers combined with secondary validation from SEC filings, customs trade data, METI industrial statistics, and SAMR GB standard registration databases. Triangulation between demand-side specification authority and supply-side capacity constraints ensures forecast robustness.
Historical trendline analysis of encoder shipments by technology type and certification tier informs projection frameworks across the modeling period. Segmentation dimensions include sensing technology, product architecture, functional safety rating, end-use vertical, and geographic production cluster. CAGRs derive from regression analysis of technology substitution rates, regulatory adoption curves, and content-per-machine expansion in electric vehicle and collaborative robot platforms. Forecast inputs incorporate rare earth magnet price indices, CE marking directive enforcement timelines, and Chinese domestic supplier capacity announcements.
Rare earth supply disruption, regulatory certification timeline extensions, and Chinese import substitution acceleration are the dominant revision risks. Forecasts embed assumptions regarding technology substitution elasticities and regional procurement authority shifts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market