
 Sweden Minimally Invasive Surgery Devices Market | 2026-2036
Sweden Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Minimally Invasive Surgery Devices Market Analytics
Hospital procurement in Sweden is fragmenting as county councils decentralize tendering authority to regional purchasing consortia. Medtronic PLC leverages its direct sales infrastructure to sustain presence across Sweden's twenty-one regions. Siemens Healthineers competes through imaging-integrated surgical platforms that anchor its minimally invasive portfolio in Nordic academic medical centers.
Minimally invasive surgery devices encompass precision instruments, camera systems, energy platforms, and robotic interfaces engineered for access through incisions under two centimeters, typically utilizing trocar cannulation and CO2 insufflation to create operative workspaces. These systems reduce tissue trauma, postoperative recovery intervals, and hospitalization duration compared with open surgical approaches. Laparoscopic instruments dominate current revenue streams due to established reimbursement pathways and broad procedure applicability across gynecology and urology, while robotic surgery systems capture accelerating capital investment as Swedish counties modernize operating suites. Endoscopic devices occupy a mature position in gastrointestinal diagnostics but face margin pressure from single-use alternatives.
Swedish market access requires compliance with EU MDR notified body certification, ISO 13485 quality management standards, and national vigilance reporting through the Swedish Medical Products Agency. The EU AI Act introduces additional conformity obligations for machine-learning-enabled surgical navigation and autonomous instrument control. Stakeholders must monitor county council technology assessment timelines and robotic surgery reimbursement deliberations to anticipate procurement windows.
Market Dynamics
Swedish county councils are consolidating procurement authority into regional purchasing consortia, fragmenting hospital tendering and forcing device manufacturers to navigate twenty-one distinct regional gatekeepers rather than centralized national contracts.
Growth Catalysts
- EU MDR Conformity Pressure:Tighter notified body certification requirements for implantable instruments are accelerating replacement cycles for legacy device inventories across Swedish hospitals.
- Robotic-Assisted Surgery:Capital budget expansions at Stockholm's university hospital cluster are pulling through integrated imaging and navigation platforms for complex oncologic procedures.
- Laparoscopic Procedure Volume:Established reimbursement pathways in gynecology and urology sustain instrument utilization rates above Nordic averages, anchoring recurring revenue for precision instrument suppliers.
Market Restraints
- High-Purity Polymer Supply:Single-use trocars and retrieval bags depend on medical-grade polymer feedstocks concentrated in German and Benelux chemical clusters, exposing Swedish distributors to input cost volatility.
- EU AI Act Compliance Burden:Machine-learning-enabled surgical navigation systems face additional conformity obligations and extended certification timelines, compressing product launch windows.
- Mature Endoscopic Segment:Reusable gastrointestinal endoscopes face margin erosion from single-use alternatives, constraining revenue growth in diagnostic device categories.
Strategic Opportunities
- Gothenburg and Malmö Hospital Networks:Underpenetrated regional clusters outside Stockholm present whitespace for robotic surgery platform vendors as county councils modernize secondary operating suites.
- Imaging-Integrated Platforms:Convergence of intraoperative imaging with laparoscopic instrumentation enables premium positioning for vendors capable of bundling visualization and energy delivery systems.
- Regional Purchasing Consortia:Direct contracting relationships with emerging procurement bodies bypass fragmented hospital-level tendering, reducing customer acquisition costs for established suppliers.
Industry Challenges
- Robotic Surgery Specialist Shortage:Swedish training programs produce insufficient console-certified surgeons to saturate installed base capacity, limiting utilization rates for capital-intensive systems.
- EU MDR Transition Timelines:Legacy device certificates expire under rolling MDR deadlines, forcing manufacturers to prioritize regulatory filings over new product development.
- Interoperability with Legacy Imaging Archives:New surgical platforms require integration with hospital PACS infrastructure, extending implementation cycles and inflating IT support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Minimally Invasive Surgery Devices Market |
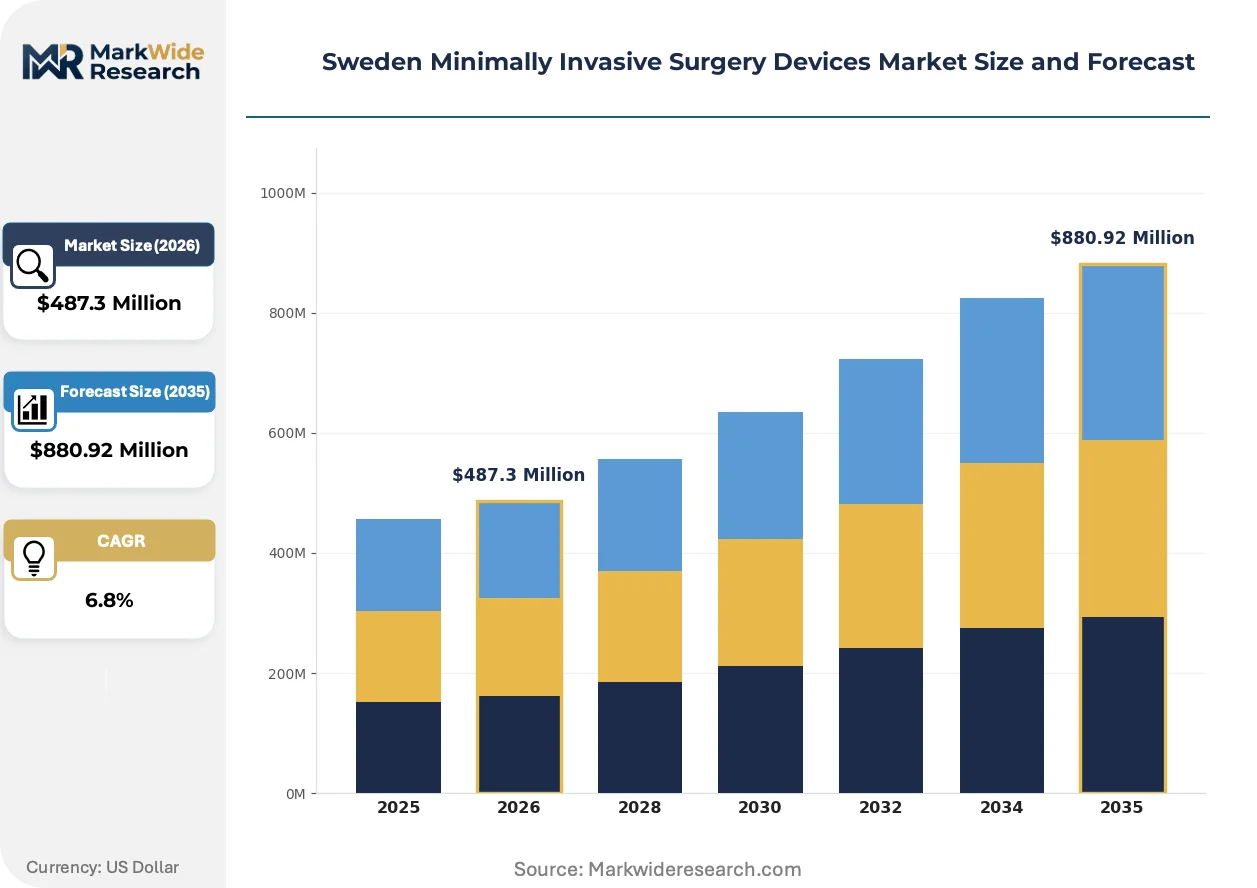
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopic Instruments, Robotic Surgery Systems, Endoscopic Devices, Suturing Devices Application Area: Gynecology, Cardiac Surgery, Orthopedics, Urology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: 3D Visualization, Energy Devices, Surgical Robotics, Imaging Technologies |
| Companies Covered | Medtronic PLC, Olympus Corporation, Intuitive Surgical Inc, Abbott Laboratories, GE Healthcare, Koninklijke Philips NV, Siemens Healthineers, Stryker Corporation, Johnson & Johnson Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Minimally Invasive Surgery Devices Market Evolving Landscape
Swedish surgical practice is migrating toward integrated platform ecosystems that bundle imaging, energy, and robotic control, compressing standalone instrument margins while rewarding full-stack vendors.
Single-use laparoscopic instrumentation is migrating from cost-sensitive ambulatory settings into mainstream hospital operating theaters as Swedish counties prioritize infection control and eliminate reprocessing infrastructure. Academic medical centers in Uppsala and Linköping are piloting disposable trocar and grasper programs, compressing procurement cycles from capital equipment budgets to consumable line items.
EU AI Act implementation is reshaping conformity assessment pathways for machine-learning-enabled surgical navigation systems, extending notified body review timelines and forcing developers to document algorithmic transparency. The Swedish Medical Products Agency is coordinating vigilance reporting for autonomous instrument control features, with academic hospital procurement committees now requiring AI Act compliance documentation before capital committee review.
County council technology assessment committees are unbundling after-sales service contracts from device procurement, forcing manufacturers to compete on discrete service modules. Stockholm's Karolinska University Hospital has separated warranty, training, and maintenance into distinct tender lots, enabling third-party service providers to capture maintenance revenue previously retained by original equipment manufacturers.
Sweden Minimally Invasive Surgery Devices Market Segmentation
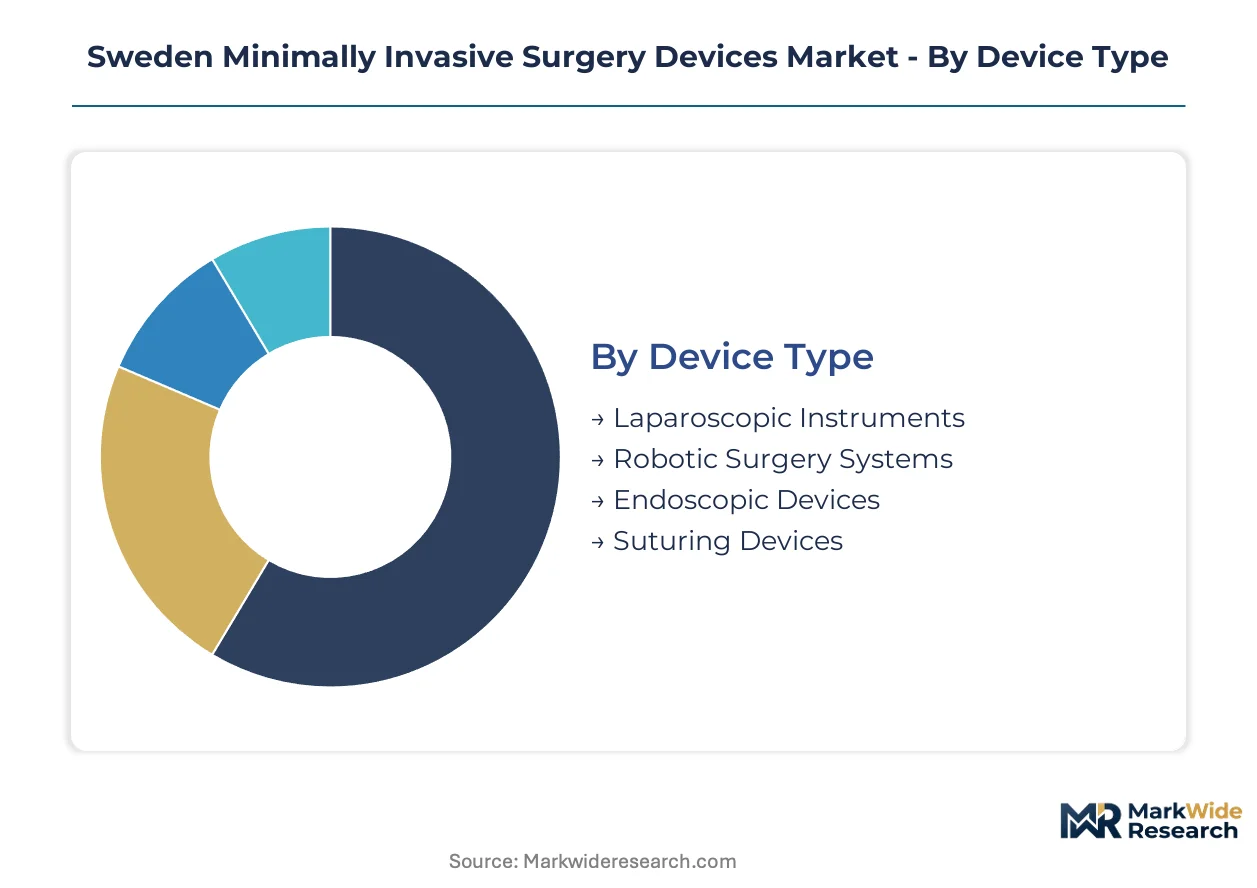
Device segmentation in Sweden reflects procurement fragmentation across county councils and the migration from capital equipment to consumable purchasing models. Understanding category boundaries clarifies where robotic platforms capture budget share versus where laparoscopic instruments sustain recurring revenue.
Device Type:
Cost tier stratification separates capital-intensive robotic installations from high-volume consumable instrument flows.
- Laparoscopic Instruments:Trocars, graspers, and scissors manufactured from medical-grade stainless steel and polymer composites dominate procedure volumes. Stockholm's university hospital cluster sustains instrument utilization above Nordic averages through established gynecology and urology reimbursement pathways.
- Robotic Surgery Systems:Console-based platforms integrating haptic feedback and 3D visualization anchor capital budgets at Karolinska University Hospital and Linköping University Hospital. County council modernization timelines for secondary operating suites in Gothenburg and Malmö are accelerating procurement cycles for these systems.
- Endoscopic Devices:Flexible gastrointestinal scopes face margin compression from single-use alternatives migrating into Swedish academic medical centers.
- Suturing Devices:Automated and manual closure systems support laparoscopic port site and internal anastomosis applications across county hospital networks.
Laparoscopic Instruments holds installed capacity. Robotic Surgery Systems is rotating up the share rankings.
Application Area:
Procedure volume concentrates in disciplines where Swedish reimbursement pathways are longest established and training infrastructure is deepest.
- Gynecology:Hysterectomy and myomectomy procedures drive trocar and energy device consumption through standardized clinical pathways. County councils prioritize laparoscopic routes for benign gynecologic conditions, compressing length-of-stay metrics.
- Urology:Prostatectomy and nephrectomy volumes sustain precision instrument demand at Sahlgrenska University Hospital and Skåne University Hospital. Robotic-assisted approaches capture increasing share as console-certified surgeon supply expands.
- Cardiac Surgery:Minimally invasive valve repair and coronary bypass procedures remain concentrated at Stockholm and Lund academic centers with hybrid operating suite infrastructure.
- Orthopedics:Arthroscopic and spine navigation applications represent emerging adoption corridors as imaging-integrated platforms penetrate musculoskeletal service lines.
Gynecology holds installed capacity. Urology is rotating up the share rankings.
End User:
Customer type determines procurement authority concentration and service contract unbundling intensity.
- Hospitals:County council-owned acute care facilities control the majority of robotic surgery capital budgets and laparoscopic instrument purchasing through regional procurement consortia. Karolinska University Hospital has separated warranty, training, and maintenance into distinct tender lots.
- Ambulatory Surgical Centers:Freestanding facilities prioritize single-use trocars and retrieval bags to eliminate reprocessing infrastructure and infection control liability.
- Specialty Clinics:Gynecology and urology-focused practices sustain endoscopic diagnostic device utilization outside hospital networks.
- Research Institutions:Academic medical centers in Uppsala and Linköping pilot disposable instrumentation programs and AI-enabled surgical navigation systems under EU AI Act compliance frameworks.
Hospitals hold installed capacity. Ambulatory Surgical Centers is rotating up the share rankings.
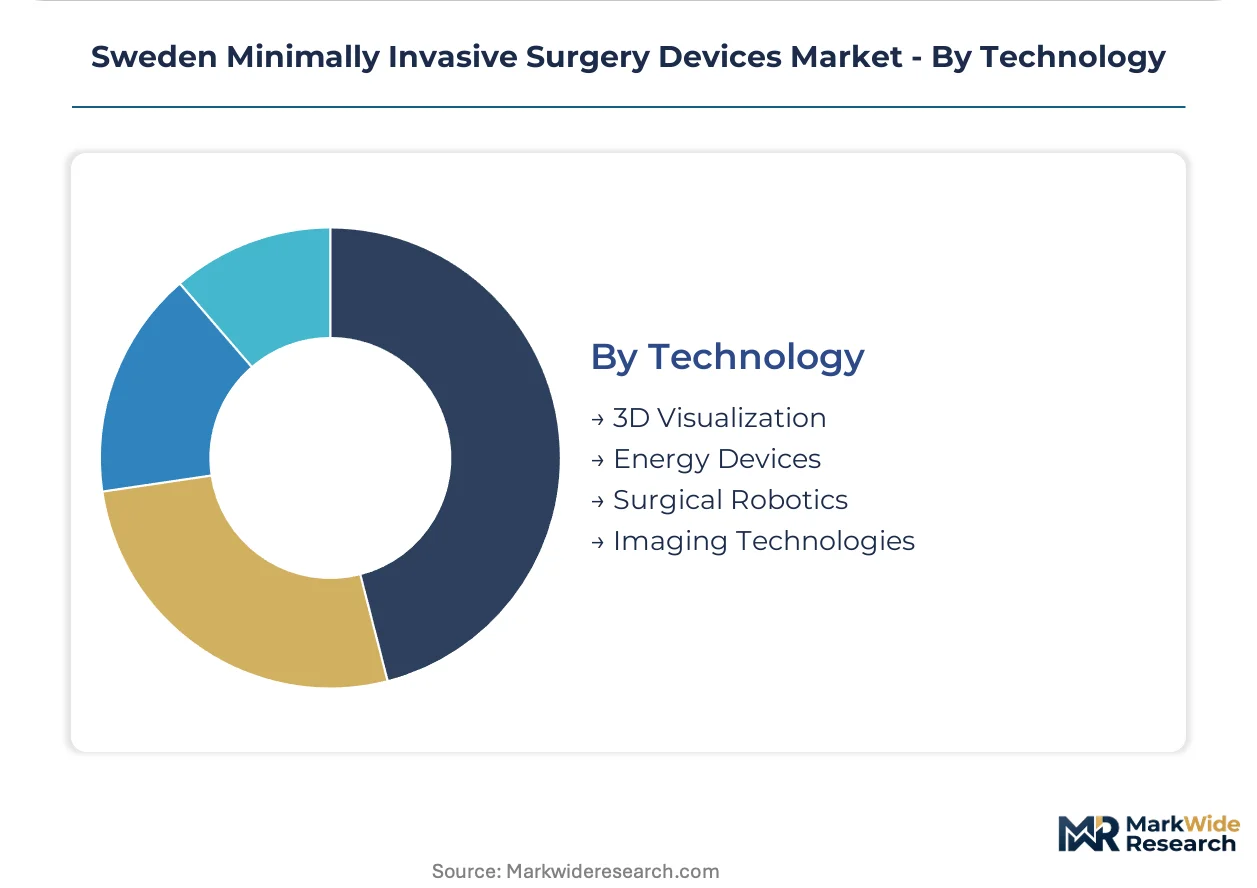
Technology:
Maturity gradients separate established visualization platforms from emerging autonomous control systems facing extended regulatory timelines.
- Energy Devices:Electrosurgical and ultrasonic cutting platforms integrate with laparoscopic instrument stacks to enable vessel sealing and tissue dissection. Swedish county procurement committees prioritize interoperability with legacy generator infrastructure.
- Surgical Robotics:Machine-learning-enabled instrument control features trigger EU AI Act conformity obligations and Swedish Medical Products Agency vigilance reporting requirements.
- 3D Visualization:High-definition camera systems and head-mounted displays enhance depth perception in complex oncologic procedures at Nordic academic centers.
- Imaging Technologies:Intraoperative CT and MRI integration with robotic platforms enables real-time navigation but requires PACS infrastructure compatibility extending implementation cycles.
Energy Devices holds installed capacity. Surgical Robotics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Stockholm's university hospital cluster, where capital budgets for surgical robotics have expanded fastest, while secondary regions face compressed procurement timelines and deferred modernization cycles.
Stockholm County
Karolinska University Hospital anchors national demand for robotic surgery platforms through its hybrid operating suite infrastructure and console-certified surgeon training programs. The Swedish Medical Products Agency coordinates EU MDR vigilance reporting for implantable instruments deployed across the county's seven acute care facilities. Solna's medical technology corridor hosts procurement committees that unbundle after-sales service contracts from device acquisition, forcing vendors to compete on discrete warranty, training, and maintenance modules.
Västra Götaland County
Sahlgrenska University Hospital sustains precision instrument utilization above national averages through established urology and gynecology reimbursement pathways. County council technology assessment timelines prioritize interoperability with legacy PACS infrastructure, extending implementation cycles for imaging-integrated platforms. Gothenburg's hospital network presents whitespace for robotic surgery vendors as regional purchasing consortia modernize secondary operating suites deferred during prior capital cycles.
Skåne County
Skåne University Hospital drives laparoscopic procedure volumes for prostatectomy and nephrectomy applications, pulling through energy device and trocar consumption. The EU AI Act introduces additional conformity obligations for machine-learning-enabled surgical navigation systems under review by regional procurement committees. Malmö's healthcare cluster is accelerating single-use instrumentation pilots as infection control priorities eliminate reprocessing infrastructure from ambulatory surgical centers.
Uppsala County
Uppsala University Hospital pilots disposable trocar and grasper programs, compressing procurement cycles from capital equipment budgets to consumable line items. Academic medical center procurement committees now require EU AI Act compliance documentation before capital committee review for autonomous instrument control features. The region's research institutions anchor early adoption corridors for imaging-integrated platforms bundling visualization and energy delivery systems.
Östergötland County
Linköping University Hospital supports robotic-assisted surgery adoption through county council modernization timelines for secondary operating suites. Regional purchasing consortia fragment tendering authority across twenty-one distinct gatekeepers, forcing device manufacturers to navigate decentralized procurement workflows. The county's technology assessment committees prioritize ISO 13485 quality management standards and EU MDR notified body certification in supplier qualification protocols.
Sweden Minimally Invasive Surgery Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain, supplying precision instruments and polymer composites to assembly operations. The vendor base stratifies across three tiers: full-stack surgical robotics vendors bundling imaging, energy, and navigation; laparoscopic instrument manufacturers with established direct sales infrastructure; and single-use consumable suppliers capturing infection-control-driven procurement shifts. Dominant competitive moves include strategic partnerships with regional purchasing consortia and portfolio diversification into imaging-integrated platforms.
Among diversified medical technology conglomerates, Medtronic PLC and Johnson & Johnson Inc occupy positions exemplifying full-stack platform strategies, while Siemens Healthineers represents the imaging-integrated archetype. Stryker Corporation and Abbott Laboratories sit within the precision instrument and energy device tier, supplying recurring consumable flows to county hospital networks. Intuitive Surgical Inc anchors the robotic surgery systems segment, with Olympus Corporation exemplifying the endoscopic device specialist position facing margin pressure from single-use alternatives.
| Leading Market Players |
|---|
| Medtronic PLC |
| Olympus Corporation |
| Intuitive Surgical Inc |
| Abbott Laboratories |
| GE Healthcare |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Stryker Corporation |
| Johnson & Johnson Inc |
| Others |
Value Network & Pricing Analysis
German and Benelux chemical clusters anchor medical-grade polymer feedstock capacity for single-use trocars and retrieval bags, concentrating input cost leverage among a narrow supplier base. Swedish county councils absorb this concentration through fragmented regional purchasing consortia that dilute collective bargaining power against upstream polymer producers.
Pricing Analysis
Configured-to-order pricing for robotic surgery platforms commands substantial premiums over standard laparoscopic instrument catalog pricing. Three-tier pricing structure across premium, standard, and economy levels separates imaging-integrated platforms from standalone energy devices and commodity trocars. Cost compression in consumable tiers is intensifying because county councils are unbundling after-sales service contracts from device acquisition. Ambulatory surgical centers exhibit highest price sensitivity due to elimination of reprocessing infrastructure budgets, while Stockholm's university hospital cluster demonstrates lowest sensitivity through expanded capital allocations for robotic modernization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard contracting features as Swedish distributors manage working capital against German polymer suppliers. Medical-grade stainless steel sourcing draws from Germany, Switzerland, and Japan, while polymer composites for single-use instrumentation hinge on Benelux chemical production. Single-source vulnerability concentrates in high-purity polymer grades certified for EU MDR implantable instrument applications. Distribution runs through regional purchasing consortia that fragment tendering authority across twenty-one county council gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sweden minimally invasive surgery devices market represents a high-growth disruption as EU AI Act implementation reshapes conformity assessment pathways for machine-learning-enabled surgical navigation systems. This regulatory inflection compresses product launch windows while rewarding early compliance investment.
For Market Incumbents: Harden defensive positions by deepening backward integration into polymer feedstock sourcing to insulate margins from German supplier pricing volatility. Prioritize ISO 13485 quality management certification maintenance ahead of rolling EU MDR deadline expirations to preserve market access. Console-certified surgeon training infrastructure represents a critical moat against utilization rate stagnation threatening capital-intensive robotic platform returns. For New Entrants and Emerging Players: Gothenburg and Malmö hospital networks present whitespace for robotic surgery platform vendors as county councils modernize secondary operating suites deferred during prior capital cycles. Secondary regional clusters outside Stockholm offer the most penetrable geographic entry points given compressed procurement timelines and limited incumbent installation density. Direct contracting relationships with emerging regional purchasing consortia bypass fragmented hospital-level tendering and reduce customer acquisition costs relative to national contract competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among single-use consumable suppliers capturing infection-control-driven procurement shifts from reusable endoscopic alternatives. Long-term viability across the analysis window favors vendors with demonstrated EU AI Act compliance documentation and established vigilance reporting relationships with the Swedish Medical Products Agency. The signal to monitor is county council technology assessment committee unbundling intensity for after-sales service contracts, which indicates margin compression pressure on original equipment manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerated notified body engagement preserves market access ahead of legacy certificate expirations. |
| Regional Purchasing Consortium Partnership | Direct contracting with emerging procurement bodies reduces customer acquisition costs across fragmented tendering. |
| Imaging-Integrated Platform Development | Convergence of intraoperative visualization with energy delivery enables premium positioning at Nordic academic centers. |
| Disposable Instrument Portfolio Expansion | Migration from capital equipment to consumable purchasing models captures infection-control procurement priorities. |
| AI Act Compliance Documentation | Algorithmic transparency requirements extend notified body timelines but secure capital committee review eligibility. |
Research Methodology
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and EU MDR regulatory affairs specialists anchored the qualitative base. Primary interviews across these stakeholder roles combined with secondary validation from hospital procurement databases, GPO contracts, Swedish Medical Products Agency vigilance reports, and EU notified body certification records. Bottom-up instrumentation volume modeling and top-down capital expenditure triangulation converged on segment-level estimates.
Scenario-bracketing framed demand projections across the analysis window through sensitivity testing of county council modernization timelines and robotic surgery reimbursement deliberations. Segmentation dimensions modeled include device type, application area, end user category, and technology maturity tier. CAGRs derived from procedure volume trajectories, replacement cycle assumptions for legacy device inventories, and capital budget elasticity to EU MDR conformity pressure. Industry-specific forecast inputs incorporated console-certified surgeon supply constraints and PACS infrastructure interoperability implementation cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by imaging-integrated platform vendors or single-use consumable specialists would shift outcomes. Macroeconomic deviation in polymer feedstock pricing, regulatory acceleration of EU AI Act enforcement, or technological breakthrough in autonomous instrument control would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Diabetes Devices Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
North America Medical Devices Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
Snoring Control Devices Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Suction Catheters Market