
 Chordal Suture Systems Market | 2026-2036
Chordal Suture Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chordal Suture Systems Market Outlook
Academic medical centers with advanced cardiac surgery programs is rotating toward robotic-assisted chordal repair protocols, displacing traditional open-stern approaches in high-volume institutions. Medtronic leverages its integrated surgical ecosystem to anchor premium positioning across hybrid operating rooms. Edwards Lifesciences differentiates through specialized mitral valve repair portfolios that extend into adjacent structural heart interventions. NeoChord competes on minimally invasive off-pump technology that reduces perfusion requirements in select patient populations.
Chordal suture systems comprise specialized implantable devices designed to reattach or replace ruptured chordae tendineae during mitral valve repair, typically constructed from expanded polytetrafluoroethylene or braided polyester with attached pledgets and needle configurations calibrated for subvalvular anatomy. These systems function to restore leaflet coaptation and eliminate regurgitation without complete valve replacement, requiring precise tensile strength matching native chordal load distribution. Absorbable sutures remain limited to temporary stabilization roles while non-absorbable configurations dominate durable repairs due to permanent tensile retention. Robotic-assisted surgery represents the fastest-expanding technology dimension as capital installation broadens beyond pioneer institutions, though traditional surgical techniques still occupy the majority of global procedure volume and associated margin pools.
FDA premarket approval pathways and EMA Medical Device Regulation conformity assessments impose substantial clinical evidence requirements on novel chordal repair platforms, filtering market access to well-capitalized developers with robust quality management systems. ISO 13485 certification and country-specific notified body engagements further structure competitive participation across regulated jurisdictions. Stakeholders must monitor reimbursement coding evolution for transcatheter and robotic mitral repair procedures as these classifications determine hospital capital allocation and surgeon adoption incentives.
Market Dynamics
Robotic-assisted surgical protocols are restructuring competitive positioning in chordal suture systems by compressing procedure times and altering capital equipment procurement patterns across cardiac surgery departments.
Growth Catalysts
- Aging demographics in established cardiac surgery markets:Patient cohorts in the United States, Germany, and Japan are expanding the addressable pool for mitral valve repair interventions.
- FDA premarket approval pathway maturation:Clear precedents for class III cardiovascular device submissions are reducing regulatory uncertainty for novel chordal repair platforms seeking market entry.
- Expanded polytetrafluoroethylene suture durability:Material science advances in tensile retention are extending repair longevity and reducing reintervention rates in high-volume surgical centers.
Market Restraints
- Capital intensity of robotic surgical systems:Da Vinci installation costs and maintenance contracts constrain adoption outside well-funded academic medical centers.
- Specialized surgeon training requirements:Steep learning curves for robotic chordal repair techniques limit addressable operator pools and procedure volume scalability.
- Reimbursement coding fragmentation:Inconsistent procedural classification across Medicare, commercial payers, and national health systems creates pricing opacity and hospital budgeting friction.
Strategic Opportunities
- Off-pump minimally invasive protocols:NeoChord's beating-heart approach demonstrates viability for reducing perfusion requirements in select anatomies, opening ambulatory surgical center channels.
- EMA Medical Device Regulation harmonization:Streamlined conformity assessment pathways for established device categories accelerate European commercialization timelines relative to pioneer submissions.
- Hybrid operating room infrastructure buildout:Hospital capital programs integrating imaging, robotics, and perfusion capabilities create bundled procurement opportunities for integrated system vendors.
Industry Challenges
- ISO 13485 quality management system maintenance:Sustained certification compliance demands dedicated regulatory affairs staffing that strains emerging manufacturer resources.
- Surgeon proctoring and credentialing logistics:Robotic platform adoption requires structured mentorship programs that conflict with productivity metrics in fee-for-service reimbursement environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chordal Suture Systems Market |
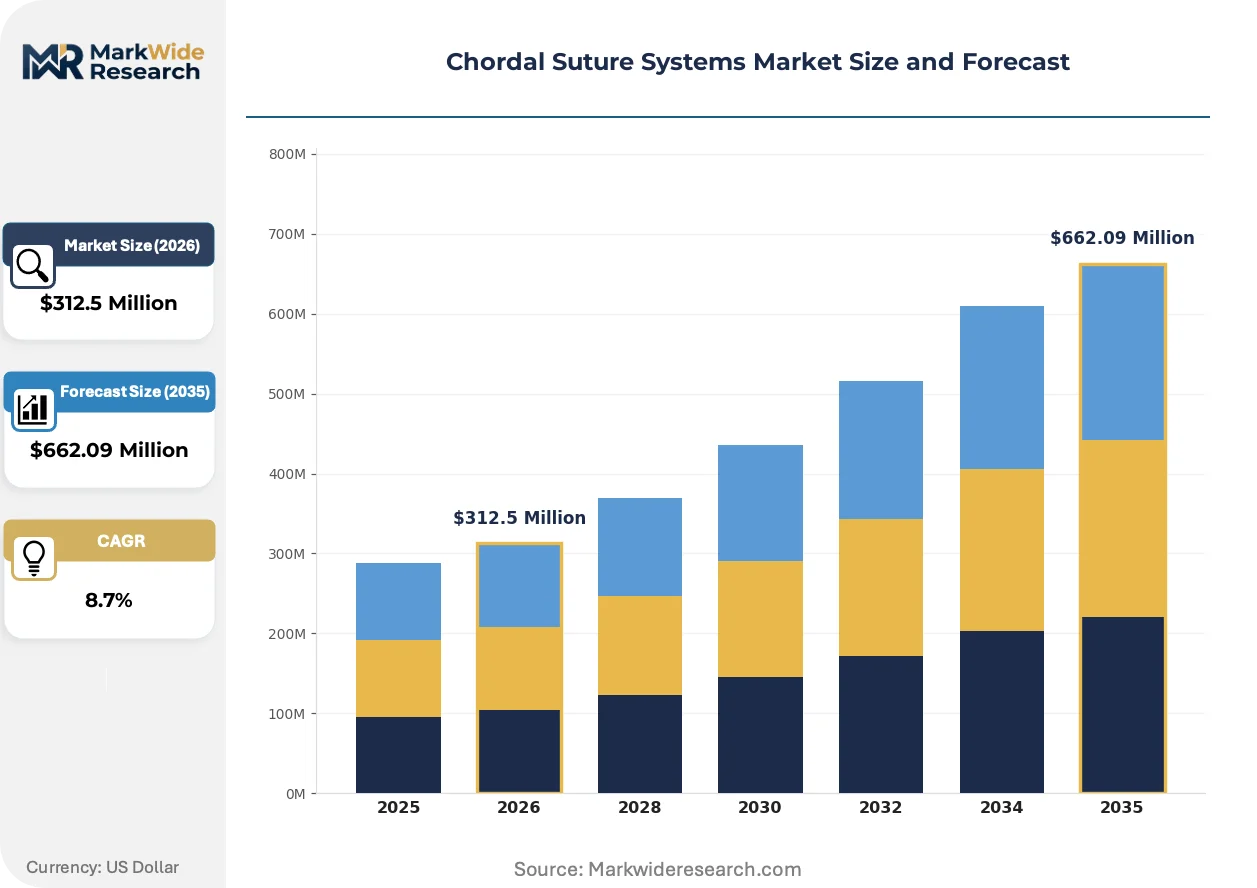
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Non-absorbable Sutures, Specialty Sutures, Monofilament Sutures End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Academic Institutions Application: Cardiac Surgery, Orthopedic Surgery, Neurosurgery, General Surgery Technology: Robotic-assisted Surgery, Traditional Surgical Techniques, Laparoscopic Surgery, Innovative Suturing Devices |
| Companies Covered | Medtronic, Johnson & Johnson, Edwards Lifesciences, NeoChord, Abbott Laboratories, Boston Scientific, CryoLife, Sofmedica, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chordal Suture Systems Market Strategic Shifts
Technology convergence between robotic surgical platforms and specialized mitral repair instruments is compressing the gap between open-stern and minimally invasive outcomes, reshaping capital allocation across cardiac surgery service lines.
Polytetrafluoroethylene chordal suture systems with integrated pledget configurations are supplanting traditional braided polyester in high-volume repair centers due to superior fatigue resistance and reduced tissue reaction profiles. Academic medical centers with established robotic programs are prioritizing these advanced material platforms in procurement specifications. The shift is compressing margin pools for conventional suture manufacturers while elevating technical barriers to competitive entry.
EMA Medical Device Regulation Article 54 conformity assessments are extending clinical evidence requirements for novel chordal repair devices beyond predecessor CE marking standards. Manufacturers must now submit systematic literature reviews and post-market surveillance plans that duplicate FDA premarket approval documentation burdens. European notified bodies are concentrating review capacity on cardiovascular class III submissions, creating backlog risks for smaller developers.
Hospital value analysis committees are consolidating vendor relationships for structural heart programs, bundling chordal suture procurement with robotic platform service contracts and imaging system maintenance agreements. This concentration is displacing independent suture suppliers from catheterization laboratory and hybrid operating room supply chains. The pattern is most visible in United States integrated delivery networks where standardized protocols reduce supply chain complexity.
Chordal Suture Systems Market Segmentation
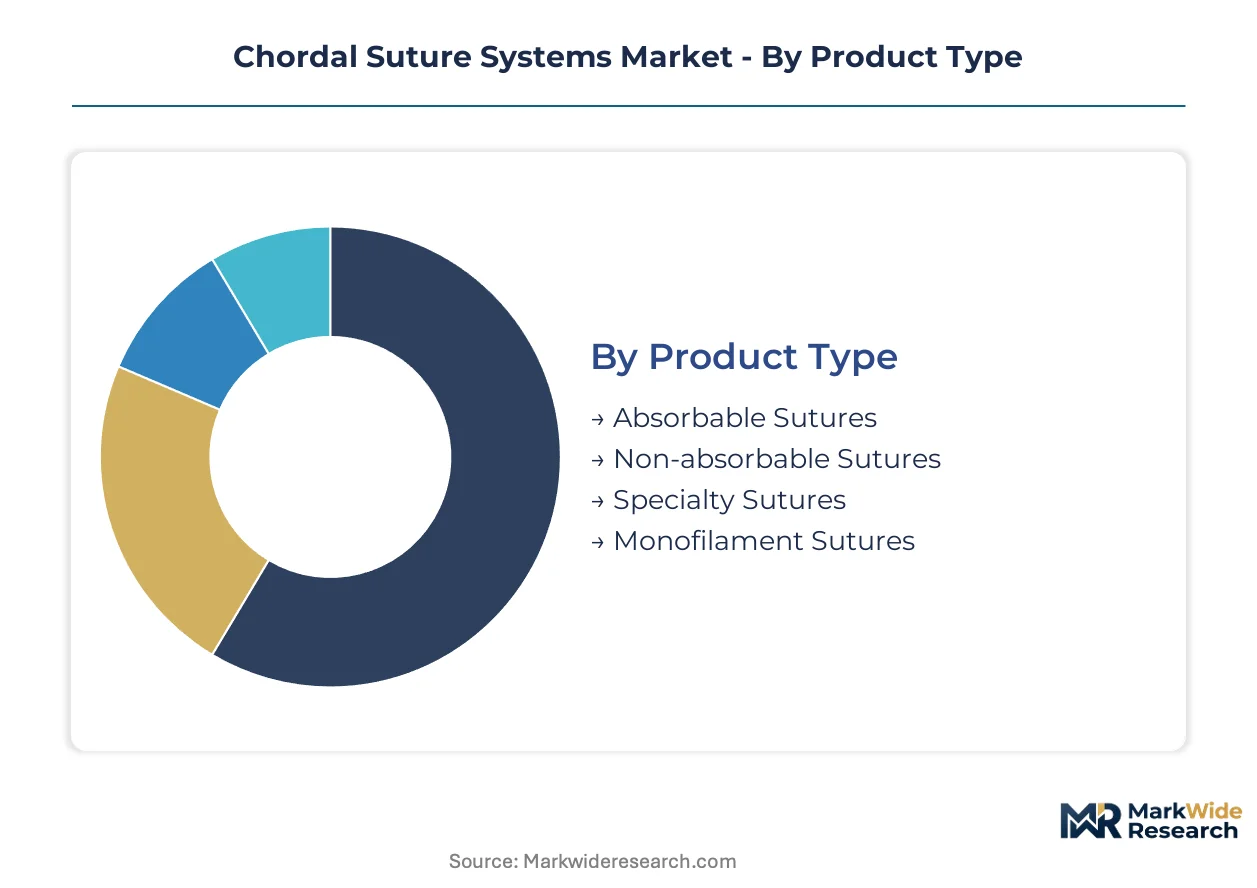
Chordal suture systems serve distinct clinical workflows across material compositions, surgical settings, and technological interfaces. Segmentation reveals where FDA and EMA regulatory pathways diverge most sharply, and which configurations command premium positioning in procurement negotiations.
Product Type:
FDA premarket approval pathways differentiate absorbable from non-absorbable configurations through distinct biocompatibility testing protocols, while EMA MDR Article 54 assessments impose heavier clinical evidence burdens on novel material platforms.
- Non-absorbable Sutures:Expanded polytetrafluoroethylene and braided polyester constructions provide permanent tensile retention for durable mitral valve repairs. Demand concentrates in United States tertiary cardiac centers where long-term hemodynamic outcomes drive procurement specifications.
- Absorbable Sutures:Polyglycolic acid and polylactic acid formulations designed for temporary chordal stabilization during healing phases. Adoption remains limited to bridging procedures in German university hospitals exploring hybrid repair protocols.
- Specialty Sutures:Pre-pledgeted configurations with integrated needle geometries calibrated for robotic instrument compatibility.
- Monofilament Sutures:Single-strand constructions reducing tissue drag in delicate subvalvular anatomies.
Non-absorbable sutures handle the majority of throughput; specialty sutures are climbing the fastest on share.
End User:
Capital equipment requirements stratify customer tiers, with robotic platform ownership determining addressable market boundaries more than surgical volume alone.
- Hospitals:Tertiary cardiac surgery departments in United States academic medical centers anchor procedure volume through hybrid operating room infrastructure. Da Vinci installation density and perfusion capability requirements filter participation to well-capitalized institutions with structured credentialing programs.
- Ambulatory Surgical Centers:Off-pump beating-heart protocols are opening limited ASC channels in select United States markets where NeoChord's minimally invasive approach reduces facility overhead requirements.
- Specialty Clinics:Concentrated structural heart practices in Germany and Japan handling high-complexity referrals.
- Academic Institutions:Training programs and proctoring hubs for robotic credentialing pathways.
Hospitals retain the dominant share of procurement volume; ambulatory surgical centers are gaining share fastest as reimbursement coding stabilizes for outpatient mitral repair.
Application:
Procedure reimbursement codes and clinical evidence requirements determine which surgical specialties sustain viable market segments for specialized suture platforms.
- Cardiac Surgery:Mitral valve repair procedures involving chordae tendineae reconstruction or replacement constitute the core addressable market. United States, German, and Japanese cardiac surgery departments generate concentrated demand through aging demographics and established valve repair infrastructure.
- Orthopedic Surgery:Ligament and tendon repair applications leverage similar tensile engineering but operate under distinct reimbursement classifications.
- Neurosurgery:Dural closure and microvascular applications requiring ultra-fine gauge configurations.
- General Surgery:Broad soft tissue approximation with limited premium suture penetration.
Cardiac surgery commands the revenue concentration; orthopedic surgery represents the steepest expansion trajectory as sports medicine protocols adopt specialized tensile materials.
Technology:
Surgeon training pathways and capital amortization schedules determine technology adoption velocity across institutional tiers.
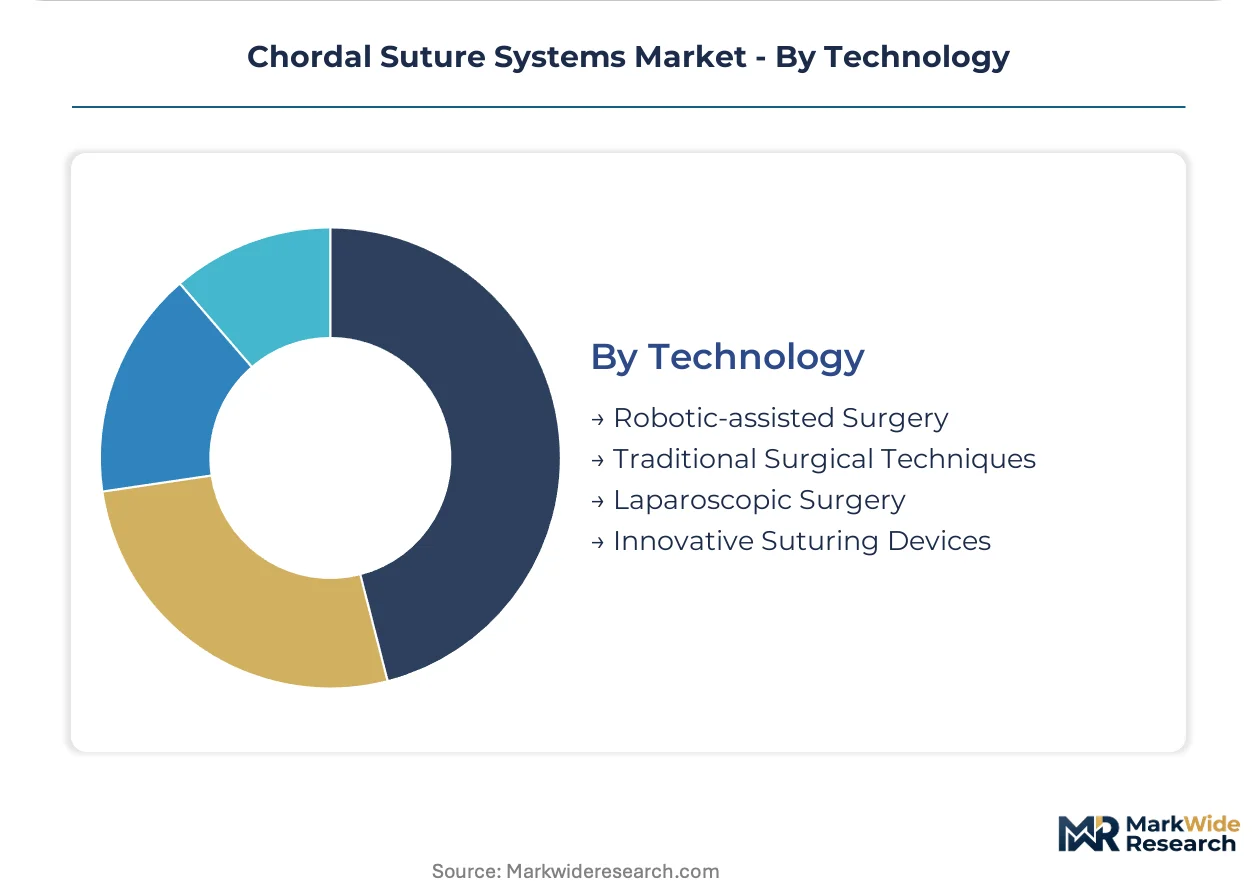
- Robotic-assisted Surgery:Da Vinci platform integration enables precise subvalvular navigation through tremor filtration and magnified visualization. United States academic medical centers with established cardiac robotics programs are prioritizing suture systems with instrument-compatible needle geometries.
- Traditional Surgical Techniques:Median sternotomy approaches with direct visualization retain majority procedure volume globally, particularly in Japanese and German centers where open-stern outcomes remain benchmark standards.
- Laparoscopic Surgery:Port-based minimally invasive approaches without robotic assistance occupy intermediate positioning.
- Innovative Suturing Devices:Automated knot-tying and tension-control mechanisms under early clinical evaluation.
Traditional surgical techniques sustain the largest installed base; robotic-assisted surgery is expanding most quickly on capital deployment schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic cardiac surgery corridor anchors United States infrastructure for mitral valve repair volume, with hybrid operating room buildout concentrated across tertiary referral networks.
United States
FDA premarket approval precedents for class III cardiovascular devices reduce regulatory friction for novel chordal repair platforms seeking 510(k) or PMA pathways. Medicare reimbursement coding for robotic mitral procedures determines hospital capital allocation across academic medical centers in the Midwest and Southeast.
Germany
EMA Medical Device Regulation Article 54 conformity assessments impose systematic literature review requirements that extend European commercialization timelines for emerging manufacturers. University hospitals in Bavaria and North Rhine-Westphalia concentrate robotic cardiac surgery training capacity and proctoring infrastructure.
Japan
PMDA marketing authorization pathways for implantable cardiovascular devices require domestic clinical trial data that filters market access to well-capitalized multinationals. Tokyo and Osaka metropolitan clusters host the majority of hybrid operating room installations serving aging patient cohorts with degenerative mitral valve disease.
Switzerland
Swissmedic device registration requirements align with MDR standards but maintain separate quality system inspections that add procedural steps for non-EU manufacturers. The Zurich-Geneva corridor concentrates specialized cardiac surgery practices serving cross-border referrals from neighboring EU markets.
United Kingdom
NICE technology appraisal processes for structural heart interventions create reimbursement uncertainty that delays robotic platform adoption outside London teaching hospitals. The Oxford-Cambridge-London triangle anchors translational research partnerships between device manufacturers and National Health Service trusts.
Chordal Suture Systems Market Competitive Environment
Concentration sits with diversified cardiovascular device conglomerates that leverage integrated surgical ecosystems across hybrid operating room infrastructure. Three strategic archetypes define participation: full-spectrum structural heart platforms with robotic compatibility, specialized mitral repair pure-plays emphasizing minimally invasive protocols, and broad surgical suture suppliers extending into cardiac applications. Dominant competitive moves include strategic partnerships with robotic platform vendors and portfolio diversification into adjacent transcatheter mitral interventions.
Among diversified cardiovascular conglomerates, Medtronic and Edwards Lifesciences occupy positions spanning integrated surgical ecosystems, while NeoChord represents the specialized mitral repair archetype with off-pump beating-heart positioning. These three entities exemplify the competitive tension between capital-intensive platform integration and targeted minimally invasive specialization that structures procurement negotiations across United States academic medical centers and European university hospitals.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Edwards Lifesciences |
| NeoChord |
| Abbott Laboratories |
| Boston Scientific |
| CryoLife |
| Sofmedica |
| Smith & Nephew |
| Others |
Value Chain & Pricing Dynamics
Expanded polytetrafluoroethylene substitution for braided polyester in high-volume repair centers simultaneously redraws raw material sourcing maps toward fluoropolymer production clusters and compresses margin pools for incumbent suture manufacturers unable to absorb the technical upgrade costs. This material transition concentrates procurement leverage with integrated cardiovascular device conglomerates that command hybrid operating room vendor consolidation.
Pricing Analysis
Volume-discount tiering structures separate premium robotic-compatible specialty sutures from standard non-absorbable configurations and economy-grade braided polyester alternatives. Price differentiation hinges on FDA PMA certification status and ISO 13485 quality system tier, with academic medical center GPOs extracting steepest concessions. Pricing pressure intensifies in the standard tier as hospital value analysis committees bundle suture procurement with capital equipment service contracts. Ambulatory surgical centers exhibit highest price sensitivity due to thin facility fee margins, while tertiary cardiac surgery departments prioritize performance metrics over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes into United States distribution hubs have elevated landed costs for polytetrafluoroethylene resin feedstocks. Supply concentrates in the United States, Germany, and Japan for finished device manufacturing, with China and India anchoring expanded polytetrafluoroethylene raw material production. Component dependencies include medical-grade fluoropolymers, precision needle alloys, and sterilization packaging materials. Single-source vulnerability in fluoropolymer resin supply creates exposure to export control restrictions. Distribution runs through integrated delivery network central warehouses and specialized cardiovascular device distributors serving catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chordal suture systems occupy an early-cycle expansion phase where robotic platform installation velocity outpaces procedural volume maturation, creating temporary supply-demand asymmetry favoring technology-integrated vendors.
For Market Incumbents: Consolidate hybrid operating room vendor relationships through bundled suture-robot-imaging procurement contracts that lock out independent suppliers. Deepen backward integration into expanded polytetrafluoroethylene resin processing to capture margin compression from material substitution trends. Fortify ISO 13485 quality systems ahead of EMA MDR Article 54 backlog risks that could filter smaller competitors from European notified body queues. For New Entrants and Emerging Players: Anchor in ambulatory surgical center channels where NeoChord's off-pump protocol has validated beating-heart mitral repair economics outside tertiary hospital infrastructure. Target German university hospitals exploring absorbable suture bridging protocols as the most penetrable entry point for novel material platforms. Pursue proctoring partnerships with established robotic cardiac surgery programs to accelerate surgeon credentialing adoption. For Investors and Strategic Acquirers: The market sits at a platform-integration phase that favors diversified cardiovascular conglomerates with capital equipment ecosystems over pure-play suture specialists. Long-term viability hinges on structural heart portfolio breadth spanning transcatheter and surgical repair modalities. Acquisition target archetypes include robotic instrument compatibility specialists and EMA MDR-ready quality system assets. Monitor FDA premarket approval pathway velocity for novel chordal repair platforms as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III cardiovascular device submissions reduce regulatory uncertainty for novel chordal repair platforms seeking United States market entry. |
| CE Marking Pathway | EMA MDR Article 54 conformity assessments extend clinical evidence requirements beyond predecessor standards for European commercialization. |
| Hospital System Partnership | Integrated delivery network vendor consolidation bundles suture procurement with robotic platform service contracts and imaging maintenance agreements. |
| Software Companion Development | Robotic platform integration demands suture systems with instrument-compatible needle geometries and automated tension-control mechanisms. |
| Reimbursement Strategy | Medicare coding evolution for robotic mitral procedures determines hospital capital allocation and surgeon adoption incentives across academic medical centers. |
Study Parameters
Operator-level perspectives from cardiac surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FDA PMA filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement coding updates. Bottom-up procedure volume estimates triangulated with top-down market sizing across material composition, technology interface, and end-user facility tiers.
Sensitivity analysis frameworks tested forecast robustness across the projection horizon by varying robotic platform installation schedules, surgeon training pipeline throughput, and reimbursement coding adoption curves. Segmentation dimensions modeled include product type, surgical setting, technology interface, and geographic regulatory cluster. CAGRs derived from procedure volume elasticity to demographic aging patterns and capital equipment replacement cycles. Industry-specific inputs incorporated hybrid operating room infrastructure buildout timelines and EMA notified body review capacity constraints.
Underlying assumptions cover stable FDA and EMA regulatory pathway precedents, with deviation risk concentrated in reimbursement coding fragmentation and robotic platform adoption velocity outside academic medical centers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vortex Mixer Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Pen Injectors Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Spinal Implant Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Global Bone Cement Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Medical Electrodes Market
Medical Devices
Hemoconcentrators Market