
 Eosinophilic Esophagitis Market | 2026-2036
Eosinophilic Esophagitis Market Size, Share, and Industry Trends Forecast 2026-2036
Eosinophilic Esophagitis Market Analysis
The divergence between biologic and corticosteroid treatment tiers is hardening as payers tighten step-therapy requirements. Regeneron Pharmaceuticals leverages its dupilumab franchise to anchor premium positioning in severe eosinophilic esophagitis. Bristol-Myers Squibb competes through immunotherapy pipeline breadth, while Takeda Pharmaceutical Company Limited dominates Asian regulatory submissions for biologic indications.
Eosinophilic esophagitis is a chronic immune-mediated inflammatory condition of the esophagus characterized by eosinophil-predominant infiltration exceeding 15 per high-power field, causing dysphagia, food impaction, and esophageal remodeling. Biologics targeting IL-4Rα and IL-13 pathways now lead clinical development, with corticosteroids occupying the maintenance tier where oral budesonide suspensions sustain generic competition. Injectable solutions command the fastest-growing delivery mode segment as subcutaneous biologics displace frequent endoscopy-dependent topical regimens.
FDA orphan drug designation and EMA priority medicines status shape investment timelines for developers, while the EU MDR tightens post-market surveillance for esophageal drug-device combinations. Japan's PMDA sakigake pathway accelerates first-in-class biologics toward national reimbursement. Stakeholders must monitor IL-5 and TSLP inhibitor readouts to anticipate which mechanism will displace existing standards of care.
Market Dynamics
Payer step-therapy mandates are compressing the window between diagnosis and biologic initiation, forcing manufacturers to demonstrate rapid histologic response or lose formulary placement to corticosteroid generics.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate pediatric trial enrollment timelines.
- Subcutaneous Delivery Platforms:Self-administered biologics reduce endoscopy burden and expand community gastroenterology prescribing.
- Germany's Dense Referral Networks:Specialist concentration enables rapid specialist-to-patient matching for complex esophageal cases.
Market Restraints
- Plasma-Derived Protein Costs:Monoclonal antibody manufacturing depends on volatile human plasma supply chains concentrated in US collection centers.
- EMA MDR Post-Market Surveillance:Drug-device combination filings face extended review timelines for esophageal delivery systems.
- Topical Corticosteroid Substitution:Generic oral budesonide suspensions maintain formulary preference in maintenance-phase patients.
Strategic Opportunities
- Japan's Sakigake Pathway:PMDA accelerated review compresses first-in-class biologic timelines toward national reimbursement.
- Pediatric Formulation Gaps:Weight-based dosing solutions for patients under 12 years remain underdeveloped relative to adult indications.
- Telehealth-Enabled Monitoring:Remote symptom tracking platforms integrate with specialty pharmacy distribution for rural patient access.
Industry Challenges
- Eosinophil Quantification Standardization:Variability in high-power field counting methods across pathology labs complicates trial endpoint validation.
- Biologic Cold Chain Infrastructure:Subcutaneous formulations require temperature-controlled logistics investment in community gastroenterology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eosinophilic Esophagitis Market |
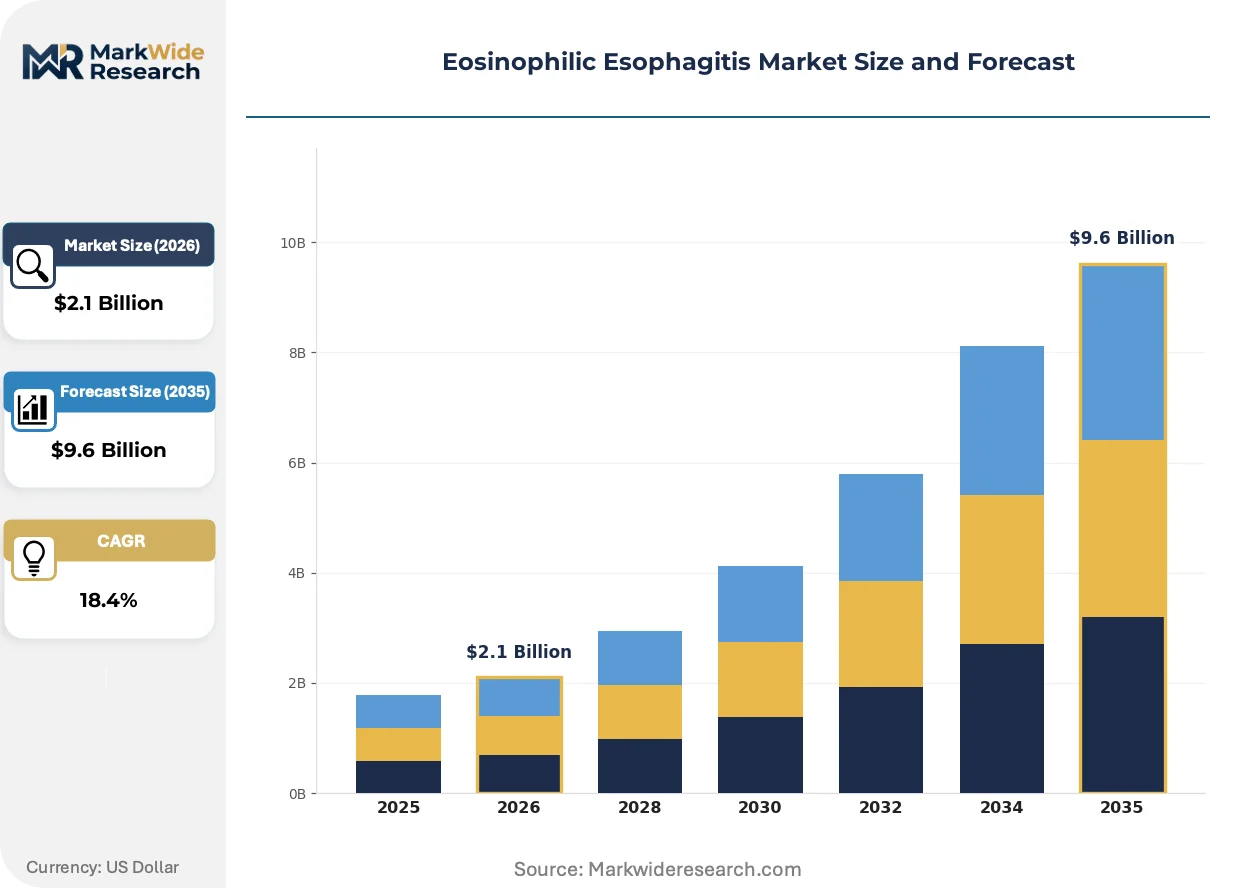
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Immunotherapy, Biologics, Corticosteroids Indication: Food Allergies, Environmental Allergies, Autoimmune Disorders, Inflammatory Conditions Delivery Mode: Oral Tablets, Injectable Solutions, Topical Treatments, Liquid Formulations End User: Hospitals, Specialty Clinics, Home Care Settings, Ambulatory Surgical Centers |
| Companies Covered | Bristol-Myers Squibb, Regeneron Pharmaceuticals, Ellodi Pharmaceuticals, Allakos, GlaxoSmithKline, AstraZeneca, Takeda Pharmaceutical Company Limited, EsoCap, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eosinophilic Esophagitis Market Emerging Trajectories
Clinical development is pivoting from histologic endpoints to patient-reported outcome measures, compressing the evidentiary burden required for regulatory submission and payer negotiation.
Digital biomarker platforms capturing real-time dysphagia severity through smartphone-based food diaries are converging with electronic health record integration to enable remote trial monitoring and post-market surveillance without repeated endoscopy.
EMA's priority medicines status designation is compressing assessment timelines for biologics demonstrating clinically meaningful histologic response, with Germany's Federal Joint Committee adjusting early benefit assessment protocols to accommodate accelerated approval data packages.
Specialty pharmacy distribution is displacing traditional hospital-based infusion centers for subcutaneous biologics, with United States payers mandating exclusive arrangements that concentrate patient volume through limited distribution networks and compress site-of-care cost differentials.
Eosinophilic Esophagitis Market Segmentation
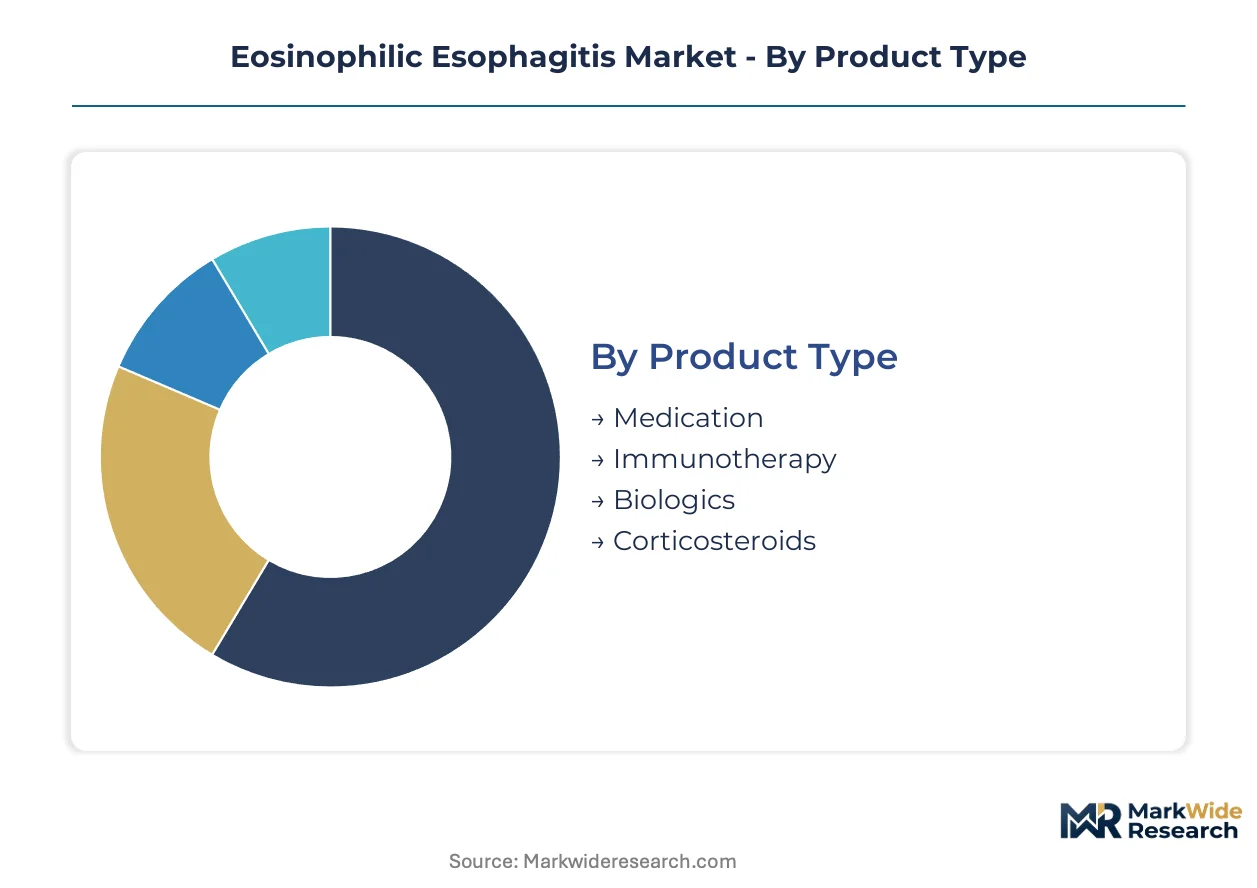
Segmentation in eosinophilic esophagitis reveals how regulatory pathways, reimbursement tiers, and site-of-care economics fragment commercial opportunity. Each dimension carries distinct FDA, EMA, or PMDA approval burdens that shape manufacturer investment priority.
Product Type:
FDA orphan drug designation and EMA accelerated assessment compress timelines for biologics while corticosteroids navigate abbreviated ANDA pathways.
- Biologics:Monoclonal antibodies targeting IL-4Rα and IL-13 require Phase III histologic response endpoints. United States specialty pharmacy networks concentrate demand for subcutaneous formulations as payers mandate step-therapy failure before authorization.
- Corticosteroids:Oral budesonide suspensions and orodispersible tablets dominate maintenance therapy. Generic substitution pressure from Teva and Mylan compresses pricing power in Germany's Federal Joint Committee reimbursement assessments.
- Medication:Proton pump inhibitors serve as first-line diagnostic exclusions rather than disease-modifying therapy.
- Immunotherapy:Allergen immunotherapy remains investigational for esophageal eosinophil reduction.
Leading the category by volume: Corticosteroids. Growing fastest: Biologics.
Indication:
Diagnostic coding specificity determines prior authorization success rates across commercial and government payers.
- Inflammatory Conditions:Eosinophilic esophagitis as primary indication commands highest biologic reimbursement rates. United States gastroenterology practices report prior authorization approval rates above 70% for patients with documented food impaction history.
- Food Allergies:Comorbid IgE-mediated allergy expands addressable population but complicates trial endpoint design. Japanese pediatric allergists increasingly co-manage cases with gastroenterology specialists under PMDA sakigake pathway incentives.
- Environmental Allergies:Seasonal aeroallergen correlation drives diagnostic testing volume in pollen-dense regions.
- Autoimmune Disorders:Overlap with connective tissue disease requires rheumatology-gastroenterology coordination.
Dominant by claim volume: Inflammatory Conditions. Steepest expansion trajectory: Food Allergies.
Delivery Mode:
Cold chain requirements and self-administration feasibility split manufacturing investment between hospital-centric and home-based models.
- Injectable Solutions:Subcutaneous biologics eliminate endoscopy dependency for administration. Community gastroenterology practices in the United States and Germany are acquiring refrigerated storage capacity to displace hospital infusion centers.
- Liquid Formulations:Oral viscous budesonide suspensions require compounding pharmacy partnerships. Japan's PMDA tightened stability testing requirements for multi-dose bottles.
- Oral Tablets:Fixed-dose corticosteroids serve pediatric patients unable to coordinate swallowing viscous suspensions.
- Topical Treatments:Orodispersible steroid films remain limited by esophageal coating uniformity challenges.
Highest patient preference scores: Injectable Solutions. Fastest site-of-care shift: Liquid Formulations.
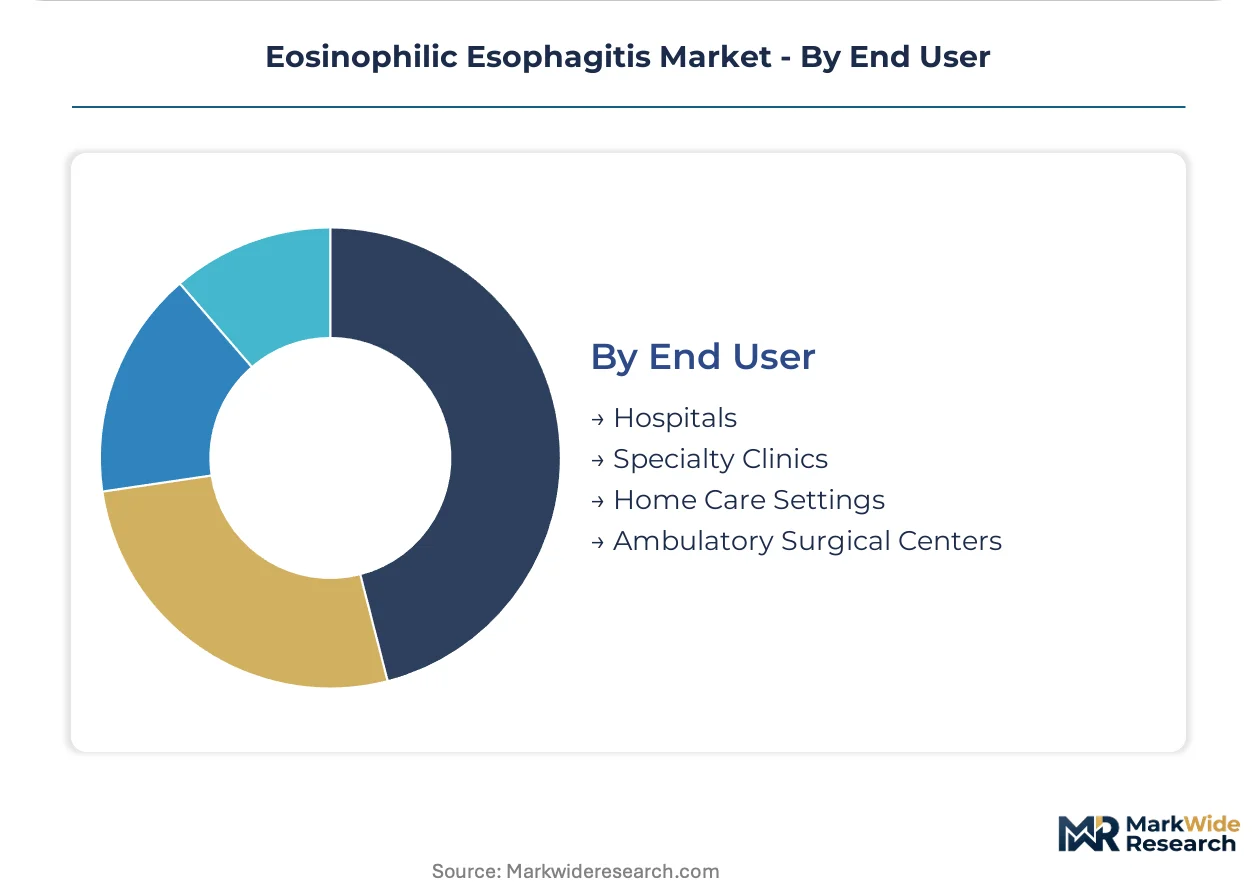
End User:
Reimbursement differentials between facility and non-facility fee schedules concentrate biologic margin capture.
- Specialty Clinics:Gastroenterology-focused practices capture biologic administration margin through buy-and-bill arrangements. United States Medicare site-of-care policies compress this advantage versus hospital outpatient departments.
- Home Care Settings:Self-administered subcutaneous biologics expand rural patient access. Germany's dense specialist referral networks enable remote monitoring integration with community pharmacy dispensing.
- Hospitals:Academic medical centers retain complex diagnostic endoscopy and dilatation procedures.
- Ambulatory Surgical Centers:Esophageal dilation and biopsy procedures concentrate in United States freestanding surgery centers with pathology partnerships.
Capturing greatest biologic volume: Specialty Clinics. Expanding access most rapidly: Home Care Settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philadelphia's corridor of specialty gastroenterology practices anchors biologic prescribing volume for eosinophilic esophagitis in North America, with referral density exceeding national averages by substantial margins.
United States
Specialty pharmacy networks concentrate subcutaneous biologic distribution through limited distribution arrangements mandated by commercial payers. FDA orphan drug tax credits accelerate pediatric trial enrollment at academic medical centers in Boston and San Francisco. The Research Triangle Park cluster in North Carolina hosts contract research organizations managing multi-site histologic endpoint trials for IL-4Rα inhibitors.
Germany
Federal Joint Committee early benefit assessments compress pricing negotiations for biologics demonstrating rapid esophageal eosinophil clearance. EMA accelerated assessment pathways enable priority medicines status for first-in-class mechanisms targeting IL-13 signaling. Munich's dense specialist referral networks enable rapid matching of complex esophageal cases with academic gastroenterology departments.
Japan
PMDA sakigake pathway accelerates first-in-class biologic review timelines toward national reimbursement decisions within twelve months. Tokyo's pediatric allergist-gastroenterologist co-management models expand addressable patient populations through diagnostic coding specificity. Osaka's community pharmacy cold chain infrastructure investments support subcutaneous biologic dispensing outside hospital settings.
United Kingdom
NICE technology appraisals mandate cost-effectiveness thresholds that favor corticosteroid generics in maintenance-phase treatment protocols. MHRA post-Brexit recognition procedures streamline EMA-approved biologic market entry for severe eosinophilic esophagitis indications. London's academic medical centers retain complex diagnostic endoscopy and esophageal dilation procedure volume.
Switzerland
Swissmedic accelerated licensing procedures align with EMA priority medicines timelines for biologics targeting Th2-mediated inflammation. Zurich's specialist gastroenterology practices participate in international histologic endpoint standardization initiatives. Basel's proximity to pharmaceutical headquarters enables rapid investigator-initiated study activation for novel mechanism trials.
Eosinophilic Esophagitis Market Vendor Landscape
Premium-margin players sit above commodity-margin players across mechanism novelty and histologic response speed, with biologic developers capturing value through orphan exclusivity while corticosteroid manufacturers compete on manufacturing scale. The vendor base stratifies into three archetypes: large-cap biopharmaceuticals with dupilumab-class franchises, mid-cap immunology specialists pursuing IL-5 and TSLP inhibition, and generic manufacturers of oral budesonide suspensions. Consolidation pressure intensifies as step-therapy requirements compress the window between diagnosis and biologic initiation, forcing portfolio diversification through immunology pipeline breadth or geographic expansion into Asian regulatory jurisdictions.
Within the large-cap biopharmaceutical tier, Regeneron Pharmaceuticals and Bristol-Myers Squibb exemplify divergent strategic positioning—one anchoring premium positioning through IL-4Rα pathway dominance, the other competing through immunotherapy pipeline breadth across multiple inflammatory indications. Takeda Pharmaceutical Company Limited occupies a distinct position as the dominant Asian regulatory submission leader for biologic indications in eosinophilic esophagitis.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Regeneron Pharmaceuticals |
| Ellodi Pharmaceuticals |
| Allakos |
| GlaxoSmithKline |
| AstraZeneca |
| Takeda Pharmaceutical Company Limited |
| EsoCap |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
The biologic-corticosteroid divergence manifests in both reimbursement tiers and manufacturing footprints. Payer step-therapy requirements compress margins for generic oral budesonide suspensions while IL-4Rα inhibitors command specialty pharmacy premiums through limited distribution networks. Cold chain infrastructure investments in community gastroenterology practices reshape site-of-care economics across the United States, Germany, and Japan.
Pricing Analysis
Histologic response rates anchor value-based pricing negotiations between manufacturers and United States payers. Three-tier pricing structure across premium biologics, standard corticosteroids, and economy generics reflects mechanism novelty and endpoint achievement. Price differentiation stems from FDA orphan exclusivity and EMA accelerated assessment status versus ANDA pathway commoditization. Cost compression in maintenance-phase corticosteroids intensifies as Teva and Mylan expand generic substitution. Pediatric allergists demonstrate highest price sensitivity due to weight-based dosing complexity, while severe disease gastroenterology specialists prioritize rapid esophageal eosinophil clearance over acquisition cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate temperature-controlled logistics for subcutaneous biologic formulations. Monoclonal antibody manufacturing draws from human plasma collection networks concentrated in US centers, with fill-finish operations anchored in Swiss and Irish facilities. Single-source vulnerability for plasma-derived proteins creates supply interruption exposure during collection shortfalls. Distribution runs through specialty pharmacy limited networks mandated by commercial payers, displacing hospital outpatient departments for subcutaneous administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Step-therapy compression is forcing portfolio consolidation among manufacturers lacking biologic pipelines or Asian regulatory capabilities. Weaker players dependent on corticosteroid generics face margin erosion without histologic response differentiation.
For Market Incumbents: Hedge against biosimilar entry by deepening IL-4Rα and IL-13 mechanism dominance through pediatric formulation investments. Acquire mid-cap immunology specialists with TSLP or IL-5 inhibitor pipelines before Japan's PMDA sakigake pathway accelerates competitor timelines. Prioritize backward integration into plasma collection infrastructure to secure monoclonal antibody feedstock against supply volatility. For New Entrants and Emerging Players: Telehealth-enabled patient monitoring platforms offer the lowest competitive density entry vector for rural United States markets underserved by specialist referral networks. Target weight-based dosing solutions for patients under 12 years where formulation gaps persist relative to adult indications. Deploy direct-to-patient specialty pharmacy partnerships to bypass entrenched hospital-based infusion center relationships. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap biologics developers holding PMDA sakigake pathway designations given Japan's twelve-month reimbursement acceleration catalyst. Long-term viability favors platforms with mechanism diversity across Th2 inflammatory pathways rather than single-target dependencies. Monitor IL-5 inhibitor Phase III readouts as inflection indicators for displacement risk to existing IL-4Rα standards of care.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | Weight-based dosing solutions for under-12 patients address regulatory gaps and expand addressable populations. |
| PMDA Sakigake Pathway Submission | Japan's accelerated review compresses first-in-class biologic timelines toward national reimbursement decisions. |
| Specialty Pharmacy Network Expansion | Limited distribution arrangements mandated by United States payers concentrate patient volume and capture site-of-care margin. |
| Cold Chain Infrastructure Investment | Community gastroenterology practices acquiring refrigerated storage displace hospital infusion centers for subcutaneous administration. |
| Digital Biomarker Platform Integration | Smartphone-based dysphagia tracking reduces endoscopy burden and enables remote trial monitoring without histologic endpoints. |
Methodological Framework
FDA filings, EMA assessment reports, and ClinicalTrials.gov formed the secondary backbone for mechanism and endpoint analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated pipeline timelines and reimbursement dynamics. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates across the analysis window.
Bottom-up volume builds started with diagnosed prevalence estimates by severity tier and treatment line progression rates. Top-down value estimates applied pricing benchmarks from specialty pharmacy claims data and Federal Joint Committee reimbursement assessments. Segmentation dimensions modeled include treatment line, delivery mode, patient age cohort, and regional regulatory cluster. CAGRs were derived from slope analysis of patent expiry curves and biologic launch trajectories.
Inputs from payer policy databases and pathology laboratory surveys were available through the study window; gaps in real-world adherence data introduce uncertainty bands around maintenance-phase patient persistence assumptions. Forecasts reflect documented assumptions regarding step-therapy failure rates and biologic penetration ceilings. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market