
 Bronchial Thermoplasty Market | 2026-2036
Bronchial Thermoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchial Thermoplasty Market Outlook
Procedure-specific software modules and remote patient monitoring subscriptions is broadening revenue capture beyond the initial device sale. Boston Scientific Corporation leverages its interventional pulmonology footprint to sustain recurring revenue from post-procedure follow-up platforms. Medtronic plc anchors its position through integrated catheter-electrode systems that dominate hospital procurement workflows. Olympus Corporation competes on optical navigation compatibility, differentiating its bronchoscopy platforms for thermoplasty integration.
Bronchial thermoplasty applies controlled radiofrequency energy to airway smooth muscle via a specialized catheter, typically delivering approximately 65°C for 10 seconds per treatment site to reduce bronchoconstriction in severe asthma. The procedure requires electromagnetic navigation or direct bronchoscopic guidance to ensure precise energy delivery without mucosal perforation. Devices command the largest value share within product type segmentation, while instruments face margin compression from commoditized catheter designs. Asthma management leads application demand due to established clinical trial evidence, though interventional pulmonology represents the fastest-expanding channel as procedural volumes shift from traditional pulmonology suites.
FDA 510(k) clearance and CE marking under the EU MDR govern market access, with both frameworks demanding extensive biocompatibility and electrical safety validation for radiofrequency ablation catheters. The EPA regulates sterilization byproducts from device reprocessing, while ISO 13485 certification remains mandatory for supplier qualification across OECD markets. Stakeholders must track evolving MDR clinical evidence requirements and reimbursement parity between inpatient and outpatient procedure codes.
Market Dynamics
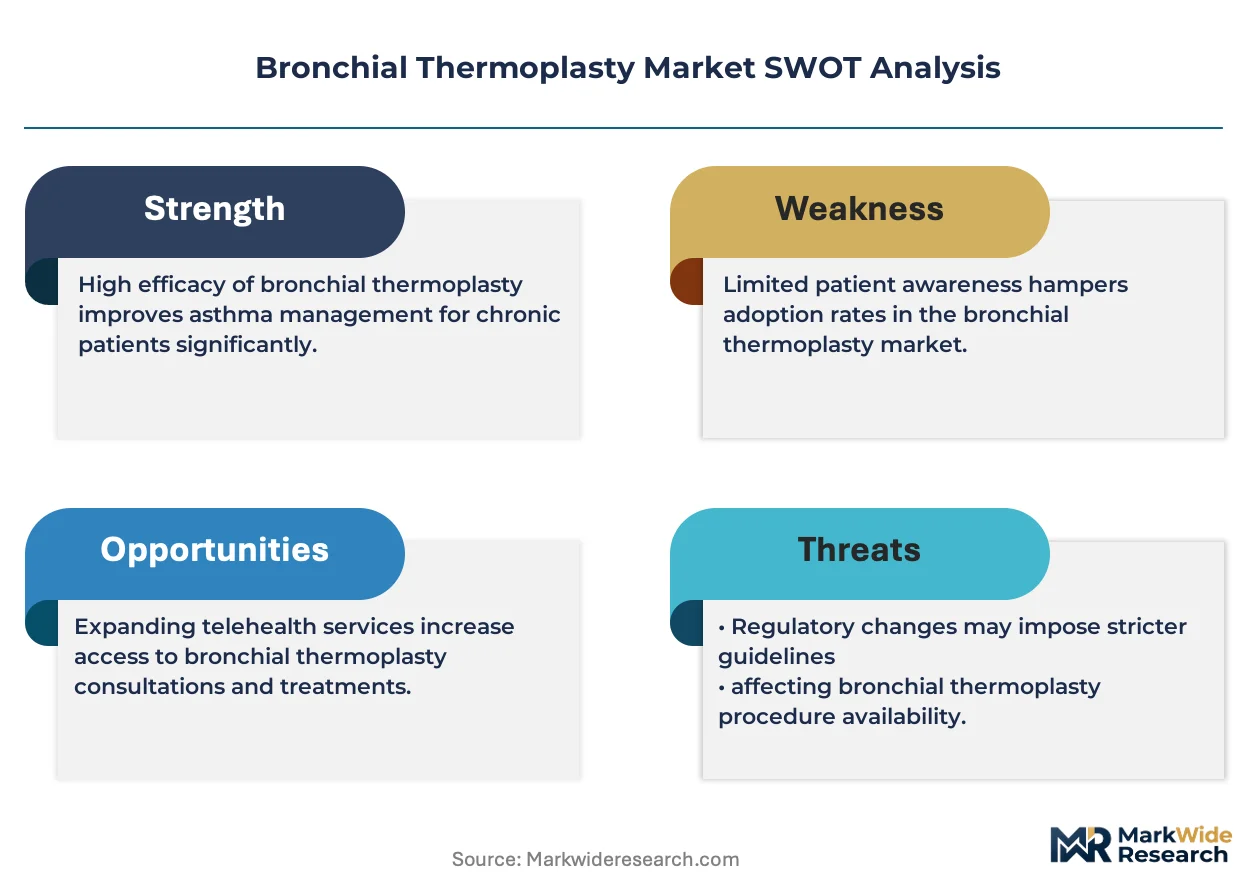
Radiofrequency catheter technology maturation is compressing procedure times and expanding treatable patient populations beyond refractory asthma into broader interventional pulmonology workflows. Device manufacturers now compete on integrated navigation compatibility rather than standalone energy delivery specifications.
Growth Catalysts
- EU MDR Clinical Evidence Pathways:Streamlined post-market surveillance requirements for Class III devices are accelerating CE marking timelines for next-generation catheter systems.
- Interventional Pulmonology Suites:Hospital investments in electromagnetic navigation infrastructure create captive demand for compatible thermoplasty platforms.
- Severe Asthma Biologic Non-Responders:Patient stratification protocols identify candidates who fail anti-IgE or anti-IL5 therapies, redirecting them toward bronchial thermoplasty intervention.
Market Restraints
- Single-Use Catheter Costs:Proprietary electrode arrays carry per-procedure material costs that strain outpatient reimbursement codes in German and Japanese hospital systems.
- Specialized Operator Dependency:Electromagnetic navigation proficiency requires fellowship-trained interventional pulmonologists, creating supply bottlenecks in secondary care centers.
- Biologic Therapy Substitution:Dupilumab and tezepelumab demonstrate comparable exacerbation reduction with lower procedural risk, capturing severe asthma cases previously routed to thermoplasty.
Strategic Opportunities
- Japan's Aging Asthma Population:METI reimbursement incentives for minimally invasive procedures in patients over 65 create procedural volume expansion potential.
- Remote Patient Monitoring Integration:Post-procedure respiratory metrics subscription models capture recurring revenue from hospital accounts.
- Chronic Obstructive Pulmonary Disease:Bronchoscopic lung volume reduction protocols are adapting thermoplasty energy delivery parameters for emphysema phenotype targeting.
Industry Challenges
- ISO 13485 Supplier Qualification:Electrode material traceability requirements extend certification timelines for contract manufacturers.
- Legacy Payer Code Fragmentation:Inpatient DRG and outpatient CPT reimbursement disparities complicate hospital financial modeling for procedure site selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchial Thermoplasty Market |
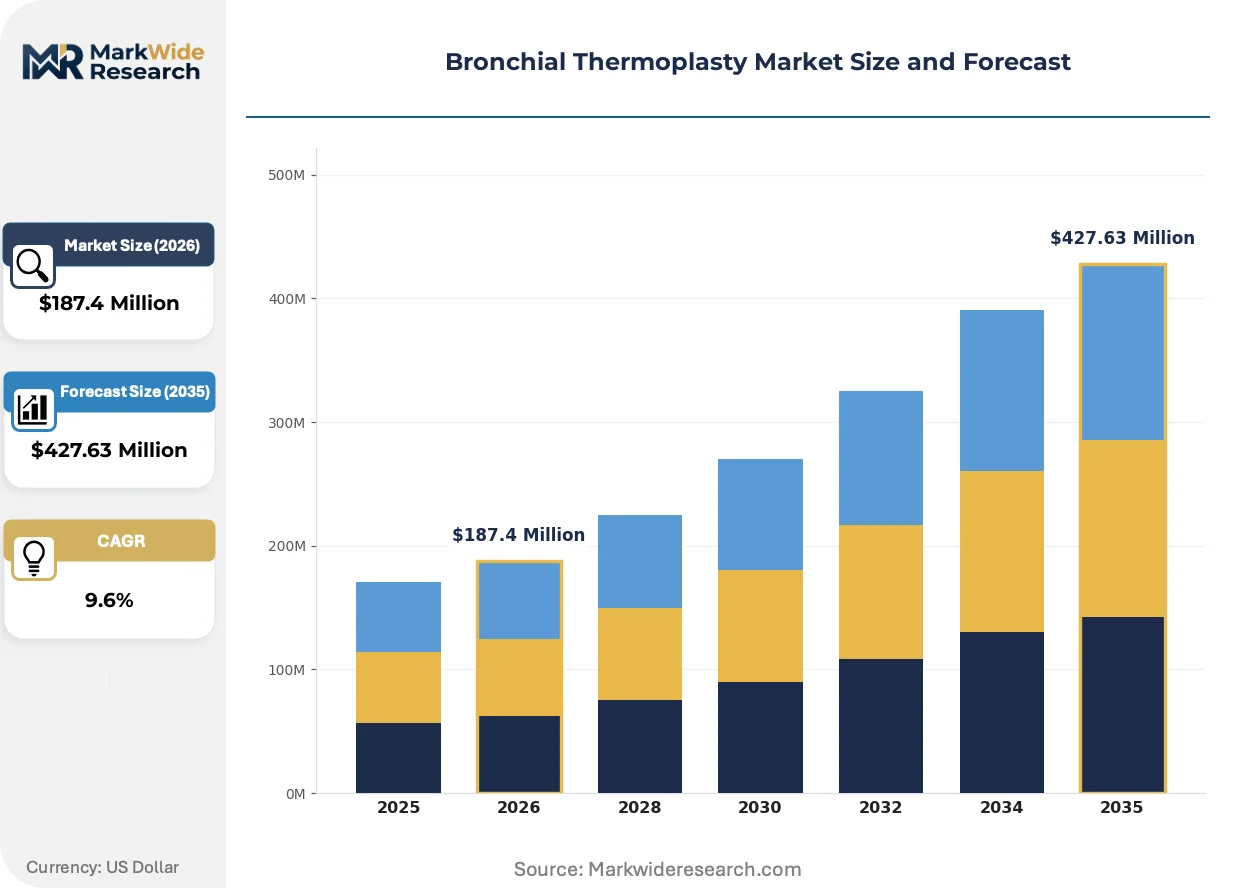
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Instruments, Equipment, Accessories Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Interventional Pulmonology, Respiratory Therapy End User: Hospitals, Outpatient Clinics, Specialized Medical Centers, Research Institutions Delivery Mode: Invasive Procedure, Outpatient Procedure, Local Anesthesia, General Anesthesia |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Olympus Corporation, Johnson & Johnson (Ethicon), Smith & Nephew plc, Teleflex Incorporated, Cook Medical LLC, Stryker Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchial Thermoplasty Market Strategic Shifts
Procedure economics and patient selection algorithms are reshaping competitive differentiation away from hardware specifications toward integrated care pathway ownership. Technology vendors now bundle navigation software with energy delivery systems to capture full procedural value.
Radiofrequency electrode array miniaturization is consolidating treatment precision standards across the competitive landscape. Interventional pulmonology departments in tertiary hospitals adopt 2.0mm diameter catheters for distal airway access. This catheter downsizing is consolidating market share among manufacturers with proprietary navigation-integrated platforms.
EU MDR post-market clinical follow-up requirements are extending evidence generation obligations for legacy thermoplasty devices. Manufacturers must submit periodic safety reports to notified bodies across all CE-marked product iterations. German hospital procurement teams now prioritize suppliers with established PMCF data repositories.
Hospital value-analysis committees increasingly bundle device selection with multi-year service agreements. Traditional capital equipment purchasing gives way to per-procedure leasing models with embedded maintenance and software updates. This contractual evolution is most visible in United States integrated delivery networks consolidating interventional pulmonology service lines.
Bronchial Thermoplasty Market Segmentation
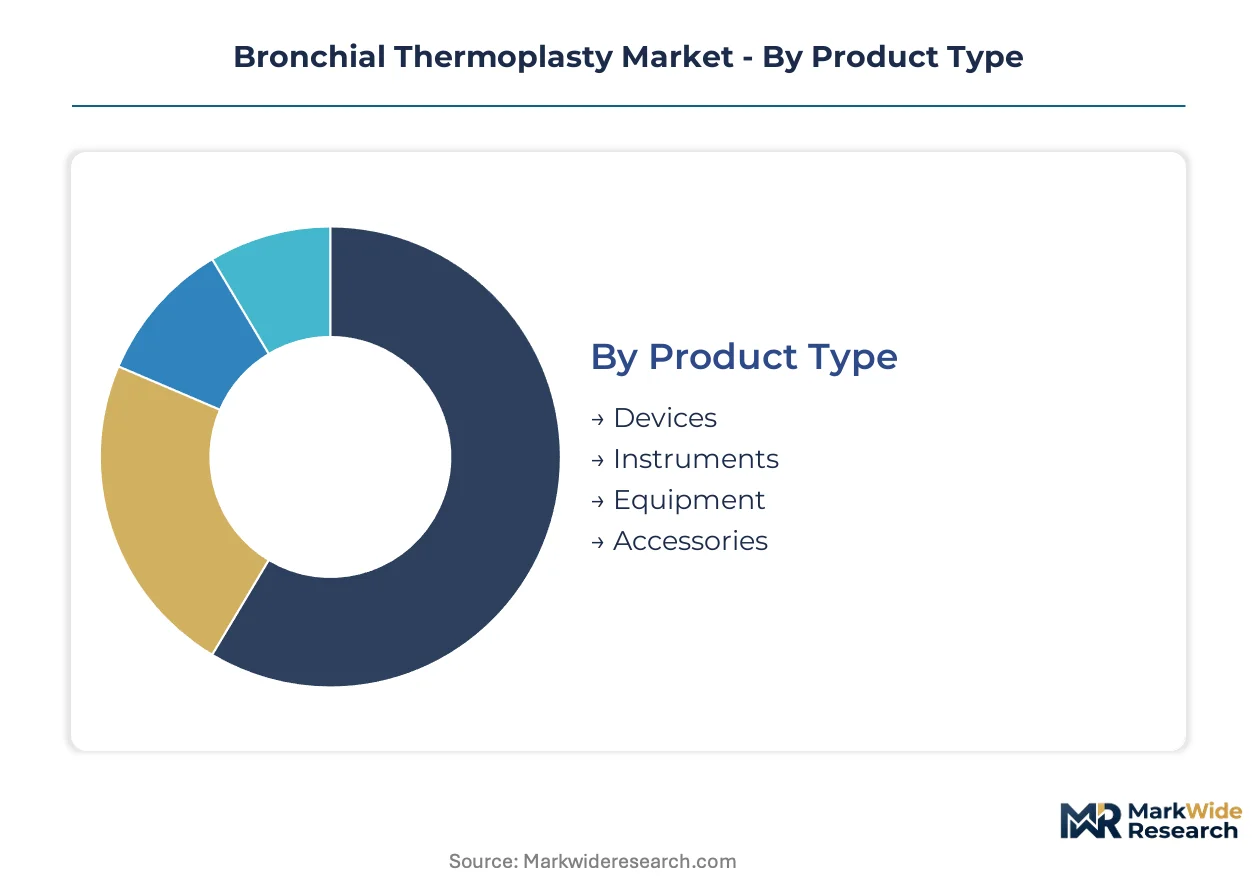
Bronchial thermoplasty vendors structure their portfolios around four intersecting dimensions that determine procurement workflows and reimbursement pathways. Product type and application segmentation drive capital allocation decisions, while end-user and delivery mode classifications shape regional commercialization strategies.
Product Type:
Standalone energy delivery systems dominate hospital procurement, whereas integrated navigation-compatible platforms command premium positioning in tertiary interventional pulmonology suites.
- Devices:Radiofrequency generators and controller units form the core capital equipment layer, with procurement concentrated in United States academic medical centers pursuing electromagnetic navigation integration. FDA 510(k) clearance timelines and service contract bundling determine vendor selection.
- Instruments:Specialized catheter-electrode arrays deliver controlled thermal energy to airway smooth muscle, with German hospital systems prioritizing single-use sterile designs to satisfy MDR traceability requirements. Per-procedure material costs strain outpatient reimbursement codes.
- Equipment:Electromagnetic navigation workstations and bronchoscopy towers provide procedural guidance infrastructure.
- Accessories:Disposable sheaths, connection cables, and calibration tools complete the consumable ecosystem.
Volume placements concentrate in Devices; the faster expansion belongs to Instruments.
Application:
Established clinical evidence separates reimbursable indications from experimental extensions, with regulatory pathway maturity determining commercial priority.
- Asthma Management:Severe refractory asthma represents the sole FDA-cleared indication, with randomized trial data supporting bronchoconstriction reduction through airway smooth muscle ablation. United States pulmonology practices drive procedural volume through prior authorization pathways for biologic non-responders.
- Interventional Pulmonology:Electromagnetic navigation integration is expanding treatable anatomy into distal airways, with Japanese tertiary centers adopting miniaturized catheter platforms for elderly patient populations. METI reimbursement incentives accelerate adoption.
- Chronic Obstructive Pulmonary Disease:Bronchoscopic lung volume reduction protocols are adapting thermoplasty parameters for emphysema phenotypes.
- Respiratory Therapy:Post-procedure monitoring and rehabilitation protocols support long-term outcomes validation.
Revenue concentration sits with Asthma Management; steepest expansion trajectory emerges in Interventional Pulmonology.
End User:
Capital intensity and reimbursement structure create distinct procurement behaviors across care settings.
- Hospitals:Integrated delivery networks in the United States consolidate interventional pulmonology service lines through multi-year equipment leasing with embedded maintenance. Value-analysis committees bundle device selection with navigation software subscriptions.
- Specialized Medical Centers:Dedicated respiratory institutes in Germany pursue CE-marked platforms with established EU MDR post-market clinical follow-up data repositories.
- Outpatient Clinics:Ambulatory surgical centers face reimbursement parity challenges between inpatient DRG and outpatient CPT codes.
- Research Institutions:Academic medical centers generate evidence for expanded indications and next-generation catheter designs.
Procurement volume clusters in Hospitals; Specialized Medical Centers gain share fastest.
Delivery Mode:
Anesthesia requirements and procedure site selection determine patient throughput economics.
- Invasive Procedure:Bronchoscopic delivery under direct visualization or electromagnetic navigation requires general anesthesia and operating room scheduling, with Japanese hospitals optimizing throughput for aging severe asthma cohorts.
- Outpatient Procedure:Same-day discharge protocols in United States ambulatory settings demand streamlined sedation workflows and rapid recovery protocols.
- Local Anesthesia:Conscious sedation approaches reduce facility costs but require extended operator presence.
- General Anesthesia:Deep sedation enables complete airway examination and multi-lobe treatment in single sessions.
Procedure scheduling favors Invasive Procedure; Outpatient Procedure climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in the United States, Germany, and Japan, while procedural adoption spreads through tertiary hospital networks in each geography. Consumption patterns diverge sharply between Medicare-reimbursed outpatient centers in the US and inpatient-focused systems in Germany and Japan.
United States
Academic medical centers in Boston and Cleveland drive electromagnetic navigation adoption for severe asthma cohorts. FDA 510(k) clearance pathways govern commercial entry, with post-market surveillance requirements extending evidence obligations. Integrated delivery networks in Texas and California consolidate procurement through multi-year equipment leasing contracts.
Germany
Specialized respiratory institutes in Munich and Heidelberg prioritize CE-marked platforms with established EU MDR post-market clinical follow-up data. The BfArM oversees device registration, while hospital procurement teams in North Rhine-Westphalia demand single-use sterile designs with full material traceability.
Japan
Tertiary centers in Tokyo and Osaka adopt miniaturized catheter platforms for elderly severe asthma patients over 65. METI reimbursement incentives accelerate procedural volume expansion. PMDA regulatory reviews emphasize biocompatibility validation for radiofrequency electrode arrays.
United Kingdom
NHS England's specialized commissioning frameworks restrict bronchial thermoplasty to designated severe asthma centers in London and Manchester. The MHRA manages post-Brexit device registration, with NICE technology appraisals determining reimbursement eligibility for biologic non-responders.
Australia
Interventional pulmonology suites in Melbourne and Sydney pilot electromagnetic navigation integration for distal airway access. The TGA regulates radiofrequency ablation catheters under medical device frameworks, while state health departments in New South Wales and Victoria evaluate procedure cost-effectiveness against biologic alternatives.
Bronchial Thermoplasty Market Competitive Environment
Top-tier vendors anchor hospital procurement workflows, while mid-tier specialists compete on navigation compatibility and catheter miniaturization. The vendor base stratifies around three archetypes: integrated platform providers owning full procedural stacks, navigation-agnostic energy delivery specialists, and consumable-focused catheter manufacturers. Dominant competitive moves include electromagnetic navigation partnerships and per-procedure leasing model rollouts.
Within the integrated platform tier, Boston Scientific Corporation and Medtronic plc occupy positions exemplifying full-stack control from generator to catheter. Olympus Corporation represents the navigation-specialist archetype, leveraging optical bronchoscopy compatibility to differentiate. These three entities anchor the competitive structure through distinct technical positioning rather than overlapping capability claims.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Olympus Corporation |
| Johnson & Johnson (Ethicon) |
| Smith & Nephew plc |
| Teleflex Incorporated |
| Cook Medical LLC |
| Stryker Corporation |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Catheter miniaturization to 2.0mm diameters for distal airway access simultaneously elevates R&D amortization burdens and consolidates procurement leverage among electromagnetic navigation-integrated platform vendors in the United States, Germany, and Japan.
Pricing Analysis
Margin tightening in single-use catheter tiers reflects MDR traceability compliance costs and proprietary electrode array material specifications. Three-tier pricing structure across navigation-integrated platforms, standalone energy systems, and commoditized consumables stratifies buyer segments. Cost-down pressure on outpatient procedure bundles accelerates because German and Japanese reimbursement codes strain to cover per-procedure material expenditures. Academic medical centers in the United States exhibit lowest price sensitivity due to bundled leasing contracts, while ambulatory surgical centers face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from hospital value-analysis committees in Germany and the United States require qualified secondary suppliers for radiofrequency generators and catheter-electrode arrays. Manufacturing concentrates in the United States, Germany, and Japan for core device assembly, with specialized polymer and conductive material inputs drawn from established medical device component hubs. Single-source vulnerability persists in electromagnetic navigation workstation supply due to concentrated intellectual property ownership. Distribution runs through integrated delivery network procurement offices and specialized respiratory institute purchasing departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic navigation proficiency bottlenecks among fellowship-trained interventional pulmonologists prop pricing power for platform-integrated vendors across the analysis window.
For Market Incumbents: Lock in hospital system partnerships through multi-year per-procedure leasing contracts embedding software update subscriptions and remote patient monitoring platforms. Deepen backward integration into catheter-electrode array manufacturing to offset MDR traceability cost inflation. Prioritize CE marking pathway acceleration for next-generation miniaturized catheter systems ahead of EU MDR clinical evidence deadlines. For New Entrants and Emerging Players: Capture Japan's aging severe asthma cohort over 65 through METI reimbursement-aligned distribution partnerships with Tokyo and Osaka tertiary centers. Target COPD bronchoscopic lung volume reduction protocols as the most penetrable indication extension. Pursue optical navigation compatibility certifications to differentiate within Olympus Corporation-installed base hospitals. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated platform vendors seeking navigation-electrode integration capabilities. Long-term viability favors manufacturers with established PMCF data repositories and FDA 510(k) clearance track records. Monitor biologic therapy non-responder stratification protocol adoption rates as the critical volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market clinical follow-up data repositories accelerate German hospital procurement decisions. |
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate interventional pulmonology service lines through bundled contracts. |
| Software Companion Development | Procedure-specific modules and remote monitoring subscriptions capture recurring revenue beyond initial device sale. |
| Reimbursement Strategy | METI incentives for minimally invasive procedures in patients over 65 expand addressable volume in Japan. |
| Regulatory Approval Pathway | FDA 510(k) clearance for COPD indication extension would unlock ambulatory surgical center demand in the United States. |
Study Parameters
FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database records formed the secondary backbone, supplemented by primary interviews with interventional pulmonologists, hospital value-analysis committee members, biomedical engineers, and GPO contracts managers. Bottom-up and top-down triangulation validated procedure volume estimates against capital equipment shipment data and reimbursement claims patterns.
Bottom-up modeling anchored forecast construction, with top-down macro validation against respiratory disease prevalence projections. Segmentation dimensions spanned product type, application, end-user setting, and delivery mode across the projection horizon. CAGRs derived from fitted adoption curves incorporating electromagnetic navigation infrastructure deployment rates and biologic therapy non-responder identification protocol penetration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biologic therapy substitution rates and MDR clinical evidence requirement evolution. A model refresh is warranted upon material change in Japanese METI reimbursement incentive structure or FDA clearance of competing bronchoscopic intervention modalities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Respiratory Disorders Treatment Market