
 Lifestyle-Related Disease Supplements Market | 2026-2036
Lifestyle-Related Disease Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Lifestyle-Related Disease Supplements Market Foresight
Personalized nutrition platforms powered by microbiome sequencing and biomarker analytics is tilting formulation science toward condition-specific supplement stacks. Abbott Laboratories leverages its diagnostic heritage to bridge testing and supplementation workflows. Bayer AG anchors its consumer health division around evidence-based cardiovascular and mineral portfolios. Amway Corporation controls a global direct-selling network that bypasses traditional retail gatekeepers in emerging markets.
Lifestyle-related disease supplements comprise bioactive compounds, concentrated botanical extracts, and micronutrient complexes manufactured through cold-press extraction, spray-drying, and enteric coating to deliver targeted physiological support for chronic condition management. The category spans vitamins, minerals, herbal extracts, and amino acids, with herbal extracts commanding premium positioning due to supply scarcity and clinical substantiation costs. Cardiovascular health and immune support applications absorb the largest share of R&D investment, while digestive wellness formulations gain traction among gut-brain axis researchers.
The FDA's Current Good Manufacturing Practice regulations and EFSA's Nutrition and Health Claims Regulation enforce stringent purity and substantiation standards that filter out undercapitalized entrants. Japan's Ministry of Health, Labour and Welfare maintains a separate Foods for Specified Health Uses framework that creates a dual-track compliance burden for multinational suppliers. Stakeholders must monitor evolving substantiation requirements for novel ingredients as regulators tighten the evidentiary threshold between structure-function claims and disease prevention assertions.
Market Dynamics
The Lifestyle-Related Disease Supplements Market pivots on regulatory substantiation requirements that now gate entry more than manufacturing scale. EFSA's health claims verification process and FDA's New Dietary Ingredient notifications force reformulation cycles that favor capitalized incumbents over commodity suppliers.
Growth Catalysts
- Japan's Foods for Specified Health Uses framework:This dual-track system creates premium positioning for clinically validated ingredients, rewarding suppliers who invest in biomarker studies.
- Microbiome sequencing convergence:Personalized nutrition platforms now integrate gut flora analysis with condition-specific supplement stacks, expanding addressable demand beyond generic multivitamins.
- Geriatric concentration in Germany:Aging demographics sustain cardiovascular and joint health formulation demand through pharmacy and direct-to-consumer channels.
Market Restraints
- Clinical substantiation cost escalation:EFSA's evidentiary threshold for disease prevention claims requires human intervention trials that strain mid-tier R&D budgets.
- Botanical extract supply concentration:Premium herbal ingredient sourcing clusters in specific cultivation regions, exposing formulators to weather-driven input volatility.
- Structure-function claim limitations:FDA enforcement actions against implied disease claims force conservative marketing that constrains consumer education.
Strategic Opportunities
- Direct-to-consumer channel expansion:Subscription-based personalized stacks bypass traditional retail gatekeepers, capturing higher margins in North America and Western Europe.
- Enteric coating technology maturation:Advanced delivery systems improve bioavailability for sensitive compounds, opening gastrointestinal and metabolic condition applications.
- India's preventive health policy tailwinds:National wellness initiatives expand reimbursement-adjacent positioning for evidence-backed formulations.
Industry Challenges
- Cross-jurisdictional compliance talent scarcity:Few regulatory affairs professionals command simultaneous expertise in FDA, EFSA, and Japan's MHLW frameworks.
- Cold-chain logistics capex requirements:Probiotic and live culture formulations demand temperature-controlled distribution infrastructure that fragments operational footprints.
- Ingredient identity verification complexity:Adulteration risks in botanical supply chains necessitate spectroscopic testing investments that compress working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lifestyle-Related Disease Supplements Market |
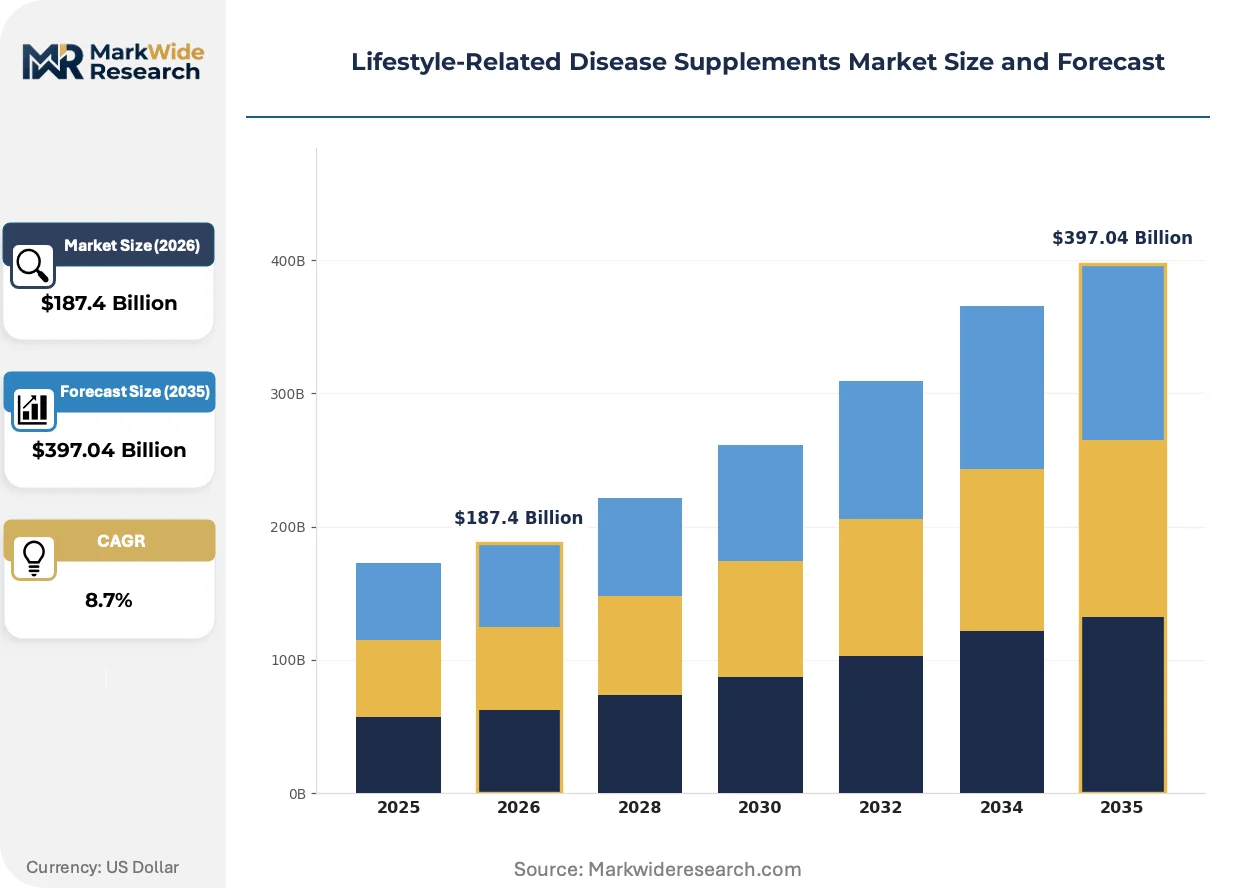
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids Application: Cardiovascular Health, Digestive Wellness, Immune Support, Joint Health End User: Adults, Seniors, Athletes, Children Distribution Channel: Online Retail, Health Food Stores, Pharmacies, Supermarkets |
| Companies Covered | Abbott Laboratories, Bayer AG, Amway Corporation, Herbalife Nutrition Limited, Nestle S.A., GNC Holdings, Nature's Bounty, Otsuka Holdings Co., Ltd., Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lifestyle-Related Disease Supplements Market Shifts & Advancements
Formulation science is digitizing across the value chain, from biomarker-driven personalization to AI-assisted compound screening. Three interconnected developments are compressing development timelines while raising the bar for clinical credibility.
Biomarker analytics platforms are digitizing supplement personalization by correlating blood metabolite panels with micronutrient deficiencies. Functional medicine clinics and employer wellness programs deploy these tools to justify premium stack pricing. The technology compresses the trial-and-error cycle that previously dominated consumer experimentation.
EFSA's 2023 guidance on botanical health claims tightens the evidentiary gap between structure-function and disease prevention assertions. Formulators must now design human studies with validated endpoints rather than relying on traditional use evidence. Cardiovascular and cognitive health segments face the steepest compliance recalibration.
Subscription commerce models disintermediate pharmacy and mass retail channels across North American and Western European markets. Consumers commit to recurring personalized deliveries based on diagnostic data rather than seasonal purchasing. This behavioral shift concentrates lifetime value with platforms that integrate testing and supplementation workflows.
Lifestyle-Related Disease Supplements Market Segmentation
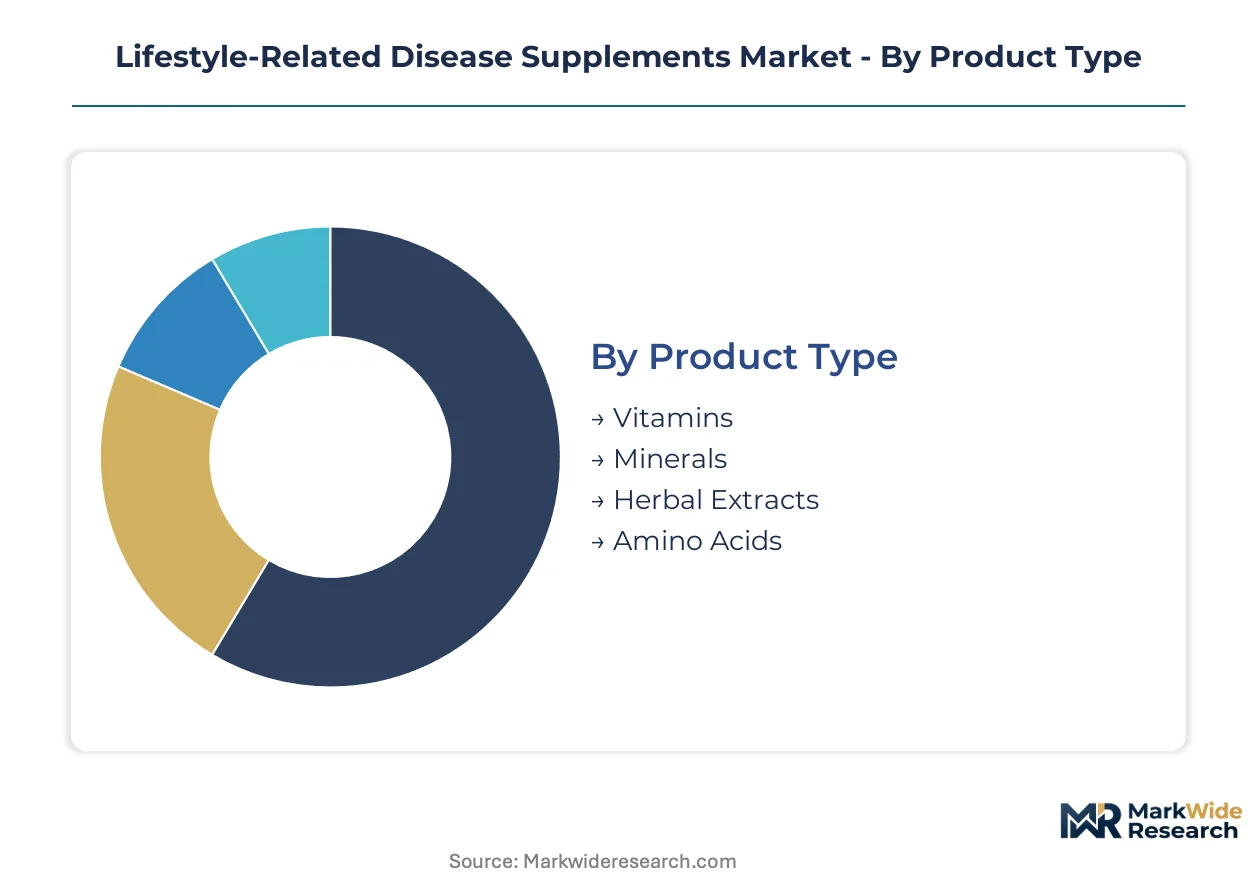
Segmentation in lifestyle-related disease supplements determines formulation priorities, regulatory pathways, and channel economics. Product type and application segments carry distinct substantiation burdens and margin profiles that reshape competitive positioning.
Product Type:
Vitamins and minerals turn inventory fastest through mass retail channels, while herbal extracts cycle slowly due to cultivation lead times and clinical validation requirements.
- Vitamins:Synthetic and natural fat-soluble and water-soluble compounds manufactured through fermentation and chemical synthesis. Demand concentrates in Germany's pharmacy channels where statutory health insurance adjacent positioning sustains premium pricing. Reformulation cycles accelerate as EFSA tightens stability testing protocols.
- Herbal Extracts:Concentrated botanical actives from standardized plant material, typically 4:1 to 20:1 extraction ratios using ethanol or supercritical CO2 methods. Supply scarcity in Rhodiola rosea and Ashwagandha root concentrates demand in Japan's Foods for Specified Health Uses framework, where clinical substantiation commands reimbursement-adjacent positioning.
- Minerals:Chelated and inorganic elemental compounds including zinc, magnesium, and selenium salts.
- Amino Acids:Proteinogenic and conditionally essential compounds including L-carnitine and N-acetylcysteine for metabolic support.
Vitamins dominate installed base through multivitamin ubiquity. Herbal extracts are where expansion concentrates as personalized nutrition platforms prioritize condition-specific actives.
Application:
Margin stratification separates preventive maintenance applications from acute condition management, with cardiovascular and immune support commanding formulation R&D investment.
- Cardiovascular Health:Omega-3 fatty acids, plant sterols, and coenzyme Q10 formulations targeting lipid profiles and endothelial function. Demand clusters in Japan's aging population where METI's functional food labeling system rewards biomarker-validated efficacy claims. Enteric coating investments improve bioavailability for sensitive polyunsaturated compounds.
- Immune Support:Vitamin D, zinc, and botanical immunomodulators including echinacea and elderberry extracts. Germany's Federal Institute for Drugs and Medical Devices (BfArM) oversight of borderline products creates compliance complexity for combination formulations. Subscription commerce models capture recurring demand through direct-to-consumer platforms.
- Digestive Wellness:Probiotic cultures, prebiotic fibers, and digestive enzymes targeting gut-brain axis modulation.
- Joint Health:Glucosamine, chondroitin, and collagen peptides for cartilage integrity support.
Cardiovascular health represents the fastest-growing trajectory as geriatric populations in Japan and Germany sustain pharmacy channel demand. Digestive wellness is where microbiome personalization platforms are gaining share fastest.
End User:
Customer lifetime value diverges sharply between episodic purchasers and chronic condition managers, with seniors and athletes showing highest retention in subscription models.
- Seniors:Formulations addressing polypharmacy interactions and reduced gastric acid secretion, with emphasis on B12, D3, and K2 bioavailability. Japan's 65-plus demographic concentration drives sustained demand through pharmacy and direct-to-consumer channels.
- Athletes:Performance and recovery formulations including branched-chain amino acids and anti-inflammatory botanicals. Evidence requirements from anti-doping agencies elevate third-party certification costs.
- Adults:Preventive and stress-management formulations targeting working-age populations.
- Children:Palatability-modified delivery formats including gummies and liquid suspensions with stringent purity protocols.
Adults dominate installed base through mass market multivitamin penetration. Seniors are where expansion concentrates as aging demographics in Germany and Japan reshape category priorities.
Distribution Channel:
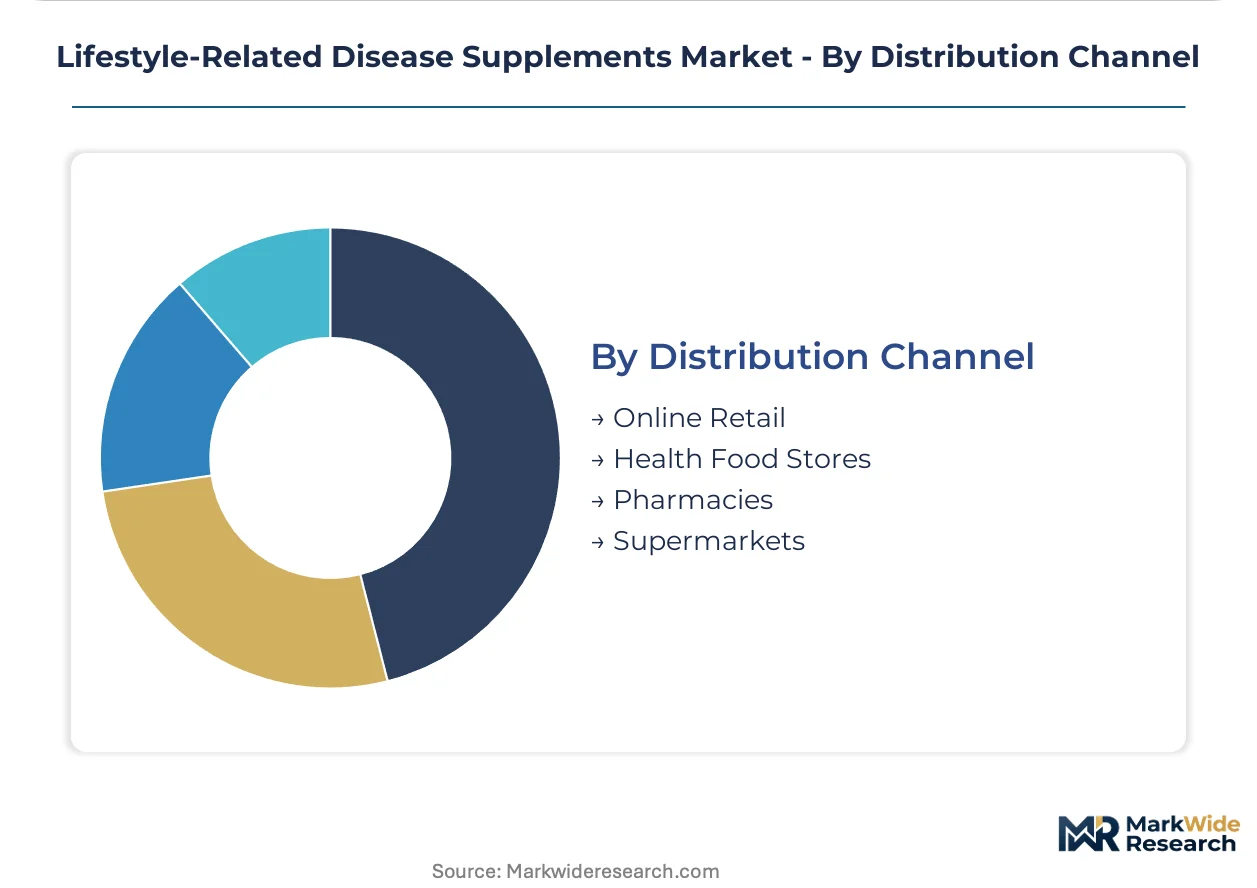
Channel economics favor vertical integration in online retail, while pharmacy and health food stores retain regulatory credibility advantages for condition-specific claims.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription-based personalized stacks. North American markets show highest penetration as FDA structure-function claim constraints favor educational content over shelf positioning.
- Pharmacies:Professional recommendation channels with pharmacist consultation services supporting premium pricing for clinically validated formulations. Germany's pharmacy-exclusive system for certain mineral combinations sustains margin protection.
- Health Food Stores:Specialty retail with trained staff and practitioner-grade product access.
- Supermarkets:Mass market accessibility with price-competitive basic vitamin and mineral offerings.
Supermarkets dominate installed base through multivitamin volume. Online retail is where expansion concentrates as diagnostic-integrated subscription models bypass traditional gatekeepers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in lifestyle-related disease supplements tilt toward net importers with aging demographics, while manufacturing clusters concentrate in jurisdictions with botanical cultivation traditions and contract manufacturing infrastructure. The United States, Germany, Japan, China, and India collectively shape procurement patterns and regulatory harmonization efforts.
United States
Direct-to-consumer subscription platforms capture the highest margins through diagnostic-integrated supplement stacks. FDA's New Dietary Ingredient notification pathway and Current Good Manufacturing Practice enforcement filter out undercapitalized entrants. The San Diego-Boston corridor houses microbiome testing laboratories that feed personalized nutrition algorithms.
Germany
Pharmacy-exclusive distribution for certain mineral combinations sustains premium pricing through professional recommendation channels. BfArM oversight of borderline products creates compliance complexity for immune support combination formulations. The Frankfurt-Rhine-Main cluster anchors logistics operations for Central European distribution.
Japan
METI's functional food labeling system rewards biomarker-validated efficacy claims for cardiovascular formulations targeting the 65-plus demographic. The Foods for Specified Health Uses framework creates a dual-track compliance burden for multinational suppliers. The Kanto region concentrates headquarters operations for domestic supplement manufacturers.
China
SAMR's health food registration requirements and dual carbon goals reshape ingredient sourcing and manufacturing footprints. Domestic demand for preventive cardiovascular and metabolic health formulations expands through e-commerce channels. The Yangtze River Delta clusters contract manufacturers serving both domestic and export markets.
India
National wellness initiatives expand reimbursement-adjacent positioning for evidence-backed formulations targeting diabetes and cardiovascular conditions. FSSAI's evolving standards for nutraceuticals create transitional compliance windows for organized players. Maharashtra and Gujarat concentrate Ayurvedic extract processing infrastructure and export-oriented manufacturing.
Lifestyle-Related Disease Supplements Market Competitive Landscape
On the supply side, the industry is consolidating around capitalized incumbents with integrated diagnostic-to-supplementation workflows and global direct-selling networks. Tiered competitive dynamics separate multinational pharmaceutical heritage players from specialized botanical extract houses and platform-native subscription brands. Dominant competitive moves include strategic partnerships between testing laboratories and formulation houses, plus geographic expansion through regulatory sandbox jurisdictions.
Within the pharmaceutical heritage tier, Abbott Laboratories and Bayer AG exemplify the diagnostic-to-consumer health bridge strategy, while Amway Corporation anchors the direct-selling archetype with bypass capabilities in emerging markets. These three occupy positions that reward clinical substantiation investments and cross-jurisdictional compliance expertise.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bayer AG |
| Amway Corporation |
| Herbalife Nutrition Limited |
| Nestle S.A. |
| GNC Holdings |
| Nature's Bounty |
| Otsuka Holdings Co., Ltd. |
| Glanbia plc |
| Others |
Supply & Pricing Matrix
Rhodiola rosea and Ashwagandha cultivation clusters in Siberia and the Indian subcontinent concentrate premium herbal extract supply, anchoring margin capture downstream with formulators who command Japan's Foods for Specified Health Uses reimbursement-adjacent positioning.
Pricing Analysis
Pharmacy channel buyers anchor premium pricing for clinically validated cardiovascular and joint health formulations, while direct-to-consumer subscription models capture recurring revenue through diagnostic-integrated personalized stacks. Three-tier pricing structure across premium, standard, and economy levels separates pharmacist-recommended clinically validated products from mass-market multivitamins and private-label commoditized offerings. Price differentiation hinges on EFSA health claims verification status and cold-chain logistics certification tier. Pricing pressure stems from EFSA's tightened evidentiary thresholds for disease prevention assertions, forcing reformulation investments that compress mid-tier margins. Mass-market multivitamin purchasers exhibit highest price sensitivity, while geriatric chronic condition managers in Japan and Germany demonstrate lowest sensitivity due to pharmacy channel professional recommendation dependence.
Supply Chain Analysis
Extended payment terms from Indian Ayurvedic extract processors and supply-chain finance facilities from Chinese contract manufacturers ease working capital cycles for branded formulators facing botanical ingredient identity verification costs. Raw material sourcing concentrates in India for Ashwagandha and turmeric extracts, China for probiotic fermentation substrates and amino acid precursors, and Japan for specialized enteric coating polymers. Formulation houses draw from concentrated Rhodiola rosea wild harvest regions, standardized green tea catechin plantations, and marine omega-3 extraction facilities. Single-source vulnerability in wild-crafted botanical supply chains exposes formulators to climate-driven harvest volatility and adulteration risks requiring spectroscopic testing investments. Distribution runs through temperature-controlled logistics networks for probiotic cultures, pharmacy-exclusive channels for mineral combinations in Germany, and direct-to-consumer subscription platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-jurisdictional regulatory affairs expertise represents the critical capability gap separating capitalized incumbents from commodity suppliers, as simultaneous FDA, EFSA, and Japan MHLW framework mastery commands premium valuation.
For Market Incumbents: Insulate formulation portfolios from EFSA substantiation cost escalation by deepening backward integration into clinically validated botanical extraction and captive biomarker study capabilities. Prioritize diagnostic-to-supplementation workflow integration through microbiome testing laboratory partnerships or in-house acquisitions. Defend against platform-native subscription brands by locking pharmacy channel exclusivity for mineral combinations in Germany and METI functional food labeling in Japan. For New Entrants and Emerging Players: India's preventive health policy tailwinds around diabetes and cardiovascular reimbursement-adjacent positioning offer the most penetrable white-space entry, given FSSAI's transitional compliance windows and national wellness initiative expansion. Target employer wellness program channels with biomarker-driven personalized stack offerings that bypass retail gatekeeper concentration. Pursue regulatory sandbox positioning in emerging markets with evolving nutraceutical standards before incumbents establish compliance infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer subscription platforms that have achieved diagnostic integration but lack cross-jurisdictional compliance scale. Five-to-ten year viability hinges on regulatory affairs talent depth and cold-chain logistics infrastructure ownership rather than brand equity alone. Watch EFSA enforcement patterns against implied disease claims as the inflection signal for portfolio rebalancing toward structure-function conservative positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Testing Integration | Abbott Laboratories bridges laboratory workflows with consumer supplementation through biomarker-validated personalized stacks. |
| Cross-Jurisdictional Compliance Buildout | Simultaneous FDA NDI notification and EFSA health claims expertise filters out undercapitalized competitors across North American and European access. |
| Cold-Chain Distribution Infrastructure | Temperature-controlled logistics networks for probiotic cultures fragment operational footprints but capture premium positioning in digestive wellness. |
| Botanical Extraction Backward Integration | Captive supply of Rhodiola rosea and Ashwagandha concentrates mitigates weather-driven input volatility and adulteration risks. |
| Subscription Commerce Platform Development | Recurring personalized delivery models concentrate lifetime value and bypass traditional pharmacy and mass retail gatekeepers. |
Research Methodology
Operator-level perspectives from regulatory affairs directors at multinational consumer health divisions, pharmacy category buyers in Germany and Japan, microbiome testing laboratory executives, and direct-to-consumer subscription platform founders anchored the qualitative base. Primary interview insights combined with secondary validation from FDA New Dietary Ingredient notification databases, EFSA health claims register filings, Japan MHLW Foods for Specified Health Uses approvals, and customs trade data for botanical extract flows. Bottom-up demand modeling across geriatric population segments, athlete performance categories, and preventive health adult cohorts triangulated with top-down market sizing from pharmacy channel audit data and e-commerce platform transaction analytics.
Scenario-bracketing around EFSA substantiation timeline acceleration, Japan METI functional food labeling expansion, and India FSSAI nutraceutical standard maturation framed the projection horizon. Segmentation dimensions modeled spanned product type tier, application condition focus, end-user demographic archetype, and distribution channel structure. CAGRs derived from regression analysis of historical regulatory approval velocity correlated with demographic aging trajectories and diagnostic technology adoption curves. Forecast inputs incorporated cold-chain logistics infrastructure buildout rates and employer wellness program penetration assumptions.
Practitioners should monitor EFSA enforcement actions against implied disease claims, Japan METI biomarker validation requirement changes, and India FSSAI transitional compliance deadline extensions for early signals of forecast revision necessity. The analysis reflects assumptions regarding sustained geriatric demand concentration in Japan and Germany, continued direct-to-consumer channel expansion in North America, and stable botanical supply from established cultivation regions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market