
 Thoracolumbar Spine Devices Market | 2026-2036
Thoracolumbar Spine Devices Market Size, Share, and Industry Trends Forecast 2026-2036
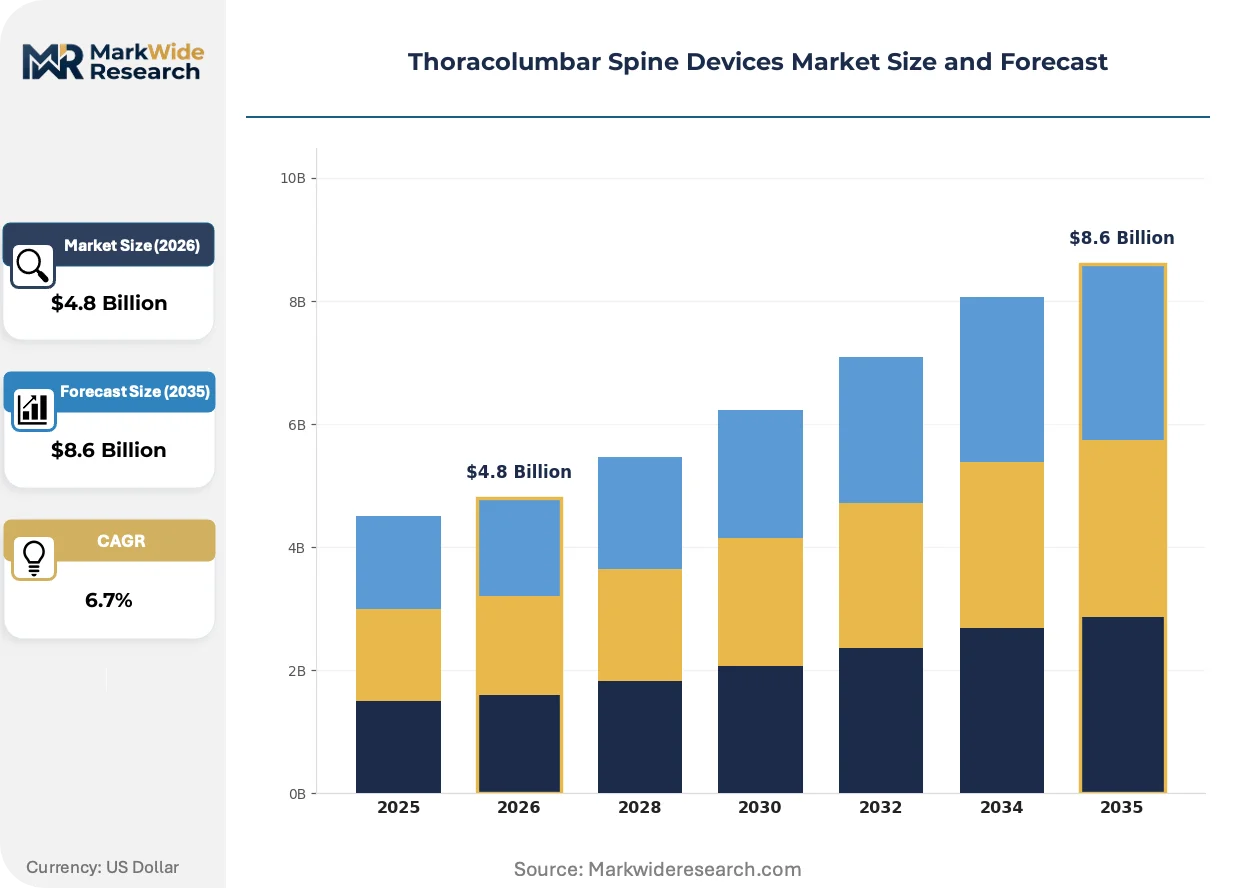
Thoracolumbar Spine Devices Market Outlook
Implantable biologics revenue is reshaping margin distribution across the thoracolumbar spine device value chain. Medtronic plc leverages its integrated biologics portfolio to capture premium positioning in fusion procedures. Stryker Corporation sustains manufacturing scale across titanium and PEEK implant platforms. Globus Medical specializes in expandable interbody technologies that differentiate its offering in minimally invasive segments.
Thoracolumbar spine devices encompass instrumentation and implants designed for stabilization, fusion, and motion preservation from the T1 vertebra through the L5-S1 junction, typically manufactured from titanium alloys, polyetheretherketone, or resorbable polymers via precision machining and additive manufacturing. These devices restore spinal alignment, decompress neural elements, and enable arthrodesis in degenerative, traumatic, and deformity pathologies. Spinal fusion devices and pedicle screws anchor the current revenue base due to established reimbursement and surgeon familiarity, while spine biologics represents the fastest-expanding margin pool as bone graft substitutes displace autograft harvesting. Minimally invasive surgery procedures command premium pricing and faster recovery profiles, though open surgery retains dominance in complex deformity and revision cases.
FDA 510(k) clearance pathways govern U.S. market entry for thoracolumbar implants, while EU MDR requirements impose strengthened clinical evidence standards for CE marking in European markets. Japan's PMDA enforces stringent QMS audits that filter non-compliant manufacturers from its high-value reimbursement environment. Stakeholders must monitor evolving FDA guidance on 3D-printed patient-specific implants and EU MDR notified body capacity constraints that could reshape competitive access timelines.
Market Dynamics
Reimbursement migration toward outpatient surgical settings is compressing hospital purchasing power while elevating ambulatory surgical centers as volume gatekeepers in thoracolumbar spine procedures.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:These three countries sustain elevated implant utilization rates through established spinal surgery infrastructures and higher procedure volumes per capita than emerging markets.
- FDA 510(k) clearance pathway:This premarket notification framework accelerates time-to-market for iterative implant designs compared to premarket approval routes, enabling faster product lifecycle turnover.
- Expandable interbody cage technology:These devices enable minimally invasive insertion with in-situ expansion, reducing neural retraction requirements and accelerating postoperative ambulation protocols.
Market Restraints
- Titanium alloy feedstock concentration:Primary titanium sponge production concentrates in a limited supplier base, exposing manufacturers to input cost volatility and geopolitical supply disruptions.
- EU MDR clinical evidence requirements:Strengthened standards for CE marking impose extended timelines and documentation burdens that filter non-compliant manufacturers from European market access.
- Autograft harvesting persistence:Surgeon familiarity with iliac crest bone graft techniques sustains substitution pressure against commercial bone graft substitutes despite longer operative times.
Strategic Opportunities
- 3D-printed patient-specific implants:FDA guidance evolution on additive manufacturing creates pathway differentiation for manufacturers with in-house electron beam melting capabilities.
- Motion preservation devices:Artificial disc replacement and dynamic stabilization systems address unmet demand in younger patient cohorts seeking alternatives to fusion.
- Ambulatory surgical center channel expansion:Outpatient reimbursement parity legislation in select US states is redirecting lumbar decompression volumes from inpatient to same-day settings.
Industry Challenges
- EU MDR notified body capacity constraints:Limited certification infrastructure extends audit waiting periods and compresses product launch windows for European market entry.
- Spine surgeon training pipeline:Fellowship program output fails to match retiring surgeon replacement rates, constraining addressable procedure growth regardless of device availability.
- Biologics cold chain integrity:Demineralized bone matrix and cellular allograft products require specialized logistics infrastructure that fragments distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thoracolumbar Spine Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Spinal Fusion Devices, Interbody Cages, Spine Biologics, Pedicle Screws Material: Titanium, Stainless Steel, PEEK, Biodegradable Polymers End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Procedure Type: Open Surgery, Minimally Invasive Surgery, Revision Surgery, Decompression Surgery |
| Companies Covered | Medtronic plc, DePuy Synthes, Stryker Corporation, Globus Medical, Zimmer Biomet Holdings, NuVasive, B. Braun Melsungen AG, Orthofix Medical, Alphatec Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thoracolumbar Spine Devices Market Strategic Shifts
Additive manufacturing, regulatory evidence standard elevation, and site-of-care migration are restructuring competitive requirements across implant design, market access, and commercial deployment.
Patient-specific titanium implants produced via electron beam melting are collapsing the distinction between standard and anatomically matched device portfolios. Academic medical centers in the United States and Germany are adopting these implants for complex revision and deformity cases where off-the-shelf geometries prove inadequate. The technology is collapsing inventory carrying costs for hospitals while compressing operative time through reduced trialing iterations.
EU MDR Article 61 clinical evaluation requirements are elevating post-market surveillance obligations for thoracolumbar implant manufacturers. The regulation mandates systematic literature reviews and clinical data generation that smaller manufacturers lack resources to compile independently. European notified bodies are prioritizing audit capacity toward high-volume device categories, extending review timelines for niche spinal applications.
Hospital purchasing consortia are consolidating vendor selection authority through centralized implant committees that override individual surgeon preference. Independent ambulatory surgical centers are responding by cultivating direct manufacturer relationships that bypass distributor markups and enable case-volume pricing. This channel disintermediation is most pronounced in Texas, Florida, and Arizona where outpatient spine procedure volumes exceed national averages.
Thoracolumbar Spine Devices Market Segmentation
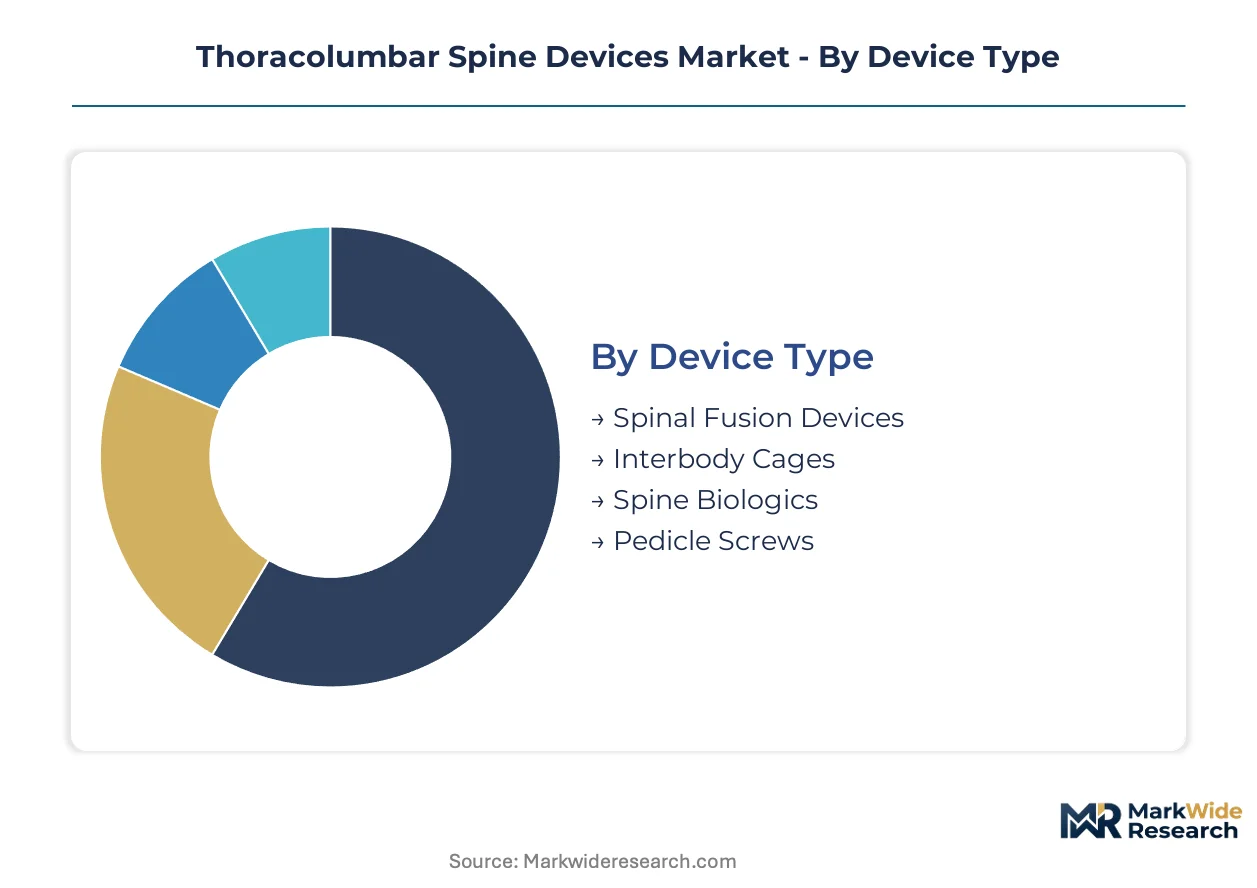
Device taxonomy in thoracolumbar spine care determines reimbursement pathways, inventory economics, and surgeon training requirements. Material selection drives biocompatibility profiles and imaging compatibility, while procedure setting shapes capital deployment and pricing power across the value chain.
Device Type:
Mature fusion hardware anchors current revenue pools, while emerging biologics and expandable technologies are capturing margin expansion.
- Spinal Fusion Devices:Rods, plates, and interbody spacers manufactured from titanium alloys or PEEK achieve arthrodesis through mechanical stabilization and load sharing. Demand concentrates in academic medical centers performing complex deformity corrections, driven by established CPT reimbursement codes that secure predictable payment cycles.
- Interbody Cages:Expandable titanium or PEEK implants enable in-situ height restoration with minimized neural retraction, collapsing operative time and accelerating ambulation protocols. Adoption is climbing fastest in ASC settings where same-day discharge metrics determine facility economics.
- Spine Biologics:Demineralized bone matrix and synthetic graft substitutes displace autograft harvesting, though cold chain logistics fragment distribution economics.
- Pedicle Screws:Polyaxial and monoaxial screw systems provide posterior column fixation across degenerative and trauma indications.
Spinal Fusion Devices handle the majority of throughput; Spine Biologics is expanding most quickly on share.
Material:
Cost tier stratification separates premium implant substrates from commoditized alternatives, with radiolucency and osseointegration properties commanding price premiums.
- Titanium:Ti-6Al-4V ELI alloy delivers strength-to-weight ratios and osteoconductive surfaces via plasma-sprayed or additive-manufactured porosity. Japan's PMDA enforces stringent QMS audits that filter non-compliant titanium suppliers from its high-value reimbursement environment.
- PEEK:Polyetheretherketone provides radiolucent modulus-matching to native bone, enabling postoperative CT assessment without scatter artifact. German trauma centers prioritize PEEK interbodies for polytrauma cases requiring repeated imaging surveillance.
- Stainless Steel:316L surgical grade retains use in cost-sensitive emerging markets and temporary external fixation constructs.
- Biodegradable Polymers:Polylactic acid and polyglycolic acid resorbables address pediatric applications where permanent implants complicate future growth.
Titanium commands the dominant share of implant value; PEEK is climbing fastest as image-guided surgery expands.
End User:
Volume concentration is shifting from inpatient facilities toward outpatient channels as reimbursement parity legislation redirects procedure economics.
- Hospitals:Tertiary centers retain complex deformity, revision, and trauma cases requiring intensive care backup and blood bank access. Purchasing consortia are consolidating vendor selection authority through centralized implant committees that override individual surgeon preference.
- Ambulatory Surgical Centers:Independent ASCs in Texas, Florida, and Arizona cultivate direct manufacturer relationships that bypass distributor markups and enable case-volume pricing for lumbar decompression volumes.
- Orthopedic Clinics:Office-based settings concentrate on non-operative management and preoperative optimization.
- Rehabilitation Centers:Post-acute facilities manage recovery protocols and functional outcome tracking.
Hospitals retain the dominant procedure load; Ambulatory Surgical Centers are gaining share fastest on site-of-care migration.
Procedure Type:
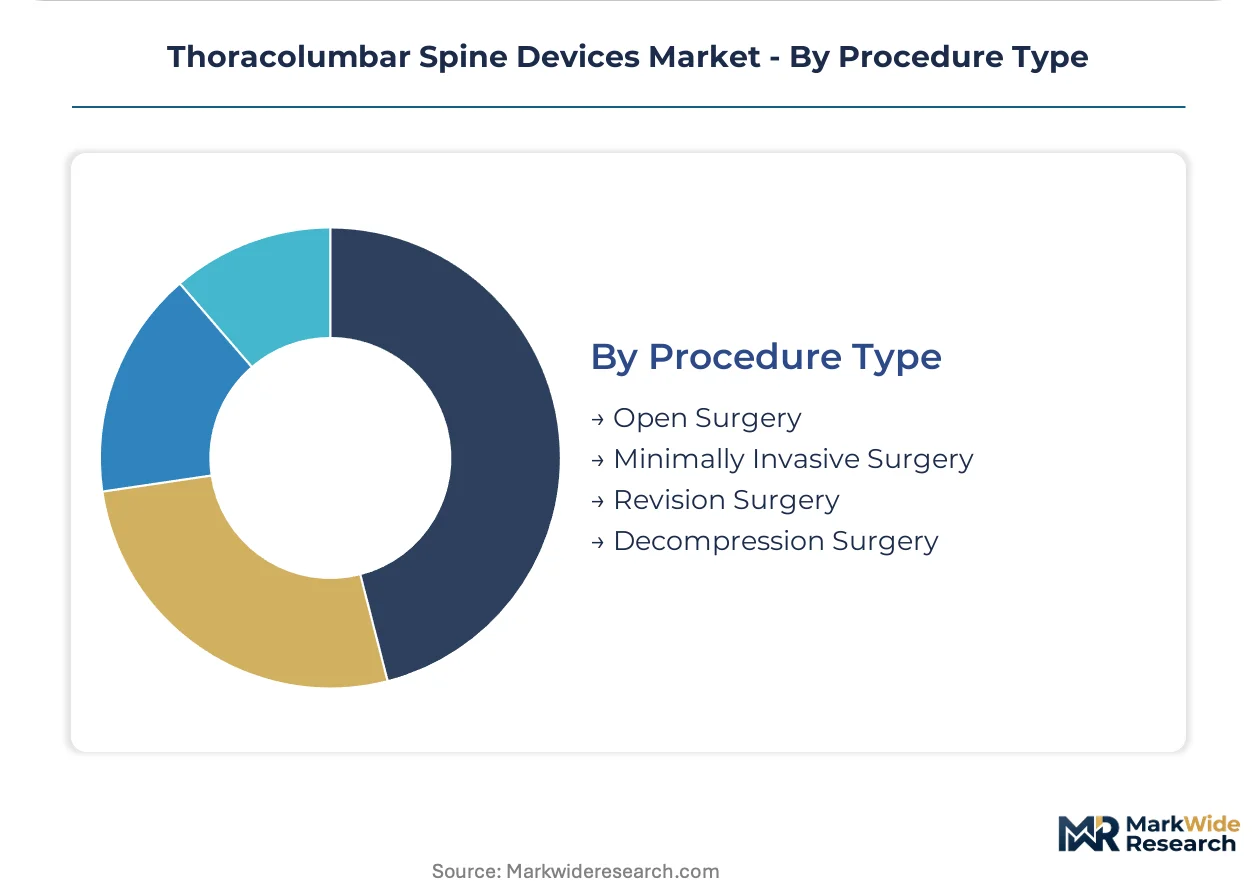
Application severity stratifies technical requirements, with complex interventions demanding specialized instrumentation and extended operative time.
- Open Surgery:Midline approaches with bilateral muscle stripping provide direct visualization for multilevel fusions and severe deformity corrections. Academic medical centers in the United States and Germany deploy open techniques where three-dimensional correction targets exceed minimally invasive capabilities.
- Minimally Invasive Surgery:Tubular retractor and percutaneous screw systems reduce soft tissue disruption and blood loss, supporting same-day discharge eligibility. ASC adoption is climbing steepest where reimbursement parity legislation enables facility fee capture comparable to hospital outpatient departments.
- Revision Surgery:Scar tissue dissection and implant extraction procedures carry elevated complication profiles and hardware costs.
- Decompression Surgery:Laminectomy and discectomy procedures address neural element compression without fusion requirements.
Open Surgery handles the majority of complex case throughput; Minimally Invasive Surgery is climbing fastest on ASC channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Implant utilization patterns diverge sharply across major markets, with the United States favoring outpatient migration while Japan and Germany retain inpatient dominance for complex deformity cases. Reimbursement velocity and regulatory stringency shape these consumption differentials.
United States
Ambulatory surgical centers in Texas, Florida, and Arizona capture accelerating lumbar decompression volumes as state-level reimbursement parity legislation enables facility fee structures matching hospital outpatient departments. FDA 510(k) clearance pathways sustain rapid product lifecycle turnover for iterative implant designs. The Dallas-Fort Worth metroplex anchors ASC channel expansion with procedure volumes exceeding national averages.
Germany
Academic medical centers in Bavaria and Baden-Württemberg deploy open surgical techniques for severe deformity corrections where three-dimensional targets exceed minimally invasive capabilities. EU MDR Article 61 clinical evaluation requirements extend audit timelines and elevate post-market surveillance obligations for CE marking. Berlin-Brandenburg clusters concentrate notified body engagement resources as manufacturers navigate strengthened evidence standards.
Japan
Aging demographics sustain elevated per-capita implant utilization through established spinal surgery infrastructures concentrated in Kanto and Kansai regions. PMDA enforces stringent QMS audits that filter non-compliant titanium suppliers from high-value reimbursement environments. Tokyo academic centers prioritize PEEK interbodies for polytrauma cases requiring repeated imaging surveillance.
China
Domestic manufacturers capture share in cost-sensitive provincial hospital tiers while premium segments remain import-dependent. NMPA medical device registration pathways are converging toward international standards, compressing historical regulatory arbitrage advantages. Yangtze River Delta clusters in Shanghai and Jiangsu concentrate additive manufacturing capabilities for patient-specific implant production.
Switzerland
Precision machining heritage sustains niche positioning in high-value titanium implant substrates for European export markets. Swissmedic certification requirements align with EU MDR standards, enabling seamless continental market access. Basel-Zurich corridor hosts specialized metallurgy suppliers serving orthopedic device value chains.
Thoracolumbar Spine Devices Market Competitive Environment
Capability concentration sits with integrated biologics-and-hardware portfolios; scale advantage sits with multi-platform titanium and PEEK manufacturers. The vendor base stratifies across three tiers: diversified orthopedic conglomerates with full spine portfolios, mid-cap specialists in expandable or motion-preservation technologies, and regional fabricators serving cost-sensitive hospital tiers. Dominant competitive moves include M&A for biologics integration and direct ASC channel cultivation bypassing distributor networks.
Within the diversified conglomerate tier, Medtronic plc, Stryker Corporation, and Globus Medical exemplify contrasting strategic postures. Medtronic represents integrated biologics-and-hardware positioning through its broad fusion portfolio. Stryker anchors scale-driven manufacturing across metallic and polymer platforms. Globus Medical occupies a specialist position in expandable interbody technologies that differentiate minimally invasive offerings. These three entities collectively illustrate the capability-scale tension reshaping vendor selection authority as hospital purchasing consortia consolidate implant committees.
| Leading Market Players |
|---|
| Medtronic plc |
| DePuy Synthes |
| Stryker Corporation |
| Globus Medical |
| Zimmer Biomet Holdings |
| NuVasive |
| B. Braun Melsungen AG |
| Orthofix Medical |
| Alphatec Holdings |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta additive manufacturing clusters in Shanghai and Jiangsu anchor patient-specific titanium implant production, concentrating capacity among electron beam melting specialists whose output scarcity translates into premium pricing power for complex revision cases. This geographic concentration shapes downstream contract structures across the thoracolumbar device value chain.
Pricing Analysis
Long-term offtake agreements between hospital purchasing consortia and tier-one manufacturers dominate spinal fusion hardware procurement, while spot purchasing persists for emergency revision cases and biologics with cold chain constraints. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared titanium interbodies from PEEK alternatives and stainless steel constructs in cost-sensitive tiers. Pricing pressure stems from ambulatory surgical centers negotiating case-volume discounts that bypass traditional distributor markups. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement for complex deformity procedures.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for titanium alloy feedstock and precision-machined components. Primary titanium sponge production concentrates in China, Russia, and Japan, while PEEK resin synthesis anchors in Germany, Belgium, and the United States. Raw material dependencies span Ti-6Al-4V ELI alloy bar stock, demineralized bone matrix allograft, and electron beam melting powder feedstock. Distribution runs through specialized orthopedic distributors with surgeon sales representative relationships, though direct manufacturer-to-ASC channels are displacing this model in Texas, Florida, and Arizona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spine biologics revenue layers—including demineralized bone matrix and cellular allograft subscriptions—are expanding faster than hardware sales as bone graft substitutes displace autograft harvesting and create recurring procurement relationships.
For Market Incumbents: Entrench biologics-and-hardware integration through captive supply of demineralized bone matrix and synthetic graft substitutes that lock hospital purchasing committees into bundled contracts. Deepen backward integration into titanium alloy feedstock to buffer against Chinese and Russian supply volatility. Prioritize direct ASC channel cultivation in Texas, Florida, and Arizona where reimbursement parity legislation concentrates outpatient volume growth and threatens traditional distributor relationships. For New Entrants and Emerging Players: Mid-market expandable interbody technologies for ambulatory surgical centers represent the most penetrable entry point, as these facilities prioritize same-day discharge metrics over brand heritage and lack incumbent purchasing committee entrenchment. Motion preservation devices for younger patient cohorts seeking fusion alternatives offer second white-space targeting. Lead with case-volume pricing models that undercut distributor-inflated hospital contracts by fifteen to twenty percent. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive manufacturing specialists with in-house electron beam melting capabilities and FDA 510(k) clearance pathways for patient-specific implants. Long-term viability hinges on EU MDR compliance infrastructure that smaller manufacturers lack resources to maintain independently. Watch notified body capacity constraints in Germany and capacity expansion announcements from Yangtze River Delta clusters as inflection indicators for competitive access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated market entry for iterative titanium and PEEK implant designs sustains product lifecycle turnover against PMA timelines. |
| EU MDR CE Marking Pathway | Strengthened Article 61 clinical evidence requirements filter non-compliant manufacturers and consolidate European market access among resourced incumbents. |
| Hospital System Partnership | Centralized implant committees at academic medical centers override surgeon preference and anchor long-term offtake contracts for fusion hardware. |
| Software Companion Development | Preoperative planning platforms for patient-specific additive-manufactured implants reduce operative trialing and collapse inventory carrying costs. |
| Reimbursement Strategy | Outpatient parity legislation in Texas, Florida, and Arizona redirects lumbar decompression volumes toward ASC facility fee capture. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body audit records, and hospital procurement contract filings preceded structured interviews with spine surgeons, biomedical engineers, GPO contracts managers, and ASC operations directors. Primary fieldwork combined with secondary validation against CMS Medicare reimbursement data, PMDA QMS audit disclosures, and titanium alloy trade flow statistics. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation across device type, material, and end-user categories.
Assumptions held fixed across the analysis window include prevailing FDA 510(k) clearance pathway timelines, EU MDR notified body capacity constraints, and reimbursement parity legislation in identified US states. Variables modeled encompass aging demographic trajectories in Japan, Germany, and the United States; additive manufacturing adoption curves in academic medical centers; and biologics cold chain logistics fragmentation. CAGRs derived from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends and spinal surgery infrastructure development patterns.
Practitioners should monitor EU MDR notified body capacity expansion, FDA guidance evolution on 3D-printed implants, and titanium alloy feedstock price volatility for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle Ear Implants Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Sialendoscopes Market
Medical Devices
Global Vessel Sealing Devices Market