
 NDT and Inspection Market | 2026-2036
NDT and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
NDT and Inspection Market Insights
A capital-intensity divergence between asset-heavy equipment manufacturers and labor-dependent service providers is rotating competitive dynamics across the NDT and Inspection landscape. Olympus Corporation leverages its vertical integration in phased array transducer manufacturing to sustain premium positioning in ultrasonic systems. Bureau Veritas anchors its global footprint through accredited laboratories that compete on turnaround speed for oil and gas certification. Waygate Technologies specializes in digital radiography and computed tomography, occupying the high-resolution segment for aerospace turbine inspection.
Non-destructive testing and inspection encompasses techniques that evaluate material properties, structural integrity, and component quality without causing damage, employing electromagnetic radiation, high-frequency sound waves, or magnetic fields to detect subsurface flaws in metals, composites, and welds. Ultrasonic technology leads in revenue contribution due to its portability and penetration depth in thick-section steel, while X-ray systems command higher capital investment and dominate aerospace casting verification. Manufacturing applications represent the broadest addressable base, though oil and gas inspection generates the highest per-contract value through regulatory-mandated turnaround schedules.
The FAA mandates recurring non-destructive evaluation for commercial aircraft structural components under airworthiness directives, while OSHA enforces workplace exposure limits that drive radiographic testing protocol upgrades. The EU AI Act and MDR frameworks are reshaping automated defect recognition systems and medical device inspection requirements across European manufacturing. Stakeholders must weigh capital deployment toward robotics-enabled inspection platforms against the defensibility of specialized technician networks as labor availability tightens in certified NDT personnel pools.
Market Dynamics
Phased array ultrasonic technology is compressing inspection cycle times across heavy-asset industries, forcing incumbents to reconfigure service delivery models around real-time data analytics rather than manual technician deployment.
Growth Catalysts
- FAA Airworthiness Directives:Recurring structural evaluation mandates for commercial aircraft fleets drive sustained ultrasonic and radiographic testing spend across North American aerospace maintenance networks.
- Pipeline Integrity Management:Regulatory pressure from PHMSA and equivalent bodies in Germany and Japan accelerates displacement of conventional radiography by automated ultrasonic corrosion mapping systems.
- Refinery Turnaround Cycles:The US Gulf Coast petrochemical corridor concentrates demand for pressure vessel and piping inspection during scheduled maintenance windows.
Market Restraints
- Certified Technician Scarcity:ASNT and ISO 9712 qualification pipelines cannot replenish retiring radiographic film interpreters, creating bottlenecks in ultrasonic phased array deployment.
- Equipment Capital Intensity:Digital radiography flat-panel detectors and computed tomography systems require substantial upfront investment, favoring rental models over ownership for mid-size inspection contractors.
- Substitution by Predictive Analytics:Sensor-based condition monitoring platforms reduce frequency of physical inspection for rotating equipment in power generation assets.
Strategic Opportunities
- Brazilian Offshore Expansion:Pre-salt field development creates demand for subsea automated ultrasonic testing and remotely operated inspection vehicles in deepwater production infrastructure.
- EU AI Act Compliance:Automated defect recognition software for weld inspection must meet algorithmic transparency requirements, creating first-mover advantage for vendors with explainable AI architectures.
- Additive Manufacturing Qualification:In-process monitoring and post-build computed tomography verification open new service lines for aerospace and medical implant producers adopting metal 3D printing.
Industry Challenges
- Data Integration Complexity:Inspection data management systems must interface with enterprise asset management platforms like SAP and IBM Maximo, requiring custom API development for each client environment.
- Multi-Standard Certification Burden:Service providers operating across US, European, and Middle Eastern jurisdictions must maintain parallel ASME, EN, and API code qualifications, inflating training and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NDT and Inspection Market |
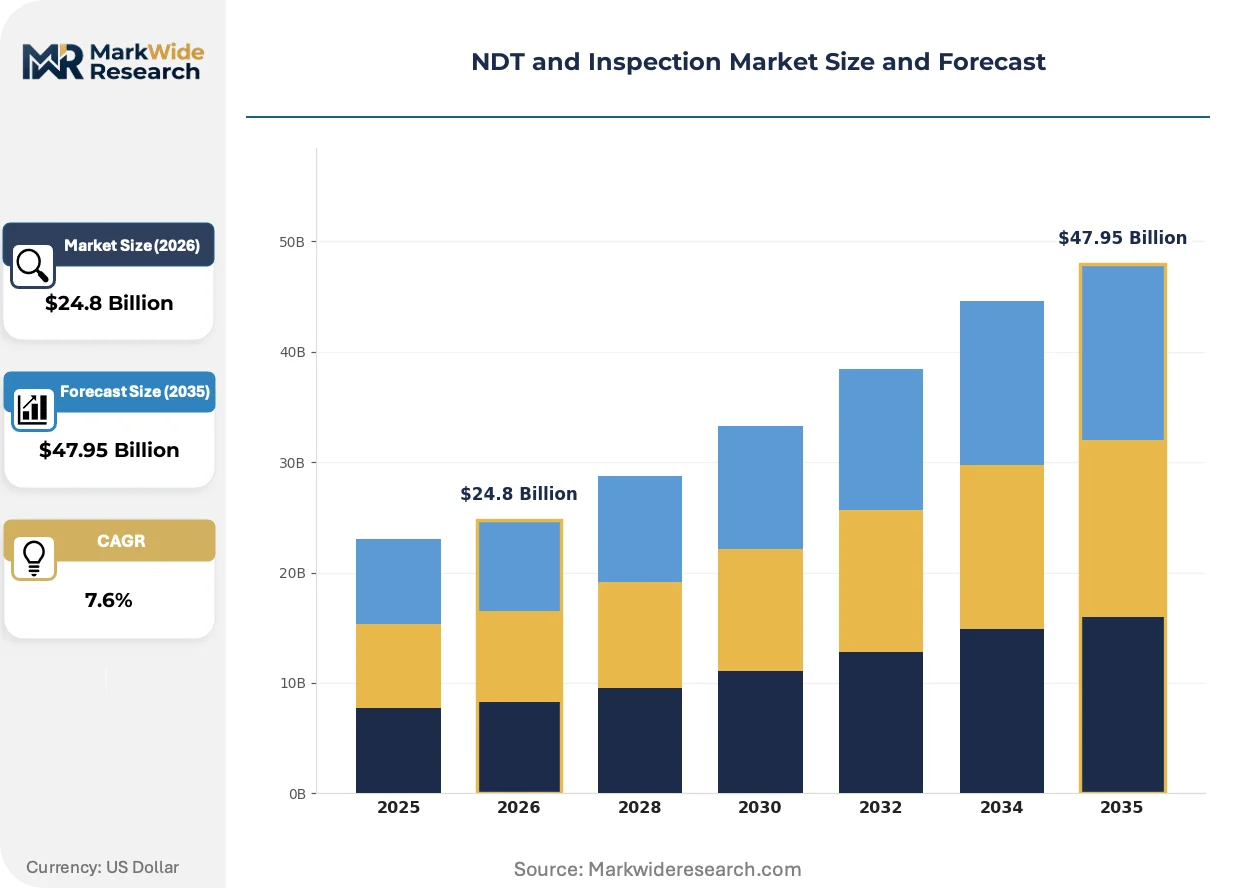
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, Ultrasonic, Magnetic Particle, Liquid Penetrant Application: Aerospace, Manufacturing, Oil & Gas, Construction End User: Energy, Automotive, Defense, Infrastructure Service Type: Inspection, Consulting, Compliance, Training |
| Companies Covered | SGS SA, Bureau Veritas, Applus+, Baker Hughes Company, Intertek Group plc, Olympus Corporation, MISTRAS Group, Ashtead Technology, Waygate Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NDT and Inspection Market Trends and Innovations
Inspection hardware and software architectures are converging toward portable, connected systems that compress the gap between field acquisition and engineering decision-making.
Phased array ultrasonic instrumentation is miniaturizing from cart-based systems to handheld units with embedded beam-forming processors. Pipeline operators in Canada and Australia now deploy backpack-portable units for rapid crack sizing in remote gathering lines. This compression is eliminating the productivity penalty that previously favored radiography in tight-access locations.
The EU AI Act imposes conformity assessment requirements on machine-learning defect classifiers used in manufacturing quality control. Automated ultrasonic testing vendors must now document training data provenance and algorithmic performance metrics for notified body review. Medical device and aerospace casting inspection segments face the steepest compliance ramps.
Asset owners in oil and gas are unbundling inspection scope from integrated maintenance contracts, awarding discrete testing packages to specialized NDT contractors on fixed-price deliverables. This disintermediation compresses margins for full-service engineering firms while creating volume opportunities for technology-focused inspection pure-plays. The shift is most advanced in Norwegian North Sea operations and US onshore shale processing facilities.
NDT and Inspection Market Segmentation
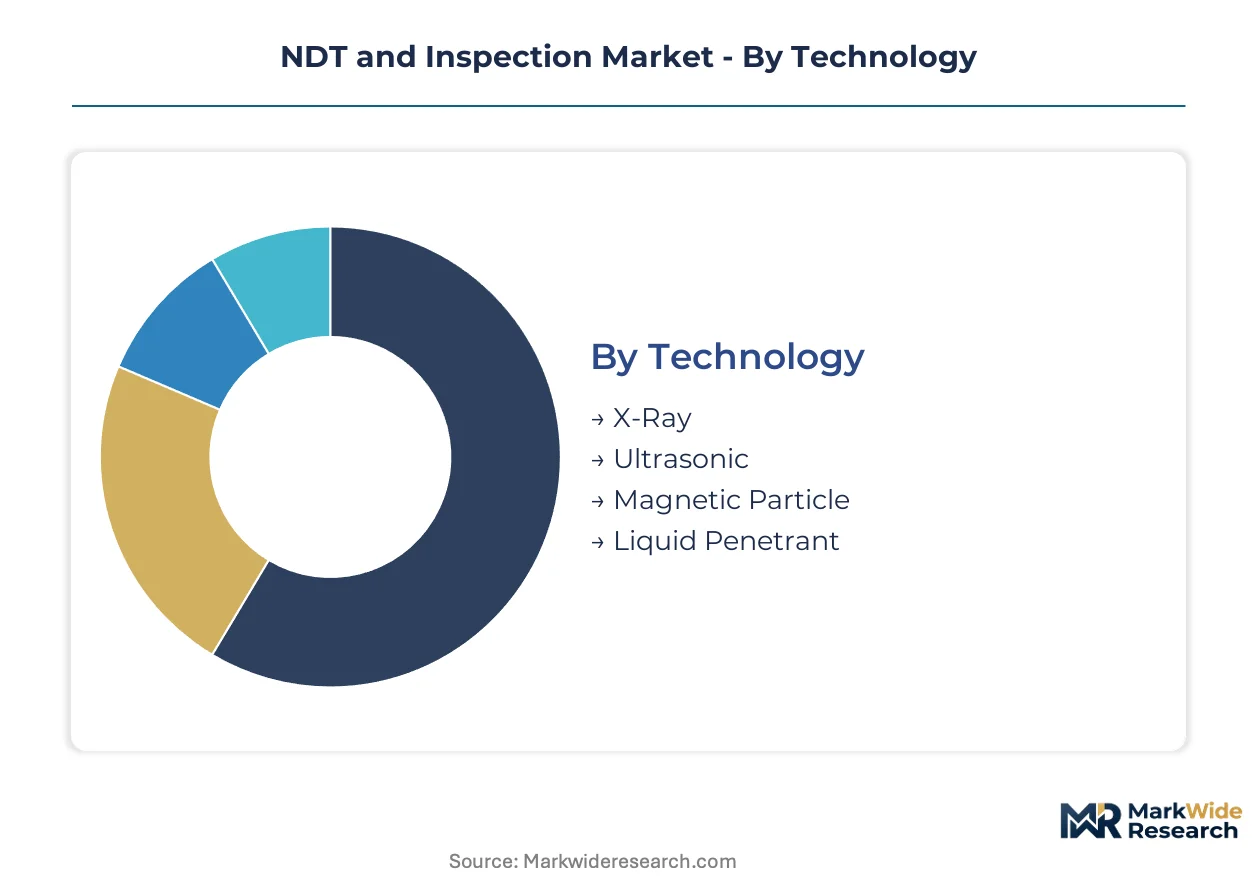
Technology selection in NDT and Inspection hinges on material thickness, defect type, and access constraints. Application mix shifts with capital cycle timing in heavy industry. End-user concentration and service bundling strategies determine margin capture across the value chain.
Technology:
X-Ray and ultrasonic deployments split between domestic maintenance programs and export-led equipment sales to offshore markets.
- Ultrasonic:Phased array systems emit steerable high-frequency sound beams to map internal flaws in thick-section steel and composite laminates. Gulf Coast refineries deploy portable units during pressure vessel turnarounds, compressing inspection windows from days to hours. Magnetic particle testing retains cost advantage for surface-breaking crack detection in field welds.
- X-Ray:Digital radiography flat-panel detectors capture subsurface porosity and inclusion patterns in aerospace castings and pipeline girth welds. FAA-mandated airworthiness evaluations sustain recurring demand across North American MRO networks. Film-based radiography persists in jurisdictions with slower digital adoption.
- Magnetic Particle:Ferromagnetic surface inspection using magnetic field disruption and visible or fluorescent particle suspension.
- Liquid Penetrant:Capillary-action dye penetration for non-porous material surface defect detection in precision manufacturing.
Ultrasonic commands the established base. The steepest expansion runs through X-Ray.
Application:
Cost tier stratification separates capital-intensive aerospace programs from price-sensitive construction contracts.
- Oil & Gas:Pipeline integrity management and refinery turnaround schedules generate the highest per-contract inspection values. PHMSA regulations mandate recurring corrosion mapping across US transmission networks. Brazilian pre-salt development drives subsea automated ultrasonic testing demand.
- Aerospace:Turbine blade casting verification and airframe structural health monitoring require radiographic and ultrasonic protocols under FAA airworthiness directives. OEMs and tier suppliers maintain captive inspection capacity for new production while outsourcing MRO testing.
- Manufacturing:In-process weld monitoring and finished goods quality assurance across automotive and industrial equipment production.
- Construction:Structural steel weld inspection and concrete integrity assessment for commercial and infrastructure projects.
Oil & Gas anchors revenue concentration. Aerospace delivers the steepest expansion trajectory.
End User:
Customer type differentiation separates asset owners with captive inspection teams from outsourced service dependence.
- Energy:Power generation utilities and renewable asset operators balance physical inspection frequency against sensor-based condition monitoring substitution. Nuclear licensees maintain specialized radiographic protocols under NRC oversight.
- Defense:Military airframe and naval vessel programs require ASNT Level III certified personnel for critical component evaluation. Classification societies and government quality assurance offices enforce multi-standard compliance.
- Automotive:Powertrain and chassis weld inspection for production line quality gates and recall-driven forensic analysis.
- Infrastructure:Bridge, tunnel, and transportation asset integrity programs for public agency and concession operator portfolios.
Energy holds the deepest inspection penetration. Defense shows the steepest contract value expansion.
Service Type:
Margin structure varies with labor intensity and certification barriers across the service stack.
- Inspection:Field execution of testing protocols using owned or rented equipment, priced per man-hour or per weld length. Norwegian North Sea operators now unbundle inspection from integrated maintenance contracts, awarding discrete testing packages on fixed-price deliverables.
- Compliance:Third-party certification and regulatory documentation for ASME, API, and EN code adherence. Notified body relationships and accreditation maintenance create defensible positioning.
- Consulting:Risk-based inspection program design and asset integrity management strategy development.
- Training:ASNT and ISO 9712 qualification preparation for radiographic film interpreters and ultrasonic phased array technicians.
Inspection commands volume scale. Compliance delivers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States Gulf Coast petrochemical corridor, where refinery turnaround cycles command premium inspection rates, while German pipeline operators extract volume discounts through multi-year integrity management frameworks.
United States
The FAA mandates recurring structural evaluation for commercial aircraft fleets, sustaining ultrasonic and radiographic testing spend across North American aerospace maintenance networks. OSHA enforces workplace exposure limits that drive radiographic testing protocol upgrades. Houston anchors the Gulf Coast petrochemical corridor, where pressure vessel inspection during scheduled maintenance windows generates recurring contract value.
Germany
Pipeline integrity programs across Germany are displacing conventional radiography with automated ultrasonic corrosion mapping systems. The EU AI Act imposes conformity assessment requirements on machine-learning defect classifiers used in manufacturing quality control. The Ruhr industrial region concentrates demand for weld inspection services serving automotive and heavy machinery producers.
Brazil
Pre-salt field development creates demand for subsea automated ultrasonic testing and remotely operated inspection vehicles in deepwater production infrastructure. ANVISA regulates medical device inspection requirements for manufacturers adopting metal additive manufacturing. The Santos Basin offshore cluster drives specialized inspection contractor deployment for riser and flowline integrity programs.
Japan
METI oversight of energy infrastructure safety accelerates phased array ultrasonic deployment in nuclear and thermal power generation assets. JIS standards govern non-destructive testing protocols for steel structures and pressure equipment. The Chubu industrial corridor around Nagoya sustains captive inspection capacity among automotive tier suppliers.
Saudi Arabia
SFDA frameworks for medical device manufacturing quality assurance drive computed tomography verification demand for implant producers. The country's national oil company maintains extensive in-house inspection capabilities for upstream and downstream assets. The Eastern Province industrial cities of Jubail and Yanbu concentrate third-party inspection contractor activity around petrochemical complex expansion.
NDT and Inspection Market Competitive Landscape
Concentration sits with diversified testing and certification conglomerates that anchor global footprints through accredited laboratory networks. The vendor base spans three tiers: integrated oilfield service providers with captive inspection divisions, pure-play NDT specialists competing on technician certification density, and equipment manufacturers monetizing hardware through rental and service bundling. Strategic moves center on M&A to acquire ASNT Level III technician pools and technology licensing partnerships to embed automated defect recognition software.
Among European-based testing and certification groups, Bureau Veritas, SGS SA, and Intertek Group plc exemplify the diversified conglomerate archetype. These entities compete on turnaround speed for oil and gas certification while maintaining parallel ASME, EN, and API code qualifications across multiple jurisdictions. Their positioning derives from notified body relationships and accreditation maintenance rather than proprietary hardware differentiation.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| Applus+ |
| Baker Hughes Company |
| Intertek Group plc |
| Olympus Corporation |
| MISTRAS Group |
| Ashtead Technology |
| Waygate Technologies |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for phased array ultrasonic transducers concentrate supply leverage in Japanese and German component manufacturers, compressing margin capture for mid-size inspection contractors while amplifying pricing power for vertically integrated equipment vendors. This inventory bandwidth shapes how service providers structure rental-versus-ownership decisions and how asset owners negotiate bundled inspection packages.
Pricing Analysis
The customization-premium spread separates configured-to-order phased array systems from standard portable units, with project-based pricing dominating discrete inspection contracts and subscription-tiered models emerging for automated defect recognition software. Price differentiation hinges on ASNT Level III certification density and ISO 9712 compliance grade, with Gulf Coast petrochemical operators showing lowest price sensitivity due to regulatory-mandated turnaround windows. Cost compression in standard ultrasonic equipment is intensifying because of Chinese manufacturing scale, while premium digital radiography systems retain margin resilience through FAA airworthiness directive stickiness.
Supply Chain Analysis
Inventory concentration for piezoelectric ceramic substrates and digital flat-panel detectors sits with suppliers in Japan, Germany, and the United States, creating procurement vulnerability for mid-tier inspection contractors. Raw material dependencies include specialized acoustic coupling gels, tungsten radiation shielding, and high-purity scintillator crystals. Single-source vulnerability runs through Japanese suppliers of precision-machined phased array wedges. Distribution runs through authorized equipment distributors and rental fleet operators serving regional oilfield service clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
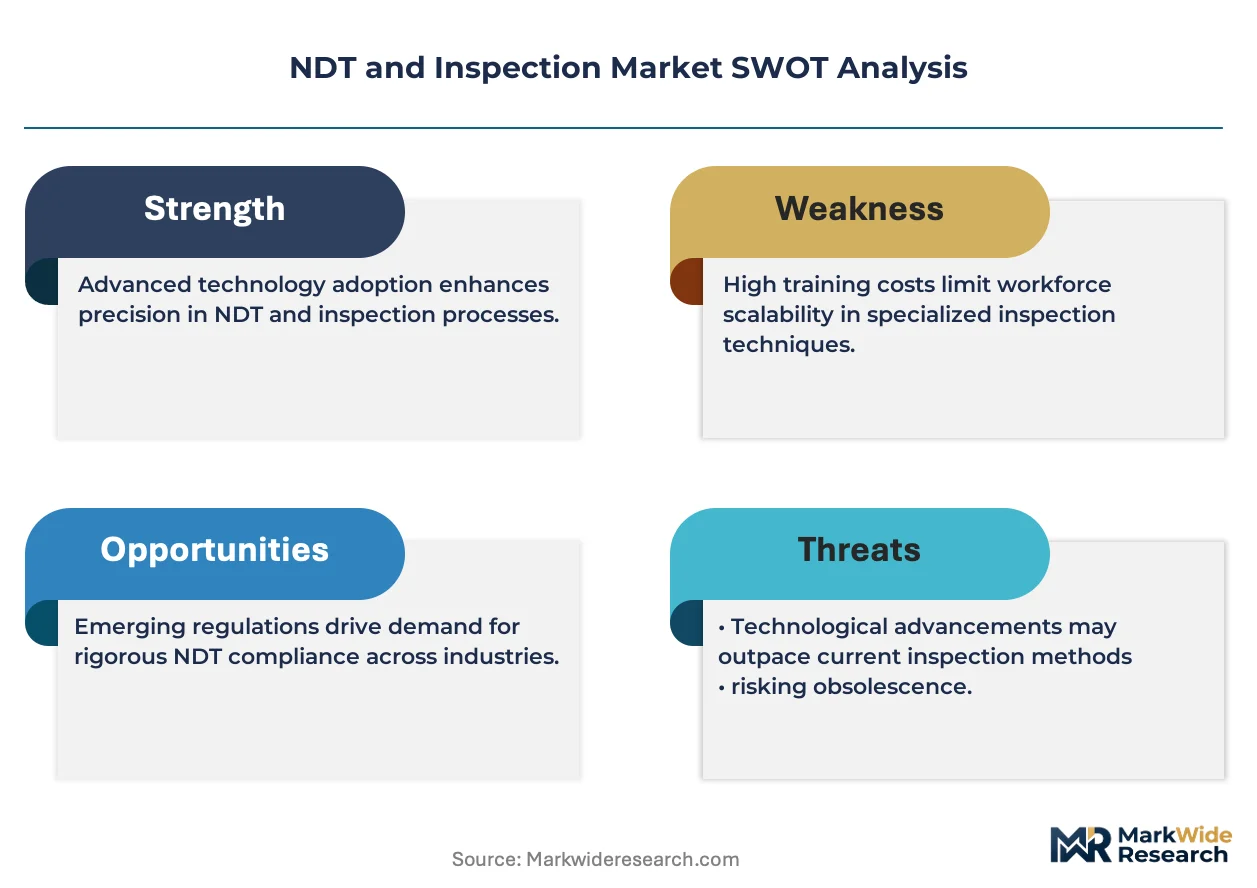
The NDT and Inspection market sits at a platform-economics inflection where automated defect recognition software must interoperate with enterprise asset management systems like SAP and IBM Maximo, rewarding vendors who build API-native architectures over point-solution specialists.
For Market Incumbents: Shield technician certification density as a competitive moat by accelerating ASNT Level III training pipelines before demographic retirement peaks erode interpretive capacity. Deepen backward integration into phased array transducer manufacturing to offset supply volatility from Japanese component suppliers. Lock in multi-year integrity management frameworks with Norwegian North Sea and US Gulf Coast operators before disintermediation trends fragment contract scope.
For New Entrants and Emerging Players: Anchor in Brazilian pre-salt offshore inspection as the most penetrable geography, where subsea automated ultrasonic testing demand outpaces established contractor capacity. Target EU AI Act compliance services for automated weld inspection as a white-space segment where explainable AI architectures create first-mover advantage. Pursue partnerships with additive manufacturing equipment OEMs to embed in-process monitoring capabilities before post-build verification becomes commoditized.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because inspection data management platforms will aggregate toward vendors with enterprise software integration depth, compressing standalone hardware margins. Prioritize acquisition targets with dense ASNT Level III technician pools and existing notified body relationships across ASME, EN, and API jurisdictions. Watch for inflection when Brazilian offshore inspection contract awards accelerate beyond incumbent service capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Technician Pools | Dense ASNT Level III certification networks create defensible positioning in ultrasonic phased array deployment. |
| Platform Integration with EAM Systems | API-native architectures for SAP and IBM Maximo interoperability capture inspection data management consolidation. |
| EU AI Act Compliance Investment | Explainable automated defect recognition software secures notified body approval ahead of algorithmic transparency mandates. |
| Subsea Equipment Localization | Brazilian pre-salt field development demands remotely operated inspection vehicles beyond incumbent capacity. |
| Additive Manufacturing Partnership | In-process monitoring and post-build CT verification open service lines for aerospace and medical implant producers. |
Research Methodology
Cross-validation between primary interviews with NDT service directors, asset integrity managers at Gulf Coast refineries, and FAA certification specialists anchors the qualitative findings, while secondary validation draws from PHMSA pipeline safety filings, ASNT membership databases, and equipment import customs records. Bottom-up triangulation aggregates contract-level inspection spend patterns across oil and gas turnaround schedules, while top-down calibration references petrochemical maintenance capex disclosures and aerospace MRO network expansions.
Sensitivity analysis around technician availability constraints and equipment replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application vertical, service delivery model, and end-user captive-versus-outsourced sourcing pattern. CAGRs derive from regression against historical turnaround frequency and regulatory mandate expansion, with specific inputs including FAA airworthiness directive issuance rates and PHMSA pipeline integrity management enforcement intensity.
Material uncertainties — certified technician retirement velocity, EU AI Act implementation timelines, and Brazilian offshore project sanctioning decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and equipment substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
North America Repair and Rehabilitation Market
Construction Services
MENA Architectural Services Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Hardbanding Services Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Industrial Maintenance Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Global Industrial Services Market
Construction Services
Train Contractor Market