
 Europe Engineering Research and Development (ER&D) Services Market | 2026-2036
Europe Engineering Research and Development (ER&D) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Engineering Research and Development (ER&D) Services Market Insights
The shift from captive in-house engineering to multi-source outsourced delivery is hardening across European manufacturing. Capgemini SE leverages its deep automotive heritage to anchor complex systems integration programs for German OEMs. Alten competes through specialized embedded software talent pools concentrated in France and Italy. Akkodis differentiates by merging IT and engineering capabilities under a unified workforce model.
Europe Engineering Research and Development (ER&D) Services encompass the full lifecycle of technical innovation outsourced by industrial enterprises, spanning conceptual design, computer-aided engineering, physical prototyping, systems testing, and product lifecycle management through integrated PLM Solutions platforms. These services enable OEMs to compress development cycles while accessing specialized simulation and digital-twin competencies without permanent headcount expansion. Design Services currently occupies the largest revenue pool as automotive and aerospace clients outsource styling, CAD modeling, and ergonomic validation. IoT-enabled engineering workflows represent the fastest-expanding technology segment as connected-product requirements reshape testing protocols. Consulting engagements around regulatory compliance and sustainability certification are emerging as high-margin adjacencies.
EMA medical device standards, REACH chemical safety frameworks, and the EU AI Act's conformity requirements are collectively elevating documentation and verification burdens across engineering workflows. ECHA substance restrictions and CE marking obligations now penetrate earlier design stages, forcing ER&D providers to embed compliance expertise directly into technical teams. Stakeholders must monitor how CSRD disclosure mandates redirect R&D budgets toward traceable sustainability metrics rather than purely performance-driven specifications.
Market Dynamics
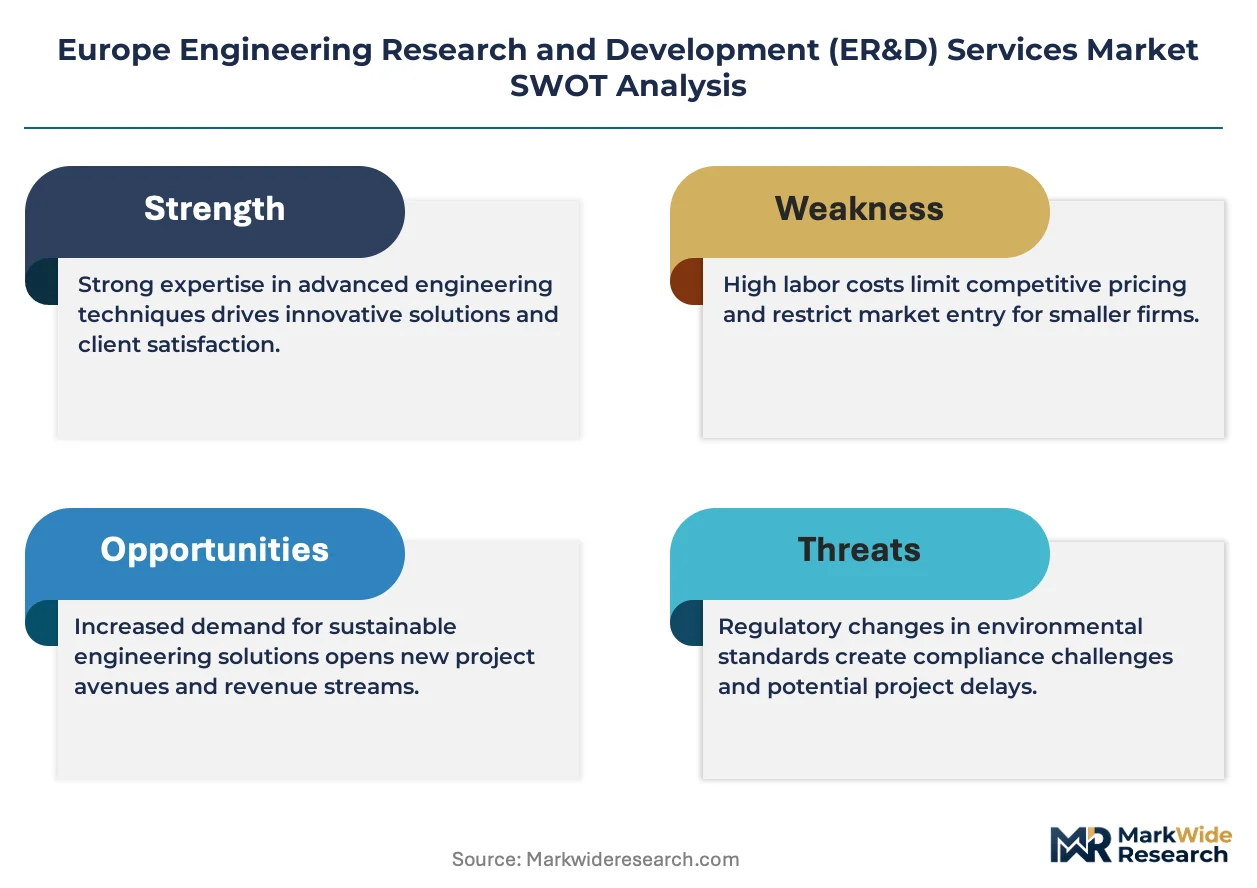
Automotive OEMs across Germany and France are accelerating outsourced engineering partnerships as the EU AI Act and REACH compliance tighten product development standards, forcing ER&D providers to embed regulatory expertise directly into technical teams rather than treating compliance as a post-design checkpoint.
Growth Catalysts
- EU AI Act conformity requirements:The regulation's risk-based classification system for AI-enabled products is expanding verification and documentation mandates across automotive and medical device engineering workflows, creating sustained demand for specialized compliance-integrated ER&D services.
- Automotive electrification programs:German OEMs in Munich, Stuttgart, and Wolfsburg are outsourcing battery thermal management and power electronics design to compress development cycles for next-generation electric vehicle platforms.
- IoT-enabled engineering workflows:Connected-product requirements are reshaping testing protocols and accelerating adoption of digital-twin competencies across aerospace and industrial equipment sectors.
Market Restraints
- Specialized embedded software talent scarcity:Concentrated talent pools in France and Italy create supply bottlenecks for complex systems integration programs, inflating labor costs and extending project timelines.
- REACH substance restriction compliance costs:ECHA's evolving restricted substance lists force repeated redesign cycles and material substitutions, eroding margin predictability for fixed-price engineering contracts.
- CSRD disclosure mandate complexity:The Corporate Sustainability Reporting Directive's traceable sustainability metrics requirements are redirecting R&D budgets away from performance-driven specifications toward documentation-heavy verification processes.
Strategic Opportunities
- Italy's underpenetrated industrial engineering corridor:Northern manufacturing clusters around Turin and Milan present expansion potential for ER&D providers seeking geographic diversification beyond saturated German markets.
- Digital-twin convergence with PLM platforms:Unified simulation and lifecycle management environments are enabling new service bundles that merge conceptual design with real-time performance optimization for aerospace clients.
- EMA medical device standards harmonization:The Medical Device Regulation's consolidated conformity pathways are creating compliance-as-a-service adjacencies for ER&D firms with embedded regulatory expertise.
Industry Challenges
- CE marking timeline compression:Earlier-stage integration of conformity assessment requirements is extending front-end engineering phases and complicating milestone-based contract structures.
- Multi-source delivery integration complexity:The shift from captive in-house engineering to fragmented outsourced models is creating coordination overhead and IP fragmentation risks across distributed technical teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Engineering Research and Development (ER&D) Services Market |
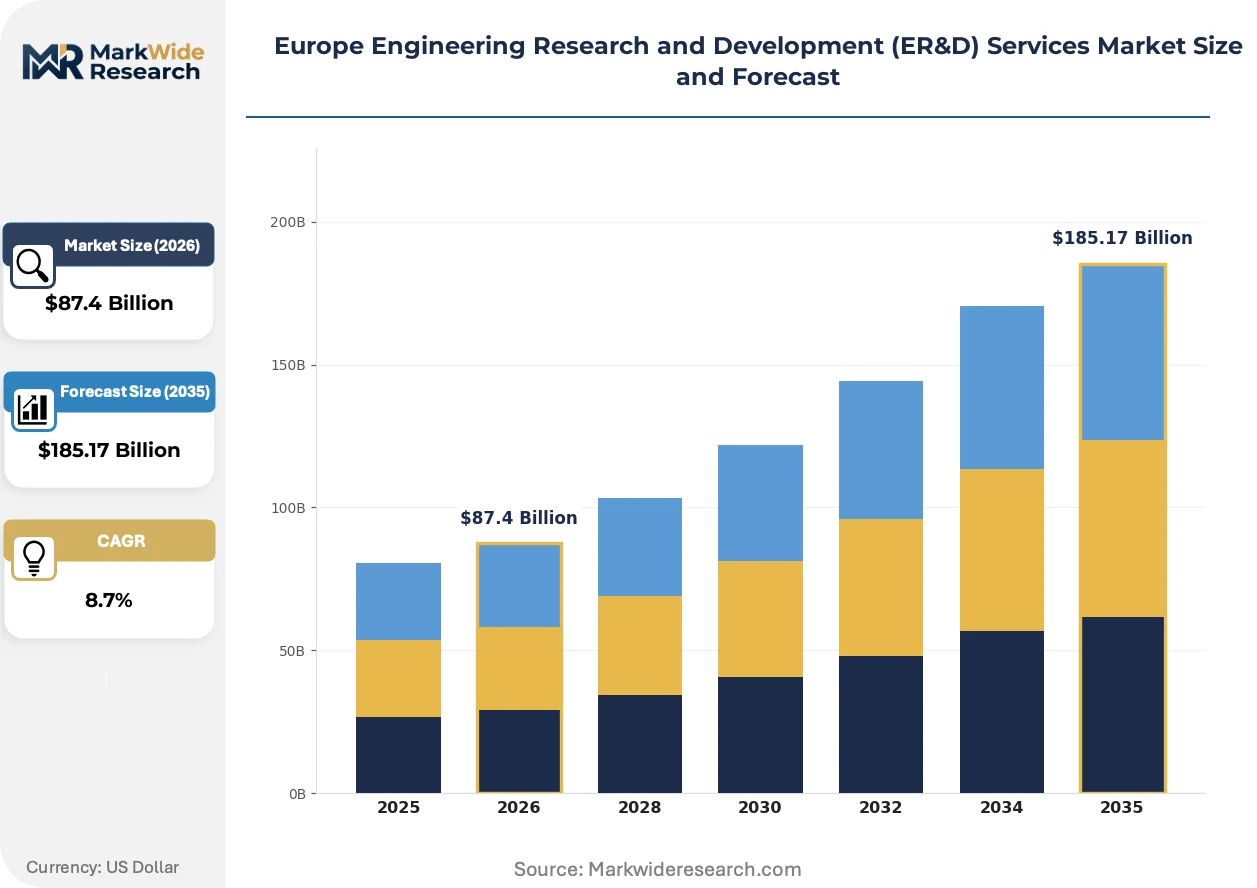
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Prototyping, Consulting, Testing End User: Aerospace, Automotive OEMs, Electronics, Healthcare Technology: Simulation Software, CAD Software, PLM Solutions, IoT Industry Vertical: Manufacturing, Telecommunications, Energy, Construction |
| Companies Covered | Capgemini SE, Alten, Akkodis, Cyient, Infosys, HCL Technologies, Wipro, Tata Consultancy Services, AKKA Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Engineering Research and Development (ER&D) Services Market Trends and Innovations
Digital-twin technology is electrifying traditional engineering workflows by merging physical prototyping with real-time simulation, compressing validation cycles and enabling predictive performance optimization across European automotive and aerospace programs.
Digital-twin platforms integrate sensor data, physics-based modeling, and machine learning to create persistent virtual representations of physical assets. Automotive OEMs in Germany's industrial corridor are deploying these systems for battery pack thermal validation and chassis durability testing. This convergence is electrifying competitive positioning by enabling ER&D providers to deliver outcome-based performance guarantees rather than discrete engineering deliverables.
The EU AI Act's risk-based conformity framework is mandating algorithmic transparency and human oversight documentation for AI-enabled engineering tools. Medical device and automotive clients must now embed explainability requirements into automated design optimization systems. France and Germany are seeing the earliest enforcement activity, with notified bodies demanding detailed technical documentation for machine-learning-assisted simulation software.
Fixed-price engineering contracts are giving way to gain-share arrangements tied to product performance metrics or time-to-market outcomes. Tier-one automotive suppliers in Stuttgart and Wolfsburg are piloting these models for powertrain development programs. This restructuring is most visible in Germany, where procurement teams are unbundling design services from verification to align vendor incentives with production launch success.
Europe Engineering Research and Development (ER&D) Services Market Segmentation
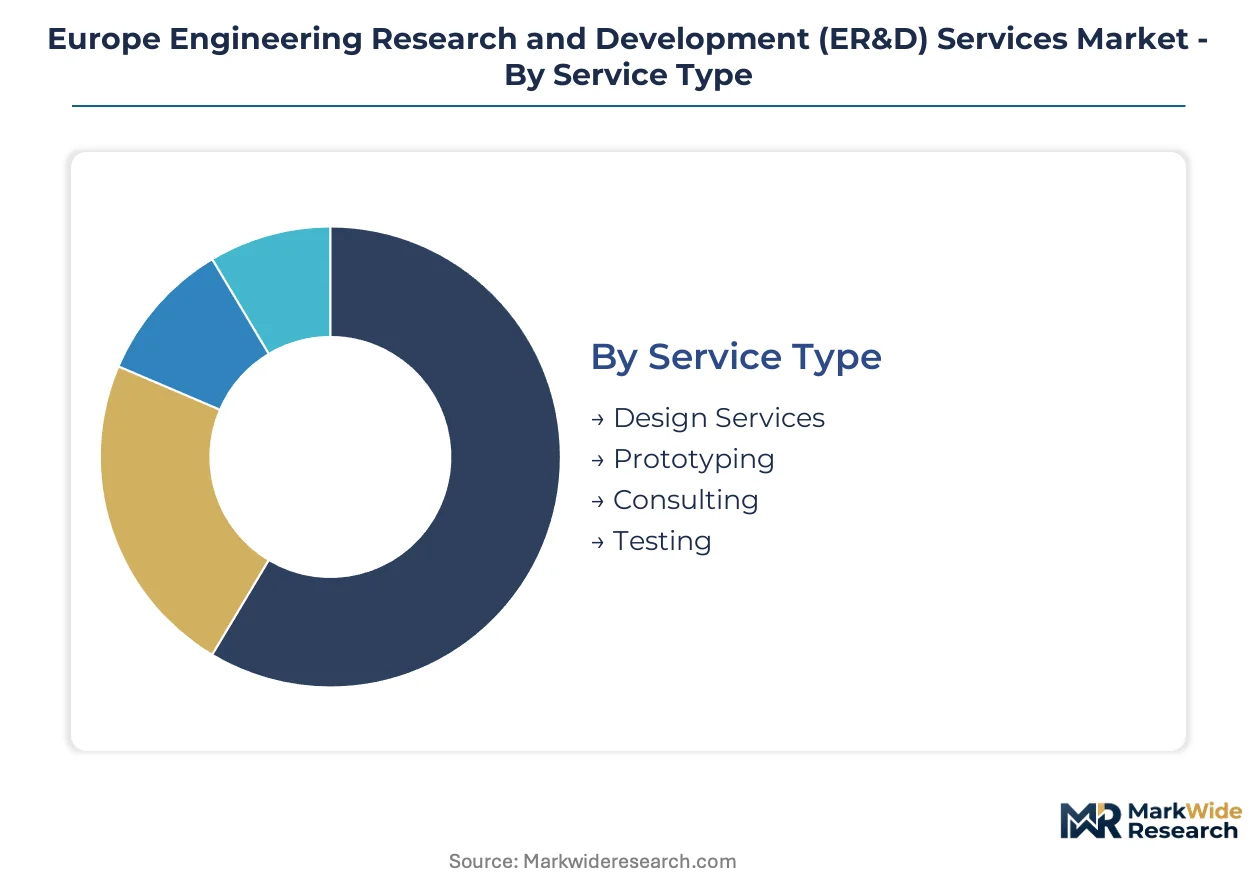
European ER&D procurement decisions hinge on whether clients prioritize speed-to-compliance, specialized technical depth, or integrated lifecycle coverage. Segment boundaries increasingly blur as providers bundle design, simulation, and regulatory verification into unified service architectures.
Service Type:
Client selection among service types tracks directly to where internal engineering gaps sit heaviest—conceptual design capacity, physical validation infrastructure, or regulatory documentation expertise.
- Design Services:Encompasses styling, CAD modeling, ergonomic validation, and conceptual engineering. German automotive OEMs in Stuttgart and Wolfsburg outsource styling and surfacing work to compress early-phase timelines for electric vehicle platforms. REACH substance restrictions now force material selection decisions into initial design sprints rather than downstream engineering phases.
- Prototyping:Covers physical model creation, rapid manufacturing, and functional mock-up validation. Aerospace clients in France leverage additive manufacturing capabilities for turbine component testing before committing to production tooling. Thermal management prototypes for battery systems command premium pricing due to specialized equipment requirements.
- Consulting:Regulatory compliance advisory, sustainability certification support, and technology roadmap planning. EU AI Act conformity documentation and CSRD traceability mandates are expanding this segment fastest among medical device and automotive clients.
- Testing:Physical validation, durability assessment, environmental simulation, and certification support. CE marking timeline compression is extending testing phases earlier into development cycles, complicating fixed-price contracting.
Design Services leads on scale; Consulting leads on momentum.
End User:
End-user concentration reflects where product complexity, regulatory burden, and compressed development cycles create the strongest outsourcing economics.
- Automotive OEMs:Full-vehicle and powertrain engineering programs across electrification, autonomous systems, and lightweighting initiatives. Munich, Stuttgart, and Wolfsburg clusters are outsourcing battery thermal management and power electronics design to specialized ER&D partners.
- Aerospace:Airframe structures, propulsion systems, and avionics integration for commercial and defense programs. Digital-twin adoption is deepest here, with unified simulation environments compressing certification timelines.
- Electronics:Embedded systems, semiconductor packaging, and connected-device engineering. IoT-enabled product requirements are reshaping testing protocols and accelerating demand for hardware-software co-design capabilities.
- Healthcare:Medical device design, diagnostic equipment engineering, and regulatory submission support. EMA Medical Device Regulation harmonization is creating compliance-as-a-service demand for ER&D providers with embedded regulatory expertise.
Automotive OEMs anchor volume commitment; Healthcare shows steepest expansion trajectory.
Technology:
Technology stack decisions determine whether ER&D engagements deliver discrete engineering outputs or outcome-based performance guarantees tied to production success.
- Simulation Software:Physics-based modeling, finite element analysis, and computational fluid dynamics tools. German automotive clients deploy these for chassis durability and crashworthiness validation without physical prototype iterations.
- CAD Software:Computer-aided design platforms for geometric modeling, assembly definition, and manufacturing documentation. PLM-integrated CAD environments enable real-time collaboration between OEM engineering teams and external service providers.
- PLM Solutions:Product lifecycle management platforms unifying design data, change control, and supplier collaboration. Aerospace programs in France and Germany are consolidating fragmented toolchains into unified environments to reduce IP fragmentation risks.
- IoT:Connected-product engineering, sensor integration, and edge computing architecture. This segment is gaining share fastest as industrial equipment and automotive clients embed connectivity requirements into core product specifications.
Simulation Software captures the largest implementation base; IoT is climbing the fastest.
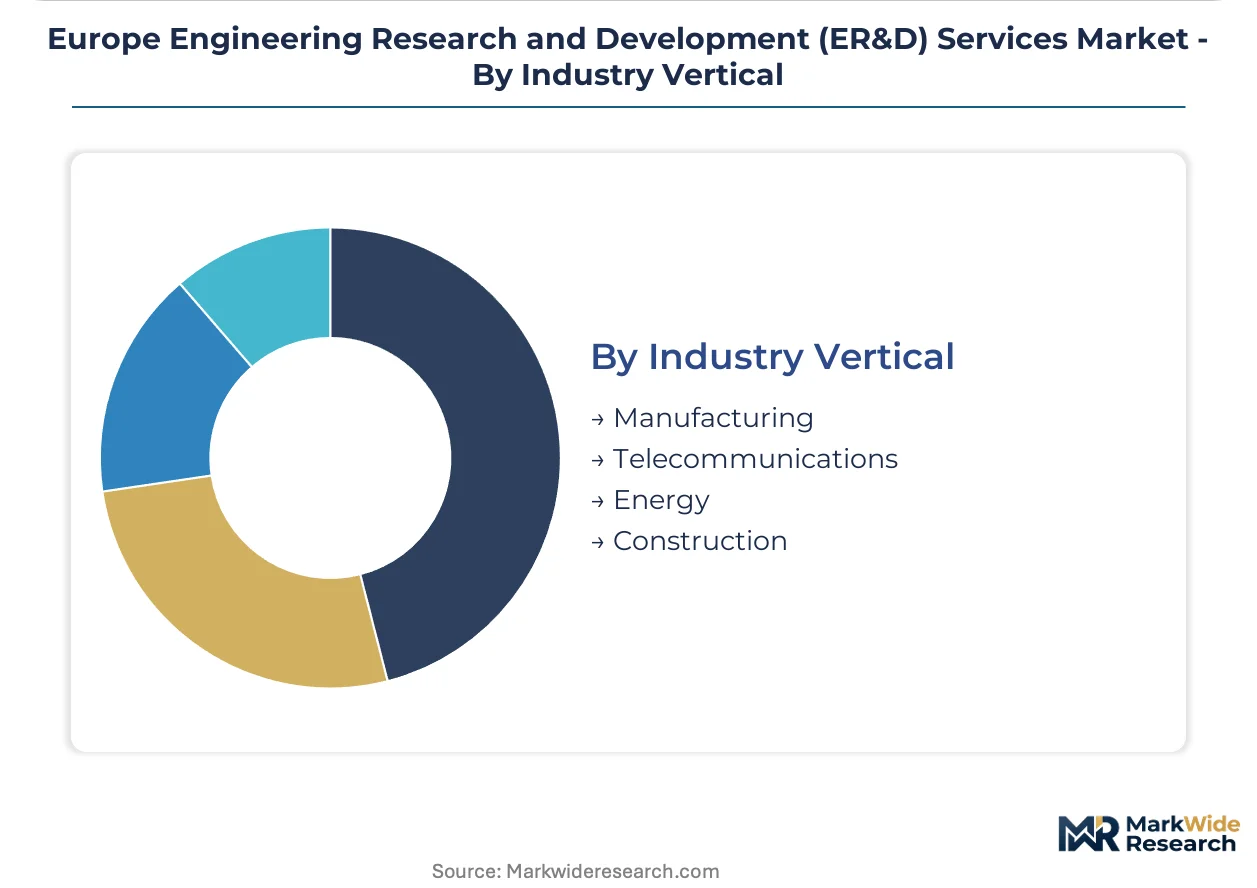
Industry Vertical:
Vertical targeting reflects where capital equipment intensity and regulatory compliance burdens make captive engineering capacity most expensive to maintain.
- Manufacturing:Industrial machinery, automation systems, and production equipment engineering. Northern Italian manufacturing clusters around Turin and Milan present expansion opportunities for providers seeking geographic diversification beyond saturated German markets.
- Energy:Renewable generation systems, grid infrastructure, and energy storage engineering. EU Green Deal implementation timelines are accelerating outsourced R&D for hydrogen and offshore wind technologies.
- Telecommunications:Network infrastructure, antenna systems, and spectrum-efficient hardware design. 5G deployment schedules are compressing development cycles for base station and terminal equipment.
- Construction:Building systems, materials engineering, and infrastructure digitization. Sustainability certification requirements are embedding lifecycle assessment capabilities into structural and MEP design services.
Manufacturing dominates current revenue contribution; Energy shows strongest forward commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor spanning Munich, Stuttgart, and Wolfsburg commands the dominant share of European ER&D demand, with automotive electrification programs and REACH compliance mandates driving procurement intensity across the continent.
Germany
Automotive OEMs in Munich, Stuttgart, and Wolfsburg outsource battery thermal management and power electronics design to compress electric vehicle development cycles. KBA vehicle certification requirements and EU AI Act conformity mandates force earlier integration of regulatory expertise into technical teams. The Stuttgart metropolitan area concentrates specialized embedded software talent pools serving powertrain electrification programs.
France
Aerospace and defense engineering programs in Toulouse and Paris leverage digital-twin platforms for airframe certification and propulsion system validation. ANSM medical device standards and EMA harmonization pathways create compliance-as-a-service demand for diagnostic equipment engineering. The Île-de-France region anchors complex systems integration capabilities for avionics and connected-product development.
United Kingdom
Automotive and industrial equipment clients in the Midlands and Southeast England procure outsourced simulation and prototyping services to address internal capacity gaps. Post-Brexit regulatory divergence from EU REACH frameworks complicates material compliance documentation for cross-border engineering programs. The West Midlands manufacturing cluster sustains demand for powertrain and chassis engineering partnerships.
Italy
Northern manufacturing clusters around Turin and Milan present expansion opportunities for ER&D providers seeking geographic diversification beyond saturated German markets. ECHA substance restriction updates force repeated redesign cycles for industrial machinery and automation equipment producers. The Piedmont region's automotive heritage supports specialized prototyping capabilities for European OEM supply chains.
Spain
Automotive component suppliers in Catalonia and the Basque Country accelerate outsourced engineering partnerships for electrification and lightweighting initiatives. CE marking timeline compression extends front-end engineering phases, complicating milestone-based contract structures. The Barcelona metropolitan area develops connected-vehicle and IoT-enabled product engineering competencies for Mediterranean-market clients.
Europe Engineering Research and Development (ER&D) Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized embedded software and regulatory-integrated delivery models. The vendor base stratifies across three tiers: global IT consultancies with automotive heritage, European pure-play engineering specialists, and India-headquartered technology services firms. Three strategic archetypes dominate: compliance-integrated systems integrators, digital-twin platform operators, and embedded software talent aggregators. Competitive intensity centers on M&A activity targeting specialized automotive and aerospace competencies, alongside strategic partnerships unifying IT and engineering workforces under single delivery models.
Within the European pure-play tier, Alten and AKKA Technologies exemplify specialized engineering talent aggregation strategies concentrated in France and Italy. Capgemini SE anchors the IT-consultancy-integrated segment, merging technology services with deep automotive heritage. Among India-headquartered technology services firms, Tata Consultancy Services, Infosys, and HCL Technologies occupy positions emphasizing scale-driven delivery and digital engineering capabilities. These three archetypes represent the competitive structure without implying specific strategic actions or market positions for individual entities.
| Leading Market Players |
|---|
| Capgemini SE |
| Alten |
| Akkodis |
| Cyient |
| Infosys |
| HCL Technologies |
| Wipro |
| Tata Consultancy Services |
| AKKA Technologies |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up engineering specialists across France and Germany have consolidated fragmented embedded software talent pools, tightening pricing discipline while compressing margin buffers for fixed-price delivery contracts. This ownership concentration feeds directly into supply behavior, as portfolio companies prioritize recurring revenue streams over project-based engagements to service debt obligations and demonstrate exit readiness to sponsors.
Pricing Analysis
Input-cost pass-through from scarce embedded software talent in France and Italy is forcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade (ISO 26262 automotive functional safety, CE marking support) and geographic delivery cost (onshore German engineering commands 40-60% premiums over nearshore Eastern European delivery). Pricing pressure stems from REACH substance restriction compliance costs eroding margin predictability. Tier-one automotive OEMs in Stuttgart show least price sensitivity for regulatory-integrated programs; mid-tier industrial machinery producers in Northern Italy exhibit highest price elasticity.
Supply Chain Analysis
Reverse-logistics flows for prototyping equipment and simulation hardware refurbishment center on Germany, France, and Poland as primary recovery nodes. The supply chain draws from specialized semiconductor components (automotive-grade MCUs, power electronics), high-performance computing infrastructure, and rare earth materials for sensor manufacturing. Single-source vulnerability concentrates in French and Italian embedded software talent pools for functional safety engineering. Distribution runs through direct OEM procurement teams in Munich and Stuttgart, supplemented by tier-one supplier channel partnerships for mid-market industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European ER&D services constitute a late-cycle quality story as automotive and medical device clients prioritize premium specifications embedding EU AI Act conformity and REACH traceability over pure cost optimization. This demand-shift rewards providers with embedded regulatory expertise and penalizes commodity engineering shops.
For Market Incumbents: Deploy certification investment as the primary lever. Incumbents should deepen functional safety credentials (ISO 26262, IEC 61508) to defend against India-headquartered technology services firms scaling automotive practices. Acquire specialized embedded software boutiques in Turin and Milan to secure talent pipelines before competitors consolidate remaining independent pools. Capacity addition in Poland and Romania extends nearshore delivery options without sacrificing regulatory proximity to German OEM decision centers.
For New Entrants and Emerging Players: Digital-twin platform specialization offers the clearest technology-first wedge into aerospace programs in Toulouse and Hamburg where incumbent relationships remain sticky but tool modernization cycles create entry windows. Target Italy's underpenetrated industrial engineering corridor around Turin and Milan, where family-owned automation equipment producers lack sophisticated PLM-integrated delivery partners. Pursue gain-share contracting models tied to time-to-market outcomes rather than competing on fixed-price engineering rates.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European pure-plays with automotive heritage but limited digital engineering scale. Long-term viability favors providers unifying IT and engineering capabilities under single workforce models as client procurement teams consolidate vendor panels. Acquisition target archetype: France-based embedded software specialists with EMA medical device regulatory expertise. Monitor CSRD disclosure mandate enforcement timelines as early signal for sustainability-integrated R&D budget redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Expertise Embedding | EU AI Act conformity documentation creates compliance-as-a-service revenue streams for EMA-versed providers. |
| Digital-Twin Platform Integration | Unified simulation environments compress certification timelines for KBA vehicle type approval in Germany. |
| Geographic Expansion to Italy | Turin and Milan manufacturing clusters offer diversification beyond saturated Munich-Stuttgart-Wolfsburg corridor. |
| Gain-Share Contracting Models | Outcome-based pricing aligns vendor incentives with Stuttgart OEM production launch success metrics. |
| Talent Pool Consolidation | Embedded software scarcity in France and Italy rewards specialized acquisition strategies over organic hiring. |
Research Methodology
Direct dialogue with ER&D procurement directors at German automotive OEMs, platform engineering leads in France, regulatory affairs specialists at notified bodies, and talent acquisition heads at engineering services firms grounded qualitative findings. Secondary validation drew from KBA type approval databases, ECHA substance restriction updates, EU AI Act implementation guidance, and SEC filings of publicly traded IT services firms. Bottom-up project pipeline analysis across Munich, Stuttgart, and Wolfsburg clusters triangulated against top-down market sizing from national statistical offices.
Segment-level outputs across the analysis window reflect modeled deployment of design, prototyping, consulting, and testing services by automotive, aerospace, electronics, and healthcare end users. Technology segmentation incorporated simulation software, CAD platforms, PLM solutions, and IoT engineering capabilities. CAGRs derived from historical procurement intensity patterns, electrification program announcements, and regulatory compliance burden trajectories. Forecast inputs included battery thermal management outsourcing ratios, digital-twin adoption curves in French aerospace, and REACH substance restriction implementation schedules.
The model holds under steady regulatory enforcement intensity and continued automotive electrification capital commitment; deviation in EU AI Act timeline delays or German OEM insourcing reversals would shift trajectory. Forecasts embed assumptions regarding talent pool mobility and cross-border service delivery friction. Practitioners should monitor ECHA substance list updates and KBA certification backlog indicators for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
North America Engineering Research and Development (ER&D) Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Seismic Services Market
Engineering Services
MEP Services Market