
 Engineering Design Service Market | 2026-2036
Engineering Design Service Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Design Service Market Insights
Outsourced engineering design is rebalancing away from single-source dependencies toward distributed specialist networks. WSP USA leverages its multidisciplinary infrastructure to compete for complex infrastructure programs across North America. Jacobs Solutions Inc. anchors its position through deep integration with defense and energy clients requiring security-cleared design teams. Fluor differentiates by sustaining proprietary modular construction methodologies that compress project timelines for industrial clients.
Engineering design services encompass the technical specification, simulation, and documentation activities required to translate functional requirements into producible systems, typically delivered through CAD platforms, finite-element analysis, and virtual prototyping workflows. These services enable OEMs to externalize specialized expertise without maintaining full-scale internal bureaus across every discipline. Detailed design and product development command the largest share of engagement value, while prototyping represents the fastest-expanding segment as iterative digital-physical validation cycles shorten. Simulation tools and 3D modeling technologies concentrate margin pools where vendors combine software licensing with embedded consulting.
The Federal Aviation Administration in the United States, the European Union Aviation Safety Agency, and Japan's Ministry of Economy, Trade and Industry each impose certification and quality standards that dictate design documentation rigor and traceability requirements for cross-border projects. Compliance with ISO 9001 and sector-specific standards such as AS9100 for aerospace shapes vendor qualification protocols and limits market access for uncertified competitors. Stakeholders must monitor how emerging digital product passport requirements and AI-generated design liability frameworks alter contracting structures and insurance obligations.
Market Dynamics
Generative AI tools are compressing design iteration cycles from weeks to days, forcing engineering service providers to restructure talent models and pricing architectures around automated workflows rather than billable hours.
Growth Catalysts
- EU AI Act:Compliance mandates for algorithmic traceability in automated design systems are creating specialized service demand for documentation and audit-ready engineering workflows.
- Aerospace outsourcing:Commercial aircraft OEMs are expanding external design partnerships to accelerate next-generation propulsion and airframe programs without expanding fixed engineering headcount.
- Distributed manufacturing:Cloud-native CAD and simulation platforms enable real-time collaboration between OEMs in Germany, Japan, and the United States and specialist design bureaus across Eastern Europe and Southeast Asia.
Market Restraints
- Security clearance bottlenecks:Defense and energy sector projects in the United States require personnel with active clearances, limiting supplier pools and extending onboarding timelines.
- Software licensing concentration:Proprietary CAD and finite-element analysis platforms from dominant vendors impose recurring cost structures that erode margins for mid-sized engineering consultancies.
- AS9100 certification barriers:Aerospace qualification protocols require multi-year quality system investments that exclude uncertified competitors from high-value design engagements.
Strategic Opportunities
- Digital product passports:EU regulatory requirements for lifecycle traceability are opening service lines for blockchain-integrated design documentation and material provenance systems.
- India engineering services:Automotive and industrial equipment OEMs are expanding captive centers in Pune and Chennai for cost-advantaged detailed design and simulation work.
- AI-human hybrid workflows:Convergence of generative design algorithms with traditional finite-element validation is enabling new premium service tiers for rapid concept-to-analysis cycles.
Industry Challenges
- Simulation talent scarcity:Shortages of engineers with combined domain expertise in computational fluid dynamics and industry-specific physics are extending project staffing timelines.
- Legacy system integration:Defense and industrial clients maintain decades-old product data management architectures that resist API-based connectivity with modern cloud design platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Design Service Market |
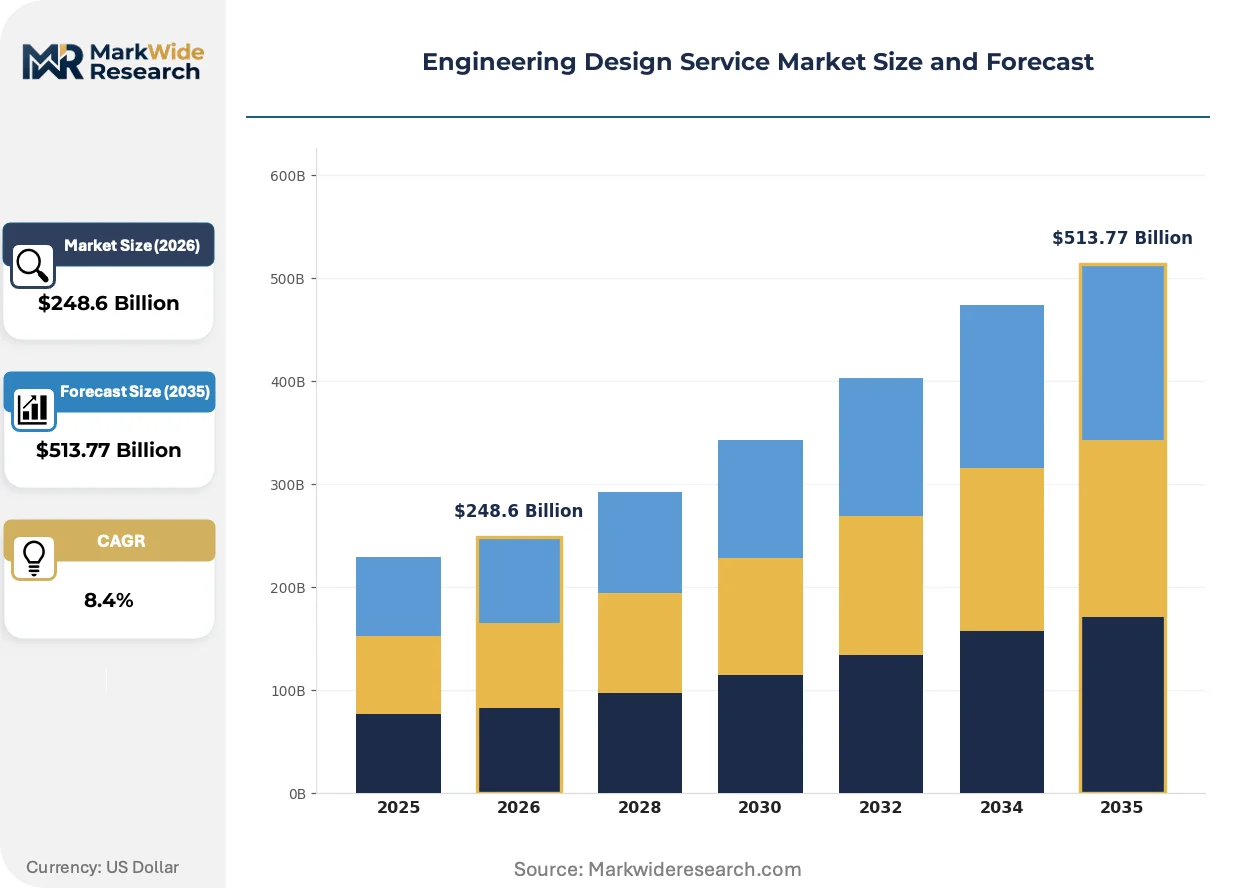
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $513.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Concept Design, Detailed Design, Prototyping, Product Development Industry Vertical: Aerospace, Automotive, Consumer Electronics, Industrial Equipment Technology: CAD Software, Simulation Tools, 3D Modeling, Virtual Reality End User: Startups, SMEs, Large Enterprises, Government Agencies |
| Companies Covered | WSP USA, HDR, AECOM, Kimley-Horn, Burns & McDonnell, Jacobs Solutions Inc., Fluor, Stantec Inc., Tetra Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Design Service Market Trends and Innovations
Computational methods are displacing manual drafting and first-principles calculation across every phase of engineering design, restructuring how expertise is packaged and priced in outsourced engagements.
Generative design software is automating topology optimization and material selection for structural components. Automotive and aerospace manufacturers are embedding these tools into early-stage development programs. The technology is automating routine engineering decisions that previously consumed senior designer hours.
The EU AI Act and emerging algorithmic accountability frameworks in North America are mandating explainability and human oversight for AI-generated design outputs. Engineering service contracts now require explicit liability allocation for machine-recommended specifications. Aerospace and medical device segments are investing in audit trail infrastructure to satisfy regulator interrogation of automated decisions.
Fixed-price outcome contracts are displacing time-and-materials billing for well-defined design modules. Industrial equipment OEMs in Germany and Japan are unbundling detailed design from systems engineering, purchasing validated CAD packages rather than designer hours. This compression of scope definition is most advanced in automotive supplier ecosystems where platform standardization enables precise specification of deliverables.
Engineering Design Service Market Segmentation
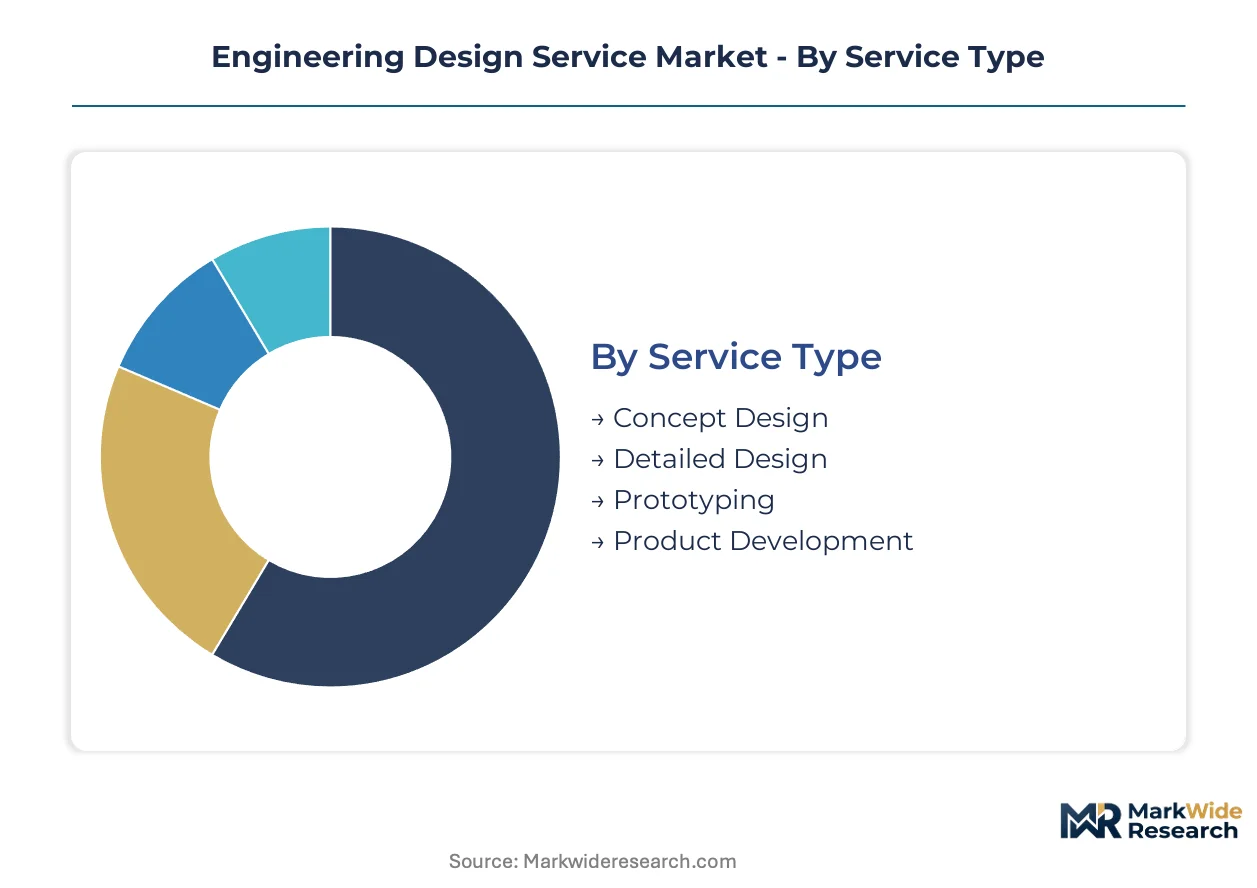
Engineering design services fragment across four distinct dimensions that determine pricing power, margin structure, and competitive intensity. Service type captures the value chain position from ideation through validation. Industry vertical dictates certification requirements and technical complexity. Technology and end-user categories reveal where automation is compressing traditional billable-hour models.
Service Type:
Detailed design and product development command premium pricing through specialized expertise, while prototyping gains volume traction as iterative cycles accelerate.
- Concept Design:Early-stage ideation services translating functional requirements into preliminary specifications and feasibility assessments. Automotive OEMs in Germany concentrate demand here for platform architecture decisions ahead of supplier engagement.
- Detailed Design:Technical specification, CAD documentation, and producibility engineering that consumes the largest share of outsourced engineering hours. Aerospace manufacturers in the United States and Japan source these services to compress development timelines without expanding fixed headcount.
- Prototyping:Physical and digital validation cycles bridging design intent with manufacturability testing. This segment is expanding most quickly as generative AI tools compress iteration cycles from weeks to days.
- Product Development:End-to-end commercialization services spanning design through production readiness. Industrial equipment manufacturers leverage these engagements for modular platform derivatives.
Today's leader: Detailed Design. Tomorrow's challenger: Prototyping.
Industry Vertical:
Certification intensity separates margin tiers, with aerospace and medical-adjacent applications requiring security-cleared teams and AS9100 compliance.
- Aerospace:Structural, propulsion, and avionics design governed by FAA and EASA certification protocols. The EU AI Act is reshaping compliance requirements for automated design tools in this vertical, creating specialized audit-ready documentation demand.
- Automotive:Powertrain, chassis, and electronics design for passenger and commercial vehicles. German and Japanese OEMs maintain dense supplier ecosystems here, unbundling detailed design from systems engineering.
- Consumer Electronics:Compact industrial design and thermal management for connected devices. Shorter product lifecycles favor fixed-price outcome contracts over time-and-materials billing.
- Industrial Equipment:Heavy machinery and process automation design with extended service-life requirements. Cloud-native CAD platforms enable real-time collaboration between OEMs and Eastern European design bureaus.
Aerospace captures the steepest expansion trajectory as commercial aircraft OEMs externalize next-generation propulsion programs.
Technology:
Software licensing concentration in CAD and simulation platforms creates margin pressure for mid-sized consultancies while enabling new service tiers.
- CAD Software:Core drafting and parametric modeling services delivered through proprietary platforms. Dominant vendors impose recurring cost structures that erode margins for independent engineering consultancies.
- Simulation Tools:Finite-element analysis and computational fluid dynamics combining software licensing with embedded consulting. Talent scarcity in combined domain expertise extends project staffing timelines.
- 3D Modeling:Surface and solid modeling for visualization, tooling, and additive manufacturing preparation. Consumer electronics and automotive styling studios drive demand for photorealistic rendering capabilities.
- Virtual Reality:Immersive design review and ergonomic validation environments. Industrial clients adopt these tools for remote stakeholder sign-off, reducing physical prototype iterations.
Simulation Tools concentrate margin pools where vendors bundle expertise with platform access.
End User:
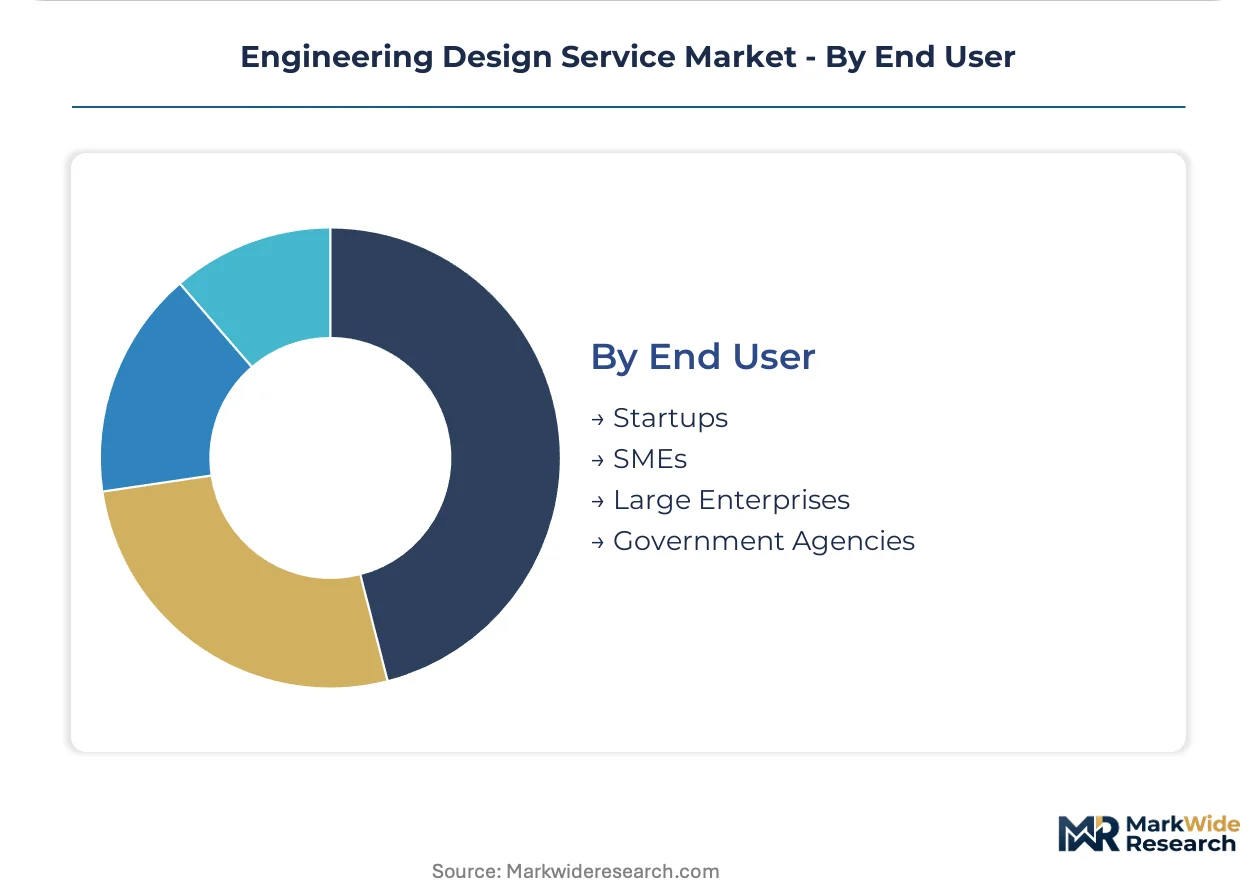
Procurement sophistication varies sharply, with large enterprises unbundling scope and startups purchasing outcome-defined packages.
- Startups:Early-stage ventures purchasing validated CAD packages and rapid prototyping sprints rather than embedded design teams. Fixed-price contracts dominate as capital constraints limit open-ended engagements.
- SMEs:Mid-sized manufacturers accessing specialist expertise without maintaining full-scale internal bureaus. These buyers concentrate in industrial equipment and automotive supplier tiers.
- Large Enterprises:OEMs with established supplier qualification protocols and security clearance requirements. German automotive and United States defense contractors anchor demand here through multi-year framework agreements.
- Government Agencies:Public infrastructure and defense programs requiring security-cleared personnel and audit-trail documentation. Active clearance bottlenecks limit supplier pools and extend onboarding timelines.
Large Enterprises currently dominate contract value. Government Agencies present the steepest growth trajectory as defense modernization programs expand outsourced design partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where engineering design work locates, with cost-of-compliance gaps between jurisdictions driving contract migration toward specialized clusters that balance certification rigor with operational flexibility.
United States
Defense modernization programs and FAA certification requirements anchor demand for security-cleared design teams. The FAA and NHTSA impose documentation rigor that shapes vendor qualification protocols. Engineering service hubs in Texas and Virginia concentrate aerospace and infrastructure design work for federal contracts.
Germany
Automotive OEM supplier ecosystems and industrial equipment manufacturers sustain dense outsourcing relationships. The EU AI Act mandates algorithmic traceability for automated design systems used in automotive development. Bavaria and Baden-Württemberg host specialized bureaus delivering detailed design for powertrain and chassis programs.
Japan
METI industrial policy supports precision manufacturing design capabilities for robotics and automotive applications. JIS standards and METI certification protocols govern quality system investments for cross-border projects. The Nagoya-Chubu corridor concentrates engineering service providers integrated with Toyota and Honda supplier networks.
India
Automotive and industrial equipment OEMs expand captive centers for cost-advantaged simulation and detailed design work. BIS standards and CDSCO protocols shape compliance requirements for medical device and industrial design exports. Pune and Chennai clusters attract outsourced engineering from German and Japanese manufacturers seeking simulation talent.
United Kingdom
Aerospace design heritage and defense procurement sustain specialized engineering service demand. EASA alignment post-Brexit maintains certification continuity for aviation design documentation. The Midlands and Southwest England host consultancies serving Rolls-Royce and BAE Systems propulsion programs.
Engineering Design Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented workflow specialization and outcome-based contracting models. The vendor base concentrates among multidisciplinary infrastructure specialists and defense-integrated engineering firms. Three archetypes dominate: security-cleared defense contractors, modular construction methodology holders, and cloud-native collaboration platform operators. Competitive moves center on M&A for specialized simulation capabilities and strategic partnerships with software vendors to secure preferential licensing terms.
Within the defense-anchored tier, Jacobs Solutions Inc. and Fluor occupy positions requiring cleared personnel and audit-trail infrastructure. WSP USA exemplifies the multidisciplinary infrastructure archetype competing for complex programs across North American markets. These three entities represent distinct competitive vectors—security integration, proprietary methodology, and geographic scale—that structure how contracts allocate across federal, energy, and industrial client segments.
| Leading Market Players |
|---|
| WSP USA |
| HDR |
| AECOM |
| Kimley-Horn |
| Burns & McDonnell |
| Jacobs Solutions Inc. |
| Fluor |
| Stantec Inc. |
| Tetra Tech |
| Others |
Pricing and Supply Chain Analysis
Captive center expansion in India and Eastern Europe anchors supply positioning for mid-tier engineering consultancies while compressing margin structures for billable-hour workflows. This geographic arbitrage in talent sourcing directly shapes pricing power, enabling tier-one vendors to maintain premium positioning through security-cleared delivery teams while forcing cost-based competitors toward outcome-defined contract structures.
Pricing Analysis
Direct-to-OEM discount structures dominate enterprise procurement, with volume-scale agreements and multi-year framework contracts replacing transactional hourly billing. Price differentiation rests on certification tier—AS9100-qualified bureaus command substantial premiums over ISO 9001-only competitors—and security clearance depth for defense-adjacent work. Cost compression in the mid-market intensifies as cloud-native CAD platforms erode proprietary methodology value. Startups and SMEs exhibit acute price sensitivity, while government agencies and aerospace OEMs prioritize audit-trail infrastructure over unit cost.
Supply Chain Analysis
Engineer availability constraints in Germany and Japan's precision manufacturing corridors are redirecting detailed design work toward India's Pune and Chennai clusters. The supply chain draws from specialized software licensing from dominant CAD vendors, finite-element analysis compute infrastructure, and security-cleared personnel pools in the United States and United Kingdom. Single-source vulnerability concentrates in proprietary simulation platforms controlled by three global vendors. Distribution runs through multi-tier supplier networks anchored by German automotive OEMs and United States defense primes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering design services constitute a late-cycle quality story as aerospace and medical device OEMs shift procurement toward audit-ready documentation and security-cleared delivery teams. This specification upgrade favors vendors with embedded compliance infrastructure over cost-based competitors.
For Market Incumbents: Deploy certification depth as the primary defensive lever. Deepen AS9100 and security clearance infrastructure to exclude emerging competitors from defense and aerospace frameworks. Accelerate proprietary methodology codification—modular construction protocols, generative AI-augmented workflows—to resist commoditization from cloud-native platform entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in simulation services offers white-space entry for cloud-native specialists targeting SME industrial equipment manufacturers. Focus initial penetration on thermal management and computational fluid dynamics niches where talent scarcity extends incumbent staffing timelines. Pursue fixed-price outcome contracts with validated CAD package deliverables rather than embedded team placements. For Investors and Strategic Acquirers: Roll-up economics work for regional engineering consultancies with dormant security clearances because defense modernization programs are expanding outsourced design partnerships faster than cleared personnel supply. Target mid-sized bureaus in Texas and Virginia with active facility clearances and established FAA or EASA documentation protocols. Monitor EU AI Act implementation timelines as inflection indicator for algorithmic traceability service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Security Clearance Acquisition | Active facility clearances unlock United States defense and energy sector contracts requiring audit-trail documentation. |
| Generative AI Workflow Integration | Automated topology optimization compresses design iteration cycles from weeks to days for automotive clients. |
| EU AI Act Compliance Infrastructure | Algorithmic traceability capabilities satisfy emerging regulatory mandates for automated design system accountability. |
| Captive Center Establishment | Pune and Chennai facilities deliver cost-advantaged simulation talent for German and Japanese OEMs. |
| AS9100 Certification Investment | Aerospace qualification protocols enable participation in next-generation propulsion and airframe programs. |
Research Methodology
Direct dialogue with engineering service procurement leads, platform engineering directors at CAD software vendors, aerospace supplier quality managers, and defense program contract officers grounded the qualitative framework. Secondary validation drew from FAA certification databases, EASA design organization approvals, SEC 10-K disclosures from publicly traded engineering consultancies, and EU regulatory filings documenting AI Act implementation timelines. Bottom-up engagement value estimates triangulated against top-down market sizing derived from OEM externalization spend patterns.
Segment-level projections across service type, industry vertical, technology platform, and end-user category structured the analytical framework across the projection horizon. CAGRs were derived from trend extrapolation in outsourced engineering intensity by sector, adjusted for regulatory compliance cost inflation and generative AI productivity absorption rates. Modeled inputs included aerospace OEM headcount constraints, automotive platform standardization trajectories, and cloud-native collaboration platform adoption curves.
Caveats apply where EU AI Act enforcement intensity, United States defense budget allocation shifts, or generative AI capability discontinuities could materially shift the outlook. Forecasts reflect documented assumptions regarding certification timeline stability and security clearance processing throughput. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Engineering Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
MEP Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
United States Engineering Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Aerospace Engineering Services Market