
 Bridge Cable Sockets Market | 2026-2036
Bridge Cable Sockets Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Cable Sockets Market Analysis
The gap between forged alloy sockets meeting full fatigue-test certification and cast commodity fittings is recalibrating procurement behavior across bridge projects. Bridon-Bekaert The Ropes Group leverages its integrated rope-and-socket manufacturing to anchor premium-tier contracts on megaprojects. WireCo WorldGroup competes through geographic dominance in North American infrastructure replacement cycles. Usha Martin specializes in high-tensile stainless steel socket variants for coastal corrosion environments.
Bridge cable sockets are mechanical terminations that secure structural cables to bridge towers, decks, and anchor blocks, typically manufactured from hot-forged alloy steel with machined bores matching strand diameters from 12mm to 120mm and proof-loaded to 95% of minimum breaking load. Their primary purpose is to transfer tensile forces from stay cables or suspension strands into bridge substructures without slippage or stress concentration. Compression sockets dominate permanent installations where fatigue resistance over 2-million-cycle thresholds determines specification, while modular systems represent the fastest-growing installation category as prefabricated bridge segments gain share. Stainless steel commands the deepest margin pools in material selection due to lifecycle cost advantages in saline atmospheres.
ISO 17893 sets wire rope socket dimensional and testing protocols that manufacturers must satisfy for international project eligibility, while China's GB/T 20067 governs domestic cable-stayed bridge socket certification and the EU's CE marking under the Construction Products Regulation mandates third-party fatigue validation for European public works. These frameworks are elevating compliance costs for smaller foundries while consolidating specification authority among tier-one suppliers. Stakeholders must monitor how evolving seismic design codes in high-risk zones reshape socket load-rating requirements and material specifications.
Market Dynamics
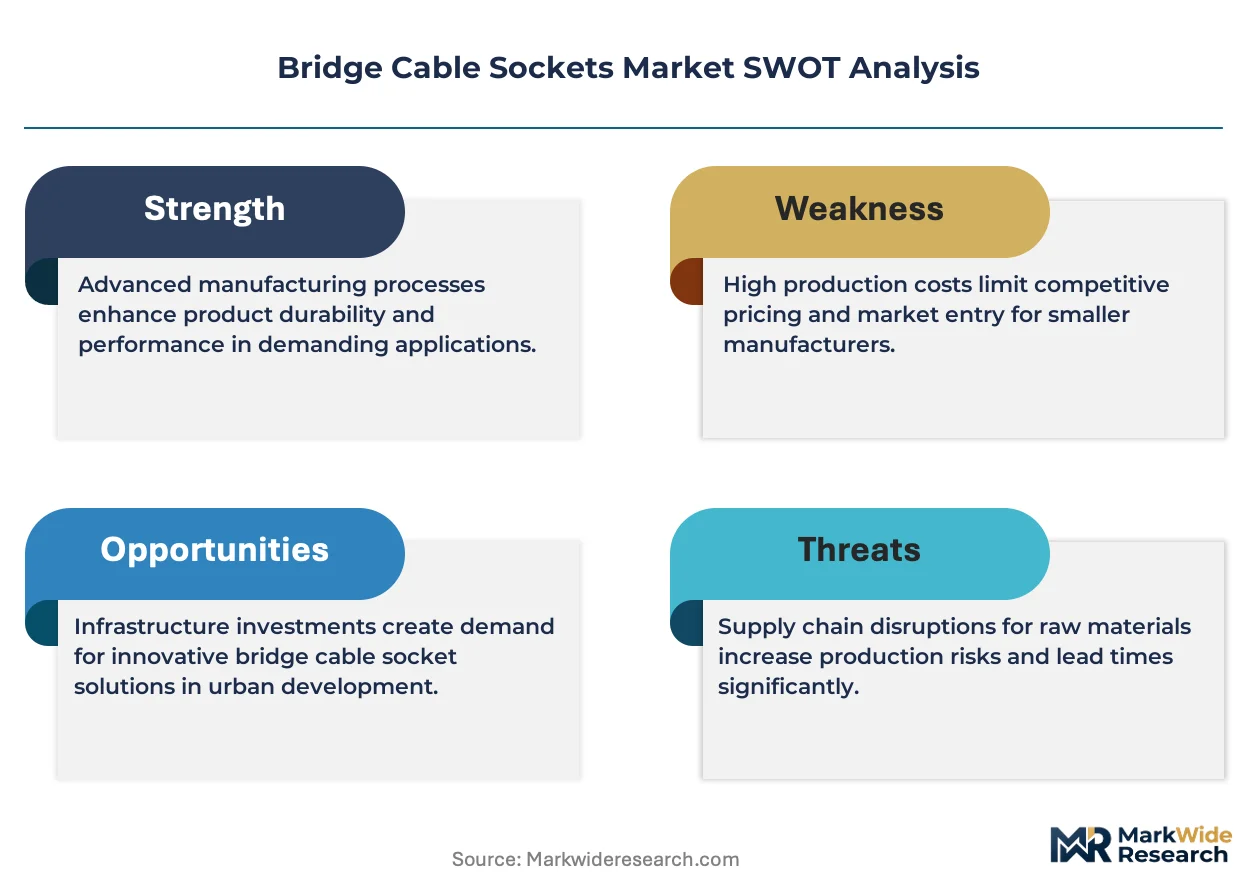
The divergence between forged alloy sockets with full fatigue certification and cast commodity fittings is compressing procurement options for bridge developers, forcing tier-one suppliers to consolidate specification authority while marginalizing smaller foundries.
Growth Catalysts
- EU Construction Products Regulation:The CE marking mandate for third-party fatigue validation in European public works is elevating demand for certified socket assemblies that meet EN 1993 steel structure standards.
- Cross-sea bridge construction:Massive suspension and cable-stayed projects in China are generating concentrated procurement volumes for high-load socket terminations rated for marine environments.
- Stainless steel variants:Coastal infrastructure developers are specifying corrosion-resistant socket materials for saline atmosphere applications, extending replacement cycles and reducing lifecycle costs.
Market Restraints
- Alloy steel price volatility:Hot-forged alloy steel input costs fluctuate with commodity markets, squeezing margins for socket manufacturers locked into fixed-price bridge contracts.
- Tier-one supply concentration:Full-fatigue certification capabilities concentrate among integrated rope-and-socket manufacturers, limiting buyer alternatives for megaproject specifications.
- Welded socket substitution:Some secondary bridge applications are adopting welded terminations where fatigue-cycle thresholds fall below 500,000 cycles, displacing mechanical sockets in non-critical segments.
Strategic Opportunities
- Prefabricated bridge segments:Modular construction methods are creating demand for rapid-install socket systems that integrate with factory-built deck components.
- Seismic zone retrofitting:Japan's updated seismic design codes are mandating socket load-rating upgrades on existing cable-stayed bridges, opening replacement markets.
- Digital twin integration:Sensor-embedded smart sockets that monitor strand tension and corrosion are enabling predictive maintenance contracts with infrastructure operators.
Industry Challenges
- Fatigue-testing bottlenecks:ISO 17893 certification requires 2-million-cycle validation protocols that extend product development timelines and tie up specialized testing equipment.
- Skilled forging technician scarcity:Hot-forging precision for 12mm-to-120mm bore machining depends on experienced operators, with workforce gaps concentrated in European and North American manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Cable Sockets Market |
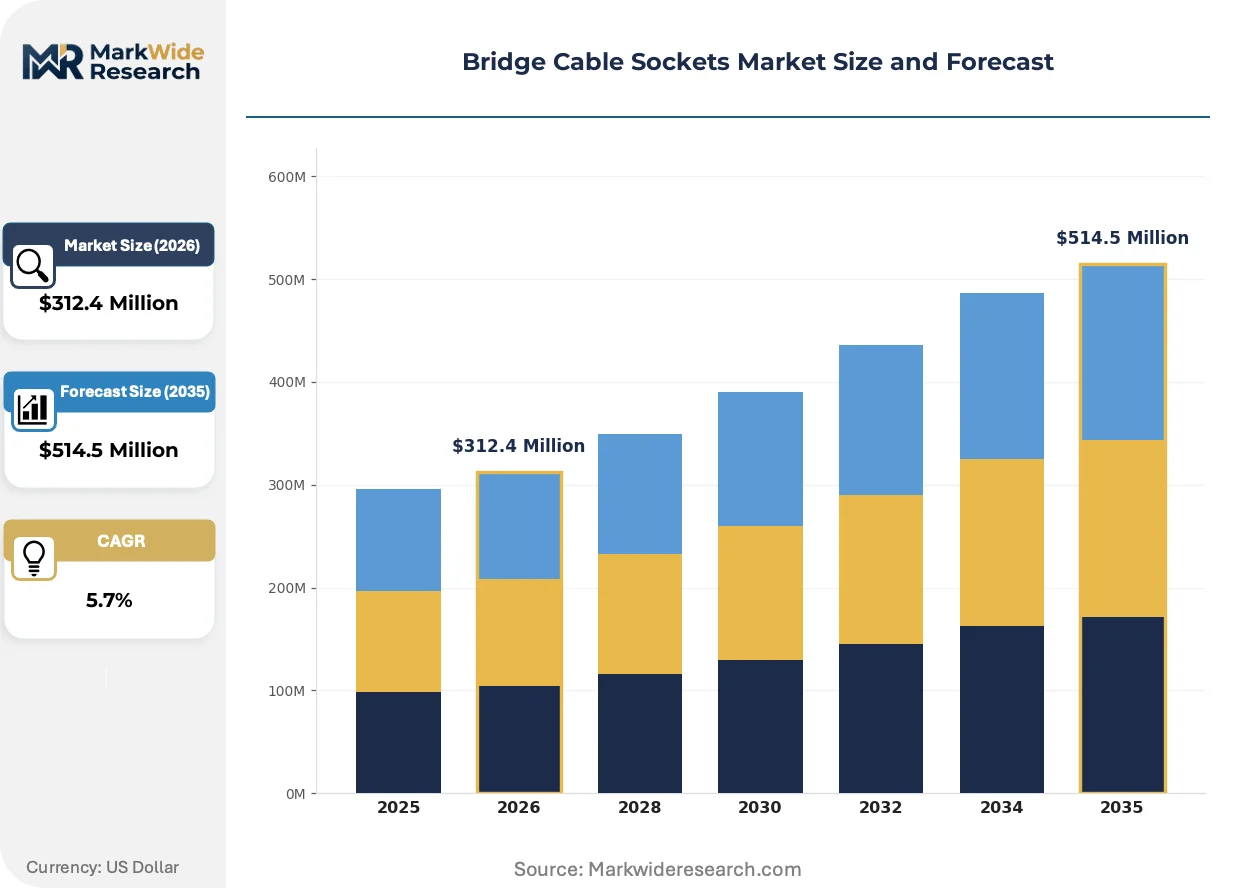
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Sockets, Socket Wrenches, Junction Boxes, Connector Housings Installation Type: Permanent Installation, Temporary Setup, Modular Systems, Automated Connections Material: Aluminum Alloy, Stainless Steel, Copper, Plastic Compounds End User: Construction Companies, Maintenance Providers, OEMs, Infrastructure Developers |
| Companies Covered | Bridon-Bekaert The Ropes Group, WireCo WorldGroup, Usha Martin, VSL International, DYWIDAG Systems International, Pfeifer Group, Macalloy Group, Tokyo Rope Mfg. Co., Ltd., GN Rope Fittings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Cable Sockets Market Emerging Trajectories
Socket technology is converging with structural health monitoring systems, while regulatory frameworks in major bridge-building regions are tightening material traceability requirements. These forces are reshaping how manufacturers differentiate their product portfolios.
Additive manufacturing of socket prototypes is unifying rapid iteration with load-testing validation. Bridge engineering firms in Germany and Japan are adopting 3D-printed alloy models to compress design-to-test cycles from months to weeks. This convergence is unifying digital design workflows with physical certification requirements, allowing socket geometries to be optimized for specific strand configurations before forging investment.
China's GB/T 20067 domestic certification framework is tightening material sourcing documentation for cable-stayed bridge sockets. The standard now requires mill certificates tracing alloy composition through the entire supply chain. Domestic infrastructure bidders are responding by pre-qualifying only suppliers with captive steel production or long-term mill partnerships, excluding trading-house intermediaries from megaproject supply chains.
Asset owners are unbundling socket procurement from rope supply contracts, reversing decades of bundled purchasing. State bridge authorities in the United States and provincial transport departments in Canada are now specifying sockets separately from stay cables, enabling competitive bidding on termination components. This fragmentation is most visible in North American infrastructure replacement cycles, where public procurement rules favor component-level transparency over integrated system awards.
Bridge Cable Sockets Market Segmentation
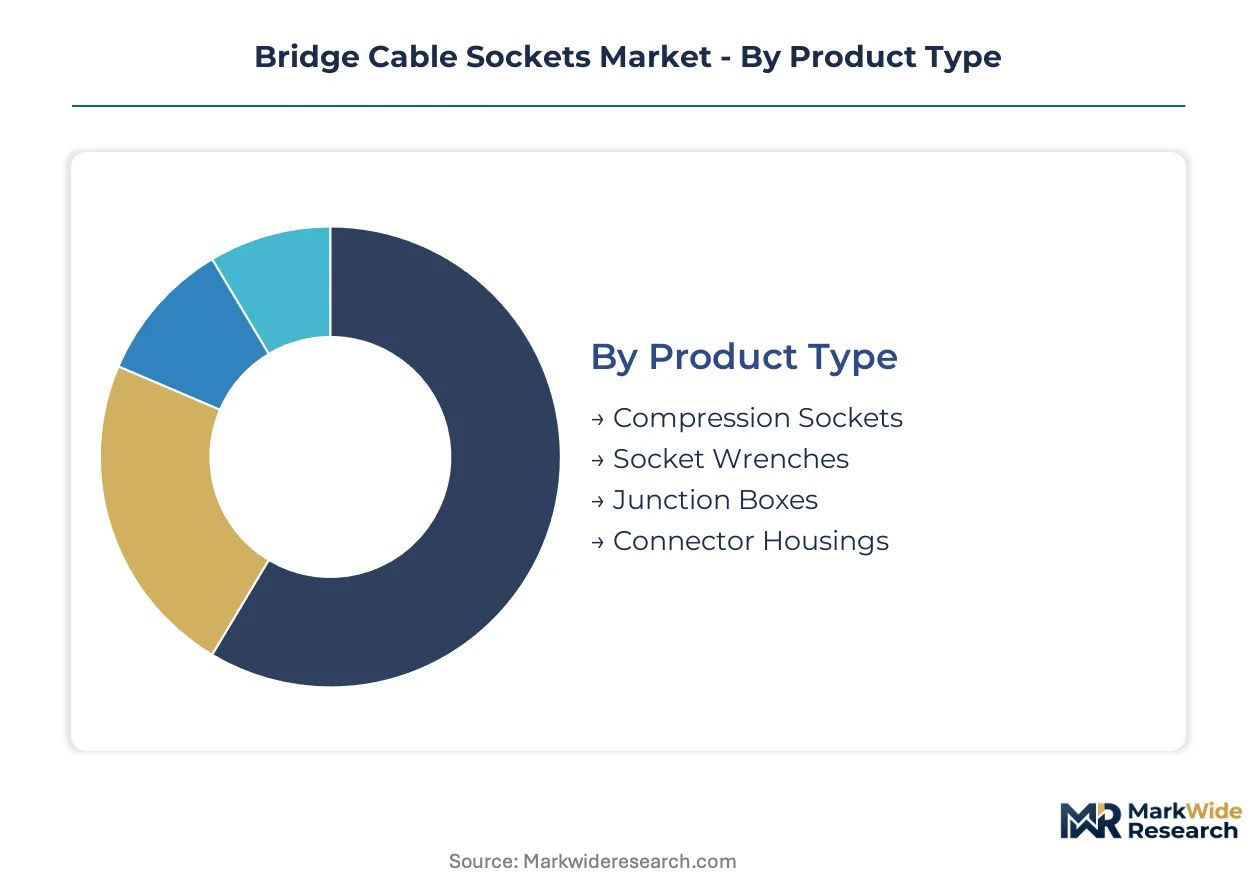
Segmentation in bridge cable sockets reveals how procurement specifications diverge across project lifecycles. Material certifications, installation methods, and end-user procurement authority each reshape competitive positioning differently.
Product Type:
Upgrade cycles from cast commodity fittings to forged certified sockets are compressing the product mix across bridge portfolios.
- Compression Sockets:Hot-forged alloy steel terminations with machined bores rated for 2-million-cycle fatigue thresholds under ISO 17893. Megaproject specifications in China and the EU now mandate these for permanent cable-stayed installations where failure carries catastrophic liability.
- Socket Wrenches:Specialized tensioning tools paired with socket assemblies for field adjustment of stay-cable preload. Maintenance providers in Japan specify these for seismic retrofit contracts requiring precise torque recalibration.
- Junction Boxes:Enclosures protecting electrical monitoring leads embedded in smart socket systems.
- Connector Housings:Interface shells for sensor-embedded terminations in digital twin bridge architectures.
Volume placements concentrate in compression sockets; the faster expansion belongs to connector housings as structural health monitoring penetrates new builds.
Installation Type:
Prefabrication economics are redistributing installation method preferences across project delivery models.
- Permanent Installation:Field-wedged or resin-potted terminations designed for 50-100 year service lives without access. China's cross-sea bridge program specifies these exclusively for marine-environment towers where maintenance access is prohibitively expensive.
- Modular Systems:Factory-integrated socket assemblies pre-installed on prefabricated deck segments. North American infrastructure replacement cycles favor these for rapid-lane closures and minimized traffic disruption.
- Temporary Setup:Reusable tensioning hardware for construction-phase cable staging.
- Automated Connections:Robotic-installation-compatible socket geometries for remote or hazardous access zones.
Permanent installation retains the revenue base; modular systems are climbing the fastest as design-build contracts proliferate.
Material:
Lifecycle cost accounting is elevating material selection from first-cost to total-ownership decisions.
- Stainless Steel:High-nickel alloy variants specified for coastal and de-icing salt exposure where corrosion-induced replacement would demand full lane closures. Japanese and Korean bridge authorities mandate these for all new marine crossings.
- Aluminum Alloy:Lightweight forged grades for pedestrian bridges and secondary cable systems where mass reduction enables longer unsupported spans.
- Copper:Electrical continuity paths in lightning-protection-integrated socket designs.
- Plastic Compounds:Insulating shrouds and corrosion barriers in hybrid metal-polymer assemblies.
Stainless steel commands the deepest margins; aluminum alloy is gaining share fastest in pedestrian and light-traffic segments.
End User:
Procurement unbundling is fragmenting purchasing authority across the project value chain.
- Infrastructure Developers:State-owned and private concession holders specifying socket systems for greenfield megaprojects. China's provincial transport departments and Canada's infrastructure banks now separate socket procurement from cable supply, enabling component-level competitive bidding.
- Maintenance Providers:Specialized contractors executing seismic retrofits and fatigue-life extensions. Japan's updated design codes have activated this segment for socket load-rating upgrades on existing cable-stayed inventory.
- Construction Companies:General contractors purchasing installation-method-appropriate assemblies under design-build contracts.
- OEMs:Stay-cable system integrators bundling sockets with strand supply in markets where unbundling has not yet penetrated.
Infrastructure developers dominate absolute volume; maintenance providers show the steepest expansion trajectory as aging bridge inventories mature into replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors bridge cable socket procurement intensity, with Shanghai and Jiangsu province infrastructure departments driving specifications for cross-river megaprojects. Procurement volumes concentrate where suspension and cable-stayed bridge construction intersects with stringent material certification regimes.
China
Provincial transport departments in Jiangsu and Guangdong specify GB/T 20067-certified sockets for cross-sea bridge towers. The standard mandates mill certificate traceability through supply chains, excluding trading intermediaries from megaproject bidding. Ningbo-Zhoushan Port corridor contractors pre-qualify only suppliers with captive steel production.
United States
State bridge authorities in California and New York unbundle socket procurement from stay-cable contracts, enabling component-level competitive bidding. Federal Highway Administration guidelines reference AASHTO fatigue specifications for suspension bridge retrofits. Pacific Northwest infrastructure replacement cycles favor modular socket systems for rapid-lane closure constraints.
Germany
Rhineland-Palatinate and Baden-Württemberg transport ministries enforce CE marking under the EU Construction Products Regulation for public bridge works. EN 1993 steel structure standards mandate third-party fatigue validation for socket assemblies. Stuttgart engineering clusters prototype 3D-printed alloy socket geometries for design-to-test compression.
Japan
METI's updated seismic design codes mandate socket load-rating upgrades on existing cable-stayed inventory in Kansai and Chubu regions. Osaka Bay coastal authorities specify high-nickel stainless steel variants for saline atmosphere exposure. Nagoya maintenance providers execute torque recalibration contracts under precise preload adjustment protocols.
Canada
Infrastructure Bank project finance in British Columbia and Quebec prioritizes lifecycle cost accounting for coastal bridge socket specifications. Provincial transport departments reference CSA S6 bridge design standards for fatigue-resistant terminations. Vancouver Island contractors specify corrosion-resistant materials for de-icing salt exposure environments.
Bridge Cable Sockets Market Vendor Landscape
Capital-heavy integrated rope-and-socket manufacturers compete with specialized forging houses lacking in-house cable production. Tier-one suppliers consolidate specification authority through captive fatigue-testing capabilities, while smaller foundries retreat to secondary bridge applications. Three archetypes dominate: integrated system providers bundling rope and termination supply, stainless steel specialists serving coastal corrosion environments, and modular system fabricators targeting prefabricated construction. Consolidation pressure manifests through acquisition of testing facilities and exclusive mill partnerships securing alloy supply.
Within the integrated-system tier, Bridon-Bekaert The Ropes Group and WireCo WorldGroup exemplify the rope-and-socket bundling model that anchors premium-tier megaproject contracts. Usha Martin occupies a position among corrosion-environment specialists, with company nomenclature indicating Indian origin and public limited structure. These three entities represent distinct competitive vectors: geographic dominance in replacement cycles, integrated manufacturing scale, and material specialization for marine atmospheres.
| Leading Market Players |
|---|
| Bridon-Bekaert The Ropes Group |
| WireCo WorldGroup |
| Usha Martin |
| VSL International |
| DYWIDAG Systems International |
| Pfeifer Group |
| Macalloy Group |
| Tokyo Rope Mfg. Co., Ltd. |
| GN Rope Fittings |
| Others |
Supply Flow & Price Mechanics
Captive steel production anchors both supply security and pricing power for tier-one socket manufacturers serving European and Chinese megaprojects. Integrated rope-and-socket producers with in-house forging and mill partnerships command premium positioning against smaller foundries dependent on spot alloy markets.
Pricing Analysis
Fatigue-cycle certification thresholds anchor value-based pricing tiers across bridge cable socket procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17893-validated forged assemblies from cast commodity fittings and welded terminations. Price differentiation hinges on certification level and captive testing capacity, with alloy steel price volatility compressing margins for non-integrated suppliers. Infrastructure developers in China show lowest price sensitivity for marine-environment specifications, while North American replacement cycles favor competitive bidding on component-level awards.
Supply Chain Analysis
Skilled forging technician scarcity in Germany and Japan constrains precision bore machining capacity for 12mm-to-120mm socket ranges. Manufacturing gravity centers on China, India, and Belgium, with hot-forged alloy steel inputs drawing from captive mill partnerships and long-term offtake agreements. Supply chain risk rests on single-source vulnerability for fatigue-testing equipment required by EN 1993 and GB/T 20067 protocols. Distribution runs through project-direct contracts with infrastructure developers and stay-cable system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bridge cable socket technology is transitioning from passive mechanical terminations to sensor-embedded smart systems, with digital twin integration displacing legacy inspection-dependent maintenance models.
For Market Incumbents: Anchor specification authority through exclusive fatigue-testing facility acquisitions and EN 1993 certification investments. Defend against procurement unbundling by bundling predictive maintenance software with socket supply contracts. Deepen backward integration into alloy steel production to offset commodity price volatility. For New Entrants and Emerging Players: CE marking under the EU Construction Products Regulation opens a window for specialized stainless steel socket fabrication serving North Sea and Mediterranean coastal infrastructure. Target seismic retrofit contracts in Japan's Kansai region where METI-mandated load-rating upgrades outpace incumbent capacity. Pursue OEM partnerships with German engineering clusters prototyping 3D-printed alloy geometries. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated rope manufacturers seeking fatigue-testing capabilities. Five-to-ten year viability favors suppliers with captive steel production and GB/T 20067 pre-qualification status. Monitor prefabricated bridge segment adoption rates as inflection indicator for modular socket system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fatigue-Testing Facility Acquisition | Consolidates specification authority for EN 1993 and ISO 17893 certification requirements. |
| Smart Socket Sensor Integration | Enables predictive maintenance contracts with Japanese and German infrastructure operators. |
| Captive Steel Mill Partnership | Secures alloy supply traceability for China's GB/T 20067 material documentation mandates. |
| Modular System Fabrication Capacity | Captures North American design-build contracts favoring rapid-install prefabricated segments. |
| Stainless Steel Specialization | Commands margin premiums in Osaka Bay and Vancouver Island saline atmosphere specifications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bridge cable socket market analysis. Primary interviews with bridge engineering consultants, infrastructure procurement officers, fatigue-testing laboratory directors, and stay-cable system integrators combined with secondary validation from EU Construction Products Regulation documentation, GB/T 20067 certification records, and AASHTO guideline releases. Bottom-up project pipeline analysis triangulated with top-down alloy steel consumption estimates.
Segment-level granularity modeled product type, installation method, material grade, and end-user procurement authority across the projection horizon. CAGRs derived from bridge construction investment flows, replacement cycle timing, and regulatory compliance cost trajectories. Industry-specific inputs included seismic retrofit mandate implementation schedules and prefabricated bridge segment adoption curves.
The model assumes a particular technology adoption path; alternative pathways for additive-manufactured socket prototyping would alter the outlook. Forecasts reflect assumptions regarding certification timeline stability and alloy supply chain continuity. Material deviation in fatigue-testing capacity expansion or regulatory harmonization between EU and Chinese standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Industrial Jacks Market