
 Vibrating Conveyor Market | 2026-2036
Vibrating Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Vibrating Conveyor Market Outlook
ISO 13350 certification for industrial fans and associated vibration machinery is redrawing the competitive threshold for entry into European and North American supply chains. GEA Group leverages its captive testing infrastructure to self-certify electromechanical systems ahead of third-party audit cycles. Carrier Vibrating Equipment anchors its position through deep backward integration into foundry-cast spring components, insulating it from steel alloy volatility. Eriez Manufacturing Co. specializes in magnetic drive coil assemblies, a sub-technology where patent density limits new entrants.
A vibrating conveyor is a mechanical transport device that uses oscillating motion—typically driven by electromagnetic coils, unbalanced motors, or eccentric shafts operating at frequencies between 15 and 60 Hz—to move bulk solids or unit items along a trough or tube. These systems achieve controlled flow rates from fractions of kilograms to thousands of tons per hour without internal moving parts in the material stream, making them essential for hygienic food processing and abrasive mining environments. Electromagnetic product types dominate precision applications where exact dosing and rapid start-stop cycles protect fragile food products, while electromechanical variants lead in heavy-aggregate mining where torque density and trough longevity matter more than positional accuracy. Direct drive installations are gaining specification share in recycling plants seeking reduced maintenance intervals, though fixed installations still occupy the majority of capital expenditure in established bulk material handling infrastructure.
The EU Machinery Directive, CE marking protocols, and OSHA vibration exposure standards collectively shape equipment design mandates, with OSHA's permissible exposure limits for whole-body vibration forcing manufacturers to isolate resonant frequencies below 8 Hz in operator-adjacent configurations. The EPA's particulate matter regulations for mining and aggregate operations indirectly boost demand for enclosed vibrating conveyor systems that suppress fugitive dust at transfer points. Stakeholders must monitor how emerging EU Ecodesign requirements for industrial motors will cascade into revised efficiency thresholds for electromechanical drive units before the next equipment replacement cycle accelerates.
Market Dynamics
Food processing automation is tightening specification requirements for vibration-controlled transport systems, forcing manufacturers to certify electromechanical drives under ISO 13350 and EU Machinery Directive protocols before securing procurement contracts from German precision engineering clusters.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking thresholds for industrial equipment are tightening, compelling facility upgrades across European food processing plants.
- Electromagnetic coil precision dosing:Fragile product handling requirements in confectionery and baked goods lines favor rapid start-stop electromagnetic systems over mechanical alternatives.
- Dortmund-Stuttgart engineering concentration:German precision manufacturing clusters generate specification intensity for vibration-isolated transport in pharmaceutical and specialty chemical applications.
Market Restraints
- Spring alloy input volatility:Foundry-cast spring components depend on nickel-chromium steel alloys subject to energy-intensive production cost swings.
- Patent density in magnetic drive assemblies:Dense intellectual property holdings around electromagnetic coil configurations limit new entrant participation in precision segments.
- OSHA whole-body vibration exposure limits:Permissible exposure thresholds below 8 Hz force costly isolation engineering in operator-adjacent installations.
Strategic Opportunities
- Recycling plant direct drive adoption:Reduced maintenance intervals and elimination of belt-drive wear components attract municipal waste and electronic scrap processors.
- EU Ecodesign motor efficiency requirements:Pending revisions to industrial motor performance thresholds will accelerate replacement cycles for electromechanical drive units.
- Enclosed dust suppression systems:EPA particulate matter regulations for mining and aggregate operations favor sealed trough configurations at transfer points.
Industry Challenges
- ISO 13350 certification timeline compression:Third-party audit cycles for industrial fans and vibration machinery extend lead times for supply chain qualification.
- Legacy fixed installation retrofit complexity:Established bulk material handling infrastructure requires costly structural modification to accommodate direct drive electromagnetic systems.
- Electromechanical-electromagnetic integration skill scarcity:Maintenance technicians trained in both unbalanced motor torque density and coil-based precision control remain scarce in regional service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibrating Conveyor Market |
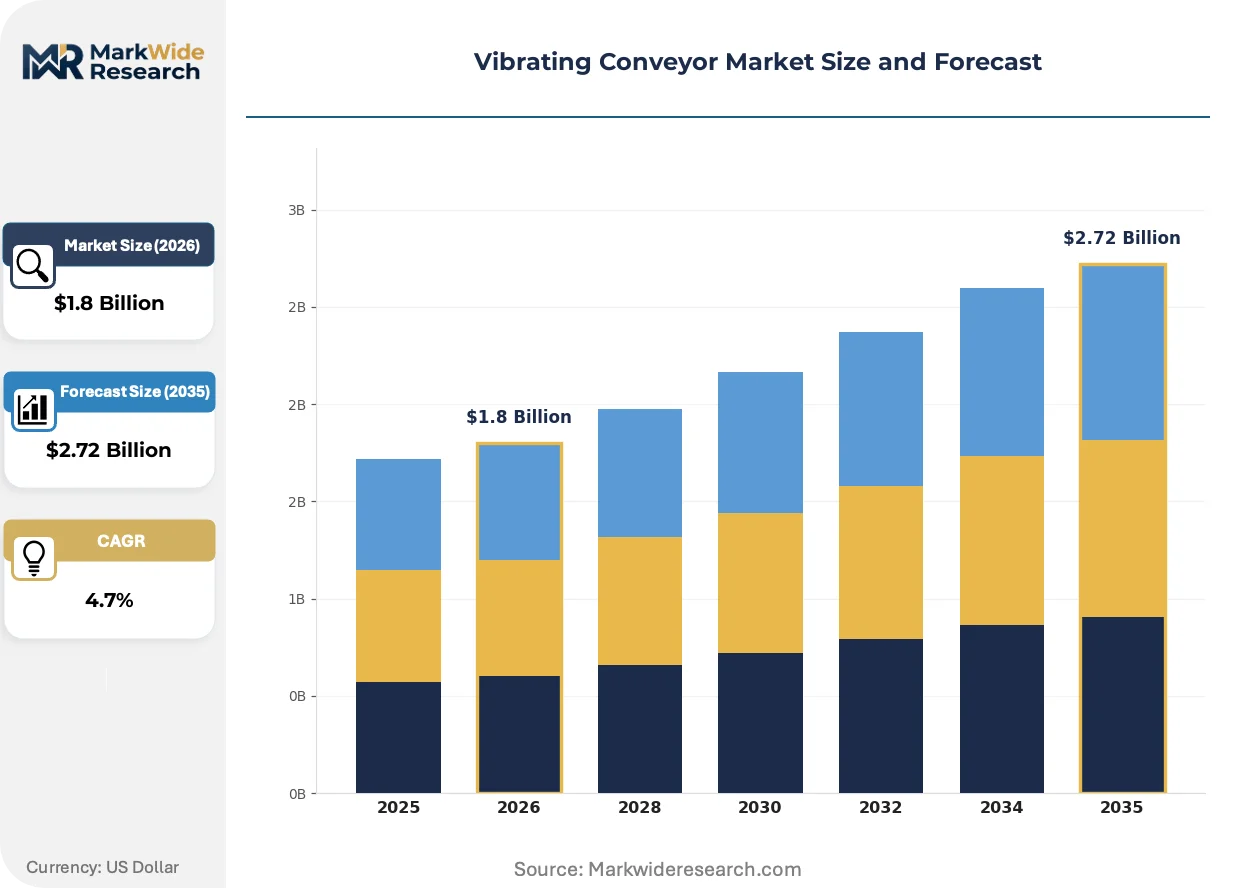
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Electromechanical, Direct Drive, Linear End User: Mining, Food Processing, Recycling, Packaging Installation: Fixed, Portable, Modular, Custom Application: Bulk Material Handling, Aggregate Transport, Sorting, Washing |
| Companies Covered | GEA Group, GMX Vibration, Carrier Vibrating Equipment, Smalley Manufacturing Co., Action Vibratory Equipment, General Kinematics, Eriez Manufacturing Co., Key Technology, AViTEQ Vibrationstechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibrating Conveyor Market Strategic Shifts
Active specification shifts in food processing and mining are compressing equipment replacement cycles while elevating certification requirements for vibration isolation and dust containment. Three developments are restructuring competitive positioning.
Direct drive electromagnetic systems are displacing belt-connected electromechanical configurations in recycling and food-grade applications. These systems eliminate mechanical wear points and enable precise frequency modulation for fragile product handling. European pharmaceutical processors and North American organic waste facilities are specifying direct drive architectures for reduced downtime and simplified sanitation protocols.
REACH substance restrictions and evolving RoHS compliance thresholds are forcing redesign of coil insulation materials and surface coatings in electromagnetic drive assemblies. Manufacturers must reformulate epoxy compounds and conductor enamels to eliminate restricted phthalates and heavy metal stabilizers. German component suppliers are accelerating material qualification programs to maintain CE marking validity across EU member states.
Food processors are unbundling after-sales service contracts from initial equipment procurement, creating independent service provider channels for vibration analysis and spring replacement. This disintermediation compresses OEM margin capture while expanding third-party maintenance networks. The pattern is most visible in North American dairy and meat processing facilities seeking operational flexibility outside captive supplier arrangements.
Vibrating Conveyor Market Segmentation
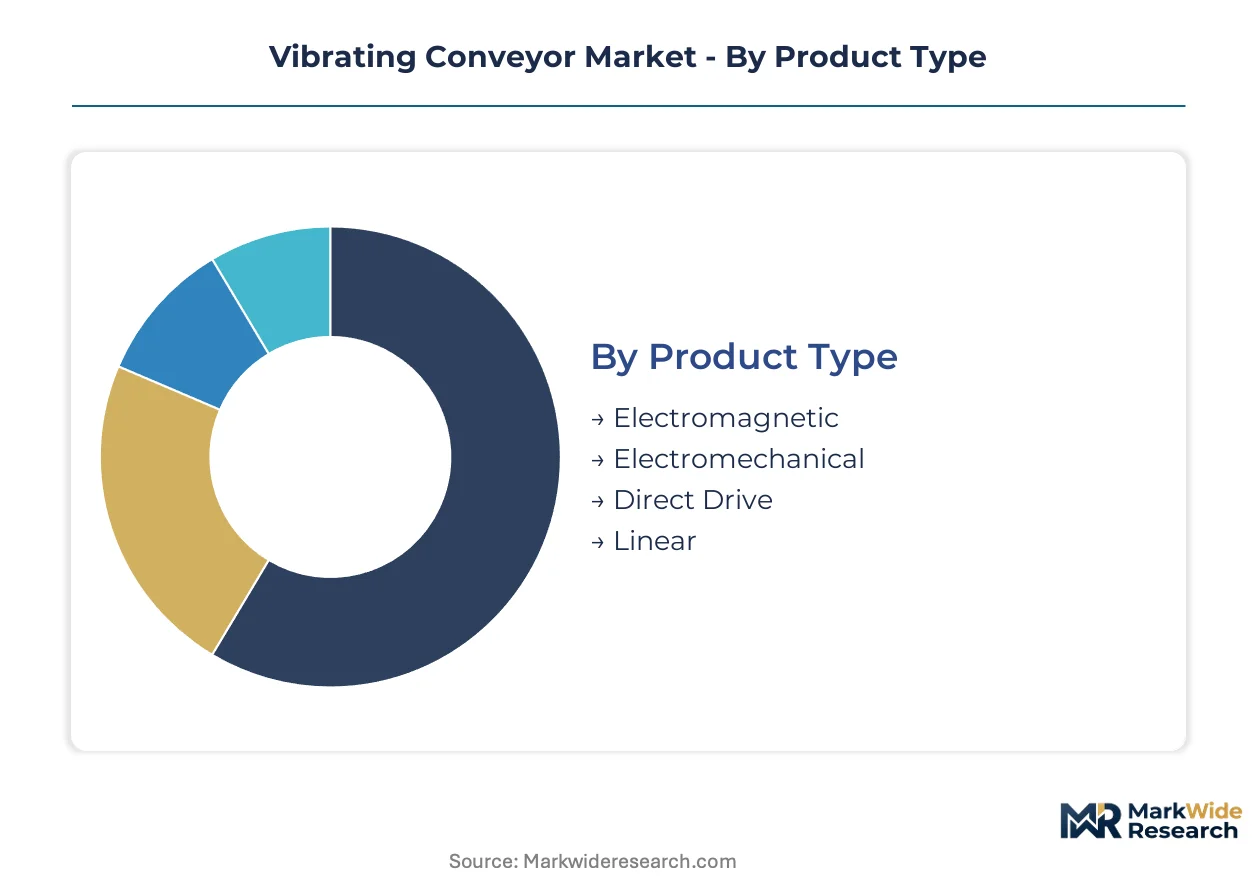
Vibrating conveyor configurations vary sharply by duty cycle and precision requirements. Equipment specification in food processing demands rapid start-stop electromagnetic systems, while mining operations prioritize torque-dense electromechanical drives for abrasive aggregate transport.
Product Type:
Electromagnetic systems dominate export specifications to European pharmaceutical clusters, while electromechanical variants anchor domestic heavy industry procurement in mining belts.
- Electromagnetic:Coil-driven oscillation at 15-60 Hz enables millisecond response times for fragile confectionery dosing. German precision engineering clusters around Stuttgart specify these systems for hygienic pharmaceutical transport where ISO 13350 vibration isolation is mandatory.
- Electromechanical:Unbalanced motor or eccentric shaft drives deliver high torque density for thousand-ton-per-hour aggregate flows. Demand concentrates in domestic mining operations across the Rust Belt and Mountain West where trough longevity outweighs positional accuracy requirements.
- Direct Drive:Eliminates belt wear components through integrated motor-trough coupling. Municipal recycling facilities in the Pacific Northwest specify these for reduced maintenance intervals.
- Linear:Restricted oscillation amplitude suits precision sorting applications. Electronics scrap processors deploy these for component separation in high-value recovery lines.
Electromechanical holds the largest share; momentum sits with direct drive as recycling automation accelerates.
End User:
Cost tier stratification separates capital-intensive mining procurement from margin-sensitive food processing specification cycles.
- Mining:Abrasive material handling at transfer points requires nickel-chromium alloy springs and enclosed trough configurations to meet EPA particulate matter regulations. Appalachian and Powder River Basin operations drive specification volume for heavy-duty electromechanical systems.
- Food Processing:USDA-inspected facilities demand rapid sanitation protocols and electromagnetic precision for fragile baked goods transport. Dairy processors in Wisconsin and meat packers in Nebraska are unbundling service contracts from initial procurement.
- Recycling:Electronic scrap and organic waste facilities favor direct drive architectures for operational uptime. West Coast municipal contracts specify modular installations for flexibility across mixed waste streams.
- Packaging:Unit item handling at case packing lines utilizes compact electromagnetic troughs. Midwest distribution centers integrate these with robotic palletizing cells.
Mining commands the highest equipment value per installation; food processing is expanding most quickly as automation penetrates mid-tier processing plants.
Installation:
Volume concentration favors fixed infrastructure in established bulk handling corridors, while customer type diversification drives portable and modular specification.
- Fixed:Permanent structural integration dominates capital expenditure in mining and aggregate infrastructure. Legacy installations in the Southeast require costly retrofit engineering to accommodate direct drive electromagnetic upgrades.
- Portable:Skid-mounted or trailer-based systems serve construction aggregate and temporary processing sites. Quarry operators in Texas and Florida specify these for mobile crushing circuits.
- Modular:Standardized sections enable rapid reconfiguration across recycling and food processing lines. Third-party maintenance networks are expanding service capabilities for these interchangeable components.
- Custom:Engineered-to-order trough geometries address unique material flow challenges. Specialty chemical processors in the Gulf Coast commission these for corrosive substance handling.
Fixed installations retain the majority of capital deployment; modular systems are gaining share fastest among facilities seeking operational flexibility.
Application:
Supply concentration in foundry-cast spring components shapes equipment availability across duty cycle intensities.
- Bulk Material Handling:Continuous flow of coal, ore, and grain requires enclosed trough configurations to suppress fugitive dust. EPA regulations indirectly boost specification for sealed systems at transfer points in Illinois and Indiana grain terminals.
- Aggregate Transport:High-tonnage movement of crushed stone and sand demands electromechanical torque density. Arizona and Nevada quarry operations anchor domestic demand for heavy-duty trough designs.
- Sorting:Vibration-assisted separation by size or density serves recycling and mining preprocessing. Colorado electronic scrap facilities integrate these with magnetic recovery systems.
- Washing:Combined vibration and water spray cleaning for aggregate and food products. California vegetable processors specify stainless steel troughs with integrated drainage for post-harvest sanitation.
Bulk material handling holds the largest installed base; sorting applications are climbing the fastest as recycling automation penetrates municipal waste systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Machinery Directive compliance timelines and EPA particulate regulations are accelerating equipment replacement cycles across industrial corridors. German precision engineering clusters and US mining belts drive specification intensity for vibration-isolated transport systems.
Germany
Dortmund-Stuttgart engineering corridors generate concentrated demand for ISO 13350-certified electromagnetic systems in pharmaceutical and specialty chemical applications. CE marking protocols under the EU Machinery Directive mandate third-party audit cycles that extend lead times for supply chain qualification. Bavarian food processors specify rapid start-stop coil assemblies for fragile confectionery handling.
United States
Appalachian and Powder River Basin mining operations anchor domestic procurement of heavy-duty electromechanical trough designs for abrasive aggregate transport. OSHA whole-body vibration exposure limits below 8 Hz force costly isolation engineering in operator-adjacent configurations. Wisconsin dairy processors and Nebraska meat packers are unbundling service contracts from initial equipment procurement.
China
Yangtze River Delta manufacturing clusters integrate vibrating conveyors into automated food processing lines serving export markets. GB standards for industrial machinery safety shape local certification requirements alongside evolving efficiency mandates. Shandong Peninsula foundries supply nickel-chromium alloy spring components to domestic and regional equipment builders.
India
Maharashtra and Gujarat pharmaceutical manufacturing zones specify electromagnetic precision systems for hygienic bulk material handling. BIS certification requirements for industrial equipment create compliance thresholds for imported machinery. Tamil Nadu food processing automation projects favor modular installations with third-party maintenance capabilities.
Japan
Kansai region electronic scrap recovery facilities deploy linear vibration systems for high-value component separation. METI industrial efficiency programs incentivize direct drive architectures in municipal waste processing. Chubu manufacturing corridors maintain specification preference for electromechanical durability in heavy-aggregate applications.
Vibrating Conveyor Market Competitive Environment
Player mix skews toward diversified industrial equipment conglomerates with captive testing infrastructure and specialized vibration technology boutiques with dense patent holdings. Market structure exhibits moderate consolidation around electromechanical system builders with backward integration into foundry-cast components. Two strategic archetypes dominate: precision electromagnetic specialists serving pharmaceutical and food-grade specifications, and torque-dense aggregate handlers anchored in mining procurement channels. Competitive moves concentrate on ISO 13350 certification acceleration and direct drive technology licensing to recycling sector entrants.
Among German-based precision engineering houses, AViTEQ Vibrationstechnik GmbH exemplifies the electromagnetic specialization archetype with deep European pharmaceutical supply chain penetration. GEA Group occupies a position representing diversified conglomerate scale with self-certification capabilities and cross-sector equipment portfolios. Carrier Vibrating Equipment anchors the North American mining-focused tier through upstream control over spring component supply chains. Eriez Manufacturing Co. sits within the magnetic drive technology niche where intellectual property density limits competitive entry.
| Leading Market Players |
|---|
| GEA Group |
| GMX Vibration |
| Carrier Vibrating Equipment |
| Smalley Manufacturing Co. |
| Action Vibratory Equipment |
| General Kinematics |
| Eriez Manufacturing Co. |
| Key Technology |
| AViTEQ Vibrationstechnik GmbH |
| Others |
Value Chain & Pricing Dynamics
Foundry capacity utilization above 85 percent in Shandong Peninsula and Ruhr Valley spring component clusters concentrates supply-side pricing power among backward-integrated electromechanical builders. This scale geometry elevates price floors for nickel-chromium alloy trough suspensions while compressing margins for non-integrated assemblers dependent on spot-market spring procurement.
Pricing Analysis
Certification level creates the primary spread across ISO 13350-validated, CE-marked, and uncertified equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects audit-cycle investment and third-party validation costs. Cost compression in standard-tier electromechanical systems is intensifying because German precision engineering clusters demand shorter lead times for pharmaceutical-grade electromagnetic alternatives. Food processing procurement teams exhibit highest price sensitivity due to unbundled service contracts, while mining operators prioritize trough longevity over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for electromagnetic coil assemblies sourced from Yangtze River Delta manufacturing zones. Supply concentrates in China for nickel-chromium alloy castings, Germany for precision-engineered vibration isolation components, and the United States for heavy-duty electromechanical drive units. Raw material dependencies span rare-earth magnetic materials, specialty steel alloys, and epoxy insulation compounds. Single-source vulnerability in magnetic coil winding equipment creates chokepoint exposure. Distribution runs through OEM-direct channels for mining procurement and third-party maintenance networks for food-grade installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vibrating conveyor market structure exhibits defensive-moat characteristics rooted in regulatory entrenchment. ISO 13350 certification timelines and EU Machinery Directive compliance protocols create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate through captive testing infrastructure expansion and accelerated third-party audit pre-qualification. Patent density in electromagnetic coil configurations limits emerging entrant replication of precision dosing architectures. Backward integration into foundry-cast spring production insulates margin position against nickel-chromium alloy volatility. For New Entrants and Emerging Players: ISO 13350 certification fast-track programs offer entry pathway into European pharmaceutical supply chains. Direct drive recycling applications present most penetrable white-space given reduced maintenance specification intensity and lower patent barriers. Municipal waste processing contracts in Pacific Northwest and Kansai region provide anchor customer base for technology demonstration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision electromagnetic specialists over torque-dense aggregate handlers. Long-term viability assessment across the analysis window should weight regulatory compliance infrastructure as durable competitive asset. Acquisition target archetype combines ISO 13350 self-certification capability with direct drive intellectual property portfolio. Signal to watch is EU Ecodesign motor efficiency mandate acceleration triggering replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13350 Certification Acceleration | Self-certification infrastructure compresses third-party audit cycles for European pharmaceutical supply chain access. |
| Direct Drive Technology Licensing | Patent licensing agreements enable recycling sector entrants to bypass electromagnetic coil assembly development costs. |
| Backward Integration into Spring Components | Foundry-cast spring production captive supply insulates electromechanical builders from nickel-chromium alloy price volatility. |
| Modular Installation Platform Development | Standardized section architectures attract food processing facilities seeking operational flexibility outside OEM service contracts. |
| EU Ecodesign Compliance Pre-positioning | Electromechanical drive unit efficiency upgrades ahead of mandate acceleration capture replacement cycle demand. |
Study Parameters
Desk research of trade association technical standards, customs import-export records, and regulatory filing databases preceded structured interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and food processing automation engineers. Primary fieldwork across German precision engineering clusters and US mining belts triangulated against secondary validation from SEC equipment manufacturer filings and EU Machinery Directive compliance registries. Bottom-up installation volume estimates and top-down capital expenditure flows were reconciled through iterative cross-checking.
Variance decomposition across product type, end-use industry, installation configuration, and regional regulatory cluster shaped the analytical framework. Growth trajectories were derived from replacement cycle timing, automation penetration rates, and compliance-driven upgrade mandates throughout the forecast period. Electromechanical-electromagnetic technology mix shifts and REACH substance restriction implementation timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and nickel-chromium alloy supply continuity assumptions; material deviation would warrant model refresh. Abrupt OSHA vibration exposure limit tightening or EU Ecodesign acceleration could compress replacement cycles beyond modeled parameters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Tree Milling Machine Market