
 Machined Springs Market | 2026-2036
Machined Springs Market Size, Share, and Industry Trends Forecast 2026-2036
Machined Springs Market Insights
Precision machining talent is rotating away from general metal fabrication toward additive-ready and CNC-multi-axis spring production, tightening labor supply for conventional coiling operations. MW Industries, Inc. leverages vertical integration across wire drawing to finished spring testing to control lead times. Smalley Steel Ring Company specializes in continuous spiral retaining rings and wave springs for aerospace and energy applications. Bal Seal Engineering, Inc. anchors its position through canted coil spring technology serving medical device and semiconductor sealing markets.
Machined springs are precision-engineered elastic components manufactured from solid bar stock through CNC turning, milling, or grinding rather than coiling wire, achieving tighter dimensional tolerances and superior fatigue resistance for critical load-bearing functions. Compression springs and wave springs dominate current volume, with titanium alloy and Inconel material grades capturing expanding share in aerospace and medical device applications where corrosion resistance and biocompatibility command premium positioning. Elevator systems and mining tools represent mature demand basins, while aerospace equipment and consumer electronics drive specification upgrades toward miniaturized, high-cycle-life designs.
FDA device regulations and ISO 13485 quality management standards shape medical device manufacturer procurement, requiring material certification and process validation for springs implanted or contacting bodily fluids. EPA hazardous air pollutant rules and OSHA metalworking fluid exposure limits raise compliance costs for U.S. fabrication facilities, favoring capital-intensive operators with environmental management systems. Stakeholders must weigh whether to deepen captive alloy processing or outsource to certified specialty mills as traceability requirements tighten across European and North American supply chains.
Market Dynamics
Precision machining talent is rotating away from conventional coiling operations toward additive-ready and CNC-multi-axis spring production, tightening labor supply for traditional fabrication while aerospace and medical device buyers demand tighter tolerances.
Growth Catalysts
- Aerospace landing gear procurement:Equipment manufacturers in Germany and the United States are expanding machined spring volumes for flight control systems and undercarriage assemblies, with Stuttgart engineering clusters anchoring specialized fabrication capacity.
- REACH material traceability mandates:European suppliers are pivoting toward certified recycled alloys under tighter ECHA standards, creating competitive differentiation for mills with verified circular metal sourcing.
- Titanium alloy biocompatibility:Medical device OEMs are specifying Ti-6Al-4V ELI grades for implantable springs, with corrosion resistance and fatigue life commanding premium positioning in orthopedic and cardiovascular applications.
Market Restraints
- Nickel superalloy price volatility:Inconel 718 bar stock costs fluctuate with aerospace build rates and mining output, compressing margins for job shops without long-term mill contracts.
- German supply concentration:Precision spring fabrication clusters around Munich and Stuttgart create geographic vulnerability to regional energy cost spikes and logistics disruptions.
- Wire coiling substitution:Cold-formed wire springs retain cost advantage in non-critical applications, limiting machined spring penetration in elevator systems and general industrial hardware.
Strategic Opportunities
- Indian aerospace MRO expansion:Bangalore and Hyderabad maintenance hubs are developing local machined spring sourcing for landing gear overhaul, reducing dependence on European airfreight.
- EU Green Deal carbon accounting:Certified low-carbon alloy processing creates qualification advantage for suppliers documenting Scope 3 emissions through EPD certification.
- Semiconductor capital equipment:Vacuum chamber sealing applications are adopting canted coil spring technology for ultra-high purity environments, with Taiwan and South Korea fab construction driving specification upgrades.
Industry Challenges
- Multi-axis CNC programming expertise:Shops struggle to recruit operators capable of simultaneous 5-axis spring contouring, with vocational pipelines favoring additive manufacturing curricula over precision turning.
- ISO 13485 validation timelines:Medical device spring qualification cycles extend 18-24 months, freezing working capital and delaying revenue recognition for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machined Springs Market |
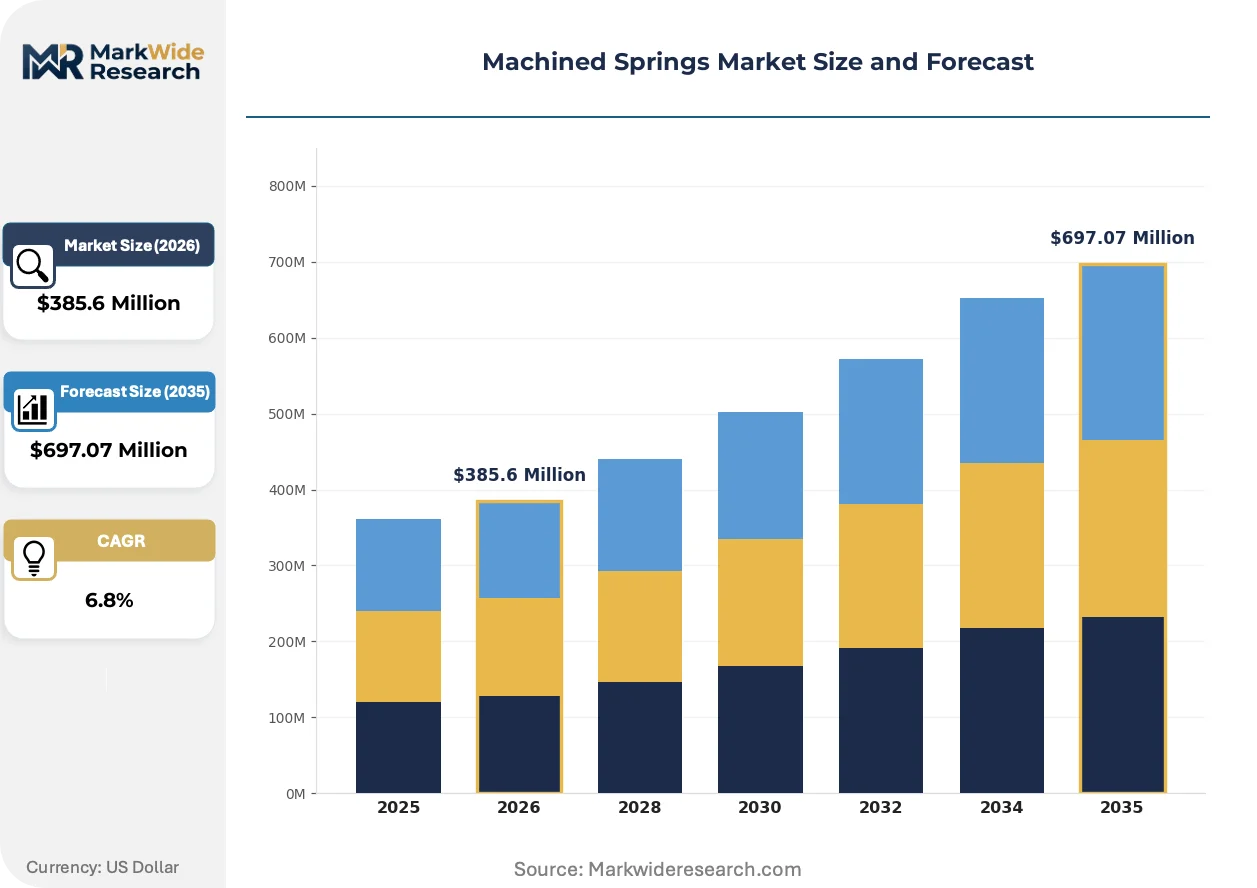
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Springs, Torsion Springs, Extension Springs, Constant Force Springs, Wave Springs Material: Stainless Steel, High Carbon Steel, Phosphor Bronze, Titanium Alloy, Inconel Application: Consumer Electronics, Aerospace Equipment, Agricultural Machinery, Mining Tools, Elevator Systems End User Industry: OEM Suppliers, Aftermarket Providers, Medical Device Manufacturers, Construction Contractors, Telecommunication Firms |
| Companies Covered | MW Industries, Inc., Smalley Steel Ring Company, Bal Seal Engineering, Inc., Associated Spring, Mubea, Inc., Tech Spring Manufacturing Corp., Helical Products Company, Lee Spring Company, Acxess Spring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machined Springs Market Trends and Innovations
Digital thread integration and hybrid manufacturing workflows are compressing design-to-test cycles, while regulatory pressure on material provenance reshapes supplier qualification criteria across aerospace and medical verticals.
Additive manufacturing of near-net-shape spring preforms is decomposing traditional bar-stock-to-finish machining sequences. Aerospace tier-one suppliers in Germany and the United States are piloting electron beam melting for Inconel 718 lattice structures, reducing titanium alloy waste by 40-60 percent and compressing lead times for low-volume flight hardware.
REACH Article 33 disclosure requirements are forcing alloy processors to document full substance composition down to 0.1 percent threshold. European spring fabricators are responding by consolidating supply chains around ECHA-registered mills with pre-validated SCIP database entries, raising barriers for non-EU competitors without established recycling partnerships.
Buyer consolidation among medical device OEMs is compressing supplier bases and extending contract durations. Three major orthopedic implant manufacturers now specify five-year machined spring agreements with locked pricing and volume commitments, displacing spot-market purchasing and favoring capital-intensive operators with validated cleanroom finishing capabilities in Ireland and Switzerland.
Machined Springs Market Segmentation
Machined springs compete against cold-formed wire alternatives across every specification tier, so substitution pressure varies sharply by precision requirement and load-cycle intensity. Segmentation reveals where bar-stock machining commands premium positioning versus where coiling retains cost advantage.
Product Type:
Compression and wave spring formats face the stiffest wire-coiling substitution pressure in non-critical industrial applications, while torsion and constant-force designs defend machining margins through geometric complexity.
- Compression Springs:Axial load-bearing coils machined from solid bar stock achieve ±0.001 inch free-length tolerance and superior squareness for aerospace landing gear and medical implant applications. Stuttgart engineering clusters anchor European fabrication capacity for flight-critical specifications where fatigue resistance disqualifies wire-formed alternatives.
- Wave Springs:Continuous spiral profiles with multiple turns occupy 50-70% less axial space than conventional coils, concentrating demand in semiconductor vacuum sealing and miniaturized consumer electronics where axial envelope constraints dominate design. Taiwan fab construction is accelerating specification upgrades for ultra-high-purity environments.
- Torsion Springs:Helical designs transmitting rotational force through machined end arms serve agricultural machinery and mining tool actuation where corrosion-resistant stainless grades outlast stamped alternatives in abrasive environments.
- Extension Springs:Tension-loaded coils with integral machined hooks or threaded inserts concentrate in elevator safety systems and industrial automation where hook fatigue governs replacement cycles.
- Constant Force Springs:Pre-stressed flat strip coils delivering uniform torque across deflection range serve cable retraction and counterbalance applications in medical device and telecommunications hardware.
Compression springs retain volume leadership across industrial and aerospace procurement; wave springs hold the steepest expansion curve driven by semiconductor capital equipment and electronics miniaturization.
Material:
Material selection stratifies by corrosion resistance requirement and regulatory exposure, with medical and aerospace procurement concentrating in certified alloy grades that command 3-5x carbon steel pricing.
- Stainless Steel:Austenitic 300-series and precipitation-hardened 17-7 PH grades dominate general industrial and food-processing applications where passivation and surface finish requirements align with machining workflows. German fabricators around Munich leverage local mill partnerships for certified 316L supply to marine and chemical processing OEMs.
- Titanium Alloy:Ti-6Al-4V ELI bar stock achieves specific strength ratios unmatched by ferrous alloys, with biocompatibility certification under FDA device regulations and ISO 13485 quality management anchoring demand in orthopedic and cardiovascular implant springs.
- Inconel:Nickel-chromium superalloy grades 718 and X-750 retain mechanical properties above 1200°F, serving aerospace turbine and exhaust applications where thermal cycling resistance mandates machined rather than formed construction.
- High Carbon Steel:Music wire and oil-tempered grades satisfy cost-sensitive agricultural and construction applications where corrosion protection through coating suffices and fatigue limits stay below machined spring thresholds.
- Phosphor Bronze:Copper-tin alloys with superior electrical conductivity and anti-galling properties serve switchgear and telecommunication connector springs where contact resistance and spark resistance govern material selection.
Stainless steel retains volume leadership across broad industrial procurement; titanium alloy holds the steepest expansion curve as medical device OEMs consolidate supplier bases around implant-grade certified mills.
Application:
Application segmentation tracks specification intensity, with aerospace and medical procurement demanding validated process documentation while elevator and mining applications prioritize unit cost over dimensional precision.
- Aerospace Equipment:Landing gear shock struts, flight control actuators, and engine mount systems specify Inconel and titanium machined springs with full material traceability and NDT certification. FAA airworthiness directives and OEM first-source approval processes extend qualification timelines to 24-36 months.
- Consumer Electronics:Miniaturized compression and wave springs for hinge mechanisms, battery contacts, and thermal management modules concentrate in Taiwan and South Korea contract manufacturing. Sub-millimeter wire diameters and million-cycle fatigue life specifications favor precision machining over micro-coiling.
- Elevator Systems:Safety gear and counterweight applications represent mature demand with established wire-spring supply chains, limiting machined spring penetration to high-rise installations with custom load requirements.
- Mining Tools:Drilling equipment and crushing machinery utilize high-carbon and alloy steel springs in abrasive environments where replacement frequency favors low-unit-cost procurement over extended fatigue life.
- Agricultural Machinery:Planter and harvester actuation springs face seasonal demand volatility and price sensitivity, with regional fabrication in India and Brazil serving localized equipment fleets.
Elevator systems retain volume leadership through installed base maintenance; aerospace equipment holds the steepest expansion curve as OEMs reshore critical component fabrication.
End User Industry:
End user concentration shapes contract structure, with medical device OEMs demanding multi-year agreements and aftermarket providers sustaining spot-market flexibility.
- Medical Device Manufacturers:Orthopedic implant, surgical instrument, and drug delivery system OEMs specify titanium and 316LVM grades with ISO 13485 process validation and FDA 21 CFR Part 820 quality system documentation. Three major orthopedic manufacturers now lock five-year machined spring agreements with volume commitments and fixed pricing.
- OEM Suppliers:Tier-one aerospace and industrial equipment manufacturers integrate machined springs into subassembly supply chains, with Stuttgart and Munich clusters serving German automotive and machinery OEMs through validated supplier development programs.
- Aftermarket Providers:Maintenance, repair, and overhaul operations in Indian aerospace hubs and North American industrial corridors sustain demand for reverse-engineered and catalog-standard springs with shorter lead times and lower documentation burdens.
- Construction Contractors:Heavy equipment fleet operators procure replacement springs through distributor channels, with price sensitivity and immediate availability outweighing specification precision for non-safety-critical applications.
- Telecommunication Firms:5G infrastructure and data center hardware deployment drives demand for phosphor bronze and beryllium copper contact springs with controlled impedance and electromagnetic shielding properties.
OEM suppliers retain volume leadership across capital equipment procurement; medical device manufacturers hold the steepest expansion curve as implantable device volumes climb and regulatory qualification barriers consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes machined springs primarily for aerospace and precision engineering, while the United States concentrates demand in medical device and defense applications, and Asian markets prioritize semiconductor capital equipment procurement.
United States
FAA airworthiness directives and defense procurement standards drive Inconel spring demand for landing gear and flight control systems. EPA hazardous air pollutant rules raise compliance costs for metalworking facilities. Connecticut and California aerospace clusters anchor specialized fabrication for military and commercial aviation programs.
Germany
Stuttgart and Munich engineering clusters serve automotive and aerospace OEMs through validated supplier development programs. REACH Article 33 disclosure requirements force alloy processors to document full substance composition. Baden-Württemberg precision fabricators are consolidating supply chains around ECHA-registered mills with pre-validated SCIP database entries.
China
Domestic aerospace build rates and semiconductor fab construction accelerate titanium and Inconel spring procurement. MIIT industrial standards and GB certification requirements shape local procurement criteria. Yangtze River Delta manufacturing hubs are developing captive machining capacity for C919 landing gear and domestic lithography equipment.
Japan
METI technology roadmaps prioritize precision component localization for semiconductor and robotics supply chains. JIS standards govern material certification and dimensional tolerances for critical applications. Nagoya aerospace suppliers and Osaka medical device manufacturers specify machined springs for implantable devices and industrial automation systems.
India
Bangalore and Hyderabad maintenance hubs are developing local machined spring sourcing for landing gear overhaul, reducing dependence on European airfreight. CDSCO medical device regulations and PLI scheme incentives attract precision component investment. Maharashtra industrial corridors host emerging fabrication capacity for domestic aerospace MRO and orthopedic implant supply chains.
Machined Springs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration into wire drawing and finished spring testing separating capital-intensive operators from job-shop competitors. The market structure favors players with validated cleanroom finishing capabilities and multi-year OEM contracts over spot-market participants. Two strategic archetypes dominate: full-process integrators controlling alloy sourcing through testing, and technology specialists commanding premium positioning through proprietary spring geometries. Competitive moves concentrate on backward integration into certified alloy supply and geographic expansion into Indian aerospace MRO hubs.
Among United States-based fabricators, MW Industries, Inc. and Bal Seal Engineering, Inc. occupy positions reflecting different strategic vectors, with the former exemplifying scale-driven integration and the latter representing technology-specialist positioning. Smalley Steel Ring Company anchors the continuous spiral and wave spring specialization tier. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive archetypes within the machined springs sector.
| Leading Market Players |
|---|
| MW Industries, Inc. |
| Smalley Steel Ring Company |
| Bal Seal Engineering, Inc. |
| Associated Spring |
| Mubea, Inc. |
| Tech Spring Manufacturing Corp. |
| Helical Products Company |
| Lee Spring Company |
| Acxess Spring |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German precision engineering clusters around Stuttgart and Munich sets price floors for aerospace-grade machined springs, with mill-scale alloy processing and validated cleanroom finishing creating natural segmentation between capital-intensive integrators and spot-market job shops. REACH-mandated material traceability and ISO 13485 validation timelines compress margins for non-integrated operators while locking in premium positioning for ECHA-registered suppliers with captive recycled alloy sourcing.
Pricing Analysis
Long-term offtake contracts dominate aerospace and medical device procurement, with five-year agreements featuring locked pricing and volume commitments displacing spot-market purchasing among orthopedic implant manufacturers. Price differentiation stems from certification grade—ISO 13485 and FDA 21 CFR Part 820 tiers command 3-5x carbon steel equivalents—and vertical integration into wire drawing and finished testing. Cost compression in standard industrial grades intensifies as cold-formed wire springs retain cost advantage in elevator systems and mining tools. Aftermarket providers and construction contractors exhibit highest price sensitivity, prioritizing immediate availability over dimensional precision.
Supply Chain Analysis
Germany and the United States anchor precision fabrication capacity for flight-critical and implant-grade specifications, with Stuttgart engineering clusters and Connecticut aerospace corridors serving validated OEM supply chains. Raw material flows draw from certified titanium alloy mills, Inconel bar stock processors, and ECHA-registered recycled alloy suppliers. Single-source vulnerability concentrates around German energy cost exposure and nickel superalloy price volatility tied to aerospace build rates. Distribution runs through tier-one subassembly integrators, direct hospital system contracts, and Indian MRO hub localization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machined spring incumbents face sustained substitution pressure from cold-formed wire alternatives in non-critical industrial applications, requiring defensive positioning around certification barriers and captive alloy processing to preserve margin architecture.
For Market Incumbents: Shield market position by deepening backward integration into certified recycled alloy supply under EU Green Deal carbon accounting rules, and by expanding cleanroom finishing capacity in Ireland and Switzerland to capture medical device OEM consolidation. Cold-formed wire cost advantages in elevator and mining applications threaten volume tiers; respond with multi-axis CNC programming apprenticeships and hybrid manufacturing workflows that compress design-to-test cycles for aerospace qualification. For New Entrants and Emerging Players: Aftermarket localization gaps in Indian aerospace MRO hubs present immediate white-space opportunity, with Bangalore and Hyderabad maintenance operations seeking reduced European airfreight dependence. Target semiconductor capital equipment sealing applications in Taiwan and South Korea fab construction, where canted coil spring technology adoption outpaces incumbent capacity. Go-to-market leverage rests on EPD-certified low-carbon alloy documentation and accelerated ISO 13485 validation partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical device spring manufacturers with locked five-year OEM agreements and validated cleanroom capabilities. Long-term viability over the projection horizon favors capital-intensive operators with ECHA-registered mill relationships and multi-axis CNC asset bases. Acquisition priority targets vertically integrated fabricators controlling wire drawing through finished testing; monitor Indian PLI scheme precision component incentives and C919 landing gear localization rates as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Alloy Supply | ECHA-registered recycled alloy sourcing creates qualification advantage under REACH Article 33 disclosure mandates. |
| Cleanroom Finishing Capacity Expansion | ISO 13485-validated facilities in Ireland and Switzerland capture medical device OEM supplier consolidation. |
| Indian Aerospace MRO Hub Localization | Bangalore and Hyderabad maintenance operations reduce European airfreight dependence for landing gear overhaul. |
| Hybrid Manufacturing Workflow Adoption | Additive-ready CNC-multi-axis production compresses design-to-test cycles for low-volume flight hardware. |
| EPD-Certified Low-Carbon Alloy Processing | Scope 3 emissions documentation aligns with EU Green Deal procurement criteria for premium positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, aerospace OEM procurement disclosures, and ECHA SCIP database entries, with input from precision machining plant managers, medical device procurement leads, aerospace tier-one supplier quality directors, and aftermarket MRO operations heads. Bottom-up sizing of CNC machining capacity and alloy consumption patterns triangulates against top-down aerospace build rate and medical device implant volume projections.
Segmentation dimensions modeled span product type, material grade, application specification intensity, and end-user industry concentration across the analysis window. CAGRs derive from regression of historical precision component demand against aerospace OEM reshoring rates, semiconductor capital expenditure cycles, and medical device regulatory qualification timelines. Industry-specific forecast inputs include titanium alloy biocompatibility certification velocity and Inconel 718 bar stock cost trajectories.
Forecasts assume regulatory continuity in REACH, FDA 21 CFR Part 820, and ISO 13485 regimes; material policy shifts in ECHA substance restrictions or FAA airworthiness directive scope would require re-modeling. Recalibration cycles align with material shifts in aerospace OEM first-source approval timelines and Indian PLI scheme precision component incentive disbursements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Port Equipment Market