
 Cam and Groove Fittings Market | 2026-2036
Cam and Groove Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Cam and Groove Fittings Market Insights
The EPA's National Emission Standards for Hazardous Air Pollutants is decoupling legacy brass fitting demand from new petrochemical infrastructure builds. Dixon Valve leverages captive brass forging capacity to sustain pricing power across North American distribution channels. PT Coupling anchors its position through deep backward integration into aluminum extrusion, while Campbell Fittings specializes in Mil-Spec certified product lines for defense fluid transfer applications.
Cam and groove fittings are quick-connect hose couplings employing a cam arm locking mechanism to seal male adapters to female couplers, typically manufactured through CNC machining, die casting, or injection molding depending on base material, with pressure ratings spanning 150 to 250 psi for standard industrial service. Aluminum couplings dominate volume in agricultural and construction fluid transfer due to favorable weight-to-cost ratios, while stainless steel adapters command premium positioning in chemical processing and food-grade applications where corrosion resistance and sanitary surface finishes justify higher unit economics. Polypropylene segments are gaining traction in water treatment and secondary containment systems where chemical inertness and electrical non-conductivity are specified.
OSHA's Process Safety Management standard and FDA's Current Good Manufacturing Practice regulations jointly shape material certification and pressure testing protocols across end-use industries. The EU REACH regulation restricts certain brass alloy compositions in European-sourced equipment, redirecting procurement toward stainless steel alternatives for export-compliant supply chains. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as gasket and seal material selections face intensifying regulatory scrutiny that could force redesign cycles across installed coupling bases.
Market Dynamics
EPA enforcement of the Clean Water Act is tightening material traceability mandates across industrial fluid transfer equipment, forcing procurement departments to requalify supplier bases and accelerating substitution toward stainless steel assemblies in corrosive service applications.
Growth Catalysts
- Texas-Louisiana Gulf Coast petrochemical expansion:New ethylene cracker and derivative plant construction is driving specification-grade stainless steel cam and groove procurement for high-pressure acid and caustic transfer lines.
- REACH brass alloy restrictions:EU regulations on lead content in brass fittings are redirecting export-oriented supply chains toward stainless steel alternatives, expanding addressable market for corrosion-resistant coupling manufacturers.
- Polypropylene gasket innovation:Advanced fluoropolymer-lined sealing systems are opening water treatment and secondary containment specifications previously closed to metallic couplings due to galvanic corrosion concerns.
Market Restraints
- Aluminum billet price volatility:Midwest aluminum premiums fluctuate with energy costs, compressing margin on volume agricultural and construction segments where aluminum dominates.
- Stainless steel scrap supply concentration:Domestic melt shop capacity concentrates in Indiana and Pennsylvania, creating geographic single-source risk for 316L and 304 alloy feedstock.
- Pressure rating ceiling:Cam arm locking mechanisms face inherent mechanical limits near 250 psi, excluding the technology from high-pressure hydraulic and compressed gas infrastructure.
Strategic Opportunities
- Per- and polyfluoroalkyl substance replacement:EPA and state-level PFAS restrictions on legacy gasket materials create redesign cycles and aftermarket upgrade revenue across installed coupling bases.
- Mil-Spec certification expansion:Defense fluid transfer specifications represent stable, long-contract demand with premium pricing and limited foreign competition due to ITAR constraints.
- Automated CNC machining cells:Lights-out production of stainless steel adapters reduces lot-size economics and enables rapid custom configuration for specialty chemical processors.
Industry Challenges
- Welder certification scarcity:Orbital welding of sanitary stainless steel fittings requires ASME Section IX qualified personnel, constraining capacity expansion in food-grade and pharmaceutical segments.
- Legacy brass inventory stranding:Distributors face write-down risk on non-REACH-compliant brass stock as European export demand shifts to certified alternatives.
- Multi-standard conformance complexity:Simultaneous compliance with OSHA Process Safety Management, FDA Current Good Manufacturing Practice, and EU Pressure Equipment Directive extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cam and Groove Fittings Market |
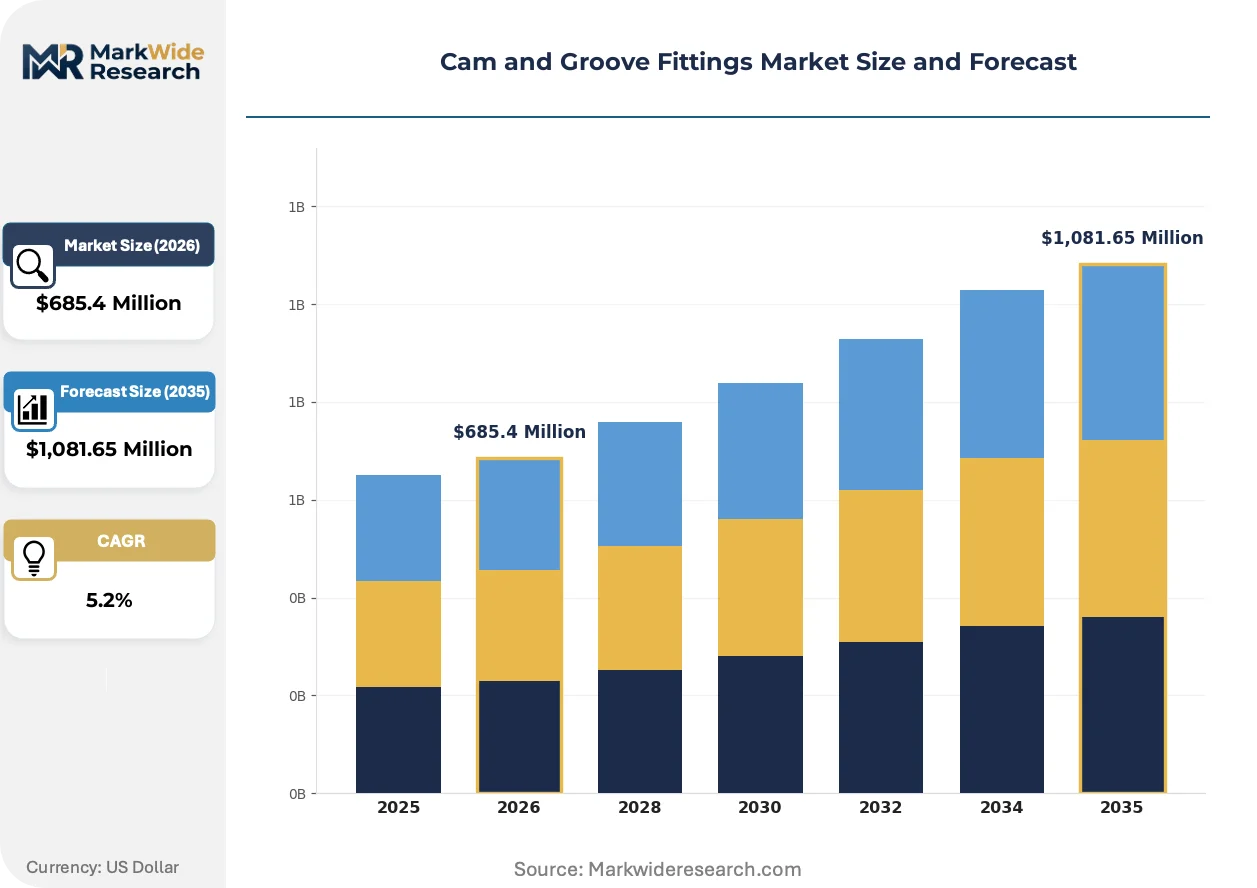
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Couplings, Caps, Adapters, Plugs, Clamps Material: Aluminum, Stainless Steel, Brass, Polypropylene, Carbon Steel Application: Chemical Processing, Food & Beverage, Petroleum, Construction, Agriculture End User Industry: Manufacturing Plants, Oil Refineries, Water Treatment Plants, Food Processing Units, Farms |
| Companies Covered | PT Coupling, Dixon Valve, Pro Flow Dynamics, Campbell Fittings, PAR Group, LMC Couplings, DME, Capital Rubber Corporation, NewAge Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cam and Groove Fittings Market Trends and Innovations
Digital thread integration across manufacturing and quality systems is compressing certification timelines and enabling lot-level traceability that satisfies tightening regulatory audit requirements.
Smart coupling systems embedding RFID tags and pressure sensors are unifying physical connection hardware with asset management platforms. Chemical processors in the Gulf Coast corridor are piloting these systems for predictive maintenance of critical transfer lines. The technology is unifying inventory tracking, inspection scheduling, and failure analysis into single-source data architectures that reduce unplanned downtime.
REACH substance restrictions on leaded brass alloys are forcing alloy reformulation across European-sourced equipment. Brass forging houses are investing in bismuth and silicon substitution chemistries to maintain machinability. North American exporters to EU markets are most affected, with stainless steel alternatives capturing specification share in food contact and potable water applications.
Specification-driven procurement consolidation is compressing distributor tiers. Large chemical and petrochemical operators are bypassing traditional wholesale channels to contract directly with forging houses and machine shops for certified lot production. This pattern concentrates most visibly in the Texas-Louisiana corridor where integrated operators demand mill-test-report traceability from melt to final assembly.
Cam and Groove Fittings Market Segmentation
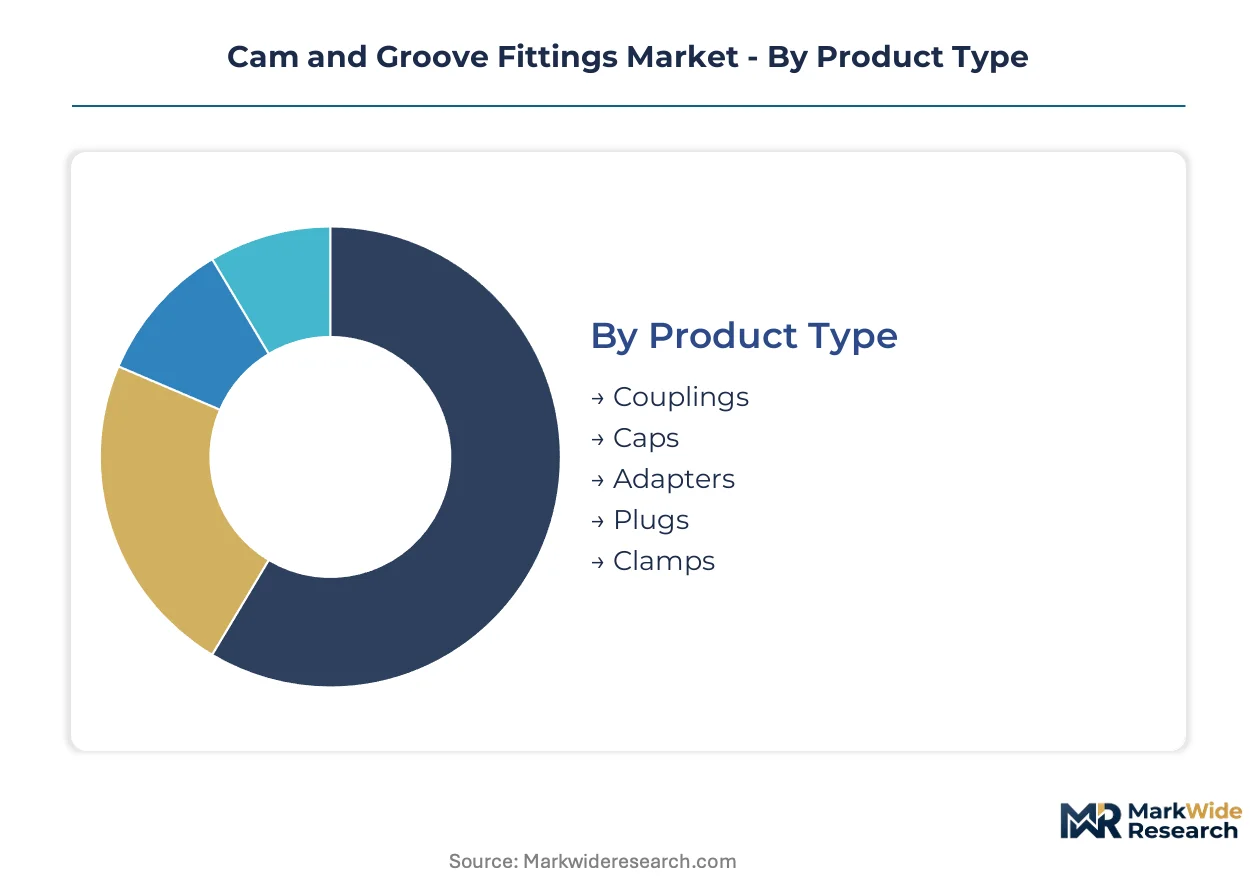
Cam and groove fittings serve distinct operational regimes where standalone quick-connect hardware dominates portable fluid transfer, while embedded assemblies integrate into fixed process infrastructure. Material selection, pressure rating, and regulatory compliance requirements fragment procurement patterns across end-use verticals.
Product Type:
Standalone couplings and adapters command the aftermarket replacement cycle, whereas caps and plugs function as embedded safety components within integrated hose assemblies.
- Couplings:Female receptacles with cam arm mechanisms form the connection nucleus in temporary fluid transfer setups. Texas-Louisiana Gulf Coast petrochemical operators specify 316L stainless steel variants for acid service lines under EPA Clean Water Act traceability mandates.
- Adapters:Male connection elements thread into hose barbs or pipe ends to complete seal interfaces. Chemical processing plants in the United States are expanding procurement of stainless steel assemblies for corrosive fluid handling where surface finish certification matters.
- Caps:Closure devices seal open coupler ends during transport and storage. Agricultural distributors favor aluminum caps for weight-sensitive field equipment.
- Plugs:Male-threaded sealing elements protect adapter faces from contamination. Food-grade polypropylene plugs serve secondary containment in water treatment systems.
- Clamps:Mechanical retention hardware secures cam arms under vibration. Mil-Spec certified clamps anchor defense fluid transfer specifications with ITAR-constrained sourcing.
Couplings lead volumes today; adapters are gaining share fastest in specification-grade petrochemical procurement.
Material:
Cost tier stratification separates commodity aluminum from premium stainless steel, with intermediate brass facing regulatory displacement and engineered polymers capturing niche electrical isolation applications.
- Aluminum:Extruded and CNC-machined alloys deliver favorable weight-to-cost ratios for agricultural and construction fluid transfer. Midwest aluminum premium volatility compresses margins on volume segments where this material dominates.
- Stainless Steel:304 and 316L grades command premium positioning in chemical processing and food-grade applications where corrosion resistance and sanitary surface finishes justify higher unit economics. Domestic melt shop capacity concentrates in Indiana and Pennsylvania, creating geographic single-source risk for alloy feedstock.
- Brass:Leaded and lead-free forgings face EU REACH restrictions redirecting export-oriented supply chains toward certified alternatives. Dixon Valve leverages captive brass forging capacity to sustain pricing power across North American distribution channels.
- Polypropylene:Injection-molded thermoplastic couplings provide chemical inertness and electrical non-conductivity for water treatment and secondary containment systems. Advanced fluoropolymer-lined sealing systems are opening specifications previously closed to metallic couplings.
- Carbon Steel:Zinc-plated or coated variants serve cost-constrained industrial applications where corrosion exposure remains limited. Construction equipment rental fleets specify carbon steel for short-duty cycle deployment.
Aluminum retains the largest installed base; polypropylene is climbing the fastest as water treatment infrastructure expands.
Application:
Customer type fragmentation separates process industry procurement—driven by regulatory compliance—from seasonal agricultural demand and project-based construction cycles.
- Chemical Processing:High-pressure acid and caustic transfer lines in ethylene cracker facilities demand full material traceability from melt to final assembly. Specification-driven procurement consolidation is compressing distributor tiers in this vertical.
- Food & Beverage:Sanitary surface finish requirements and FDA Current Good Manufacturing Practice regulations shape material certification protocols. ASME Section IX qualified welders for orbital welding of sanitary fittings remain scarce, constraining capacity expansion.
- Petroleum:Downstream refining and midstream terminal operations specify hardened alloys for hydrocarbon service. The Texas-Louisiana Gulf Coast corridor concentrates demand for specification-grade stainless steel procurement.
- Construction:Temporary dewatering and concrete pumping applications favor aluminum for portability. Equipment rental fleets drive replacement demand on damage-prone job sites.
- Agriculture:Irrigation and liquid fertilizer transfer systems prioritize weight reduction and cost minimization. Seasonal demand patterns create inventory management challenges for distributors.
Chemical processing commands the highest value per unit; food and beverage is expanding most quickly behind regulatory upgrade cycles.
End User Industry:
Facility scale and operational criticality determine whether procurement flows through integrated direct contracts or fragmented wholesale channels.
- Manufacturing Plants:Integrated chemical and specialty material producers bypass traditional distribution to contract directly with forging houses for certified lot production. Mill-test-report traceability is non-negotiable in this segment.
- Oil Refineries:Gulf Coast downstream operators specify stainless steel assemblies for process-critical transfer lines. Predictive maintenance pilot programs embedding RFID-tagged smart couplings are unifying inventory tracking with asset management platforms.
- Water Treatment Plants:Secondary containment and chemical dosing systems specify polypropylene for galvanic corrosion avoidance. EPA enforcement of the Clean Water Act is tightening material traceability mandates across this infrastructure class.
- Food Processing Units:Dairy, beverage, and prepared food facilities demand sanitary finishes with documented surface roughness certification. Multi-standard conformance with FDA and EU Pressure Equipment Directive extends product development timelines.
- Farms:Individual and cooperative agricultural operations purchase through dealer networks with seasonal credit terms. Aluminum couplings dominate volume due to favorable weight-to-cost ratios for field-portable equipment.
Manufacturing plants generate the highest contract values; water treatment plants are gaining procurement share fastest behind infrastructure investment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cam and groove fittings trace their industrial lineage to mid-20th century American petroleum handling, where Gulf Coast refineries pioneered quick-connect standards for hazardous fluid transfer. The technology subsequently diffused through NATO military specifications and European chemical processing standards, establishing transatlantic design conventions that persist today.
United States
Texas-Louisiana Gulf Coast petrochemical operators drive specification-grade stainless steel procurement for ethylene cracker acid transfer lines. EPA Clean Water Act enforcement tightens material traceability mandates across industrial fluid transfer equipment. Houston-Beaumont-Port Arthur corridor concentrates demand for mill-test-report certified assemblies from melt to final fabrication.
Germany
Ruhr Valley chemical processors and Bavarian specialty material producers anchor European demand for corrosion-resistant coupling systems. EU REACH regulation restricts lead content in brass alloys, redirecting procurement toward certified stainless steel alternatives. Ludwigshafen-Basel industrial cluster demands full regulatory documentation for export-compliant supply chains.
China
Yangtze River Delta and Pearl River Delta manufacturing bases consume aluminum and carbon steel variants for construction equipment and agricultural machinery. MIIT industrial standards and GB certification protocols shape domestic procurement specifications. Shanghai-Suzhou manufacturing corridor concentrates injection-molded polypropylene production for water treatment applications.
India
Gujarat and Maharashtra chemical processing corridors expand stainless steel fitting imports for corrosive service infrastructure. BIS certification requirements and DGFT import regulations govern material quality protocols. Mumbai-Pune industrial belt drives specification-grade procurement from European and East Asian suppliers.
United Arab Emirates
Dubai and Abu Dhabi petrochemical terminals specify hardened alloy couplings for hydrocarbon export infrastructure. UAE national oil company procurement standards exceed baseline API specifications for critical transfer applications. Jebel Ali industrial zone serves as redistribution hub for Middle East and African markets.
Cam and Groove Fittings Market Competitive Landscape
Capital-heavy producers with captive forging and extrusion capacity compete with asset-light designers outsourcing fabrication to certified machine shops. The vendor base stratifies across three tiers: integrated forging houses commanding premium specification work, mid-scale CNC specialists serving regional distribution, and commodity assemblers competing on aluminum volume. Two dominant competitive moves define current positioning: backward integration into aluminum extrusion and brass forging to secure margin control, and direct contracting with large chemical operators to bypass wholesale channels.
Within the integrated forging tier, Dixon Valve and PT Coupling occupy positions shaped by captive manufacturing assets. Dixon Valve exemplifies brass forging specialists leveraging in-house capacity to sustain pricing power across North American distribution channels. PT Coupling represents aluminum extrusion-integrated fabricators controlling upstream material flow. Campbell Fittings anchors the defense-specialist archetype, with Mil-Spec certification positioning it for ITAR-constrained procurement. These three patterns—brass forging integration, aluminum extrusion control, and military specification focus—capture the structural diversity of competitive positioning.
| Leading Market Players |
|---|
| PT Coupling |
| Dixon Valve |
| Pro Flow Dynamics |
| Campbell Fittings |
| PAR Group |
| LMC Couplings |
| DME |
| Capital Rubber Corporation |
| NewAge Industries |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between 316L stainless steel assemblies and commodity aluminum extrusions manifests in parallel supply chain configurations: premium-tier procurement bypasses wholesale channels for direct mill-test-report contracting, while volume agriculture and construction segments flow through distributor tiers vulnerable to Midwest aluminum premium volatility. EPA Clean Water Act traceability mandates reinforce this bifurcation by concentrating specification-grade demand around captive forging capacity in Indiana and Pennsylvania melt shops.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Mil-Spec certified stainless steel from commercial-grade aluminum and polypropylene alternatives. Price differentiation hinges on material certification depth and pressure rating compliance, with 316L assemblies commanding substantial premiums for acid service documentation. Cost compression in aluminum segments intensifies because energy-linked billet volatility erodes distributor margins on agricultural volume. Construction equipment rental fleets exhibit highest price sensitivity, while Gulf Coast petrochemical operators prioritize traceability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from integrated chemical operators mandate qualified supplier redundancy across stainless steel feedstock and brass forging capacity. Geographic supply concentration centers on domestic melt shops in Indiana and Pennsylvania for 316L and 304 alloys, with aluminum extrusion anchored in Midwest energy corridors. Raw material dependencies rest on nickel-chromium alloy feedstock, aluminum billet premiums, and polypropylene resin from petrochemical derivatives. Single-source vulnerability concentrates in orbital welding certification scarcity for sanitary fittings. Distribution runs through forging house direct contracts for specification-grade procurement and regional wholesale channels for commodity volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in stainless steel specification-grade tiers where EPA traceability mandates and REACH brass restrictions accelerate substitution toward premium-certified alternatives. Automated CNC machining cells and fluoropolymer-lined sealing innovation compress production economics for compliant producers.
For Market Incumbents: Acquire captive aluminum extrusion and brass forging assets to insulate margin from Midwest premium volatility and EU alloy restrictions. Defensive consolidation moves center on qualifying secondary stainless steel melt sources in Pennsylvania and Indiana to mitigate geographic single-source risk, while embedding RFID-enabled smart coupling systems anchors predictive maintenance revenue streams against commodity price erosion. For New Entrants and Emerging Players: EPA PFAS restrictions on legacy gasket materials open a window for fluoropolymer-lined polypropylene coupling penetration in water treatment and secondary containment specifications previously closed to metallic alternatives. White-space targets concentrate on automated small-lot CNC production for specialty chemical processors demanding rapid custom configuration, with go-to-market execution through direct contracting with Texas-Louisiana Gulf Coast operators seeking mill-test-report traceability. For Investors and Strategic Acquirers: Consolidation pressure builds where distributor tier compression and direct procurement consolidation strand legacy brass inventory and marginal aluminum extrusion capacity. Long-term viability favors vertically integrated forging houses with captive melt shop relationships and ITAR-constrained Mil-Spec certification moats. Acquisition target archetypes include regional CNC specialists with ASME Section IX welding qualification and established chemical processor relationships. The signal to watch is distributor write-down velocity on non-REACH-compliant brass stock as European export demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captures margin control against Midwest premium volatility for agricultural volume segments. |
| Automated CNC Machining Cell Deployment | Enables lights-out production of stainless steel adapters for specialty chemical processors. |
| Fluoropolymer-Lined Sealing System Development | Opens water treatment specifications previously closed to metallic couplings by galvanic corrosion concerns. |
| Mil-Spec Certification Expansion | Secures ITAR-constrained defense procurement with premium pricing and limited foreign competition. |
| RFID-Enabled Smart Coupling Integration | Unifies inventory tracking with predictive maintenance platforms for Gulf Coast petrochemical operators. |
Research Methodology
Direct dialogue with plant engineers, procurement leads at downstream chemical processors, distribution channel partners, and aftermarket service heads grounded qualitative assessment in operational reality. Secondary validation drew from EPA enforcement disclosures, SEC 10-K filings of integrated forging houses, customs trade data on alloy feedstock flows, and OSHA Process Safety Management audit records. Bottom-up demand modeling across end-use verticals triangulated against top-down macroeconomic indicators to establish baseline projections.
Segmented outputs across material tier, pressure rating class, end-use industry, and regional regulatory cluster fed into analytical framework spanning the projection horizon. CAGRs derived from regression analysis against industrial capital expenditure cycles and infrastructure investment trajectories. Industry-specific forecast inputs incorporated ethylene cracker construction pipelines in the Texas-Louisiana corridor and water treatment infrastructure appropriation trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum premium spike conditions or accelerated PFAS restriction timelines. Projections reflect assumptions on regulatory enforcement velocity and melt shop capacity expansion schedules. Deviation in stainless steel scrap supply concentration or orbital welder certification availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
North America Conveyor Belt Market