
 Hoist Market | 2026-2036
Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Hoist Market Outlook
Heavy-duty wire rope specifications are rotating toward higher fatigue-resistance grades as infrastructure projects demand longer service intervals. Konecranes leverages its Scandinavian engineering heritage to dominate harbor crane integrations. Zoomlion Heavy Industry Science & Technology Co., Ltd. anchors its position through massive production scale across Chinese industrial zones. Tadano Ltd. differentiates via all-terrain mobile crane hoists that serve Japanese construction standards.
A hoist is a mechanical lifting device comprising a drum or lift-wheel around which rope or chain wraps, powered by electric, hydraulic, or pneumatic motors to raise, lower, or suspend loads with precision control through brake systems and gearing ratios. Its primary purpose centers on vertical material handling in industrial, construction, and logistics operations where manual lifting exceeds safety or capacity thresholds. Wire rope hoists capture premium margin pools in heavy-lift applications above ten tons, while electric hoists lead volume across manufacturing end users due to energy efficiency and programmable control integration. Chain hoists sustain steady replacement demand in construction and mining sectors where portability and spark-resistant operation prove essential.
OSHA crane and derrick standards in the United States mandate operator certification and equipment inspection protocols that elevate compliance costs but filter subscale suppliers from project bidding pools. The EU Machinery Directive and CE marking requirements enforce fail-safe brake systems and emergency stop functionality, reshaping product development roadmaps for European-bound manufacturers. China's SAMR administers GB standards for lifting machinery safety that align with international norms while preserving domestic certification pathways. Stakeholders must monitor how carbon-border adjustments and local-content rules in major economies reshape sourcing decisions for hoist motors and steel components.
Market Dynamics
Electric motor architectures are decomposing traditional powertrain hierarchies in material handling equipment, compressing maintenance intervals and rewiring supplier relationships across industrial procurement channels.
Growth Catalysts
- OSHA crane and derrick mandates:United States construction fleets must expand powered lifting capacity to meet operator certification and inspection protocols, filtering subscale suppliers from federal project bidding pools.
- Port modernization corridors:China's eastern manufacturing belt is accelerating demand for heavy-duty wire rope specifications as container throughput expansion requires longer service intervals.
- CE marking integration:The EU Machinery Directive enforces fail-safe brake systems and emergency stop functionality, reshaping product development roadmaps for European-bound hoist manufacturers.
Market Restraints
- Steel input volatility:Fluctuations in high-grade alloy pricing compress margin predictability for drum and lift-wheel fabricators serving infrastructure contractors.
- Supply concentration risk:Specialty wire rope manufacturing clusters in limited geographic zones create vulnerability when logistics disruptions hit heavy-lift component sourcing.
- Pneumatic displacement friction:German automotive assembly plants face capital recovery timelines when retiring compressed-air infrastructure for electric hoist architectures.
Strategic Opportunities
- Carbon-border alignment:China's dual carbon goals and SAMR-administered GB standards create certification pathways for hoist motor suppliers meeting international efficiency benchmarks.
- Aftermarket service unbundling:Predictive maintenance platforms using IoT-enabled load monitoring open recurring revenue streams independent of original equipment sales cycles.
- Spark-resistant specification gaps:Mining sector safety requirements in extraction zones lacking compliant chain hoist penetration represent white space for explosion-proof product lines.
Industry Challenges
- Certification timeline compression:CE marking and OSHA compliance documentation requirements extend product launch cycles, delaying revenue recognition for new hoist architectures.
- Legacy system integration friction:Programmable electric controls must interface with existing crane management systems in aging industrial facilities, complicating deployment engineering.
- Specialized technician scarcity:Advanced brake system diagnostics and variable-frequency drive calibration demand skills absent from traditional mechanical maintenance workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoist Market |
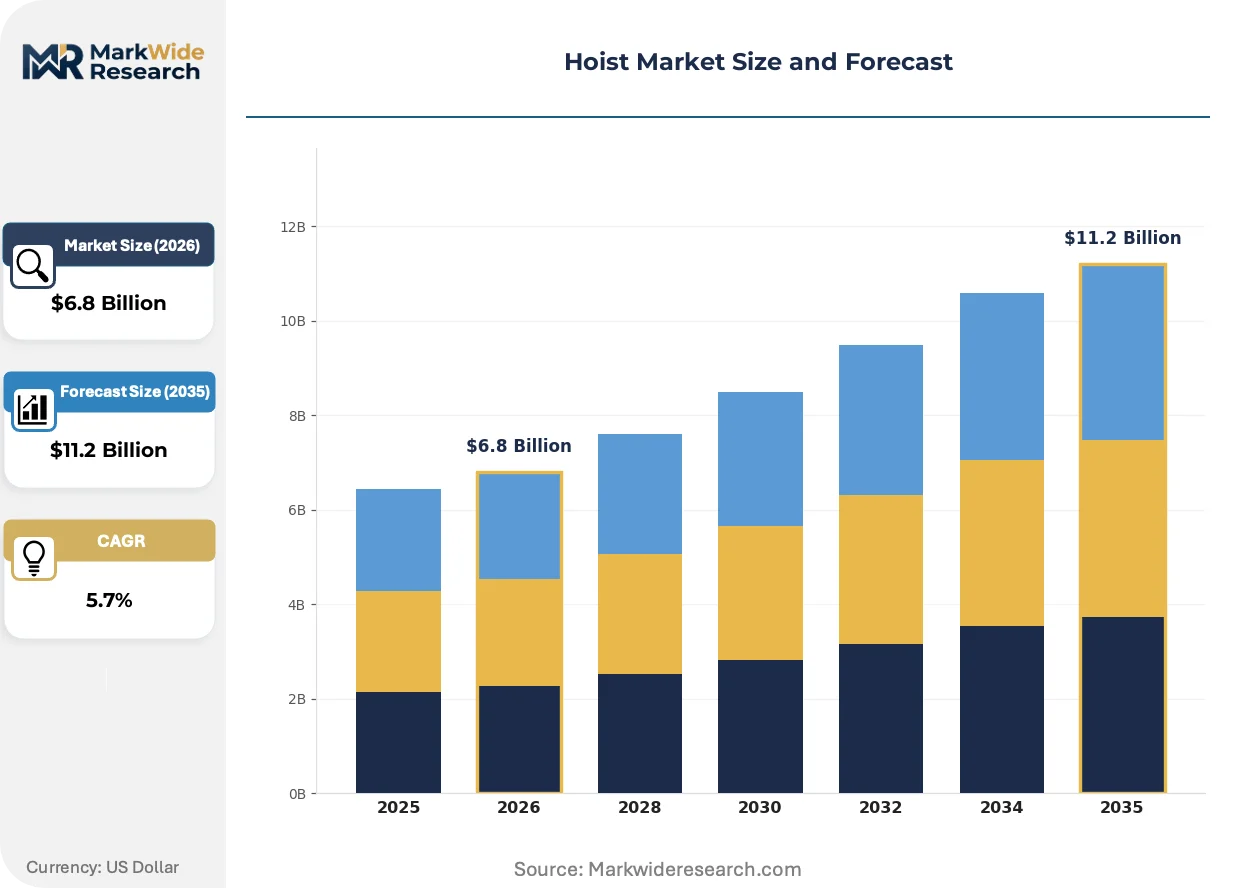
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Hoists, Chain Hoists, Wire Rope Hoists, Air Hoists End User: Manufacturing, Construction, Shipping, Mining Technology: Hydraulic, Pneumatic, Electric, Manual Capacity: Up to 1 Ton, 1-5 Tons, 5-10 Tons, Over 10 Tons |
| Companies Covered | Tadano Ltd., Zoomlion Heavy Industry Science & Technology Co., Ltd., Konecranes, KITO, Harrington Hoists, Liebherr, The Manitowoc Company, Inc., Jentan, Demag Cranes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoist Market Strategic Shifts
Digitalization of load monitoring and control systems is fragmenting traditional equipment procurement into hardware-software bundles, forcing manufacturers to restructure R&D allocation toward embedded electronics competencies.
Variable-frequency drive technology is decomposing fixed-speed motor dominance in industrial hoisting applications. Assembly plants in the German automotive sector are adopting these systems to enable precision positioning with reduced mechanical wear. The technology is compressing traditional gearbox maintenance revenue pools while expanding software-enabled service contract opportunities.
The EU Machinery Directive's fail-safe brake mandates are forcing redesign of emergency stop architectures across European-bound product lines. Manufacturers must integrate redundant braking circuits and diagnostic feedback loops to maintain CE marking eligibility. Harbor crane integrators serving Rotterdam and Hamburg ports face the steepest compliance recertification costs due to duty-cycle intensity requirements.
Buyers in United States construction fleets are unbundling after-sales service from capital equipment contracts, preferring third-party maintenance providers with OSHA-certified inspection capabilities. This fragmentation is eroding manufacturer-captive service revenue and redirecting margin toward specialized inspection firms. The shift is most visible in infrastructure projects along the Gulf Coast where contractor specialization has accelerated.
Hoist Market Segmentation
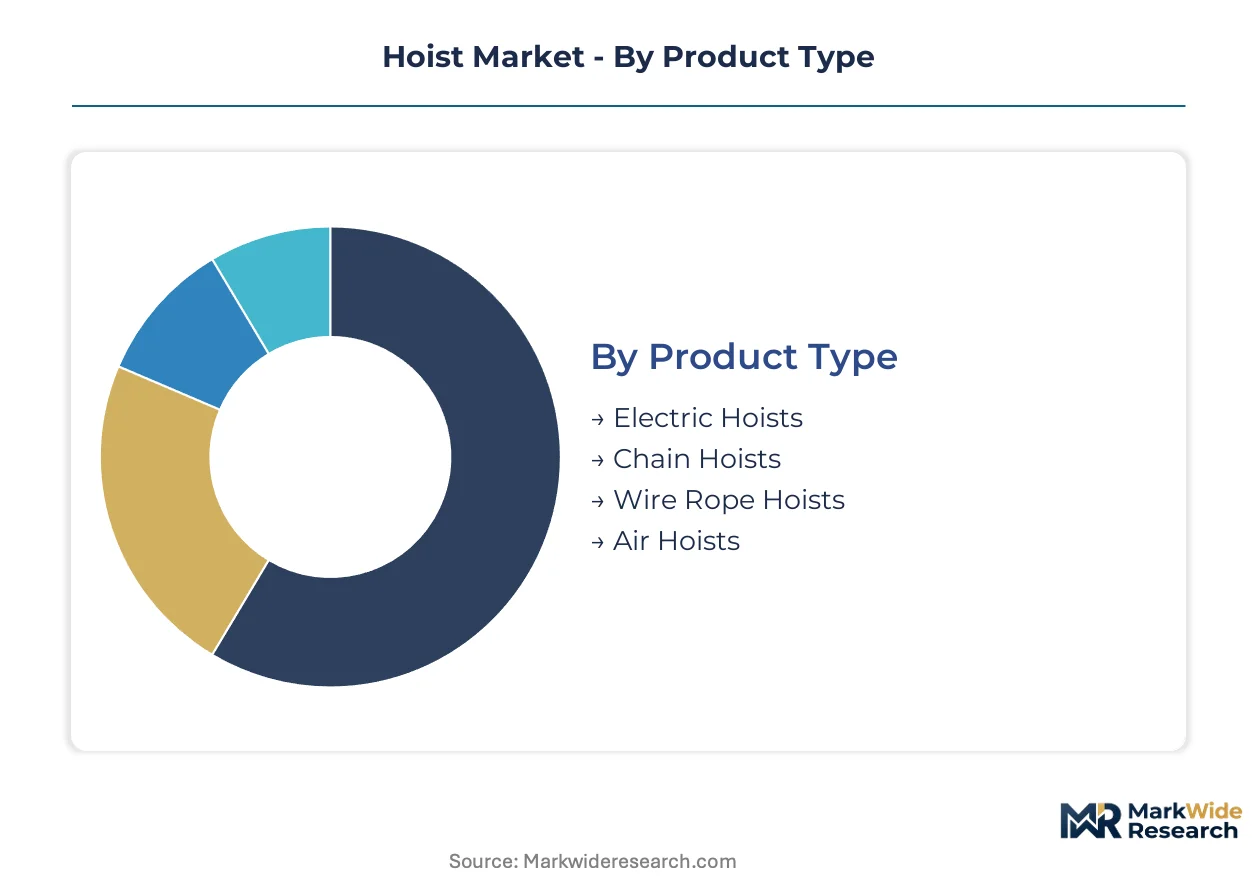
Hoist procurement decisions fragment across four critical dimensions where specification mismatches create costly downtime. Product architecture determines maintenance cadence and energy consumption. End-use verticals impose divergent duty-cycle and safety requirements. Technology choice locks facilities into specific infrastructure investments. Capacity tiers separate commodity replacement demand from engineered heavy-lift systems.
Product Type:
Margin pools concentrate in wire rope specifications serving infrastructure contractors with extended service-interval demands.
- Electric Hoists:Motor-driven drum or chain mechanisms with programmable variable-frequency drives enable precision positioning in automated assembly environments. German automotive plants favor these architectures for energy efficiency and reduced mechanical wear compared to pneumatic alternatives.
- Wire Rope Hoists:Multi-strand cable configurations wrapped around grooved drums deliver fatigue-resistant lifting above ten tons. China's eastern port modernization corridors drive specification upgrades toward higher-grade wire constructions.
- Chain Hoists:Linked metal configurations offering spark-resistant operation for hazardous extraction zones. Portable units sustain replacement cycles in construction and mining sectors.
- Air Hoists:Compressed-air motor systems retaining niche presence where explosion-proof ratings exceed electric alternatives. Capital recovery timelines extend replacement decisions in facilities with sunk pneumatic infrastructure.
The dominant share belongs to electric hoists, while wire rope hoists are closing the gap fastest.
End User:
Application concentration shapes procurement patterns where duty-cycle intensity determines specification premiums.
- Manufacturing:Assembly line integration demands programmable controls with synchronized crane management systems. Electric architectures dominate volume through energy efficiency mandates and IoT-enabled predictive maintenance adoption.
- Construction:OSHA crane and derrick compliance requirements filter subscale suppliers from federal project bidding pools. Mobile and tower crane integrations drive demand for certified inspection documentation.
- Shipping:Harbor crane duty cycles in Rotterdam and Hamburg ports impose steepest CE marking recertification costs due to fail-safe brake mandates. Container throughput expansion concentrates in China's eastern manufacturing belt.
- Mining:Extraction zone safety requirements create specification gaps where explosion-proof chain hoist penetration remains limited. Spark-resistant operation proves essential for underground deployment.
Manufacturing captures the largest volume share, with shipping expanding most quickly on port modernization investments.
Technology:
Powertrain selection locks facilities into infrastructure investment trajectories with diverging maintenance economics.
- Electric:AC and DC motor systems with solid-state controls displacing fixed-speed dominance. Variable-frequency drive adoption compresses traditional gearbox maintenance revenue pools while expanding software-enabled service contracts.
- Hydraulic:Fluid-power systems delivering high torque density for heavy-lift applications. Niche presence persists where load precision requirements exceed electric motor responsiveness.
- Pneumatic:Compressed-air motors retaining position in explosion-critical environments. German automotive assembly plants face capital recovery timelines when retiring legacy infrastructure.
- Manual:Hand-chain and lever mechanisms for maintenance access and low-frequency lifting. Construction sectors favor portability where powered supply proves impractical.
Electric technology holds commanding position, as hydraulic systems gain share in specialized heavy-lift niches.
Capacity:
Tonnage thresholds separate commodity replacement markets from engineered system procurement with extended qualification cycles.
- Over 10 Tons:Engineered wire rope configurations with redundant braking and diagnostic feedback loops for harbor crane and infrastructure applications. CE marking and OSHA compliance documentation extend product launch cycles.
- 5-10 Tons:Mid-range electric and chain hoists serving manufacturing and construction fleets. Standardized specifications enable competitive sourcing across multiple qualified suppliers.
- 1-5 Tons:Volume concentration in general manufacturing and warehouse operations. Electric architectures dominate through energy efficiency and programmable control integration.
- Up to 1 Ton:Portable chain and electric units for maintenance tasks and light assembly. Replacement demand sustains steady aftermarket parts and service revenue.
The 1-5 ton range maintains volume leadership, while over 10 ton specifications show steepest expansion trajectory on infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese hoist manufacturers export heavily into Southeast Asian port modernization projects, while German engineering houses supply precision lifting systems to automotive assembly plants across Central Europe.
United States
Construction fleet operators face OSHA crane and derrick mandates requiring expanded powered lifting capacity and certified inspection documentation. Federal infrastructure spending filters subscale suppliers from project bidding pools. Gulf Coast contractors concentrate demand for mobile crane hoist integrations with third-party maintenance unbundling.
Germany
Automotive assembly plants in Baden-Württemberg and Bavaria displace pneumatic infrastructure with electric hoist architectures featuring variable-frequency drives. CE marking requirements under the EU Machinery Directive enforce fail-safe brake systems and emergency stop functionality. Stuttgart and Munich industrial zones drive specification upgrades for precision positioning systems.
China
SAMR-administered GB standards for lifting machinery safety align with international norms while preserving domestic certification pathways. Port modernization accelerates demand for heavy-duty wire rope specifications in Shanghai, Ningbo, and Shenzhen container terminals. Eastern manufacturing belt throughput expansion requires longer service interval engineering.
Japan
METI industrial standards shape domestic crane and hoist safety protocols for all-terrain mobile applications. Construction sector procurement favors equipment meeting Japanese duty-cycle intensity requirements. Osaka and Nagoya manufacturing clusters sustain replacement demand for integrated crane management systems.
India
BIS certification requirements for lifting equipment create compliance barriers for non-standard imports. Manufacturing sector expansion in Gujarat and Maharashtra drives electric hoist volume for automated assembly environments. Mumbai and Ahmedabad industrial corridors concentrate demand for mid-capacity programmable control systems.
Hoist Market Competitive Environment
Listed leaders compete with private specialists across certification and scale dimensions, producing a tiered structure where engineering heritage separates premium integrators from commodity fabricators. Consolidation pressure concentrates harbor crane and heavy-lift segments, while mid-capacity manufacturing remains fragmented across regional suppliers. Two archetypes dominate: Scandinavian engineering houses leveraging maritime integration expertise, and Chinese scale players capturing volume through production corridor proximity. Competitive moves center on predictive maintenance platform development and carbon-border alignment for motor efficiency certification.
Within the engineering-heritage tier, Konecranes and Tadano Ltd. occupy positions defined by maritime and mobile crane specialization respectively. Zoomlion Heavy Industry Science & Technology Co., Ltd. anchors the scale-driven segment through production concentration in Chinese industrial zones. These three exemplify how geographic origin and corporate structure shape competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| Tadano Ltd. |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Konecranes |
| KITO |
| Harrington Hoists |
| Liebherr |
| The Manitowoc Company, Inc. |
| Jentan |
| Demag Cranes |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization disparities between Chinese scale fabricators and European precision engineering houses create divergent cost floors that reshape competitive entry barriers across tonnage tiers. High-volume electric motor production in eastern Chinese industrial zones compresses unit economics for standard-capacity hoists, while specialized wire rope manufacturing in Germany and Japan sustains premium positioning through fatigue-resistance certification tiers.
Pricing Analysis
Variable-frequency drive technology commands a generational pricing premium over fixed-speed electric architectures, while pneumatic legacy systems trade at depreciation-driven discounts in facilities facing capital recovery timelines. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked harbor crane integrations from OSHA-compliant construction fleet specifications and uncertified replacement units. Pricing pressure stems from steel alloy input volatility eroding drum fabricator margins. Construction contractors exhibit highest price sensitivity due to third-party maintenance unbundling, while port operators accept premium tiers for extended service interval engineering.
Supply Chain Analysis
Extended lead times for specialty wire rope configurations from German and Japanese manufacturing clusters force inventory pre-positioning among harbor crane integrators serving Rotterdam and Hamburg. High-grade alloy steel draws from Chinese, German, and South Korean metallurgical capacity. Supply chain risk centers on single-source vulnerability for fatigue-resistant cable constructions certified to EU Machinery Directive standards. Distribution runs through OEM-anchored dealer networks for heavy-lift specifications, while mid-capacity electric units flow through industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and capacity bands creates niche entry points for specialists as unbundled aftermarket service redirects margin away from integrated manufacturers. Predictive maintenance platform adoption splits procurement decisions between hardware and software vendors.
For Market Incumbents: Shield harbor crane integration revenue through captive wire rope supply agreements with Japanese and German specialty manufacturers. Vertical integration into IoT-enabled load monitoring software defends against third-party service providers capturing inspection documentation margins. Prioritize CE marking recertification investment to maintain eligibility for EU port modernization contracts. For New Entrants and Emerging Players: OSHA certification fast-track programs for mobile crane hoist operators open bidding access to Gulf Coast federal infrastructure projects. Mining sector spark-resistant chain hoist specifications in extraction zones lacking compliant penetration represent the most penetrable white space. Target aftermarket parts distribution for 1-5 ton electric units through direct procurement relationships with maintenance directors at Midwest manufacturing plants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance platform providers with IoT-enabled diagnostic feedback loops integrated into variable-frequency drive systems. Five-to-ten year viability favors acquisition targets combining Chinese production scale with European certification heritage. Monitor carbon-border adjustment implementation timelines as inflection indicators for motor efficiency certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | IoT-enabled load monitoring creates recurring revenue independent of equipment sales cycles. |
| CE Marking Recertification Investment | Fail-safe brake compliance maintains eligibility for EU harbor crane integration contracts. |
| Backward Integration into Wire Rope Supply | Captive sourcing of fatigue-resistant cable secures margin pools in heavy-lift specifications. |
| OSHA Certification Fast-Track Programs | Operator credentialing opens federal project bidding access for construction fleet suppliers. |
| Carbon-Border Alignment for Motor Efficiency | SAMR-administered GB standards certification preserves Chinese export competitiveness. |
Study Parameters
The analysis maps electric, wire rope, chain, and air hoist architectures, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with harbor crane integrators in Rotterdam, Hamburg, and Shanghai combined with secondary validation from customs trade data, SEC filings of listed equipment manufacturers, SAMR certification databases, and OSHA compliance records. Bottom-up capacity and shipment estimates triangulate against top-down infrastructure spending allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-use vertical, powertrain technology, and capacity tier. CAGRs derive from installed base replacement cycles and infrastructure investment trajectories. Forecast inputs incorporate port container throughput expansion rates and automotive assembly plant automation adoption patterns.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA enforcement and EU Machinery Directive continuity; material deviation in regulatory stringency would warrant model refresh. Steel price volatility and logistics disruption scenarios present specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Pneumatic Conveying Diverters Market