
 Mill Liner Market | 2026-2036
Mill Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Mill Liner Market Intelligence
Copper extraction operations is hardening demand for high-wear mill liner systems across South American and African mining corridors. Metso Outotec leverages its integrated foundry-to-field service network to dominate large-diameter SAG mill retrofits. Tega Industries anchors its position through specialized rubber-metal composite formulations tailored to tropical ore abrasiveness. Bradken competes aggressively in the aftermarket segment with rapid-delivery liner kits designed for 72-hour changeout windows.
Mill liners are engineered protective shells installed inside grinding mills to shield the steel shell from abrasive ore impact while optimizing lift and trajectory of the charge. High manganese steel variants typically contain 11-14% manganese content to achieve work-hardening surfaces that reach 550 BHN under operational stress, with rubber composite inserts reducing noise and impact damage in secondary grinding stages. Chrome steel segments command premium positioning in high-impact primary milling where ore hardness exceeds 15 kWh/t, while polyurethane formulations represent the fastest-growing niche in fine-grinding circuits seeking reduced liner mass and faster installation. Ball mill applications remain the mature volume base, though SAG mill liners concentrate margin pools due to custom engineering requirements and shorter replacement intervals.
ISO 9001 quality management standards govern liner casting consistency across export-oriented foundries, while Australia's WHS regulations and Chile's DS 594 mine safety codes mandate documented liner integrity inspections at prescribed intervals. The EU's REACH framework restricts certain alloying element imports, pushing European end-users toward certified domestic suppliers with full material traceability. Stakeholders must monitor ore grade deterioration trends and corresponding liner wear acceleration to calibrate inventory and procurement strategies.
Market Dynamics
Ore grade deterioration across mature copper belts is compressing liner replacement cycles and forcing procurement teams to recalibrate inventory buffers against unplanned downtime costs.
Growth Catalysts
- DS 594 mine safety codes:Chile's mandatory liner integrity inspections at prescribed intervals accelerate planned replacement schedules and expand addressable aftermarket volume.
- Polyurethane composite formulations:These lightweight alternatives reduce installation labor hours and enable faster changeout windows in fine-grinding circuits.
- Peru's copper belt expansion:Throughput expansion projects across Antamina and Las Bambas operations are generating concentrated demand for high-performance SAG mill lining solutions.
Market Restraints
- High manganese steel input costs:Manganese alloy price volatility directly impacts foundry margins and liner pricing stability.
- Foundry capacity concentration:Brazil and India dominate export-oriented casting operations, creating geographic supply vulnerability.
- REACH framework restrictions:The EU's alloying element import constraints force European end-users toward certified domestic suppliers with full material traceability.
Strategic Opportunities
- Indonesia's nickel-cobalt corridor:Hydrometallurgical processing expansion creates untapped demand for corrosion-resistant liner systems in aggressive leaching environments.
- Digital liner monitoring:Embedded wear sensors and predictive analytics enable condition-based replacement contracts.
- Australia's WHS regulations:Stricter noise and vibration mandates favor rubber-metal composite adoption in secondary grinding stages.
Industry Challenges
- Metallurgical engineering talent scarcity:Specialized foundry process engineers with manganese steel expertise are in short supply across export-oriented manufacturing hubs.
- ISO 9001 certification timelines:Extended audit cycles delay new supplier qualification for major mining houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mill Liner Market |
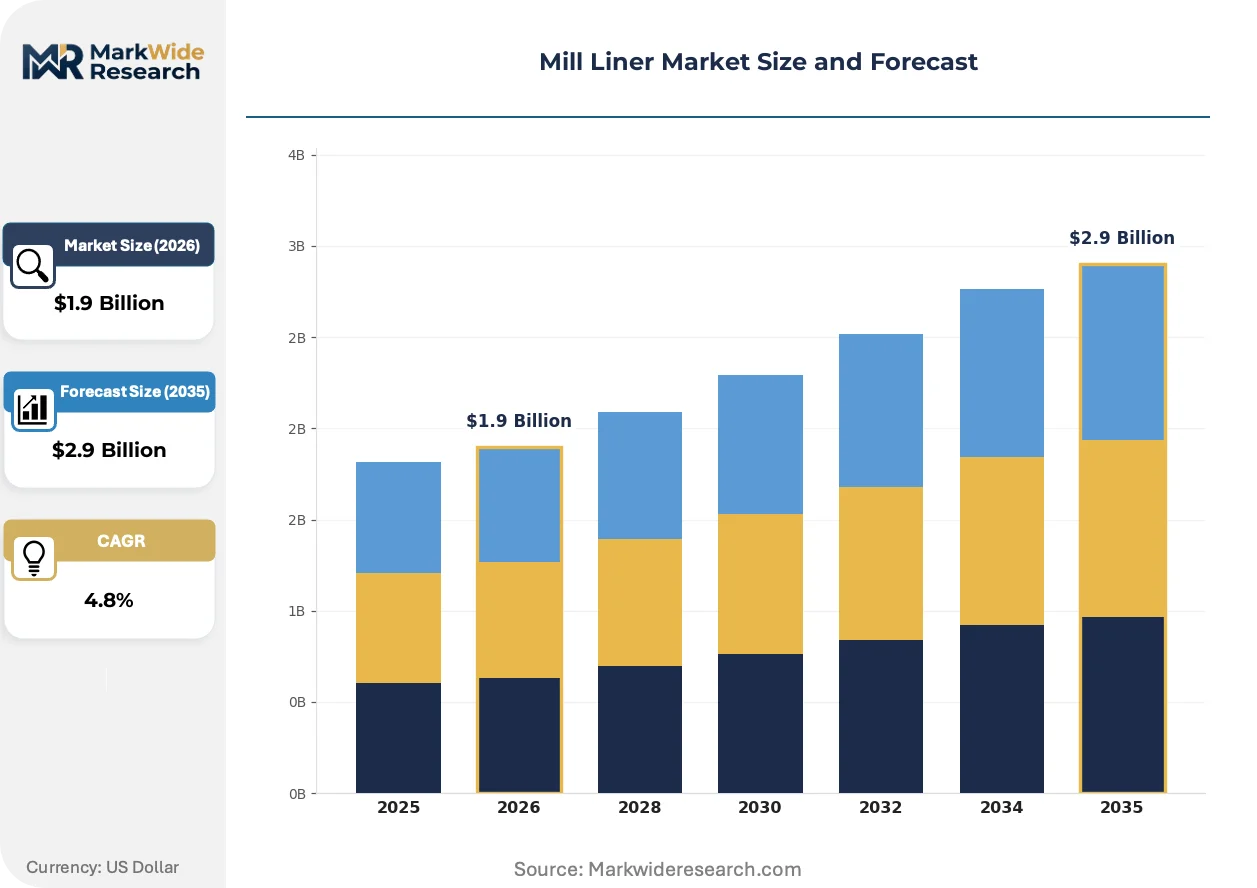
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $2.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
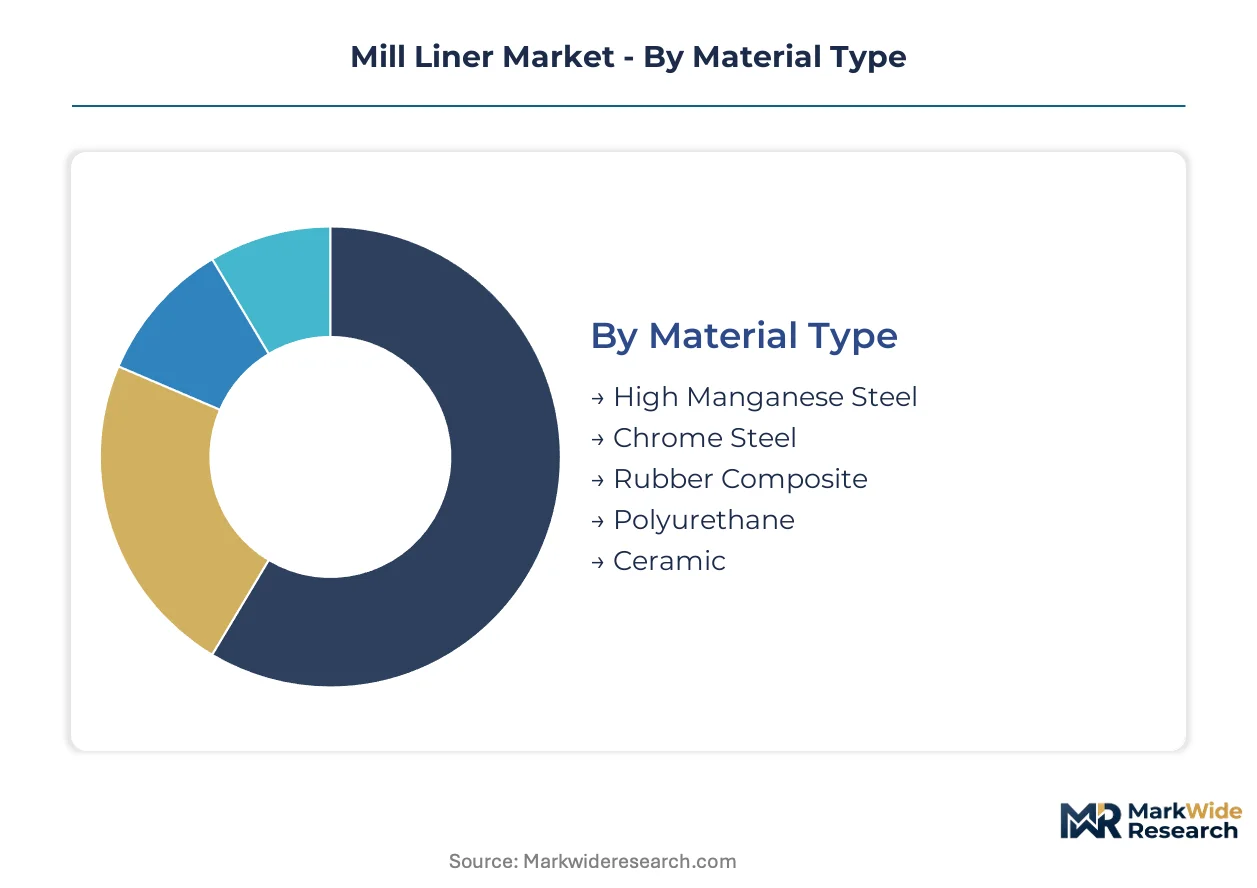
| Segmentation | Material Type: High Manganese Steel, Chrome Steel, Rubber Composite, Polyurethane, Ceramic Mill Type: Ball Mill, SAG Mill, Rod Mill, Autogenous Mill, Semi-Autogenous Mill Application Sector: Mining Operations, Cement Processing, Mineral Processing, Aggregate Production, Construction Material End User: Metal Extraction Facilities, Quarry Plants, Cement Manufacturers, Chemical Processing Plants, Power Generation Units |
| Companies Covered | Magotteaux, Tega Industries, Metso Outotec, Trelleborg, ME Elecmetal, FLSmidth, Bradken, Multotec, Weir Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mill Liner Market Strategic Shifts & Innovations
Digitalization of wear monitoring and materials science advances are compressing the traditional reactive replacement model toward predictive maintenance paradigms.
Sensor-embedded liner systems is rewriting maintenance economics across large-diameter SAG installations. BHP and Codelco operations are piloting acoustic and vibration monitoring arrays that map wear patterns in real time. This capability is compressing unplanned shutdown frequency and enabling outcome-based service contracting.
Australia's WHS regulations are mandating documented noise exposure controls that exceed baseline ISO standards. Mining operators must demonstrate engineered noise reduction below 85 dB across grinding circuits. Rubber composite liner segments are capturing preference in secondary milling applications where acoustic compliance is most acute.
Buyer consolidation among tier-one mining houses is centralizing procurement authority and unbundling after-sales service from initial liner supply. Rio Tinto and Glencore are separating installation contracting from material purchase, creating standalone service specialist opportunities. Chile and Peru operations are most advanced in this procurement restructuring.
Mill Liner Market Segmentation
Mill liner procurement decisions hinge on ore abrasiveness, mill kinematics, and regulatory compliance requirements. Material specification and mill architecture together determine wear rates, replacement intervals, and total cost of ownership across extraction and processing operations.
Material Type:
Material specification dictates work-hardening behavior, impact resistance, and acoustic damping properties in grinding environments.
- High Manganese Steel:Alloy formulations containing 11-14% manganese content achieve surface hardness of 550 BHN through operational work-hardening. Demand concentrates in Chile's copper belt where DS 594 safety codes mandate documented liner integrity for high-impact primary milling.
- Rubber Composite:Steel-reinforced elastomeric formulations reduce shell noise transmission below 85 dB thresholds. Australia's WHS regulations are accelerating adoption in secondary grinding circuits at BHP and Rio Tinto operations.
- Chrome Steel:High-carbon chromium alloys deliver extreme abrasion resistance for ore hardness exceeding 15 kWh/t.
- Polyurethane:Lightweight castable formulations enable single-operator installation and reduced changeout labor.
- Ceramic:Alumina-zirconia composites target ultra-fine grinding circuits with minimal metallic contamination requirements.
Mature deployment sits with high manganese steel. Newer deployment is concentrated in rubber composite and polyurethane formulations.
Mill Type:
Mill architecture determines liner design complexity, replacement frequency, and service contracting structures.
- SAG Mill:Large-diameter semi-autogenous installations require custom-engineered shell and lifter configurations with 12-18 month replacement cycles. Peru's Antamina and Las Bambas expansions are generating concentrated demand for high-performance lining systems.
- Ball Mill:Conventional rotating drum designs with steel grinding media represent the installed volume base across cement and mineral processing. Replacement intervals extend to 24-36 months in secondary grinding duty.
- Rod Mill:Longitudinal steel rod charge configurations demand specialized liner profiles for cascading media control.
- Autogenous Mill:Ore-only grinding circuits without supplemental media require impact-resistant lifter designs.
- Semi-Autogenous Mill:Hybrid configurations with partial ball charge occupy niche applications in platinum group metal extraction.
Volume concentration remains with ball mill applications. Margin expansion is steepest in SAG mill segments.
Application Sector:
End-use severity varies from high-abrasion metallic ore grinding to controlled-finesse cement finish milling.
- Mining Operations:Copper, gold, and iron ore extraction drives premium liner specifications with accelerated wear monitoring. Ore grade deterioration across mature belts is compressing replacement cycles and expanding aftermarket service contracts.
- Cement Processing:Clinker grinding and finish milling demand thermal-shock-resistant formulations with predictable 18-month replacement scheduling.
- Mineral Processing:Phosphate, bauxite, and industrial mineral beneficiation requires corrosion-resistant liner systems.
- Aggregate Production:Construction material crushing circuits utilize standard manganese configurations with volume-driven procurement.
- Construction Material:Specialty silica and limestone grinding for building products occupies price-sensitive procurement tiers.
Specification intensity peaks in mining operations. Standardization dominates construction material applications.
End User:
Procurement authority and technical specification sophistication diver sharply across buyer categories.
- Metal Extraction Facilities:Tier-one mining houses centralize liner procurement with unbundled installation contracting. Rio Tinto and Glencore operations are separating material purchase from field service, creating standalone specialist opportunities.
- Cement Manufacturers:Integrated producers negotiate long-term supply agreements with foundry-direct pricing and volume commitments.
- Quarry Plants:Regional aggregate operators prioritize rapid-delivery liner kits with 72-hour changeout guarantees.
- Chemical Processing Plants:Specialty mineral grinding for fertilizers and industrial chemicals demands material traceability under REACH framework constraints.
- Power Generation Units:Limestone flue gas desulfurization grinding circuits require corrosion-resistant formulations.
Procurement sophistication concentrates in metal extraction facilities. Price sensitivity dominates quarry plant purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's mining investment promotion program under ProInversión is concentrating capital deployment in copper extraction corridors. This tax-incentive zone is drawing foundry partnerships and service infrastructure toward the Andean mineral belt.
Chile
DS 594 mine safety codes mandate documented liner integrity inspections at prescribed intervals across Codelco and Antofagasta Minerals operations. This regulatory framework accelerates planned replacement schedules and expands aftermarket service contracting. The Atacama Desert copper cluster anchors regional demand for high-impact primary milling solutions.
Australia
WHS regulations enforce noise exposure controls below 85 dB across BHP and Rio Tinto grinding circuits. Rubber-metal composite formulations are capturing preference in Western Australian iron ore and Queensland coal operations. The Pilbara region concentrates procurement authority for large-diameter SAG mill retrofits.
Peru
Throughput expansion at Antamina and Las Bambas is generating concentrated demand for custom-engineered SAG mill lining systems. ProInversión's fiscal stability contracts reduce investment risk for foreign foundry joint ventures. The Ancash and Apurímac mining corridors are emerging as procurement decision centers.
Indonesia
Hydrometallurgical processing expansion across the nickel-cobalt corridor is creating demand for corrosion-resistant liner systems in aggressive leaching environments. The country's national mineral regulator oversees environmental compliance for tailings and processing infrastructure. Sulawesi and Halmahera island clusters are attracting liner technology partnerships.
South Africa
Platinum group metal extraction drives premium liner specifications with accelerated wear monitoring requirements across Anglo American Platinum and Sibanye-Stillwater operations. The country's mine health and safety inspectorate enforces equipment integrity standards. The Bushveld Igneous Complex anchors regional foundry-to-field service networks.
Mill Liner Market Key Industry Players
Top-tier vendors anchor integrated foundry-to-field service networks, while mid-tier specialists compete on material formulation differentiation. The vendor base stratifies across three capability tiers: full-service multinationals with captive casting capacity, regional composite formulators, and rapid-delivery aftermarket kit providers. Strategic archetypes include work-hardening steel specialists, rubber-metal hybrid engineers, and sensor-embedded predictive maintenance enablers. Competitive moves center on unbundling installation contracting from material supply and embedding digital wear monitoring into long-term service agreements.
Among integrated multinationals, Metso Outotec and FLSmidth exemplify the full-service archetype with captive foundry capacity and field engineering networks. Tega Industries occupies a position as a composite formulation specialist with tropical ore abrasiveness expertise. Bradken represents the rapid-response aftermarket tier with compressed changeout window guarantees. These three anchors illustrate the competitive vectors shaping procurement restructuring across tier-one mining houses.
| Leading Market Players |
|---|
| Magotteaux |
| Tega Industries |
| Metso Outotec |
| Trelleborg |
| ME Elecmetal |
| FLSmidth |
| Bradken |
| Multotec |
| Weir Group |
| Others |
Cost & Logistics Intelligence
Captive foundry-to-field integration anchors both supply security and pricing power for tier-one vendors serving Chile's DS 594-mandated replacement schedules. This vertical control over manganese alloy casting and installation contracting insulates integrated multinationals from spot volatility while compressing margins for kit-dependent aftermarket specialists.
Pricing Analysis
Premium pricing for sub-72-hour changeout windows separates rapid-response aftermarket tiers from standard lead-time contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ISO 9001 and volume scale commitments from tier-one mining houses. Price erosion runs through economy-grade manganese configurations as Indian and Brazilian foundries compete on casting cost. Quarry plant operators exhibit acute price sensitivity, while Codelco and BHP procurement teams prioritize performance guarantees over unit cost.
Supply Chain Analysis
Direct-to-mine-site channels handle tier-one mining house demand, while distributor networks serve regional quarry and cement operations. Foundry capacity concentrates in Brazil, India, and South Africa, with manganese ore dependency anchored in South Africa and Gabon. Supply chain risk centers on single-source vulnerability for 11-14% manganese alloy formulations. Distribution runs through unbundled installation contractors in Chile and Peru, separating material supply from field service execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. Chile's DS 594 mine safety codes erect barrier-to-entry moats that favor certified suppliers with documented liner integrity protocols.
For Market Incumbents: Hedge manganese alloy price exposure through long-term offtake agreements with South African ore producers. Fortify captive foundry capacity in Brazil or India to defend margin position against rapid-delivery kit specialists. Digital wear monitoring capabilities represent the priority capability investment as BHP and Codelco pilot predictive maintenance contracts. For New Entrants and Emerging Players: Indonesia's nickel-cobalt hydrometallurgical corridor offers an underserved buyer archetype seeking corrosion-resistant liner systems for aggressive leaching environments. Polyurethane composite formulations for fine-grinding circuits present a second penetrable white space with reduced capital intensity versus steel foundry entry. A materials-science-led go-to-market angle targeting tropical ore abrasiveness differentiates against established manganese steel incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated mining technology conglomerates seeking foundry-to-field service networks. Long-term viability hinges on digitalization capabilities and regulatory certification depth rather than casting scale alone. Watch for inflection when tier-one mining houses unbundle installation contracting from material supply across additional geographies beyond Chile and Peru.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Liner Development | Enables outcome-based service contracting with BHP and Codelco pilot programs. |
| Foundry Joint Venture in Peru | ProInversión fiscal stability contracts reduce investment risk for Antamina proximity. |
| Rubber-Metal Composite Capacity Expansion | Australia's WHS noise mandates accelerate demand for sub-85 dB formulations. |
| ISO 9001 Certification Investment | Extended audit cycles delay competitor qualification for major mining houses. |
| Corrosion-Resistant Formulation R&D | Indonesia's hydrometallurgical expansion creates untapped demand in leaching circuits. |
Research Approach
Multi-period observation of liner replacement cycle compression and ore grade deterioration anchored the trend analysis, supplemented by interviews with foundry operations managers, mine maintenance directors, procurement leads at tier-one mining houses, and aftermarket service heads. Secondary validation drew from customs trade data, Chile's DS 594 regulatory filings, SEC disclosures by listed mining technology vendors, and ISO certification registry records. Bottom-up volume triangulation across material type and mill type segments was cross-checked against top-down mining capital expenditure flows.
Segment-weighting across material type, mill architecture, and application sector informed the analytical framework over the projection horizon. CAGRs were derived from elasticity modeling against mining throughput expansion and regulatory-mandated replacement acceleration. Industry-specific forecast inputs included manganese alloy price trajectory assumptions and DS 594 inspection interval compliance rates across Chilean operations.
Revisions become necessary when manganese ore supply disruptions, REACH framework alloy restrictions, or tier-one mining house procurement restructuring materialize at scale. Forecasts reflect documented assumptions regarding ore hardness progression and foundry capacity expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Heavy Duty Loading Ramps Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market