
 Industrial Carts Market | 2026-2036
Industrial Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Carts Market Foresight
The split between premium engineered carts and commodity-grade alternatives is realigning procurement patterns across industrial channels. KION Group AG leverages its integrated manufacturing footprint to sustain margin capture in automated guided cart systems. Hamilton Caster & Mfg. Co. anchors its position through specialized heavy-duty configurations that dominate foundry and aerospace floor environments.
Industrial carts are wheeled material handling platforms, typically fabricated from steel, aluminum, or reinforced polymer composites, designed to transport goods across factory floors, warehouses, and distribution centers with load capacities spanning 100 to over 1,000 pounds. Steel-framed heavy-duty carts occupy the dominant share of replacement revenue due to durability requirements in metalworking and automotive assembly, while aluminum utility carts represent the fastest-expanding material category as operators prioritize weight reduction for manual handling compliance. The 500-1000 lbs capacity band captures disproportionate margin pools because it bridges manual and semi-automated workflows where ergonomic liability intersects with productivity targets.
OSHA workplace ergonomics enforcement, EU machinery directive CE marking requirements, and ISO 3691 safety standards for industrial trucks collectively elevate compliance costs for entry-level suppliers while creating specification barriers for cross-border trade. The EPA's focus on sustainable manufacturing processes is redirecting material selection toward recycled-content steel and bio-based plastics in certain contract segments. Stakeholders must monitor how evolving forklift-collision avoidance mandates transfer design requirements downstream to manually operated cart fleets.
Market Dynamics
Warehouse automation mandates from third-party logistics providers are compressing replacement cycles for manually operated cart fleets while elevating specification thresholds for load-bearing precision and collision-avoidance compatibility.
Growth Catalysts
- EU Machinery Directive CE marking:Compliance requirements are filtering out low-specification imports and consolidating procurement toward certified European suppliers with documented safety validation.
- E-commerce fulfillment density:Parcel sortation hubs in Germany and the United States are deploying high-capacity aluminum utility carts to meet throughput targets under OSHA ergonomic enforcement.
- Recycled-content steel specifications:EPA sustainable manufacturing guidelines are redirecting material selection toward circular supply chains in automotive assembly contracts.
Market Restraints
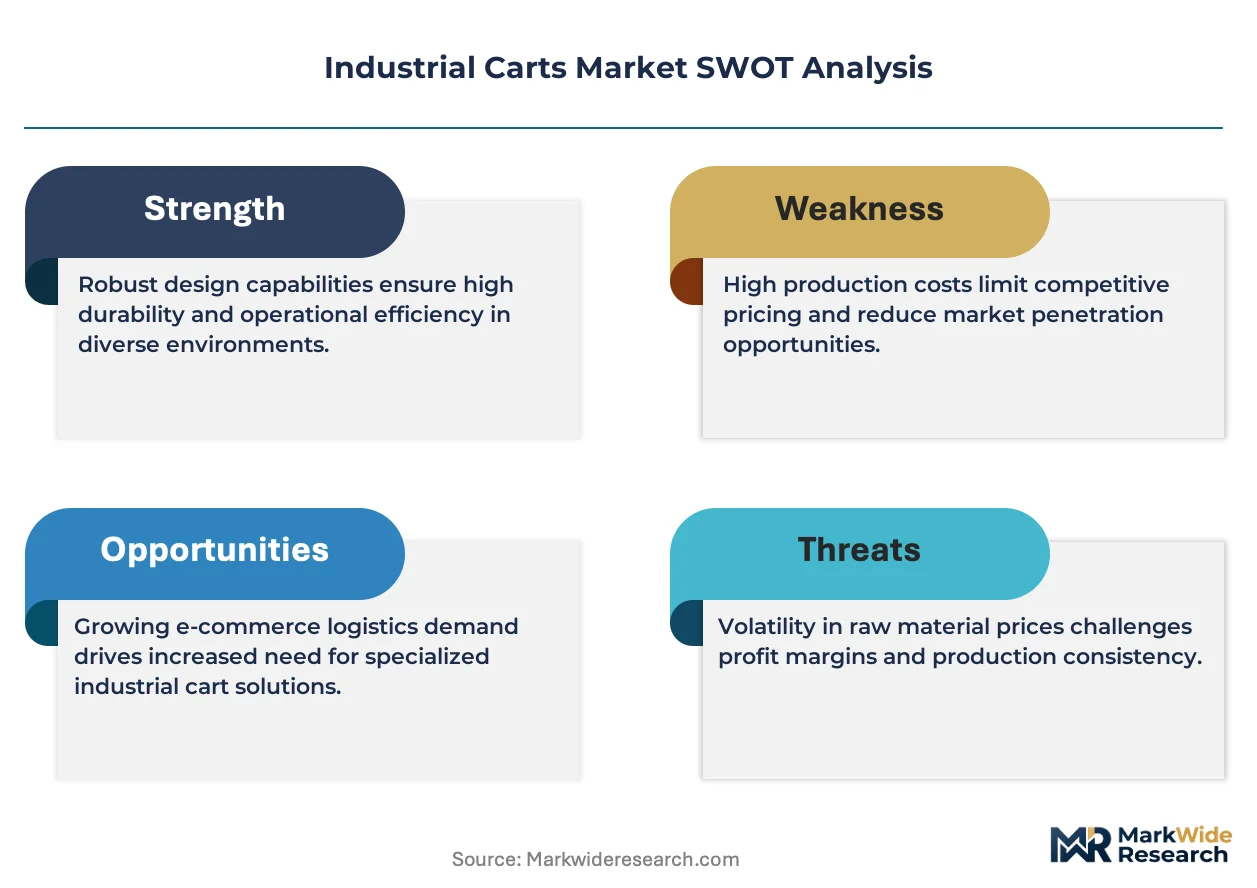
- Steel price volatility:Input cost swings for hot-rolled coil compress margins on heavy-duty fabricated platforms and destabilize long-term contract pricing.
- Concentrated motor and drive sourcing:Automated guided cart systems depend on controller hardware concentrated in East Asian manufacturing clusters, exposing lead time risk.
- ISO 3691 certification friction:Safety standard compliance for industrial trucks creates specification barriers for cross-border trade of semi-automated cart fleets.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics and automotive assembly are creating first-mover advantage for localized cart fabrication capacity.
- Forklift-collision avoidance mandate spillover:Sensor integration requirements for powered industrial trucks are transferring design specifications to manual cart fleets in German automotive plants.
- Bio-based polymer convergence:Reinforced composite platforms combining recycled steel frames with plant-derived decking materials are opening specification windows in food processing and pharmaceutical clean rooms.
Industry Challenges
- Welding automation technician scarcity:Fabrication of heavy-duty steel platforms requires certified operators that foundry and aerospace suppliers struggle to retain.
- Legacy fleet integration complexity:Retrofitting existing cart infrastructure with RFID tracking and automated dispatch compatibility demands capital outlay that mid-size distributors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Carts Market |
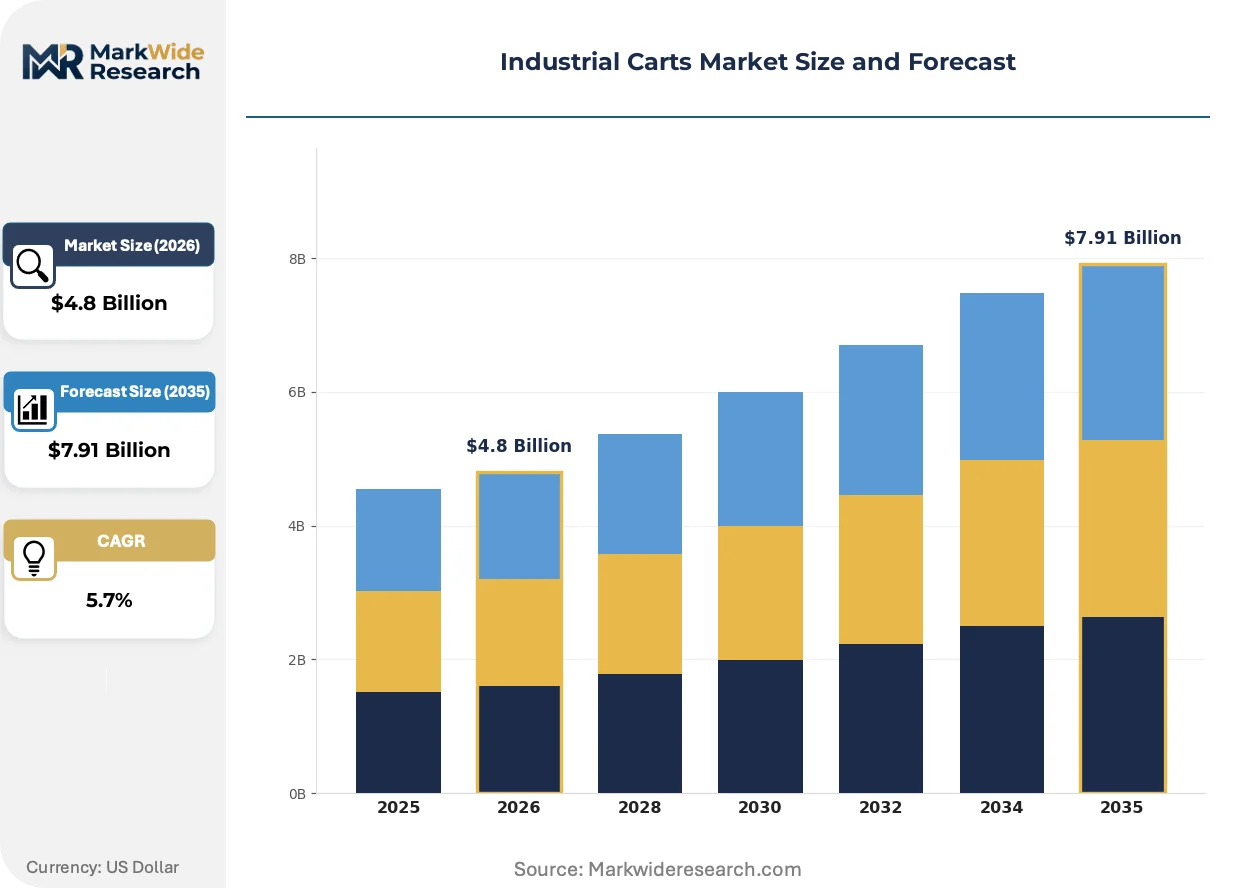
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Carts, Utility Carts, Trolleys, Platform Carts End User: Construction, Warehousing, Manufacturing, Logistics Material: Wood, Steel, Aluminum, Plastic Capacity: 100-200 lbs, 200-500 lbs, 500-1000 lbs, Over 1000 lbs |
| Companies Covered | KION Group AG, Crown Equipment Corporation, Toyota Material Handling, Kinetic Technologies, Hamilton Caster & Mfg. Co., FlexQube AB, Jungheinrich AG, Hangcha Group Co., Ltd., Magline, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Carts Market Shifts & Advancements
Material substitution and sensor integration are restructuring competitive advantage around weight reduction and data capture rather than pure load capacity. Specification convergence between manual and automated workflows is compressing product development timelines.
Aluminum utility carts with modular deck configurations are overtaking fixed steel platforms in parcel handling and pharmaceutical distribution environments. Third-party logistics operators in the United States are specifying these platforms to meet OSHA manual handling thresholds while maintaining 500-pound load ratings. The shift is overtaking traditional procurement patterns that prioritized upfront capital cost over total cost of ownership.
REACH substance restrictions on hexavalent chromium coatings are forcing electroplating process conversions across European steel fabrication supply chains. Surface treatment suppliers in Germany are accelerating trivalent chromium and zinc-nickel alternatives to maintain CE marking eligibility. Heavy-duty cart manufacturers serving automotive assembly in Stuttgart and Wolfsburg are absorbing compliance costs that commodity-grade competitors cannot sustain.
Specification consolidation around integrated weighing and dimensioning systems is compressing vendor selection criteria in e-commerce fulfillment. Distribution center operators in China are bundling cart procurement with warehouse management system compatibility requirements, displacing standalone hardware vendors. The pattern is most visible in Shenzhen and Shanghai sortation hubs where automated dispatch integration determines contract awards.
Industrial Carts Market Segmentation
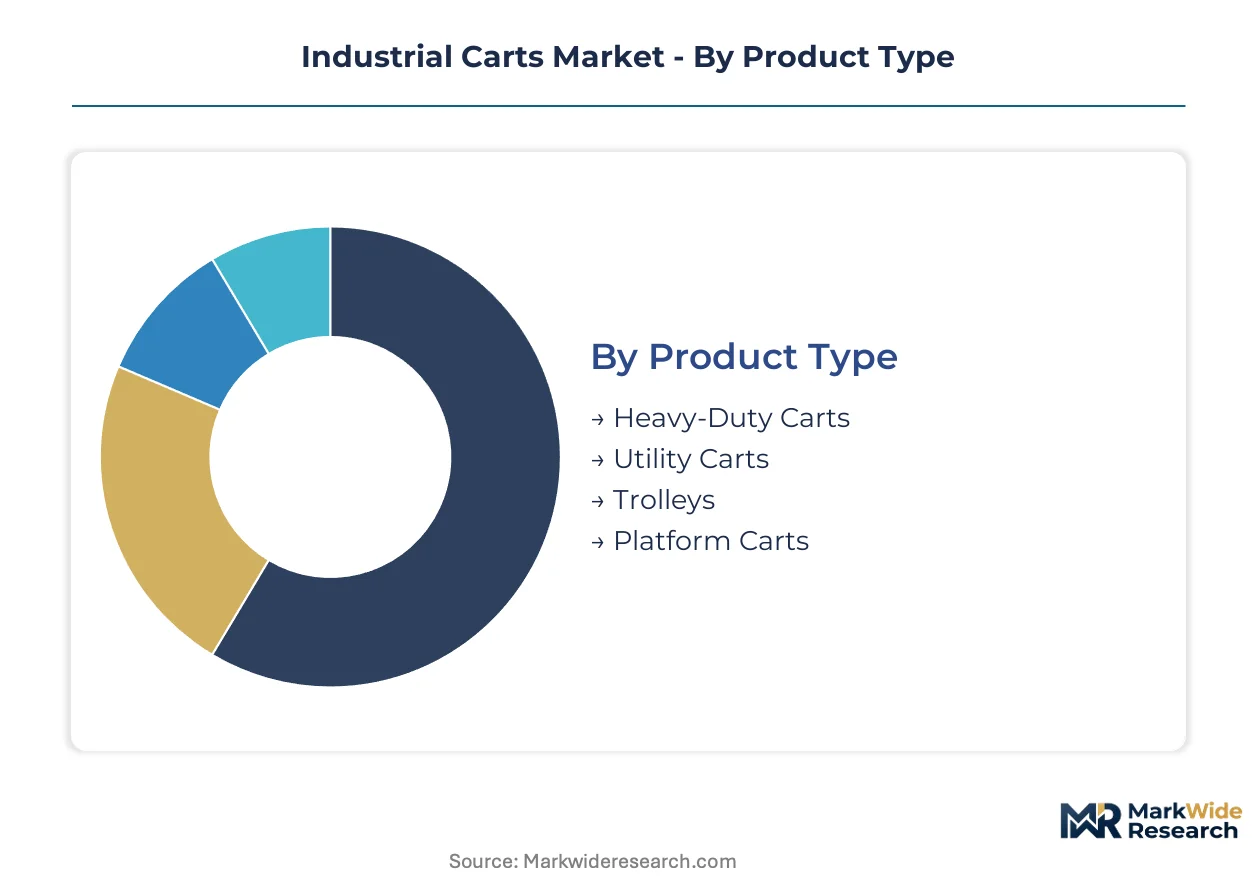
Industrial cart procurement patterns diverge sharply between standalone manual fleets and integrated automated workflows. Specification requirements for embedded sensor compatibility and warehouse management system interoperability now override pure load-capacity metrics in contract awards.
Product Type:
Standalone manual carts dominate replacement revenue, while automated guided variants embed directly into orchestrated material handling systems.
- Heavy-Duty Carts:Fabricated from reinforced steel with welded undercarriages rated for continuous shock loading. Demand concentrates in German automotive assembly plants where OSHA ergonomic enforcement intersects with 1,000-pound-plus payload requirements. CE marking compliance under EU Machinery Directive filters procurement toward certified European fabricators.
- Utility Carts:Aluminum-framed modular platforms with configurable deck heights and quick-release casters. Parcel sortation hubs in the United States specify these for 500-pound loads under manual handling thresholds. The segment is expanding most quickly as third-party logistics operators prioritize weight reduction.
- Trolleys:Narrow-profile platforms designed for aisle-constrained environments with fixed-direction wheel locking.
- Platform Carts:Flat-deck steel or aluminum bases with perimeter rail options for oversized load stability.
Heavy-Duty Carts lead volumes today; Utility Carts are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive automated deployments from price-sensitive replacement cycles.
- Manufacturing:Continuous-duty steel platforms with precision casters for cleanroom and assembly line integration. German automotive OEMs in Stuttgart and Wolfsburg mandate REACH-compliant surface coatings.
- Warehousing:High-turnover aluminum fleets with RFID tracking compatibility for warehouse management system integration. Shenzhen distribution centers bundle cart procurement with automated dispatch requirements.
- Logistics:Mixed-material fleets optimized for cross-dock velocity with rapid reconfiguration capabilities.
- Construction:Weather-resistant steel platforms with pneumatic tires for uneven terrain navigation.
Manufacturing commands premium pricing; Warehousing drives volume scale.
Material:
Application environment dictates selection between durability, weight reduction, and regulatory compliance.
- Steel:Hot-rolled coil construction with powder-coat or electroplated finishes for corrosion resistance. Foundry and aerospace floor environments in the United States specify these for impact tolerance.
- Aluminum:Extruded frame assemblies with riveted or welded joints for manual handling compliance. Parcel handling and pharmaceutical distribution in Germany favor these for OSHA ergonomic adherence.
- Plastic:Reinforced polymer composites for cleanroom and food processing applications with chemical washdown compatibility.
- Wood:Hardwood or plywood decking for temporary job site use and non-conductive electrical work environments.
Steel anchors replacement revenue; Aluminum climbs the fastest.
Capacity:
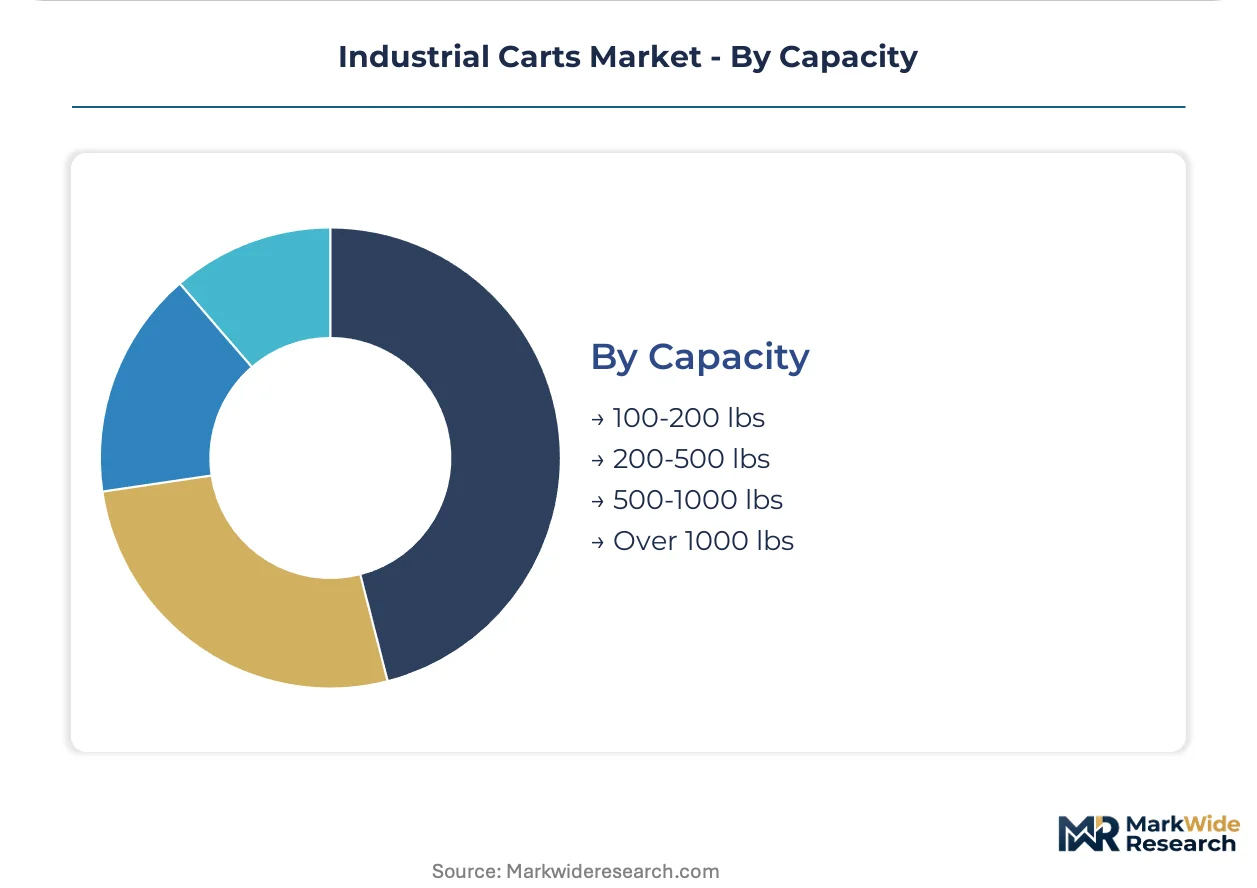
Margin concentration pools where ergonomic liability thresholds intersect with semi-automated workflow compatibility.
- 500-1000 lbs:Bridges manual and motorized handling with reinforced undercarriages and precision braking casters. German automotive plants specify these for forklift-collision avoidance mandate spillover.
- Over 1000 lbs:Structural steel platforms with dual-wheel bogies and tow-bar integration for powered traction units. Metalworking and heavy assembly in the United States require these for durability cycles.
- 200-500 lbs:Light-duty aluminum or steel platforms for single-operator manual handling in retail backrooms.
- 100-200 lbs:Compact polymer or wire-frame carts for office and light commercial document transport.
500-1000 lbs captures disproportionate margins; Over 1000 lbs sustains longest replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding technicians in Stuttgart, Wolfsburg, and Munich anchor German fabrication capacity for heavy-duty automotive platforms. Shenzhen and Shanghai sortation hubs concentrate logistics engineering talent for automated dispatch integration. Foundry floor specialists in Pittsburgh and Cleveland sustain demand for impact-tolerant steel configurations.
Germany
Automotive OEM assembly plants in Stuttgart and Wolfsburg drive specification for 1,000-pound-plus payload platforms with REACH-compliant surface coatings. EU Machinery Directive CE marking filters procurement toward certified fabricators with documented safety validation. Bavarian metalworking clusters absorb compliance costs for trivalent chromium conversion that commodity-grade competitors cannot sustain.
China
E-commerce fulfillment density in Shenzhen and Shanghai sortation hubs elevates demand for warehouse management system-compatible aluminum fleets. NMPA-equivalent equipment safety standards and GB certification requirements shape cross-border specification barriers. Yangtze River Delta distribution centers bundle cart procurement with automated dispatch integration requirements.
United States
OSHA ergonomic enforcement in parcel handling and pharmaceutical distribution channels prioritizes weight-reduced aluminum platforms under manual handling thresholds. EPA sustainable manufacturing guidelines redirect automotive assembly contracts toward recycled-content steel specifications. Pittsburgh and Cleveland foundry environments specify hot-rolled coil construction for continuous shock loading tolerance.
India
PLI scheme incentives for electronics and automotive assembly manufacturing corridors create first-mover positioning for localized fabrication capacity. BIS equipment safety standards and DGFT import certification requirements elevate specification barriers for cross-border suppliers. Maharashtra and Gujarat assembly plants prioritize modular platform configurations for rapid workflow reconfiguration.
Japan
METI industrial efficiency mandates and JIS precision manufacturing standards compress product development timelines for sensor-integrated cart systems. Kanto and Kansai automotive clusters specify collision-avoidance-compatible platforms for forklift mandate spillover. Osaka pharmaceutical distribution networks prioritize cleanroom-compatible polymer composite decking materials.
Industrial Carts Market Competitive Landscape
Top-tier vendors anchor automated guided cart systems with integrated manufacturing footprints, while mid-tier fabricators compete on specialized heavy-duty configurations. The vendor base stratifies across three archetypes: integrated material handling conglomerates with captive controller supply, specialized heavy-duty fabricators serving foundry and aerospace floors, and modular aluminum platform specialists targeting third-party logistics weight-reduction mandates. Competitive moves concentrate on backward integration into East Asian motor and drive sourcing, and geographic expansion into India PLI-subsidized manufacturing corridors.
Among Germany-based integrated material handling conglomerates, KION Group AG and Jungheinrich AG exemplify the premium-tier vector with captive supply chain control over automated system components. Hamilton Caster & Mfg. Co. occupies a position within specialized heavy-duty fabricators serving impact-intensive floor environments. FlexQube AB represents the modular configuration archetype targeting rapid workflow reconfiguration requirements in Scandinavian and North American logistics channels.
| Leading Market Players |
|---|
| KION Group AG |
| Crown Equipment Corporation |
| Toyota Material Handling |
| Kinetic Technologies |
| Hamilton Caster & Mfg. Co. |
| FlexQube AB |
| Jungheinrich AG |
| Hangcha Group Co., Ltd. |
| Magline, Inc. |
| Others |
Supply & Pricing Matrix
Captive control over automated controller hardware anchors both supply security and premium pricing power for integrated material handling conglomerates serving German automotive OEMs. This integration choice insulates tier-one vendors from East Asian lead time volatility while compressing margins for commodity-grade competitors locked into spot-market steel procurement.
Pricing Analysis
The bundled hardware-software service split separates automated guided cart systems from standalone manual platforms. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels reflects CE marking validation and ISO 3691 certification tiers. Cost compression in economy-grade steel platforms is intensifying because hot-rolled coil volatility destabilizes contract pricing. Third-party logistics operators exhibit highest price sensitivity, while German automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Container freight rate fluctuations between East Asia and European ports directly impact landed costs for motor and drive controller imports. Controller hardware concentrates in China, Taiwan, and South Korea, while heavy-duty steel fabrication clusters in Germany and the United States. Raw material dependencies span hot-rolled coil, aluminum extrusions, and precision caster assemblies. Single-source vulnerability for semiconductor motor controllers creates inventory risk. Distribution runs through OEM direct contracts, industrial distributor networks, and e-commerce fulfillment integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Carts Market functions as a stable compounder where warehouse automation mandates and ergonomic regulatory enforcement sustain replacement cycle predictability across manufacturing and logistics channels.
For Market Incumbents: Lock in captive supply agreements for East Asian motor controllers before lead time risk escalates. Deepen backward integration into recycled-content steel processing to meet EPA sustainable manufacturing guidelines in US automotive contracts. Consolidate certified welding technician pipelines in Stuttgart and Wolfsburg to defend against fabrication capacity constraints. CE marking compliance investment filters out commodity competitors. For New Entrants and Emerging Players: The premium-to-economy tier price gap opens positioning for mid-market aluminum utility platforms with modular deck configurations. Target Indian PLI-subsidized electronics and automotive manufacturing corridors where localized fabrication capacity remains underdeveloped. Pursue warehouse management system integration partnerships as the primary go-to-market angle in Shenzhen and Shanghai distribution hubs. For Investors and Strategic Acquirers: Roll-up economics work for specialized heavy-duty fabricators because certified welding technician scarcity creates regional moats around Stuttgart, Pittsburgh, and Cleveland production clusters. Five-to-ten-year viability hinges on automation retrofit compatibility and collision-avoidance sensor integration capabilities. Watch for forklift-collision avoidance mandate spillover into manual cart specifications as the inflection signal for platform sensorization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Steel Processing | EPA guidelines in US automotive contracts favor circular supply chains. |
| CE Marking Certification Investment | EU Machinery Directive compliance filters procurement toward validated European fabricators. |
| Sensor Integration Partnership | German automotive plants mandate collision-avoidance compatibility for manual fleets. |
| Localized Fabrication in India PLI Corridors | Maharashtra and Gujarat electronics assembly creates first-mover capacity advantage. |
| Warehouse Management System Bundle | Shenzhen distribution centers displace standalone vendors through integrated procurement. |
Research Methodology
Direct dialogue with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads grounded qualitative findings in operational reality across German automotive assembly, US foundry floors, and Chinese distribution hubs. Secondary validation drew from customs trade data, OSHA enforcement disclosures, EU Machinery Directive registration databases, and SEC filings from listed material handling conglomerates. Bottom-up unit demand modeling triangulated against top-down manufacturing output correlations.
Bottom-up volume projections across product type, material grade, capacity tier, and end-use segment anchored the analytical framework over the projection horizon. Segmentation dimensions spanned manual versus automated workflow integration, steel versus aluminum versus composite material selection, and regional regulatory cluster alignment. CAGRs derived from replacement cycle analysis, automation penetration curves, and ergonomic compliance mandate timelines. Industry-specific inputs included hot-rolled coil price indices and certified welding technician labor availability by metropolitan cluster.
Caveats apply where steel price volatility, semiconductor controller shortages, or regulatory enforcement delays could materially shift the outlook. Forecasts reflect assumptions about warehouse automation adoption rates and ergonomic mandate implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Water Hose Market