
 Arrestor Cables Market | 2026-2036
Arrestor Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Arrestor Cables Market Analytics
FAA airfield design standards is recalibrating the cost-of-entry calculus for arrestor cable suppliers seeking commercial airport certification. General Atomics leverages its electromagnetic aircraft launch system heritage to dominate advanced arresting gear development for naval aviation. Curtiss-Wright Corporation anchors its position through sustained R&D intensity in specialized wire rope engineering for extreme-load applications. WireCo WorldGroup competes by extending its synthetic rope expertise into non-metallic arrestor solutions for lighter aircraft categories.
Arrestor cables are high-tensile energy-absorption systems engineered from multi-strand steel wire rope or advanced synthetic fiber composites, typically rated for dynamic loads exceeding 150,000 pounds to decelerate military and emergency aircraft during aborted takeoffs or landing overruns. Their primary purpose is to convert kinetic aircraft energy into controlled thermal and mechanical dissipation within seconds, preventing runway excursions and protecting aircrew and airframe integrity. Metallic cables still occupy the largest installed base among product types, though hybrid cables represent the fastest-growing segment as operators seek weight reduction without sacrificing load capacity. Defense end users command the deepest margin pools, while surge protection applications in electrical transmission are expanding as grid hardening investments accelerate.
The U.S. FAA, the U.S. Navy's Naval Air Systems Command, and ISO 9001 quality management frameworks collectively shape arrestor cable demand through airworthiness certification, military specification compliance, and manufacturing process standardization. These requirements force suppliers to maintain dual-track quality systems serving both commercial aviation and defense procurement channels. Stakeholders must monitor how electrification of naval aviation platforms and heavier unmanned aerial vehicle weights will redefine load-rating thresholds and material specifications across the next procurement cycle.
Market Dynamics
Naval aviation electrification and heavier unmanned aerial vehicle platforms are recalibrating load-rating specifications across the arrestor cable procurement cycle. Defense agencies now demand energy-absorption systems capable of handling dynamic loads well beyond legacy thresholds, forcing material science acceleration and certification protocol updates.
Growth Catalysts
- NATO Airfield Modernization:Member states are replacing aging hook-wire infrastructure with advanced arresting systems to accommodate next-generation fighter deployments.
- FAA Certification Tightening:Updated U.S. Federal Aviation Administration airfield design standards are mandating enhanced emergency arresting gear specifications at commercial airports.
- Synthetic Fiber Advancement:High-performance polymer composites are penetrating lighter aircraft categories where weight reduction delivers operational fuel savings.
Market Restraints
- Specialized Steel Alloy Volatility:Nickel and chromium price swings in high-tensile wire rope production compress margin predictability for metallic cable manufacturers.
- Dual-Track Quality System Burden:Suppliers must simultaneously maintain ISO 9001 frameworks and military specification compliance, elevating fixed cost structures.
- Electromagnetic System Substitution:Advanced electromagnetic aircraft recovery systems threaten conventional mechanical arrestor cable demand on next-generation naval platforms.
Strategic Opportunities
- Grid Hardening Applications:Electrical transmission surge protection represents an adjacent demand channel as utility infrastructure resilience investments accelerate.
- Hybrid Cable Development:Converging steel-core and synthetic-sheath technologies create performance tiers for intermediate load-rating requirements.
- UAE Defense Procurement:Gulf state airbase expansion programs present untapped demand for certified emergency arresting systems.
Industry Challenges
- Specialized Metallurgical Talent Scarcity:Wire rope engineering expertise for extreme-load applications concentrates within a narrow cohort of experienced practitioners.
- Extended FAA Certification Timelines:Commercial airport arrestor system approval cycles stretch 18-24 months, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arrestor Cables Market |
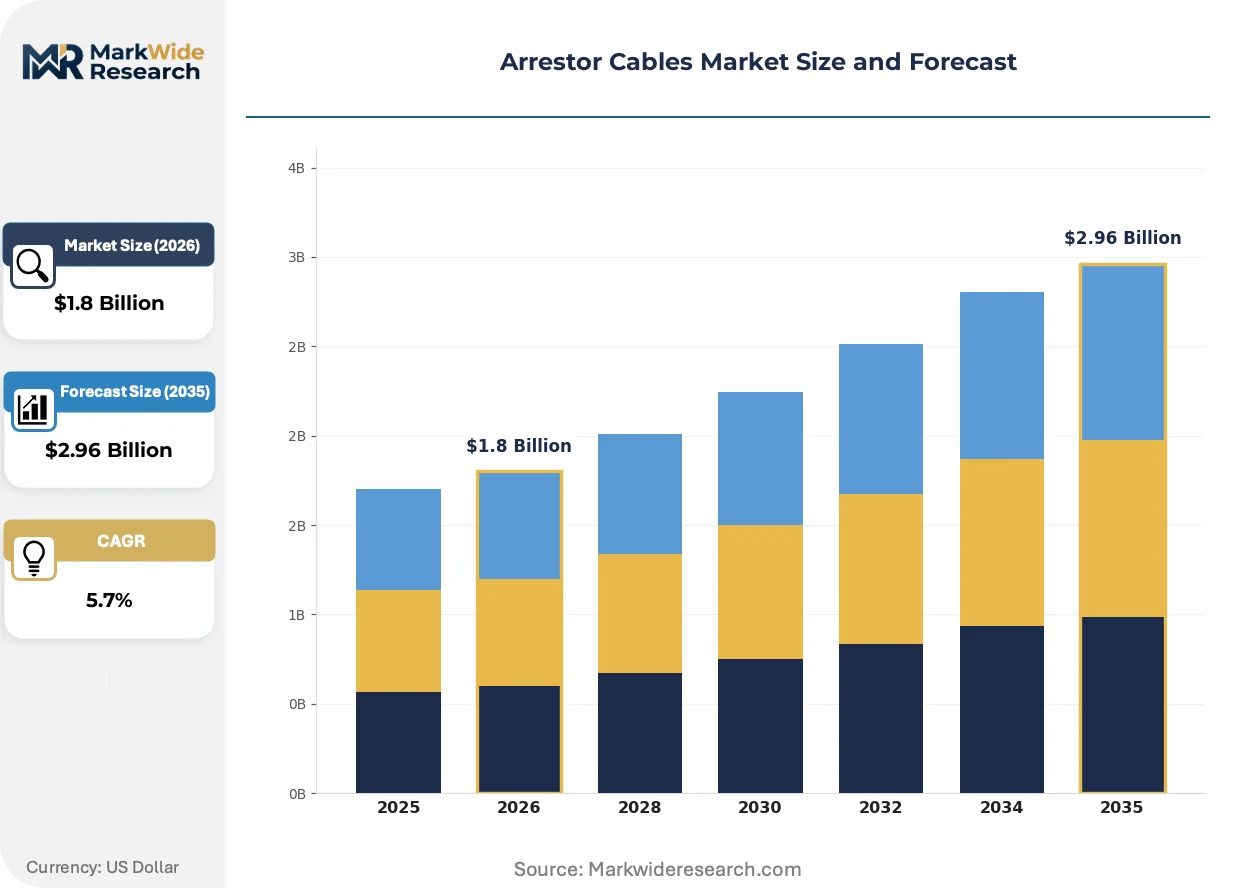
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Cables, Non-metallic Cables, Hybrid Cables, Composite Cables End User: Telecommunications, Railways, Power Utilities, Defense Installation: Overhead, Underground, Utilized in Structures, Mounted on Equipment Application: Lightning Protection, Surge Protection, Grounding Systems, Electrical Transmission |
| Companies Covered | General Atomics, Curtiss-Wright Corporation, Runway Safe, SCAMA AB, Zodiac Aerospace, Atech Inc., WireCo WorldGroup, MacTaggart Scott, QinetiQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arrestor Cables Market Evolving Landscape
Material substitution and procurement model evolution are compressing traditional competitive advantages in arrestor cable supply. Energy-absorption system design is pivoting toward modular architectures that accommodate faster reconfiguration across aircraft weight classes.
Carbon nanotube-reinforced polymer composites are absorbing kinetic energy loads previously reserved for steel wire rope constructions. Naval aviation procurement offices are piloting these materials on unmanned carrier-based platforms where weight reduction extends operational range. The technology is absorbing market share from conventional metallic cables in sub-100,000 pound load-rating segments.
The U.S. Federal Aviation Administration's updated airfield design standards are tightening emergency arresting gear certification windows. Commercial airport operators must now demonstrate accelerated engagement response times and reduced maintenance intervals. General aviation facilities in the United States are responding by consolidating procurement specifications to pre-approved vendor lists.
Defense procurement officers are unbundling installation and lifecycle maintenance from initial system acquisition. Prime contractors now compete on availability-based service metrics rather than unit price alone. This behavioral shift is most visible in U.S. Navy and Air Force base upgrade programs where total cost-of-ownership frameworks dominate source selection.
Arrestor Cables Market Segmentation
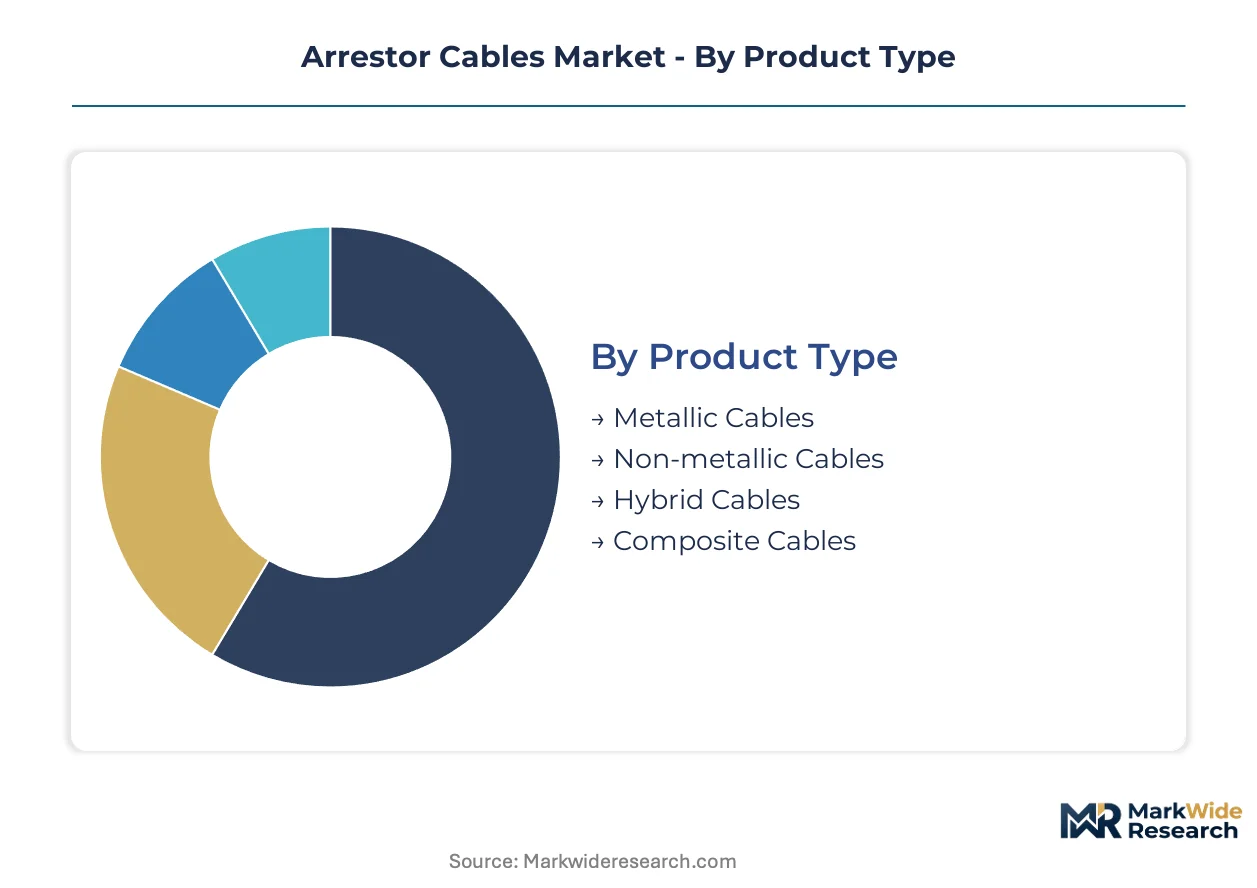
Arrestor cable procurement splits across material science, end-use mission profiles, and installation topology. Each segmentation axis reveals distinct margin structures and certification barriers that shape supplier positioning.
Product Type:
Supply concentration clusters around manufacturers with captive wire rope engineering capabilities and polymer composite R&D infrastructure.
- Metallic Cables:Multi-strand steel wire rope constructions rated for dynamic loads exceeding 150,000 pounds dominate naval aviation and heavy fighter recovery. Demand concentrates in U.S. Navy and Air Force base upgrade programs where legacy hook-wire replacement cycles are accelerating.
- Hybrid Cables:Converged steel-core and synthetic-sheath architectures deliver intermediate load ratings with reduced weight penalties. NATO airfield modernization programs are absorbing these configurations for next-generation fighter deployments where fuel efficiency and arresting performance must balance.
- Non-metallic Cables:High-performance polymer composites serve lighter unmanned aerial vehicle categories and general aviation emergency systems.
- Composite Cables:Carbon nanotube-reinforced constructions are penetrating experimental naval platforms for extreme weight reduction.
Metallic cables absorb the bulk of installed capacity; hybrid cables are expanding most quickly.
End User:
Application maturity and procurement sophistication vary sharply across customer categories, with defense buyers commanding the deepest specification requirements.
- Defense:Naval Air Systems Command and NATO procurement offices drive demand for MIL-SPEC certified systems with availability-based service contracts. U.S. carrier air wing modernization and Gulf state airbase expansion programs are concentrating orders among dual-track quality system suppliers.
- Power Utilities:Grid hardening investments are accelerating surge protection deployments across transmission infrastructure. Electrical transmission operators are specifying arrestor cables for lightning strike dissipation and fault current management.
- Telecommunications:Tower grounding and lightning protection specifications are tightening with FCC infrastructure resilience guidelines.
- Railways:Electrified track systems utilize arrestor configurations for catenary protection and signaling equipment grounding.
Defense procurement commands the specification premium; power utilities are climbing the fastest as grid investment accelerates.
Installation:
Physical deployment topology dictates maintenance access, environmental exposure, and reconfiguration flexibility across the asset lifecycle.
- Overhead:Suspended aerial configurations dominate electrical transmission and telecommunications tower applications where visual inspection and rapid replacement remain operational priorities.
- Underground:Buried installations serve substation grounding grids and critical infrastructure protection where electromagnetic interference shielding is required.
- Utilized in Structures:Embedded building lightning protection systems integrate arrestor cables into architectural steel and concrete reinforcement.
- Mounted on Equipment:Mobile and containerized configurations support expeditionary military operations and temporary airfield deployments.
Overhead systems retain the largest installed base; underground installations are gaining share fastest with grid modernization.
Application:
Functional purpose determines load-rating thresholds, material specifications, and regulatory certification pathways.
- Lightning Protection:Building and infrastructure grounding systems dissipate atmospheric electrical strikes through low-impedance pathways to earth. FAA airfield design standards and NFPA codes are tightening conductor sizing requirements for commercial aviation facilities.
- Surge Protection:Transmission line arrestors clamp transient overvoltages from switching operations and fault conditions. Utility infrastructure resilience programs are expanding procurement volumes across North American and European grid operators.
- Grounding Systems:Equipotential bonding and earth reference networks protect personnel and equipment from stray currents and fault conditions.
- Electrical Transmission:High-voltage line hardware integrates arrestor functions for insulation coordination and system reliability.
Lightning protection retains the deepest specification history; surge protection is expanding most quickly with grid hardening mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in the United States, where carrier air wing modernization and Air Force base upgrades absorb the bulk of metallic cable demand. Commercial certification tightening by the FAA is redirecting supplier investment toward dual-track quality systems serving both military and civilian airfields.
United States
Naval Air Systems Command procurement and FAA airfield design standards are the twin demand pillars. The FAA's updated certification requirements are compressing approval timelines for emergency arresting gear at commercial airports. Norfolk and San Diego cluster naval aviation infrastructure where legacy hook-wire replacement cycles are accelerating.
United Kingdom
Royal Air Force base modernization and NATO interoperability requirements are driving specification upgrades. The UK Ministry of Defence's procurement frameworks are mandating availability-based service contracts for arresting system lifecycle management. BAE Systems integration hubs in Lancashire and Warton concentrate defense aerospace supply chain coordination.
Germany
Luftwaffe airfield infrastructure renewal and NATO burden-sharing commitments are expanding procurement volumes. The country's national aviation regulator enforces EU-wide airworthiness standards through certification alignment with EASA frameworks. Bavaria's aerospace corridor around Munich hosts system integration specialists serving Central European defense customers.
France
Dassault Aviation fighter deployments and aircraft carrier modernization are sustaining naval arresting gear demand. The Direction Générale de l'Armement procurement office specifies MIL-SPEC compliant systems through competitive tender processes. Toulouse and Bordeaux aerospace clusters concentrate subsystem engineering for next-generation carrier platforms.
United Arab Emirates
Gulf state airbase expansion programs and regional security partnerships are opening procurement channels for certified emergency systems. The UAE's General Civil Aviation Authority is harmonizing military and civilian airfield standards through infrastructure investment mandates. Al Dhafra Air Base and emerging facilities in Abu Dhabi are absorbing expeditionary arresting system deployments.
Arrestor Cables Market Competitive Landscape
United States producers anchor the defense-tier supply base; European specialists hold commercial aviation and NATO procurement channels. The vendor structure stratifies across three tiers: prime contractors with captive R&D infrastructure, mid-scale fabricators with dual-track certification capability, and regional specialists serving national airfield operators. Consolidation pressure is intensifying as availability-based contracting elevates lifecycle service requirements above unit-price competition.
Within the prime contractor tier, General Atomics and Curtiss-Wright Corporation exemplify integrated system development positions. WireCo WorldGroup sits within the specialized materials archetype. These three anchors demonstrate how heritage in adjacent defense technologies translates into arresting gear procurement access, though their competitive differentiation increasingly rests on service metrics rather than hardware specifications alone.
| Leading Market Players |
|---|
| General Atomics |
| Curtiss-Wright Corporation |
| Runway Safe |
| SCAMA AB |
| Zodiac Aerospace |
| Atech Inc. |
| WireCo WorldGroup |
| MacTaggart Scott |
| QinetiQ |
| Others |
Value Network & Pricing Analysis
Carbon nanotube-reinforced polymer adoption is compressing traditional steel-wire cost structures while concentrating procurement leverage among dual-track certified suppliers. This materials transition simultaneously elevates R&D fixed costs and tightens supplier margins for metallic cable producers facing nickel and chromium volatility.
Pricing Analysis
Volume concentrates in MIL-SPEC certified metallic cables where margins remain protected by military specification compliance, while commercial aviation tiers face cost compression from FAA certification tightening. Price differentiation hinges on ISO 9001 certification tier and after-sales service bundling under availability-based contracts. Pricing pressure stems from electromagnetic recovery system substitution threats on naval platforms. Power utility buyers exhibit highest price sensitivity due to commodity-procurement frameworks, whereas Naval Air Systems Command contracts prioritize performance over unit cost.
Supply Chain Analysis
Certification gating restricts qualified suppliers to a narrow cohort with simultaneous FAA airworthiness and military specification compliance, concentrating production in the United States, Germany, and France. Raw material flows draw from specialized nickel-chromium alloy mills and high-performance polymer composite foundries. Supply chain risk centers on single-source vulnerability for extreme-load wire rope engineering talent. Distribution runs through prime contractor-direct channels for defense procurement and electrical transmission OEMs for utility applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FAA airfield design standards and Naval Air Systems Command specifications erect formidable barrier-to-entry moats for certified suppliers.
For Market Incumbents: Anticipate electromagnetic aircraft recovery system substitution by accelerating hybrid cable R&D investments and securing availability-based service contract renewals at Norfolk and San Diego naval clusters. Deepen backward integration into specialized wire rope engineering talent pipelines to defend against metallurgical expertise scarcity. For New Entrants and Emerging Players: General aviation facilities consolidating to pre-approved vendor lists represent the most penetrable buyer archetype for certified emergency arresting gear. Target grid hardening surge protection applications as an adjacent channel with lower certification barriers. Pursue partnership-based go-to-market models with electrical transmission OEMs to bypass direct FAA approval timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime contractor acquisitions of dual-track certified mid-scale fabricators. Long-term viability favors suppliers with captive polymer composite R&D and military service contract portfolios. Watch for unmanned aerial vehicle weight threshold revisions as the signal for material specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cable Development | Converged steel-synthetic architectures capture NATO airfield modernization specifications. |
| Availability-Based Contracting | Service metrics displace unit-price competition in U.S. Navy procurement frameworks. |
| Grid Hardening Partnership | Utility surge protection opens adjacent revenue channels beyond aviation applications. |
| Carbon Nanotube R&D Investment | Polymer composite advancement addresses unmanned platform weight reduction requirements. |
| Dual-Track Certification Expansion | Simultaneous FAA and military compliance widens addressable procurement pools. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Naval Air Systems Command procurement officers, FAA certification engineers, electrical transmission utility planners, and wire rope manufacturing plant managers. Bottom-up volume estimates triangulated against top-down defense budget allocations and infrastructure investment disclosures.
Data-stream reconciliation across product type, end-user mission profile, and installation topology dimensions shaped the analytical framework over the projection horizon. CAGRs derived from procurement cycle timing, replacement rate assumptions, and material substitution elasticity. Forecast inputs incorporated NATO burden-sharing commitments and grid hardening investment trajectories.
Revisions become necessary when electromagnetic recovery system adoption accelerates beyond pilot phases or FAA certification timelines compress further. Forecasts reflect assumptions on defense procurement continuity and specialty alloy price stability. A model refresh is warranted upon material change in unmanned aerial vehicle load-rating specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Global Submersible Slurry Pumps Market