
 Pneumatic Conveying Diverters Market | 2026-2036
Pneumatic Conveying Diverters Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Conveying Diverters Market Insights
Buyer consolidation among multinational food processors is recalibrating procurement specifications for pneumatic conveying diverters, favoring suppliers with global service networks and standardized platform designs. Coperion leverages its integrated compounding systems expertise to bundle diverter sales with upstream equipment. Zeppelin Systems anchors its position through project engineering capabilities across European starch and grain handling installations. DMN-WESTINGHOUSE specializes in rotary diverter configurations for high-pressure pneumatic lines, competing on sealing integrity under abrasive duty cycles.
Pneumatic conveying diverters are flow-control devices that redirect bulk solids between multiple destination points in pressurized or vacuum conveying systems, typically constructed with wear-resistant housings, precision-machined sealing surfaces, and actuated disc or plug mechanisms rated for pressure differentials up to 15 psi and temperatures exceeding 200°C. Their primary purpose is to enable continuous, contamination-free distribution of powders, granules, and pellets across parallel process lines without system depressurization. Rotary diverters dominate installations in cement and mining operations where abrasive mineral throughput demands hardened alloy construction and minimal maintenance intervals. Stainless steel material grades command premium positioning in pharmaceutical manufacturing and food processing applications where surface finish requirements and cleanability validation under FDA and EFSA frameworks create margin pools above standard carbon steel offerings.
EPA NESHAP standards for particulate matter emissions from pneumatic conveying systems in US mineral processing facilities mandate sealed diverter designs with verified leakage rates below prescribed thresholds. REACH substance restrictions and the EU Machinery Directive's safety integration requirements shape material selection and actuator guarding specifications for European installations. China's GB standards for dust explosion prevention in bulk solids handling impose construction and certification requirements on diverter suppliers accessing domestic cement and chemical markets. Stakeholders should monitor evolving PFAS restrictions under ECHA proposals, as fluoropolymer seal materials common in food-grade diverters face prospective substitution mandates that could reshape supplier qualification timelines and retrofit demand.
Market Dynamics
Buyer consolidation among multinational food processors is recalibrating procurement specifications toward suppliers with global service networks and standardized platform designs, compressing margins for regional specialists while rewarding integrated system providers.
Growth Catalysts
- EU F-Gas Regulation:Compliance mandates for sealed, low-emission diverter designs are accelerating replacement cycles across European starch and grain handling installations.
- Abrasive mineral throughput demands:Cement and mining operations require hardened alloy construction with minimal maintenance intervals, sustaining premium positioning for rotary diverter configurations.
- Germany's industrial corridor:Bulk solids handling infrastructure upgrades are concentrating demand for automated material handling systems with contamination-free distribution capabilities.
Market Restraints
- Alloy input cost volatility:Hardened steel and specialty alloy prices fluctuate with mining output, pressuring margins on wear-resistant housing production.
- Fluoropolymer seal dependency:Prospective ECHA PFAS substitution mandates threaten supply continuity for food-grade diverter components.
- High-pressure sealing limitations:Precision-machined surfaces face degradation thresholds above 15 psi differentials in abrasive duty cycles.
Strategic Opportunities
- Pharmaceutical surface finish validation:FDA and EFSA cleanability requirements create margin pools above standard carbon steel offerings for stainless steel material grades.
- China's GB dust explosion standards:Certification requirements for cement and chemical markets open retrofit demand for sealed diverter designs with verified leakage rates.
- Actuator guarding integration:EU Machinery Directive safety requirements are unifying diverter and control system procurement decisions.
Industry Challenges
- Cleanability validation expertise:Pharmaceutical and food-grade applications require specialized surface finish documentation that stretches supplier qualification timelines.
- Legacy system integration friction:Upgrading pressurized conveying lines without complete shutdown demands modular diverter designs compatible with existing flange configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Conveying Diverters Market |
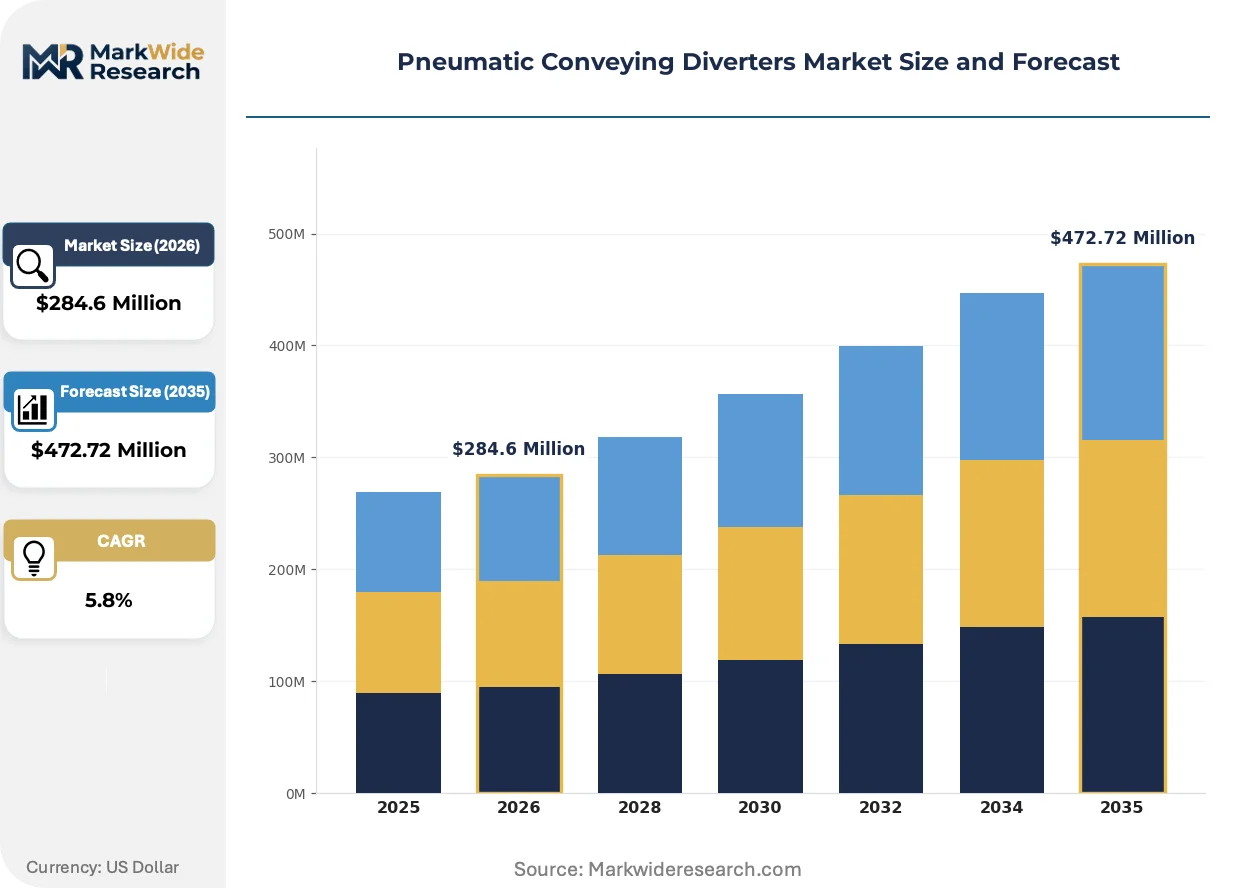
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $472.72 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Diverters, Slide Gate Diverters, Pop-up Diverters, Sleeve Valve Diverters Material: Stainless Steel, Carbon Steel, Cast Iron, Aluminum, Polymer Application: Bulk Material Handling, Food Processing, Pharmaceutical Manufacturing, Chemical Processing, Packaging End User Industry: Mining Operations, Cement Plants, Paper Manufacturing, Plastics Production, Agriculture Processing |
| Companies Covered | Coperion, Zeppelin Systems, Qlar, Gericke, DMN-WESTINGHOUSE, Palamatic Process, FLSmidth, Atlas Copco, VAC-U-MAX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Conveying Diverters Market Trends and Innovations
Sealed diverter architectures are displacing conventional designs as emission thresholds tighten across mineral processing and food handling installations. Material selection and actuator integration are converging under unified compliance frameworks.
Modular plug-and-play diverter assemblies with integrated position feedback are unifying maintenance protocols across multi-site operator portfolios. Food processors with pan-European footprints are standardizing on these configurations to reduce spare parts inventories. The technology is unifying procurement decisions that previously separated mechanical and control system vendors.
EPA NESHAP particulate matter standards for US mineral processing facilities are mandating verified leakage rate documentation for all new diverter installations. Sealed designs with third-party certification are becoming baseline specifications in request-for-quotation documents. Cement producers in the Midwest and Mountain West regions are accelerating replacement schedules to preempt enforcement actions.
Specification bundling is compressing vendor selection cycles as multinational buyers consolidate pneumatic conveying equipment procurement under integrated system contracts. Regional specialists face exclusion from qualified bidder lists without global service networks. This pattern is most visible in Germany's starch processing corridor and the US grain belt, where facility operators prioritize single-source accountability over component-level sourcing.
Pneumatic Conveying Diverters Market Segmentation
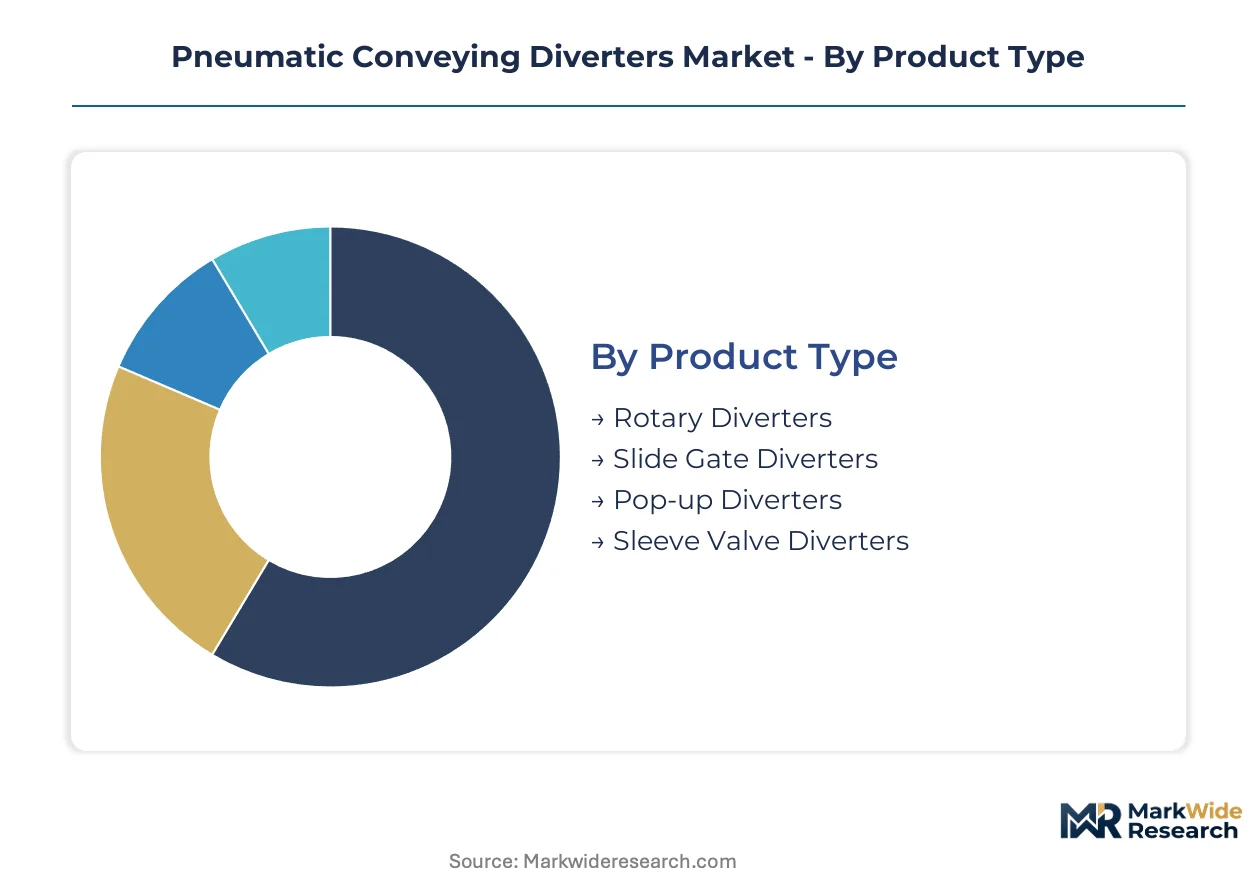
Pneumatic conveying diverters serve distinct operational requirements across pressure ratings, abrasion tolerance, and contamination control. Specification alignment with end-use severity determines procurement decisions and supplier qualification pathways.
Product Type:
Rotary configurations dominate high-pressure mineral handling where sealing integrity under abrasive cycling commands premium positioning.
- Rotary Diverters:Disc or plug mechanisms rotate within hardened alloy housings to redirect flow between pressurized lines without depressurization. Cement plants in Germany's industrial corridor specify these for continuous mineral throughput exceeding 200°C and 15 psi differentials.
- Slide Gate Diverters:Linear actuated blades traverse rectangular or circular ports to isolate destination lines. Bulk material handlers favor these for simple maintenance protocols and compatibility with existing flange standards during retrofit installations.
- Pop-up Diverters:Piston-style plugs rise to seal alternate ports in low-profile configurations.
- Sleeve Valve Diverters:Flexible elastomer sleeves compress to direct flow in gentle-handling applications.
Mature deployment sits with Rotary Diverters. Newer deployment is concentrated in Slide Gate Diverters.
Material:
Surface finish validation requirements fragment procurement across FDA-regulated food processing and abrasion-dominated mining operations.
- Stainless Steel:Grades 304 and 316L deliver Ra surface finishes below 0.8 micrometers for pharmaceutical cleanability validation under FDA and EFSA frameworks. Food processors pay substantial premiums for these specifications versus carbon alternatives.
- Carbon Steel:Standard housings with protective coatings serve non-corrosive bulk solids in cost-sensitive cement and grain applications.
- Cast Iron:Ductile iron variants absorb impact loads in heavy mineral handling.
- Aluminum:Lightweight housings reduce actuator sizing in low-pressure pneumatic systems.
- Polymer:Reinforced thermoplastics eliminate metallic contamination in sensitive chemical processing.
Carbon Steel retains the largest installed base. Stainless Steel is climbing the fastest as cleanability mandates expand beyond pharmaceutical into premium food tiers.
Application:
Contamination-free distribution requirements concentrate specification authority in multinational food and pharmaceutical operators with pan-European footprints.
- Bulk Material Handling:High-volume mineral and grain distribution through pressurized lines demands wear-resistant sealing surfaces and rapid actuation cycles. Midwest US cement producers accelerate replacement schedules to meet EPA NESHAP leakage documentation requirements.
- Food Processing:Automated starch and grain handling installations require sealed, low-emission designs under EU F-Gas Regulation compliance mandates.
- Pharmaceutical Manufacturing:Surface finish documentation stretches supplier qualification timelines for cleanability validation.
- Chemical Processing:Corrosion-resistant material grades handle reactive powder transfer.
- Packaging:Compact diverters integrate into finished goods filling lines.
Food Processing leads current procurement volume. Pharmaceutical Manufacturing shows the steepest specification escalation trajectory.
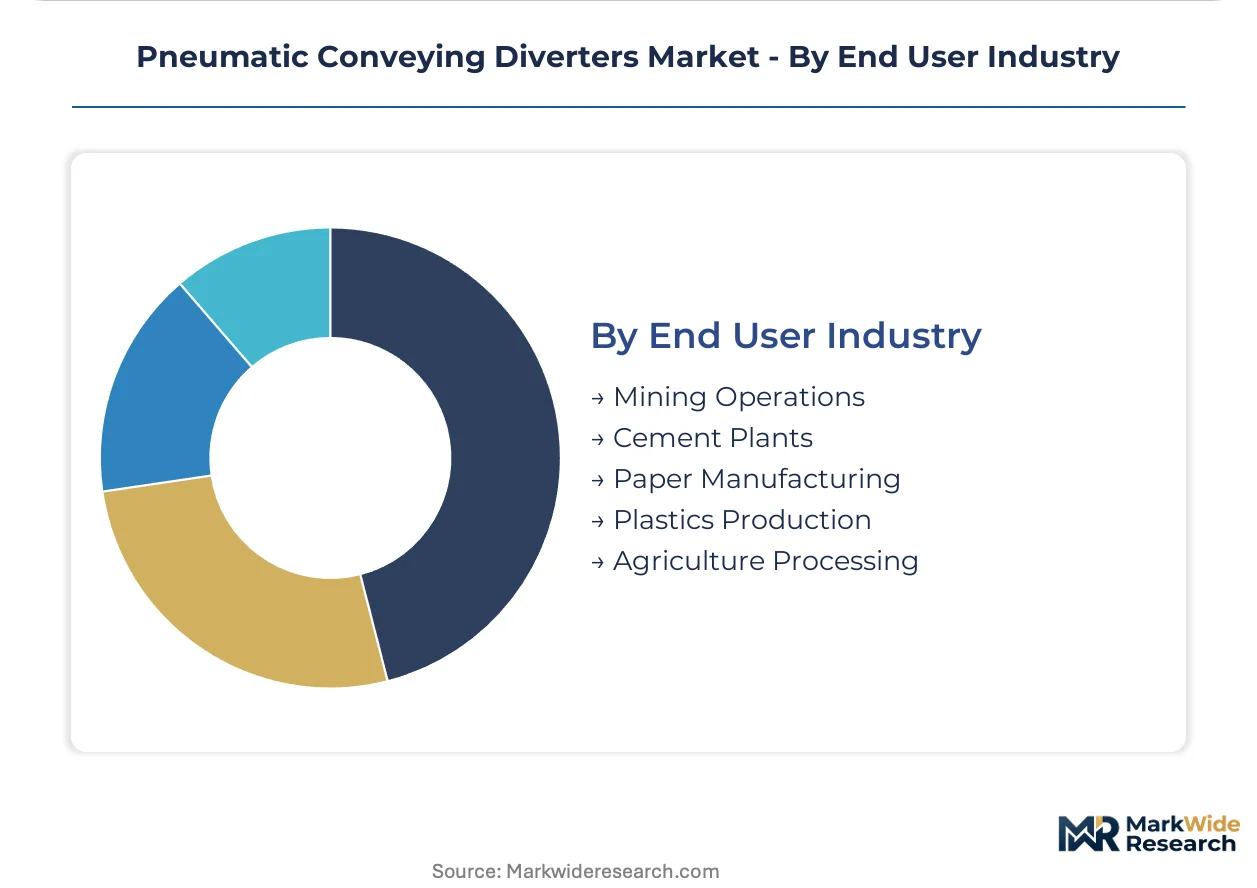
End User Industry:
Infrastructure upgrade cycles and emission enforcement timelines create asynchronous demand peaks across heavy industry verticals.
- Mining Operations:Abrasive mineral throughput at remote sites demands hardened alloy construction with extended maintenance intervals. Rotary configurations with tungsten carbide sealing surfaces dominate these specifications.
- Cement Plants:EPA NESHAP particulate standards mandate verified leakage rate documentation, accelerating sealed diverter adoption in US Mountain West facilities.
- Paper Manufacturing:Wood fiber handling requires corrosion-resistant materials for humid environments.
- Plastics Production:Pellet diversion at extrusion lines favors gentle-handling sleeve configurations.
- Agriculture Processing:Grain elevator automation standardizes on modular plug-and-play assemblies with integrated position feedback.
Cement Plants anchor replacement demand. Agriculture Processing is gaining share fastest through automation standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia and hard coal seams in Germany's Ruhr Basin anchor regional demand for abrasion-resistant pneumatic handling equipment. Bulk mineral throughput infrastructure upgrades concentrate procurement authority in industrial corridors with established cement and mining footprints.
United States
Midwest cement producers accelerate sealed diverter replacement schedules to preempt EPA NESHAP enforcement actions. The Mountain West region concentrates bulk mineral handling infrastructure where particulate matter thresholds drive specification escalation. Denver-area engineering firms report rising retrofit demand for verified leakage-rate documentation.
Germany
EU F-Gas Regulation compliance mandates push starch and grain processors toward low-emission diverter architectures. REACH substance restrictions reshape material selection timelines for food-grade installations. North Rhine-Westphalia's industrial corridor hosts the densest concentration of automated bulk solids handling upgrades.
China
GB standards for dust explosion prevention in cement and chemical markets impose certification requirements on diverter suppliers. Domestic producers expand captive alloy foundry capacity to reduce hardened steel input dependency. Shandong Province's chemical processing clusters drive demand for corrosion-resistant flow control systems.
Australia
Iron ore export terminals in Western Australia specify rotary diverters with tungsten carbide sealing surfaces for abrasive mineral throughput. Mining automation programs standardize on modular plug-and-play assemblies with integrated position feedback. Perth-based engineering contractors bundle diverter procurement with conveyor system overhauls.
India
FSSAI cleanability mandates expand stainless steel diverter specifications beyond pharmaceutical into premium food processing tiers. The country's national bulk handling regulator imposes construction standards on grain elevator automation projects. Gujarat's chemical manufacturing corridor concentrates import demand for sealed, low-emission designs.
Pneumatic Conveying Diverters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized sealing technologies and regional service density. The vendor base stratifies between integrated system providers with project engineering capabilities and component specialists competing on abrasion-resistant material grades. Two dominant archetypes prevail: multinational bulk handling conglomerates bundling diverters with upstream equipment, and regional fabricators competing on retrofit compatibility with legacy flange standards. Competitive moves concentrate on backward integration into alloy foundry operations and technology licensing for modular actuator integration.
Among German-based engineering groups, Coperion and Zeppelin Systems exemplify the integrated system provider archetype, anchoring procurement decisions through project-level accountability rather than component sales. DMN-WESTINGHOUSE occupies a position within the specialist tier, representing Dutch fabrication expertise in high-pressure rotary configurations. These three entities illustrate the competitive tension between bundled system contracts and standalone component qualification pathways that shapes vendor selection cycles across European starch processing and US grain belt installations.
| Leading Market Players |
|---|
| Coperion |
| Zeppelin Systems |
| Qlar |
| Gericke |
| DMN-WESTINGHOUSE |
| Palamatic Process |
| FLSmidth |
| Atlas Copco |
| VAC-U-MAX |
| Others |
Pricing and Supply Chain Analysis
Precision machining specialists concentrated in Germany's Ruhr Basin and northern Italy's industrial districts command wage premiums that widen spreads between premium alloy diverters and standard carbon steel configurations. Labor-cost differentials between these engineering clusters and Eastern European fabrication zones translate directly into three-tier pricing stratification across European procurement markets.
Pricing Analysis
Volume-margins split sharply between bulk mineral handlers purchasing standardized rotary configurations at contract rates and pharmaceutical operators paying substantial premiums for FDA-validated surface finishes. Pricing stratifies across premium, standard, and economy tiers where stainless steel grades with Ra sub-0.8 micrometer documentation command multiples above protective-coated carbon alternatives. Cost compression in the standard tier intensifies as Chinese foundry capacity expands into hardened alloy production. Cement producers in the US Mountain West exhibit highest price sensitivity due to EPA compliance-driven replacement schedules, while pharmaceutical cleanability mandates render European drug manufacturers least sensitive to unit cost.
Supply Chain Analysis
Refurbishment flows for tungsten carbide sealing surfaces create reverse logistics networks from Australian mining sites back to German reconditioning facilities, extending component lifecycles and compressing new-build demand cycles. Manufacturing concentration centers on Germany, China, and Italy for precision-machined housings, with specialty alloy feedstock drawing from Swedish and Austrian steel producers. Supply chain vulnerability rests on single-source dependency for fluoropolymer seal compounds facing prospective ECHA substitution mandates. Distribution runs through project engineering firms bundling diverters with upstream pneumatic conveying equipment rather than standalone component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized foundry capacity for hardened alloy housings operates at effective utilization ceilings, constraining supply elasticity and sustaining pricing power for qualified suppliers despite input cost volatility.
For Market Incumbents: Anchor market position through captive alloy foundry investments in Germany's industrial corridor to secure tungsten carbide supply continuity against emerging Chinese competition. Deepen project engineering capabilities to bundle diverter sales with control system integration, preempting specification unbundling by multinational food processors. Prioritize REACH-compliant material qualification pipelines to accelerate PFAS-free seal validation ahead of regulatory enforcement timelines. For New Entrants and Emerging Players: Begin with modular plug-and-play retrofit configurations targeting US Midwest cement plants facing accelerated EPA NESHAP replacement schedules without complete line shutdown capability. India's FSSAI cleanability mandate expansion into premium food processing offers the most penetrable white-space for stainless steel specialists lacking pharmaceutical validation heritage. Pursue technology licensing partnerships with established actuator manufacturers to bypass control system integration barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier European fabricators possessing REACH pre-qualified material portfolios given accelerating substitution demand from fluoropolymer-dependent competitors. Long-term viability over the next decade favors suppliers with backward integration into specialty alloy production and pan-European service networks. Monitor ECHA PFAS restriction finalization timelines as the critical inflection signal for seal material retrofit demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Foundry Operations | Captive tungsten carbide supply secures margin stability against Swedish steel input volatility. |
| REACH-Compliant Seal Material Certification | PFAS-free validation accelerates supplier qualification for EU starch processing procurement cycles. |
| Modular Retrofit Platform Development | Plug-and-play compatibility with legacy flange standards unlocks US cement plant replacement demand. |
| Project Engineering Capability Expansion | Integrated system bundling preempts component-level sourcing by multinational food processors. |
| Pharmaceutical Surface Finish Validation Investment | FDA documentation expertise creates margin pools above standard carbon steel offerings. |
Research Methodology
Document review covered customs trade databases, SEC filings from bulk handling equipment manufacturers, and EU regulatory filings, complemented by interviews with plant engineers at cement and grain processing facilities, procurement leads at multinational food processors, aftermarket service heads at pneumatic conveying distributors, and technical R&D directors at alloy foundry operations. Secondary validation drew from EPA enforcement action records, ECHA substance restriction proposals, and GB standard certification registries. Bottom-up installation data triangulated against top-down equipment spending estimates across the analysis window.
Historical shipment patterns cross-referenced against expert panel input from engineering contractors in Germany's North Rhine-Westphalia corridor and Denver-area retrofit specialists. Segmentation modeling captured product type, material grade, application severity, and end-user industry vertical. CAGRs derived from regression analysis of replacement cycle timing against regulatory enforcement schedules. Forecast inputs incorporated alloy price indices and dust explosion standard adoption trajectories without year-specific anchoring.
Underlying measurement precision varies by segment; pharmaceutical and food-grade specifications carry tighter precision than bulk mineral handling due to documentation requirements. Forecasts reflect assumptions about regulatory enforcement timing and alloy input cost stabilization. Practitioners should monitor ECHA PFAS restriction finalization and EPA NESHAP inspection intensity for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Light Duty Telehandler Market