
 Sorting Equipment Market | 2026-2036
Sorting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sorting Equipment Market Outlook
Near-infrared polymers are repositioning optical sorter configurations across recycling lines, replacing legacy RGB camera arrays with hyperspectral detection modules. TOMRA Systems ASA leverages deep-learning classification algorithms to sustain technology leadership in post-consumer plastic recovery. Bühler Group anchors its position through captive sensor manufacturing and grain-specific optical calibration for food processing clients. Sesotec GmbH competes on magnetic resonance detection for mixed-waste streams, differentiating from camera-based rivals.
Sorting equipment comprises automated material separation systems utilizing electromagnetic sensors, compressed air ejectors, and conveyor-fed detection arrays to classify objects by physical or chemical properties at throughput rates exceeding multiple tons per hour. Optical sorters dominate installed value due to mature hyperspectral imaging supply chains and proven uptime in 24-hour food processing operations. AI-based sorting technology captures the fastest expansion trajectory as neural network training reduces false-reject rates below legacy mechanical thresholds. Conveyor sorters occupy stable replacement demand in logistics hubs where barcode-scanning integration with warehouse management systems drives retrofit cycles.
EPA hazardous waste classification rules and EU REACH substance restrictions shape equipment design requirements for metal recovery and e-waste sorting applications. FDA food safety modernization standards mandate detectable foreign-object removal thresholds that directly determine optical sorter resolution specifications for fruit and vegetable processors. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between modular upgrade paths versus full-platform replacements as detection technologies shift from rule-based algorithms to self-training neural architectures.
Market Dynamics
Neural-network-based detection architectures are compressing replacement cycles across food processing and recycling installations, forcing equipment vendors to pivot from hardware-margin models toward software-recurring revenue streams.
Growth Catalysts
- EU Green Deal waste diversion mandates:Post-consumer plastic recycling quotas in Germany, France, and Italy are accelerating optical sorter procurement for municipal material recovery facilities.
- Near-infrared hyperspectral modules:Polymer identification accuracy improvements are expanding addressable waste streams beyond legacy PET and HDPE categories into mixed-flexible packaging.
- Food processing yield recovery targets:FDA foreign-object detection thresholds for frozen vegetable processors are mandating sub-millimeter optical resolution upgrades.
Market Restraints
- Sensor supply concentration:InGaAs photodiode production concentrates in Japanese and German specialty semiconductor fabs, creating 16-24 week lead time volatility for hyperspectral camera manufacturers.
- Compressed air system energy intensity:Pneumatic ejector arrays consume 15-25% of facility power draw, exposing operators to EU ETS carbon pricing pass-through costs.
- Mechanical density separator substitution:Air classification and sink-float tanks retain cost advantages for low-value construction and demolition waste streams.
Strategic Opportunities
- India PLI scheme for food processing:Domestic optical sorter assembly incentives are opening import-substitution pathways for European and Japanese component suppliers.
- Converged X-ray and optical detection:Dual-sensor fusion for bone fragment and glass shard identification is creating premium pricing tiers in poultry and prepared meal segments.
- Extended producer responsibility expansion:California, Washington, and Oregon state-level packaging fee structures are funding municipal sorting infrastructure retrofits.
Industry Challenges
- Mechatronics integration complexity:Retrofitting legacy conveyor lines with AI-enabled detection arrays requires synchronization with programmable logic controllers and warehouse management systems.
- Hyperspectral calibration expertise gap:Field service engineers with chemometric model training are scarce relative to deployment timelines for multi-material recycling contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorting Equipment Market |
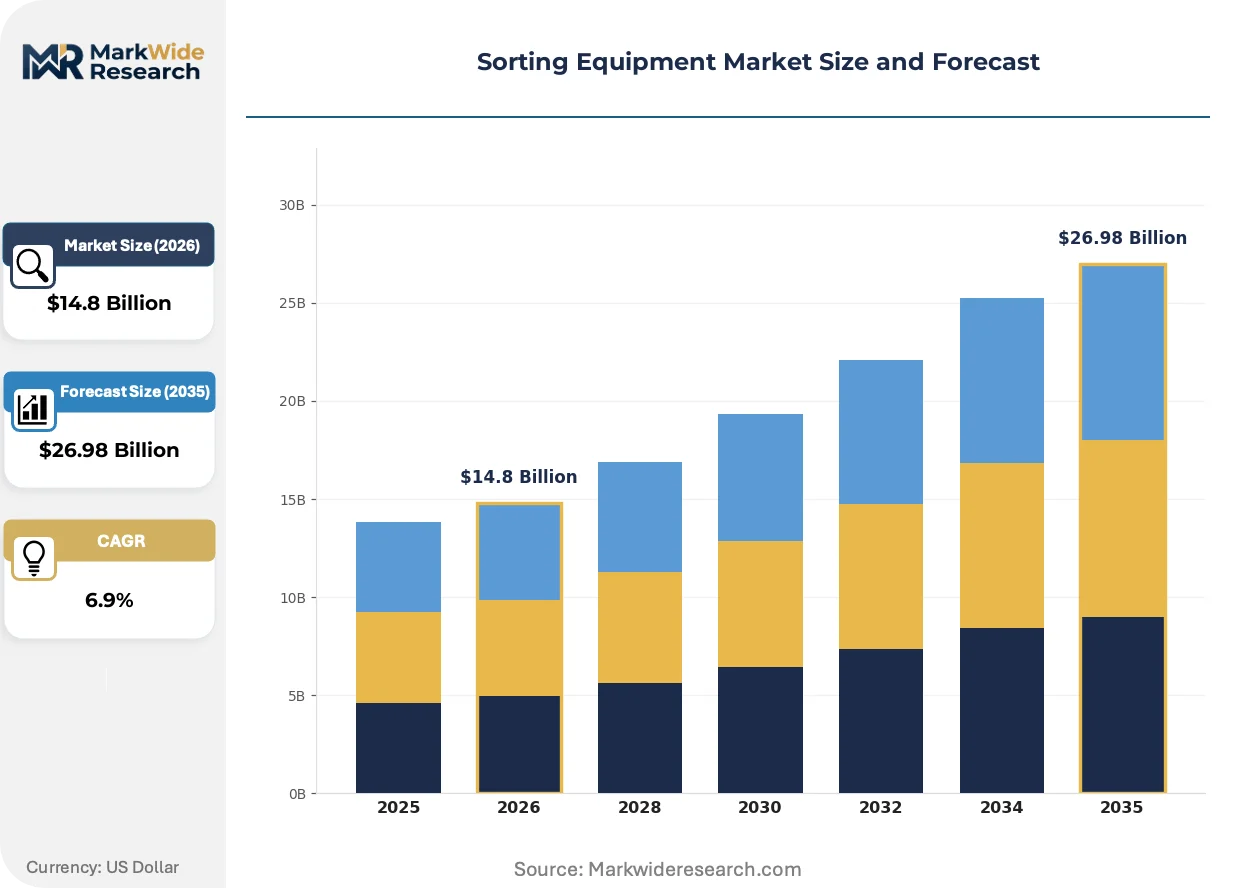
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sorters, Conveyor Sorters, Robotic Sorters, Manual Sorters Technology: Mechanical Sorting, Optical Technology, AI-Based Sorting, Vibration Sorting End User: Food Processing, Recycling Industry, Mining Sector, Logistics Application: Fruit Sorting, Plastic Recycling, Metal Sorting, Package Sorting |
| Companies Covered | TOMRA Systems ASA, Bühler Group, Sesotec GmbH, Satake Corporation, Key Technology, Steinert Global, Duravant LLC, Binder+Co AG, Hefei Meyer Optoelectronic Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorting Equipment Market Strategic Shifts
Detection technology convergence is collapsing the historical separation between food safety and recycling applications, with neural network architectures trained on one domain transferring to adjacent material streams.
Self-training convolutional neural networks are overtaking rule-based classification algorithms in post-consumer plastic recovery lines. German and Dutch recycling cooperatives are deploying these systems for real-time polymer identification at throughputs exceeding five tons per hour. The shift is compressing vendor software update cycles from annual releases to continuous cloud-delivered model improvements.
EU REACH substance restrictions on brominated flame retardants are forcing e-waste sorting facilities to deploy laser-induced breakdown spectroscopy for hazardous material segregation. Equipment vendors must now certify compliance with both RoHS substance thresholds and WEEE collection quotas. Metal recovery operators in Belgium and the Netherlands are absorbing 12-18 month certification timelines for new detection modalities.
Buyers are unbundling after-sales service contracts from initial equipment procurement, preferring third-party maintenance providers with multi-vendor expertise. Food processors in California's Central Valley are consolidating service relationships with independent technical firms rather than OEM captive service arms. This procurement pattern is eroding vendor service margin pools and accelerating spare parts commoditization.
Sorting Equipment Market Segmentation
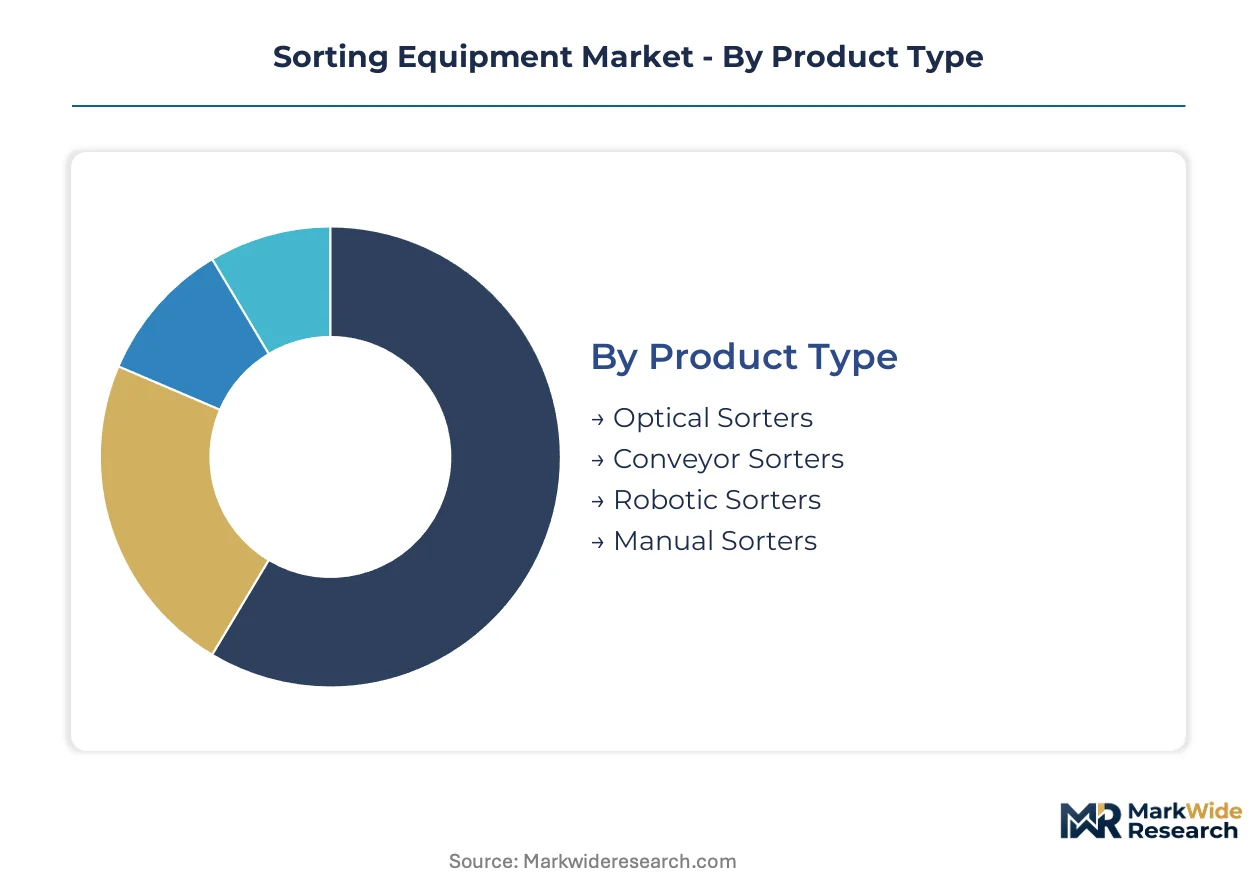
Sorting equipment procurement varies sharply by operational throughput requirements and contamination tolerance thresholds. Buyers in food processing prioritize sub-millimeter detection resolution, while recycling operators optimize for polymer identification breadth across mixed-waste streams.
Product Type:
Equipment selection hinges on capital intensity tolerance versus labor substitution economics across processing environments.
- Optical Sorters:Hyperspectral imaging arrays with InGaAs photodiode sensors classify materials by chemical signature at throughputs exceeding five tons per hour. Food processing facilities in Germany and California's Central Valley are retrofitting legacy RGB configurations with near-infrared modules to meet FDA foreign-object detection mandates.
- Conveyor Sorters:Barcode-scanning integration with warehouse management systems drives replacement cycles in logistics hubs. Amazon and DHL distribution centers are standardizing on modular retrofit kits rather than full-platform replacements to preserve existing belt infrastructure.
- Robotic Sorters:Articulated pick-and-place arms with vision-guided grippers target irregular object handling in e-waste and construction debris streams.
- Manual Sorters:Human-operated quality control stations persist in premium specialty crop segments where tactile assessment outperforms machine vision.
Volume sits with Conveyor Sorters; growth tilts toward Optical Sorters.
Technology:
Detection modality determines false-reject rates and energy consumption profiles that shape total cost of ownership calculations.
- AI-Based Sorting:Self-training convolutional neural networks reduce classification error rates below legacy mechanical thresholds through continuous cloud-delivered model updates. Dutch and German recycling cooperatives are deploying these architectures for real-time polymer identification at municipal material recovery facilities.
- Optical Technology:Hyperspectral camera modules leverage near-infrared reflectance spectroscopy to distinguish polymer grades invisible to RGB arrays. Japanese and German specialty semiconductor fabs supply the InGaAs photodiodes that create 16-24 week procurement lead times for equipment manufacturers.
- Mechanical Sorting:Density-based air classification and sink-float separation retain cost advantages for low-value construction and demolition waste streams where contamination tolerance is high.
- Vibration Sorting:Oscillating deck screens with amplitude-tuned drives separate by particle size in mining and aggregate applications.
Optical Technology commands installed value; AI-Based Sorting is gaining share fastest.
End User:
Regulatory compliance intensity and yield recovery economics differentiate procurement priorities across verticals.
- Food Processing:Frozen vegetable processors face FDA modernization standards mandating detectable foreign-object removal thresholds that directly determine optical sorter resolution specifications. Yield recovery targets of 99.5% plus drive hyperspectral upgrade cycles.
- Recycling Industry:EU Green Deal waste diversion mandates and California's extended producer responsibility frameworks are funding municipal infrastructure retrofits. Post-consumer plastic quotas in Germany, France, and Italy accelerate optical sorter procurement for material recovery facilities.
- Mining Sector:Ore grade sensor-based sorting reduces downstream processing energy intensity through early gangue rejection.
- Logistics:E-commerce fulfillment velocity requirements push barcode-scanning conveyor retrofits with warehouse management system integration.
Food Processing anchors technology development; Recycling Industry shows the steepest expansion trajectory.
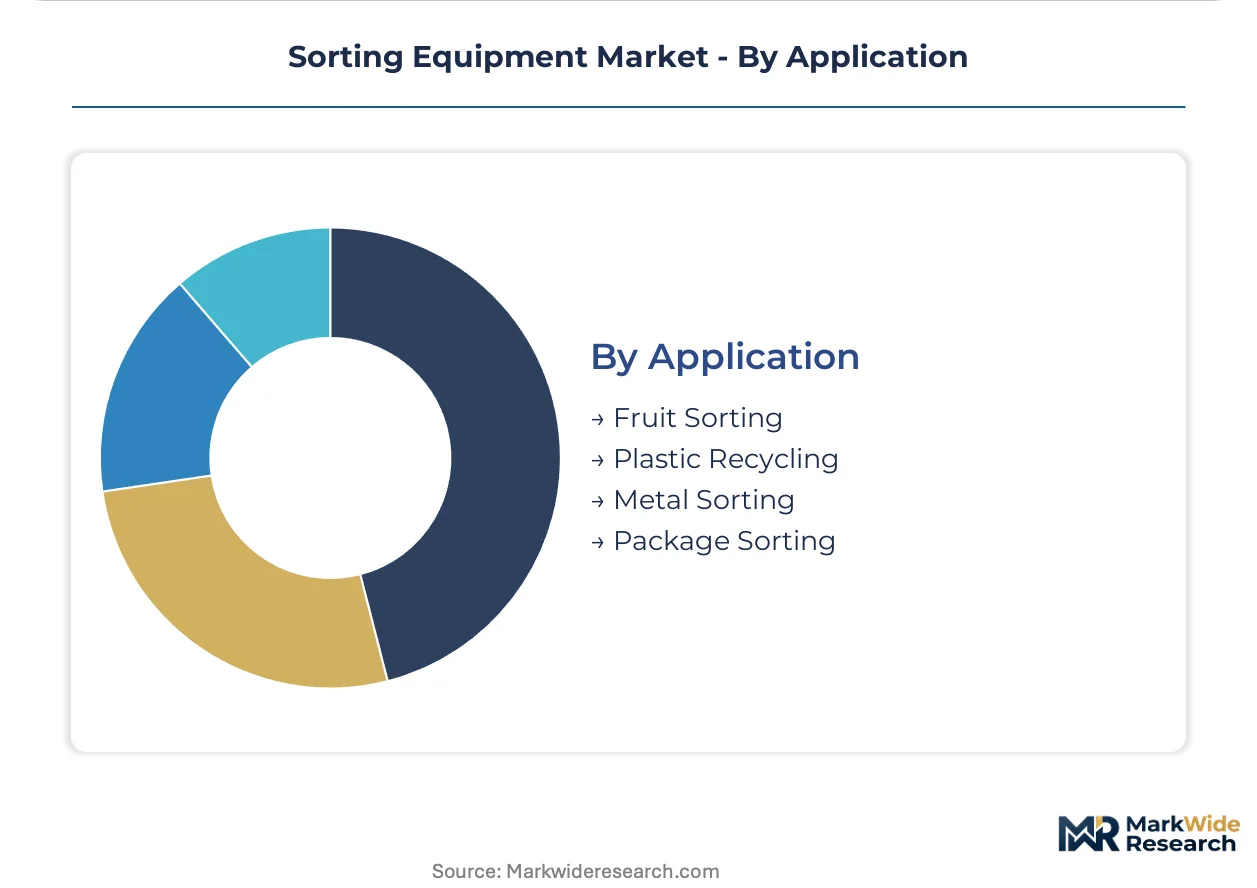
Application:
Material physical properties and contamination risk profiles dictate sensor configuration and ejector array design.
- Plastic Recycling:Mixed-flexible packaging streams beyond legacy PET and HDPE categories require near-infrared hyperspectral modules with chemometric model calibration. Belgium and Netherlands e-waste facilities absorb 12-18 month certification timelines for laser-induced breakdown spectroscopy deployment under EU REACH substance restrictions.
- Fruit Sorting:Stone fruit and berry processors deploy sub-millimeter optical resolution to detect stem fragments and surface defects. California's Central Valley operations are unbundling after-sales service contracts from initial procurement, consolidating relationships with independent technical firms.
- Metal Sorting:Eddy current and X-ray fluorescence sensors recover non-ferrous fractions from shredded automotive and electronics waste.
- Package Sorting:Dimensioning and weight integration with sort-to-light systems optimizes last-mile distribution center throughput.
Plastic Recycling drives sensor innovation; Fruit Sorting sustains replacement demand stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in Germany, the United States, and China, where regulatory mandates and processing scale create concentrated upgrade cycles. Municipal waste diversion targets and food safety modernization drive parallel investment waves across these markets.
Germany
Post-consumer plastic quotas under the EU Green Deal accelerate optical sorter deployment at municipal material recovery facilities. The country's national packaging regulator enforces extended producer responsibility fee structures that fund infrastructure retrofits. The Rhine-Ruhr industrial corridor hosts dense clusters of recycling cooperatives deploying near-infrared hyperspectral modules for mixed-flexible packaging streams.
United States
FDA foreign-object detection thresholds for frozen vegetable processors mandate sub-millimeter optical resolution upgrades in California's Central Valley. EPA hazardous waste classification rules shape equipment specifications for metal recovery and e-waste sorting applications. The Central Valley fruit processing belt unbundles after-sales service contracts from initial procurement, consolidating relationships with independent technical firms.
China
Dual carbon goals and municipal waste diversion targets accelerate automated sorting investments in Yangtze River Delta material recovery facilities. The Ministry of Ecology and Environment enforces waste classification standards that drive optical sorter procurement. Shanghai and Suzhou industrial zones concentrate hyperspectral camera assembly operations serving domestic food processing and recycling sectors.
Japan
InGaAs photodiode production concentrates in Japanese specialty semiconductor fabs, creating supply chain leverage for domestic equipment manufacturers. METI industrial efficiency standards promote AI-based detection architectures in food processing and electronics recycling. The Nagoya-Tokyo manufacturing belt anchors photodiode fabrication serving global hyperspectral camera manufacturers.
India
PLI scheme incentives for food processing open import-substitution pathways for European and Japanese optical sorter component suppliers. The Food Safety and Standards Authority of India mandates detectable foreign-object removal thresholds that drive resolution specifications. Maharashtra and Gujarat industrial corridors attract domestic assembly investments for grain-specific optical calibration systems.
Sorting Equipment Market Competitive Environment
Technology licensing dominates the current landscape as vendors pivot from hardware-margin models toward software-recurring revenue streams. The vendor base stratifies across integrated sensor manufacturers, specialized detection technology developers, and modular retrofit providers. Three archetypes anchor competitive positioning: captive sensor producers with in-house photodiode supply, AI-software specialists leveraging cloud-delivered model updates, and regional fabricators serving price-sensitive emerging markets. Portfolio diversification and geographic expansion represent the dominant competitive moves as neural-network architectures compress replacement cycles.
Among European-anchored specialists, TOMRA Systems ASA and Bühler Group exemplify divergent strategic positions within the premium tier. TOMRA represents the AI-software archetype with deep-learning classification algorithms, while Bühler occupies the captive manufacturing position through controlled sensor production. Sesotec GmbH anchors the specialized detection tier, differentiating through magnetic resonance capabilities for mixed-waste applications. These three entities collectively illustrate how technology specialization and supply chain control define competitive separation in a market shifting from mechanical to neural architectures.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler Group |
| Sesotec GmbH |
| Satake Corporation |
| Key Technology |
| Steinert Global |
| Duravant LLC |
| Binder+Co AG |
| Hefei Meyer Optoelectronic Technology |
| Others |
Value Chain & Pricing Dynamics
Captive sensor manufacturing anchors both supply security and pricing power for premium-tier vendors, as in-house InGaAs photodiode production insulates against Japanese and German specialty semiconductor fab lead time volatility while supporting margin retention against commoditized retrofit competitors.
Pricing Analysis
Volume concentrates in conveyor sorter retrofits where barcode-scanning integration commands standard-tier margins, while premium pricing stratifies across premium, standard, and economy tiers based on hyperspectral resolution grade and AI-software subscription bundling. Cost compression in the economy tier intensifies because third-party maintenance providers with multi-vendor expertise are eroding OEM service margin pools. Food processors in California's Central Valley exhibit highest price sensitivity through unbundled procurement patterns, whereas German recycling cooperatives absorb premium positioning for real-time polymer identification capabilities.
Supply Chain Analysis
Dual-sourcing requirements for InGaAs photodiodes mandate qualification across Japanese and German specialty semiconductor fabs, as equipment manufacturers hedge against 16-24 week lead time volatility. Hyperspectral camera modules draw from concentrated photodiode fabrication in the Nagoya-Tokyo manufacturing belt and Rhine-Ruhr industrial corridor, with compressed air ejector arrays and conveyor belt systems sourced from Italian and Chinese mechanical component suppliers. Single-source vulnerability in photodiode supply creates exposure to export restriction shocks. Distribution runs through OEM direct sales for premium AI-enabled platforms and regional fabricator networks for price-sensitive emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
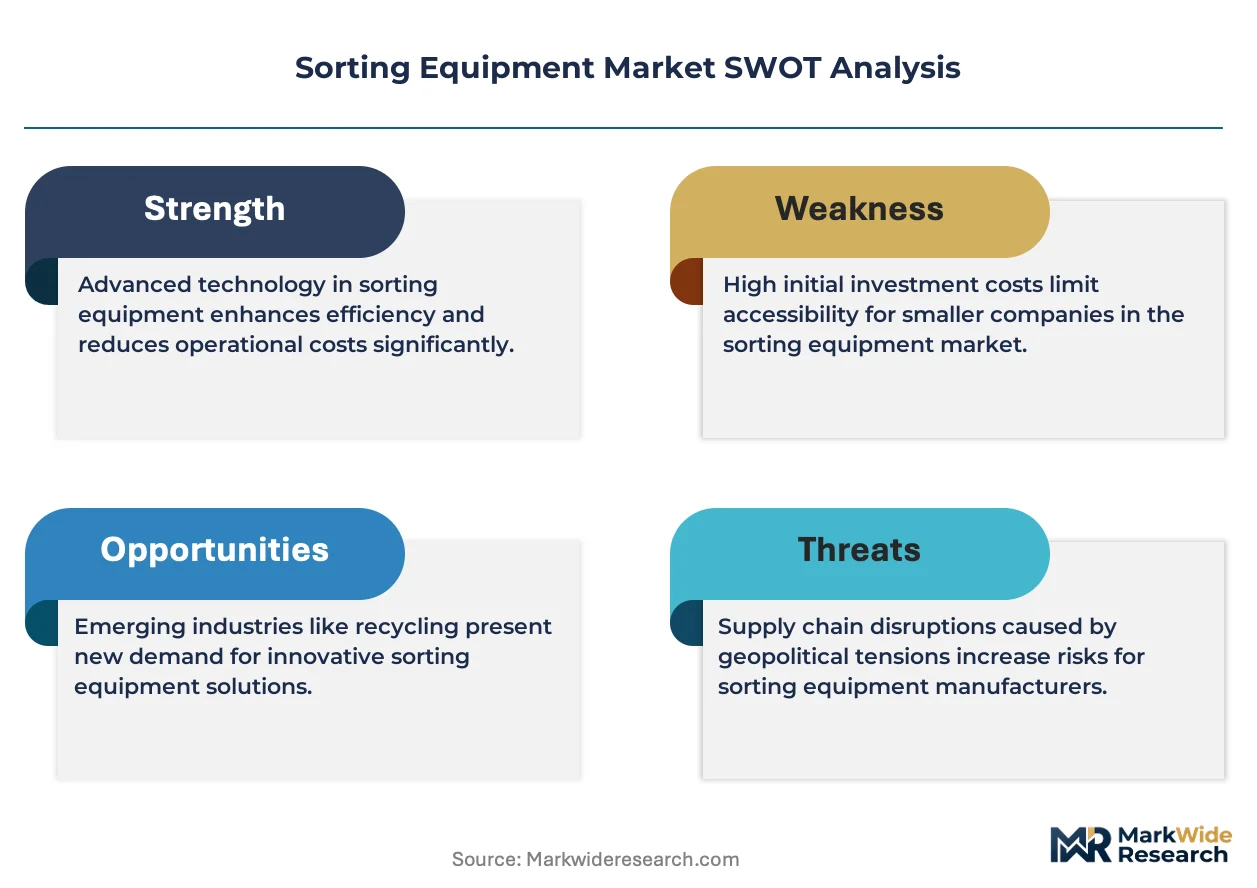
InGaAs photodiode fab capacity constraints prop pricing power for vendors with captive sensor supply, as Japanese and German specialty semiconductor output limits hyperspectral camera production scalability.
For Market Incumbents: Hedge against software-recurring revenue erosion by deepening backward integration into photodiode fabrication or securing long-term offtake agreements with Japanese specialty semiconductor fabs. Reinforce differentiation through continuous cloud-delivered model updates that compress competitor catch-up cycles, while monitoring third-party maintenance provider consolidation as a channel control threat. For New Entrants and Emerging Players: Enter via modular retrofit kits for legacy conveyor lines in logistics hubs, where barcode-scanning integration with warehouse management systems sustains replacement demand without requiring full-platform development. Target India's PLI scheme incentives for domestic optical sorter assembly, leveraging import-substitution pathways for European and Japanese component suppliers as the most penetrable geography. For Investors and Strategic Acquirers: Exit pathways concentrate in AI-software specialists with cloud-delivered neural network architectures, as neural-network-based detection architectures compress replacement cycles and sustain recurring revenue streams. Long-term viability favors vendors with hybrid hardware-software positioning over pure-play mechanical fabricators. Watch hyperspectral calibration expertise scarcity as an inflection indicator for service margin expansion opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive InGaAs photodiode supply insulates TOMRA and Bühler against Japanese fab lead time volatility. |
| AI-Platform Subscription Launch | Cloud-delivered neural network updates transform Steinert and Sesotec from hardware vendors to recurring revenue operators. |
| Geographic Expansion into India PLI Corridors | Maharashtra and Gujarat assembly investments open import-substitution pathways for European component suppliers. |
| Dual-Sensor Fusion Product Development | Converged X-ray and optical detection creates premium pricing tiers in poultry and prepared meal segments. |
| Third-Party Service Provider Partnership | Independent technical firm alliances address California Central Valley procurement unbundling trends. |
Study Parameters
Trade publications, customs records, and SEC filings formed the secondary backbone, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and recycling cooperative technical directors. Bottom-up equipment shipment tracking and top-down waste processing capacity modeling were triangulated against regulatory mandate timelines from the EU Green Deal, FDA modernization standards, and India's PLI scheme documentation.
Historical trendline analysis of optical sorter deployment rates across food processing and recycling verticals established baseline growth patterns, with segmentation modeling across product type, detection technology, end-user industry, and application material stream. CAGRs were derived from installed base replacement cycles and greenfield capacity addition trajectories, incorporating EU ETS carbon pricing pass-through effects and extended producer responsibility fee structures as demand-side forecast inputs.
Revisions become necessary when InGaAs photodiode fab capacity expansion timelines, EU REACH substance restriction amendments, or FDA foreign-object detection threshold adjustments materialize outside baseline assumptions. Deviation in Japanese or German semiconductor export policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Global Lifting Columns Market