
 Brazil Metal Fabrication Equipment Market | 2026-2036
Brazil Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Metal Fabrication Equipment Market Analysis
Brazil is reconfiguring its metalworking capacity as domestic infrastructure programs and reshoring initiatives expand local demand for fabrication machinery. Trumpf GmbH leverages its laser technology leadership to anchor premium positioning among precision engineering buyers. BMA Brazil competes through deep channel control across the country's interior manufacturing zones. DMG Mori sustains its reputation for CNC reliability among automotive OEMs investing in flexible production lines.
Metal fabrication equipment encompasses machinery that cuts, bends, welds, or machines metallic workpieces, typically operating at tolerances from 0.01 mm for CNC systems to 2 mm for structural plasma cutting. These systems transform raw steel, aluminum, and alloy stock into finished components for assembly across heavy industry. CNC Machines dominate capital allocation among Brazilian buyers seeking multi-axis flexibility for batch production. Robotic Welding represents the fastest-growing technology segment as labor costs rise and repeatability standards tighten in automotive and shipbuilding applications. Structural Fabrication occupies the largest application share, driven by federal infrastructure contracts and commercial construction momentum.
ANVISA oversees workplace safety certifications that affect equipment import approvals and domestic manufacturing compliance. The Brazilian central bank's industrial credit programs shape machinery acquisition timelines for mid-tier fabricators. ABNT technical standards align with ISO welding qualifications to determine market access for foreign equipment suppliers. Stakeholders must monitor how proposed changes to local content rules in government procurement reshape competitive dynamics between imported and domestically assembled machinery lines.
Market Dynamics
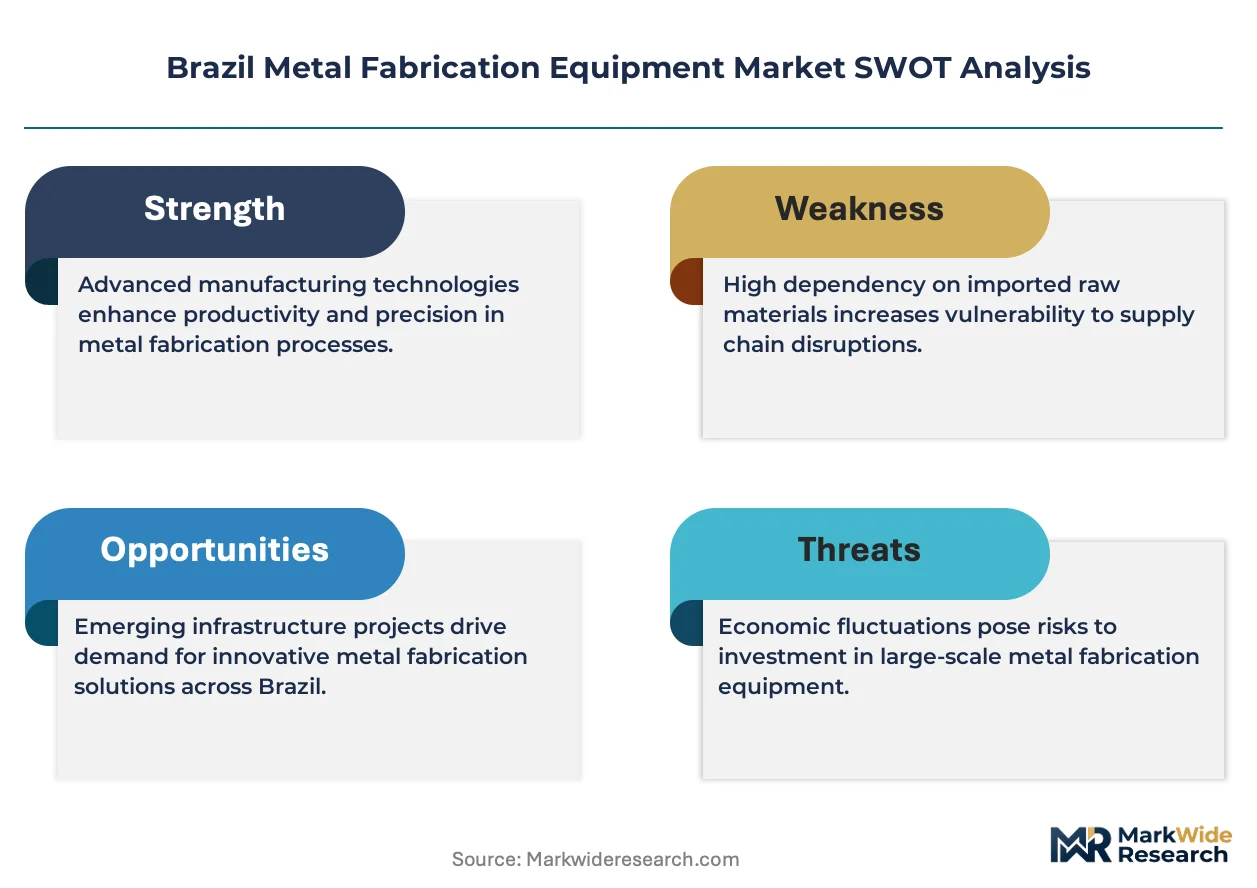
ANVISA's workplace safety certification requirements are restructuring import approval timelines, forcing foreign equipment suppliers to establish domestic assembly partnerships or risk exclusion from federal infrastructure tenders.
Growth Catalysts
- Federal infrastructure contracts:PAC and other federal programs mandate domestic steel fabrication for bridges, ports, and energy transmission corridors. Equipment demand concentrates in São Paulo state's industrial corridor.
- Automotive local content rules:OEMs are expanding captive metalworking capacity to meet industrial policy thresholds. Flexible CNC systems attract capital allocation for batch production of chassis and powertrain components.
- Robotic welding adoption:Labor cost escalation in shipbuilding and heavy truck assembly is accelerating repeatability investments. Shipyards in Rio de Janeiro state deploy automated seam tracking for hull construction.
Market Restraints
- Steel price volatility:Input cost swings compress fabricator margins and defer machinery replacement cycles. Mid-tier workshops in Minas Gerais delay laser cutting upgrades when coil prices spike.
- Import dependency for precision components:Linear drives and motion controllers concentrate among German and Japanese suppliers. Foreign exchange exposure extends delivery timelines for high-accuracy systems.
- ABNT-ISO welding qualification gaps:Certification mismatches between Brazilian and international standards create friction for multinational contractors. Equipment validation costs rise for imported robotic welding cells.
Strategic Opportunities
- Northeast industrialization:Pernambuco and Bahia manufacturing zones remain underpenetrated for advanced fabrication machinery. Port complexes at Suape and Pecém attract shipyard and wind tower fabricators seeking localized supply.
- Hybrid laser-arc welding convergence:Combined heat source technologies reduce distortion in thick-plate applications. Offshore platform builders in Espírito Santo evaluate these systems for jacket fabrication.
- Central bank industrial credit lines:FINAME and BNDES programs reduce effective interest rates for machinery acquisition. Mid-tier fabricators in Paraná leverage these instruments for CNC press brake investments.
Industry Challenges
- CNC programming and maintenance talent scarcity:Technical institutes in interior states produce insufficient operators for multi-axis systems. Fabricators in Goiás and Mato Grosso compete for limited technician pools.
- Legacy mechanical press integration:Pneumatic and hydraulic systems from prior decades resist connectivity with modern MES platforms. Retrofit costs deter full digitalization in family-owned workshops.
- ANVISA certification timeline compression:Safety approval backlogs extend equipment commissioning by four to eight months. Importers face working capital strain during regulatory review periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Metal Fabrication Equipment Market |
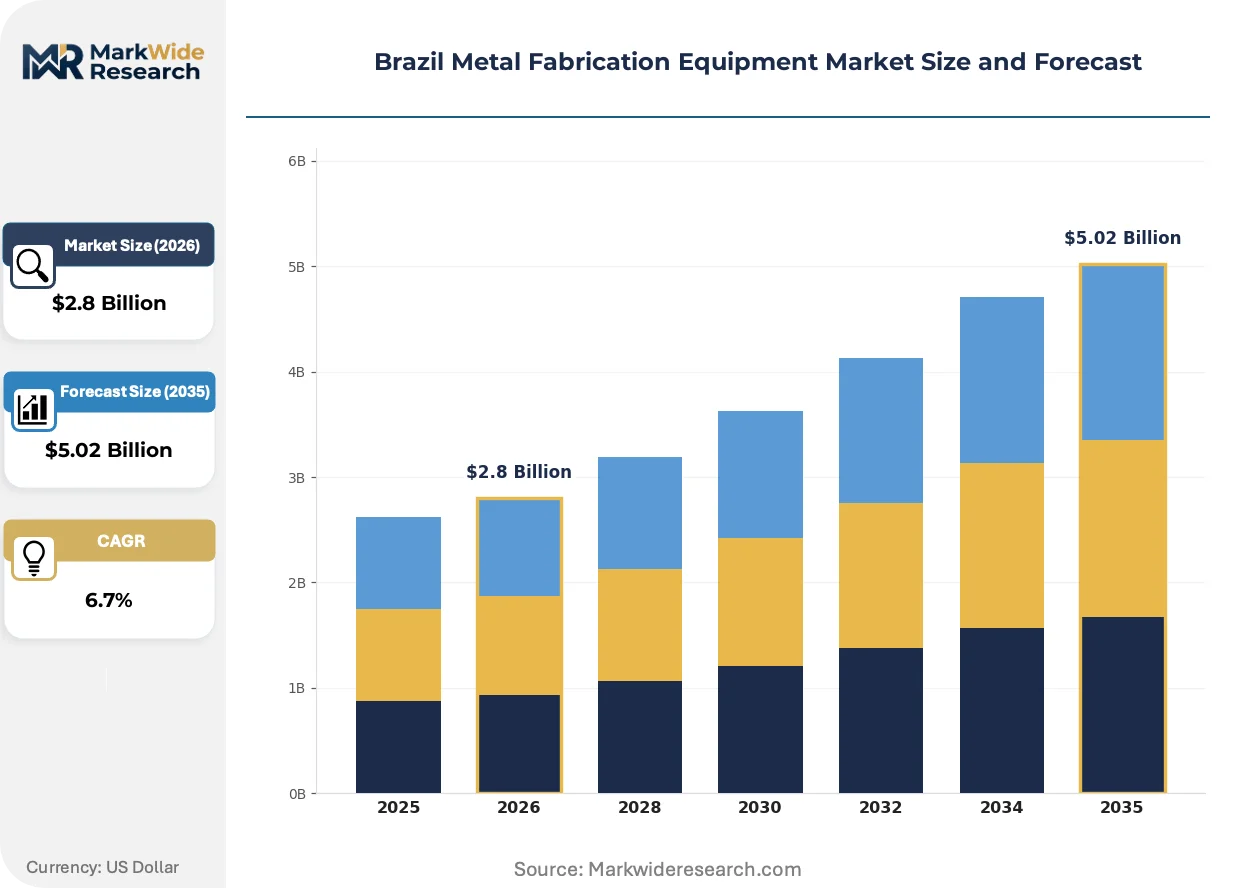
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welding Machines, CNC Machines, Bending Machines, Plasma Cutters End User: Aerospace, Automotive OEMs, Construction, Shipbuilding Technology: Laser Cutting, Waterjet Cutting, Robotic Welding, Manual Welding Application: Structural Fabrication, Sheet Metal Work, Precision Engineering, Metal Repair |
| Companies Covered | BMA Brazil, Colfax Corporation, DMG Mori, Amada Co., Ltd., Shenyang Machine Tool, Hurco Companies, Inc., Kennametal Inc., MAG Giddings & Lewis, Trumpf GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Metal Fabrication Equipment Market Emerging Trajectories
Digital thread integration and energy-efficient process technologies are restructuring how Brazilian fabricators justify capital expenditure. Equipment vendors now compete on operational data transparency rather than throughput specifications alone.
Fiber laser cutting is collapsing the productivity gap between thin-sheet job shops and heavy-plate specialists. Automotive stampers in São Bernardo do Campo deploy 12-kilowatt systems for aluminum body panel nesting. The technology is collapsing batch size economics, enabling profitable runs below fifty pieces.
ANVISA's alignment with ISO 13849 safety integrity standards is mandating redundant control architectures for robotic cells. Welding equipment suppliers must recertify controller firmware for Brazilian market access. Automotive OEMs in São José dos Campos accelerate compliance investments ahead of anticipated enforcement tightening.
Service unbundling is separating hardware procurement from maintenance contracts and consumables supply. Independent technical service networks in Campinas and Curitiba challenge manufacturer-captive service organizations. Chemical processing and pulp mill fabricators in the interior states increasingly source spare parts through regional distributors rather than direct OEM channels.
Brazil Metal Fabrication Equipment Market Segmentation
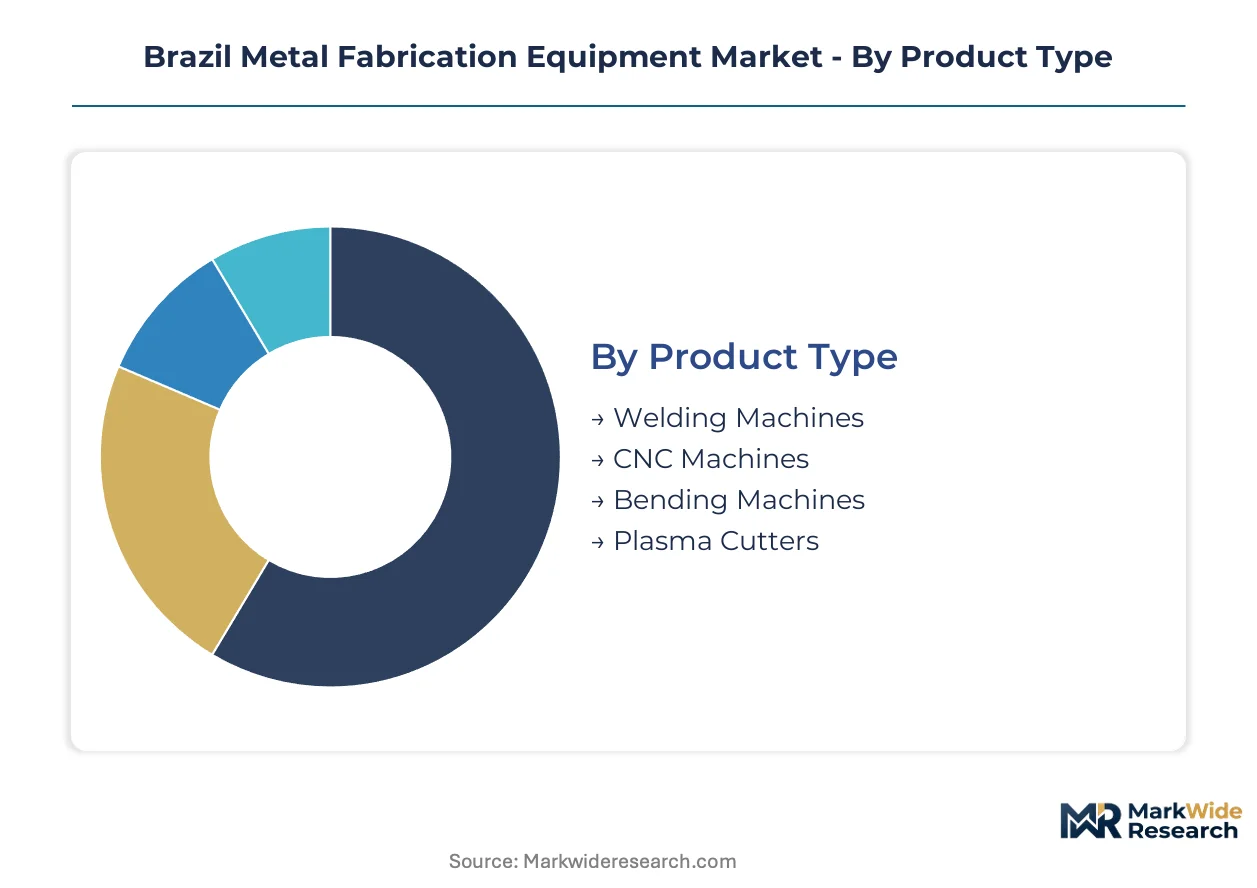
Segmentation in Brazilian metal fabrication equipment reveals how capital flows concentrate across technology maturity levels and application intensities. Distinct buyer profiles emerge between precision-driven automotive OEMs and volume-focused infrastructure contractors.
Product Type:
Mature mechanical systems anchor installed base volumes while digitally integrated platforms reshape procurement priorities among southeastern manufacturers.
- CNC Machines:Multi-axis systems deliver 0.01 mm positioning repeatability through synchronized servo drives and real-time thermal compensation. São Paulo state automotive suppliers prioritize these systems for flexible chassis component batches under local content mandates. Capital allocation favors five-axis configurations that reduce fixture changeover downtime.
- Welding Machines:Arc and resistance welding platforms span manual through fully automated configurations with seam tracking integration. Shipyards in Rio de Janeiro state deploy submerged arc systems for thick-plate hull sections where penetration consistency outweighs speed metrics. Power source inverter technology is displacing transformer-based units in new installations.
- Bending Machines:CNC press brakes and roll formers process coil stock into structural profiles with programmable backgauge positioning.
- Plasma Cutters:High-definition plasma systems pierce carbon steel up to 50 mm with dross-free edge quality for structural steel service centers.
CNC Machines retain volume leadership; Robotic Welding holds the steepest expansion curve as labor costs escalate in heavy assembly.
End User:
Application intensity varies sharply between regulated export sectors and domestically focused construction demand.
- Automotive OEMs:Tier-one suppliers and final assemblers operate captive metalworking cells for chassis, powertrain, and body-in-white fabrication. ABC Paulista manufacturers invest in fiber laser blanking and servo press lines to meet industrial policy local content thresholds. Flexible manufacturing systems accommodate model mix volatility in the Brazilian market.
- Construction:Structural steel fabricators and rebar processors supply federal infrastructure contracts including bridge and transmission tower frameworks. Minas Gerais and São Paulo workshops dominate bidding for PAC program steel packages. Beam drilling and coping machinery demand tracks civil engineering award cycles.
- Shipbuilding:Rio de Janeiro and Pernambuco yard complexes assemble offshore platforms and merchant vessels with thick-plate cutting and panel line automation.
- Aerospace:Embraer suppliers and maintenance facilities deploy precision machining and titanium welding for airframe and engine component fabrication.
Construction retains volume leadership; Automotive OEMs hold the steepest expansion curve as reshoring accelerates captive capacity investments.
Technology:
Process selection hinges on material thickness, edge quality requirements, and automation integration depth.
- Laser Cutting:Fiber laser systems from 6 kW through 12 kW collapse batch economics for aluminum and mild steel processing. São Bernardo do Campo automotive stampers deploy these for aluminum body panel nesting with nitrogen assist gas. Solid-state resonator technology reduces maintenance intervals versus CO2 laser platforms.
- Robotic Welding:Six-axis articulated arms with through-arm torch cabling execute seam tracking in shipbuilding and heavy truck assembly. ANVISA safety integrity mandates are accelerating controller recertification investments ahead of enforcement tightening. Collaborative welding cobots penetrate mid-tier job shops with reduced fencing requirements.
- Waterjet Cutting:Abrasive and pure waterjet systems process heat-sensitive alloys and composites without thermal distortion.
- Manual Welding:Stick and MIG processes persist in field construction and repair applications where portability outweighs repeatability.
Laser Cutting retains volume leadership; Robotic Welding holds the steepest expansion curve as repeatability standards tighten.
Application:
Structural demands dominate capital deployment while precision segments command premium pricing.
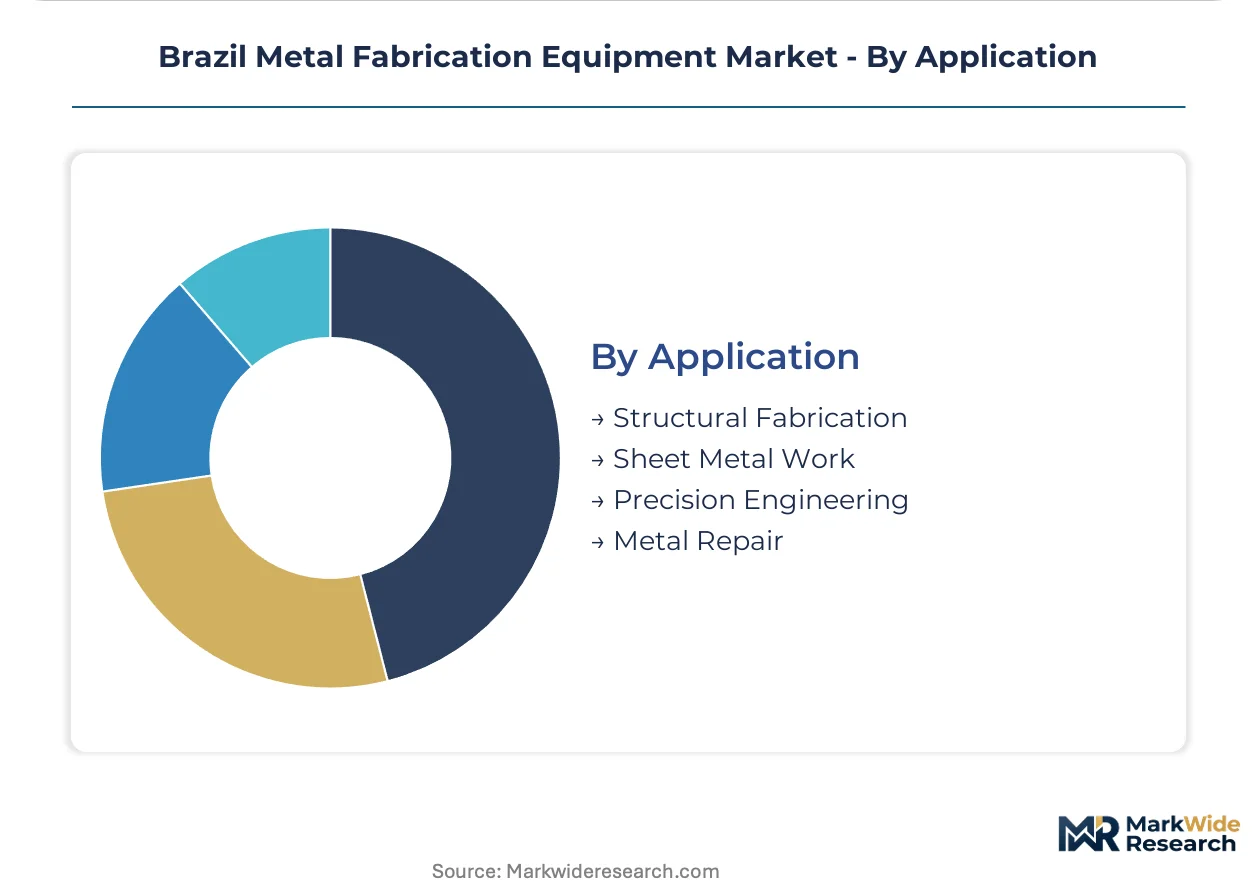
- Structural Fabrication:Heavy plate cutting, beam processing, and welded assembly for infrastructure and building frameworks constitute the largest equipment demand category. Federal energy transmission and port expansion contracts flow through São Paulo and Rio de Janeiro state fabricators. Multi-torch oxyfuel and plasma beveling systems dominate this segment.
- Sheet Metal Work:Thin-gauge forming, punching, and laser cutting serve HVAC ducting, electrical enclosures, and appliance manufacturing. Campinas and Curitiba industrial clusters concentrate job shop capacity for batch production below five hundred units. Nesting software integration determines material yield competitiveness.
- Precision Engineering:Tight-tolerance machining and welding for aerospace, medical, and instrumentation applications.
- Metal Repair:Cladding, remanufacturing, and field welding services for mining equipment and offshore infrastructure.
Structural Fabrication retains volume leadership; Precision Engineering holds the steepest expansion curve as aerospace supplier tiers deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment demand concentrates in Brazil's southeastern industrial corridor, where machinery clusters serve automotive OEMs and federal infrastructure contractors. State-level industrial policies and ANVISA certification requirements reshape competitive dynamics across sub-regional manufacturing belts.
São Paulo
ABC Paulista automotive suppliers deploy fiber laser blanking and servo press lines to meet local content thresholds under federal industrial policy. BNDES credit programs accelerate CNC machinery acquisition timelines for tier-one chassis fabricators. São Bernardo do Campo and São José dos Campos anchor precision metalworking capacity for flexible batch production.
Minas Gerais
Structural steel workshops dominate bidding for PAC program bridge and transmission tower contracts across the state. Steel price volatility compresses fabricator margins and defers laser cutting upgrades when coil costs spike. Belo Horizonte industrial clusters concentrate beam drilling and coping machinery demand tied to civil engineering award cycles.
Rio de Janeiro
Shipyards in the state deploy submerged arc welding systems and automated seam tracking for thick-plate hull construction. ANVISA safety certification backlogs extend equipment commissioning timelines by four to eight months. Niterói and Itaguaí port complexes attract offshore platform builders evaluating hybrid laser-arc welding for jacket fabrication.
Rio Grande do Sul
Metalworking machinery distributors in the state leverage central bank FINAME credit lines to reduce effective interest rates for mid-tier fabricators. Legacy mechanical press integration challenges resist connectivity with modern MES platforms in family-owned workshops. Porto Alegre industrial zones concentrate job shop capacity for batch production below five hundred units.
Bahia
The northeastern manufacturing zone remains underpenetrated for advanced fabrication machinery despite port complex expansion at Aratu. Wind tower fabricators evaluate localized supply options as federal infrastructure programs extend into the region. Camaçari industrial park attracts shipyard suppliers seeking proximity to Atlantic offshore development corridors.
Brazil Metal Fabrication Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The Brazilian market structures around three distinct competitive layers: premium technology vendors with direct OEM relationships, mid-market distributors with deep interior channel control, and regional service networks unbundling maintenance from hardware procurement. Strategic moves concentrate on domestic assembly partnerships to circumvent ANVISA import approval bottlenecks, and service network expansion to challenge manufacturer-captive technical organizations.
Within the premium technology tier, Trumpf GmbH and DMG Mori exemplify positioning anchored in precision engineering credibility. BMA Brazil occupies a distinct archetype as a channel-controlled domestic specialist with interior manufacturing zone penetration. Amada Co., Ltd. and Shenyang Machine Tool represent the scale-driven mid-market segment where pricing competitiveness and regional distributor density determine contract outcomes.
| Leading Market Players |
|---|
| BMA Brazil |
| Colfax Corporation |
| DMG Mori |
| Amada Co., Ltd. |
| Shenyang Machine Tool |
| Hurco Companies, Inc. |
| Kennametal Inc. |
| MAG Giddings & Lewis |
| Trumpf GmbH |
| Others |
Supply Flow & Price Mechanics
The Santos-Guarulhos freight corridor anchors equipment distribution cost dynamics across Brazil's southeastern manufacturing belt. Rising container rates from European and Asian origin ports concentrate pricing power among domestic assembly partnerships that circumvent ANVISA import approval bottlenecks. This logistics structure feeds downstream price differentiation between federally certified premium systems and uncertified economy-tier alternatives.
Pricing Analysis
ANVISA certification tiers dictate the pricing stratification across premium, standard, and economy levels in Brazilian metal fabrication equipment. Equipment validation costs and local content compliance separate premium CNC systems from standard mechanical presses and economy-grade manual welding platforms. Pricing pressure stems from BNDES credit program interest rate adjustments that compress margins for mid-tier distributors serving Paraná and Goiás fabricators. Automotive OEMs in São Paulo state exhibit lowest price sensitivity due to local content mandate penalties, while family-owned job shops in Rio Grande do Sul face acute cost compression.
Supply Chain Analysis
Extended payment terms from German and Japanese linear drive suppliers now stretch to 180 days for Brazilian distributors facing foreign exchange exposure. Precision motion controllers and servo motors draw from concentrated supply bases in Germany, Japan, and South Korea. Single-source vulnerability concentrates in high-accuracy linear encoder imports subject to euro-real volatility. Distribution runs through São Paulo-based machinery clusters that serve interior manufacturing zones via Campinas and Curitiba technical service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's metal fabrication equipment sector sits in early-cycle expansion as federal infrastructure programs and automotive reshoring accelerate capital deployment ahead of prior replacement cycles.
For Market Incumbents: Harden domestic assembly partnerships to neutralize ANVISA certification timeline risks that exclude pure importers from PAC program tenders. Deepen channel control through captive technical service networks in Minas Gerais and Goiás to defend against independent distributors unbundling maintenance contracts. Prioritize controller firmware recertification investments ahead of anticipated ISO 13849 enforcement tightening. For New Entrants and Emerging Players: Northeast manufacturing zones in Pernambuco and Bahia present underpenetrated demand for robotic welding systems serving wind tower and shipyard fabricators. Hybrid laser-arc welding technologies offer technical differentiation against established arc welding incumbents in Espírito Santo offshore construction. Leverage FINAME credit line partnerships to reduce effective acquisition costs for first-time CNC buyers in Camaçari industrial park. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core metalworking machinery divisions amid balance sheet restructuring. Five-to-ten year viability hinges on exposure to federal infrastructure contract pipelines rather than cyclical automotive capital expenditure. Monitor BNDES credit allocation shifts as early signals of equipment demand inflection across mid-tier fabricator segments.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | ANVISA certification timelines compress by four to eight months for locally assembled robotic welding cells. |
| Service Network Unbundling | Independent technical organizations in Campinas challenge manufacturer-captive maintenance contract structures. |
| Hybrid Laser-Arc Welding Deployment | Offshore platform builders in Espírito Santo evaluate reduced distortion for thick-plate jacket fabrication. |
| FINAME Credit Line Integration | Mid-tier fabricators in Paraná leverage central bank programs for CNC press brake acquisitions. |
| Northeast Channel Expansion | Port complexes at Suape and Pecém attract shipyard suppliers seeking proximity to Atlantic offshore corridors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of BNDES credit disbursement records, ANVISA certification databases, ABNT technical standards filings, and customs import manifests. Interviews with maintenance directors at automotive tier-one suppliers, plant engineers at structural steel fabricators, aftermarket service heads at machinery distributors, and OEM procurement teams informed demand-side validation. Bottom-up equipment shipment tallies triangulate against top-down federal infrastructure contract value allocations.
Forecast inputs incorporate CNC machine tool adoption rates, robotic welding penetration curves, and laser cutting technology substitution patterns across the projection horizon. Segmentation modeling spans product type, end-user industry, technology maturity, and application intensity dimensions. CAGRs derive from equipment replacement cycle analysis and capital expenditure elasticity to BNDES interest rate movements. Steel price volatility indices and foreign exchange exposure metrics inform scenario-weighted outputs.
Practitioners should monitor ANVISA regulatory enforcement calendars, central bank industrial credit policy shifts, and federal infrastructure program award cycles for early signals of demand trajectory revision. Macroeconomic deviation in steel input costs, regulatory changes to local content thresholds, or technological disruption in fiber laser economics would prompt forecast reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Tower Crane Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Case Erectors Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Construction Pump Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Mortar Testing Equipment Market