
 Mill Pulverizer Market | 2026-2036
Mill Pulverizer Market Size, Share, and Industry Trends Forecast 2026-2036
Mill Pulverizer Market Foresight
Buyer concentration among multinational cement producers is recalibrating procurement volumes across the mill pulverizer supply base. Hosokawa Micron leverages its micron-scale classification expertise to serve pharmaceutical powder specifications. Babcock & Wilcox anchors its position through utility-scale coal pulverization systems with integrated emissions controls. Metso Outotec competes in mineral processing circuits where throughput reliability determines contract awards.
A mill pulverizer is a size-reduction machine that employs rotating hammers, balls, or discs to fracture feedstock into controlled particle distributions, typically operating at rotor speeds between 1,800 and 3,600 RPM depending on material friability. Its primary purpose is to prepare raw materials for combustion, chemical reaction, or downstream formulation by achieving specified fineness with minimal energy expenditure. Hammer mill configurations dominate cement and coal applications where abrasive wear tolerance outweighs precision requirements, while cryogenic systems command premium positioning in food processing and pharmaceuticals where heat-sensitive compounds require sub-zero grinding temperatures. Ball mill technology retains mature share in mineral processing but faces displacement where pneumatic conveying integration reduces footprint and maintenance intervals.
The US EPA enforces Maximum Achievable Control Technology standards that compel pulverizer upgrades in coal-fired power generation, while China's MEE implements dual carbon goals that accelerate electric drive retrofits across heavy industry. REACH compliance in Europe restricts certain alloy compositions in grinding media, redirecting sourcing toward certified suppliers. Stakeholders must weigh regulatory compliance timelines against equipment replacement cycles to avoid stranded mechanical assets.
Market Dynamics
China's MEE is tightening GB dust emission standards while Southeast Asian cement manufacturers accelerate capacity additions, compressing procurement timelines and forcing pulverizer suppliers to integrate electric drive retrofits into legacy mechanical systems.
Growth Catalysts
- Indonesia's clinker grinding corridor:Domestic cement producers are expanding grinding capacity to serve regional infrastructure projects, pulling in hammer mill pulverizers rated for abrasive limestone feedstock.
- EPA Maximum Achievable Control Technology:US coal-fired utilities face mandated pulverizer upgrades to meet particulate emission thresholds, sustaining replacement demand for integrated emissions control systems.
- Cryogenic grinding technology:Pharmaceutical formulators in Japan and South Korea are adopting sub-zero pulverization to process heat-sensitive APIs without thermal degradation.
Market Restraints
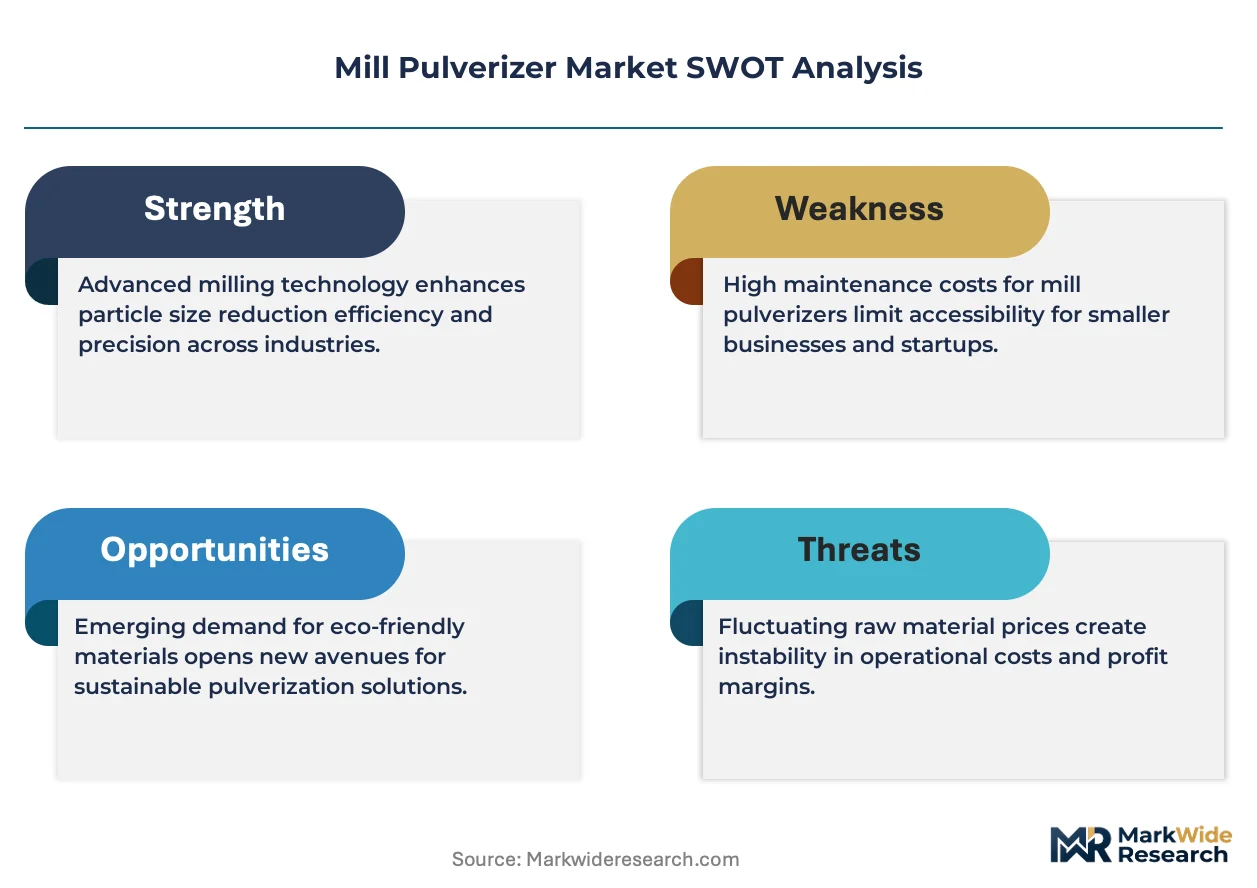
- Chromium alloy sourcing concentration:REACH compliance restricts certain grinding media compositions in Europe, forcing buyers toward certified South African and Turkish suppliers with limited spot availability.
- Rotor wear part replacement cycles:Hammer mills processing high-silica cement raw materials require disc and liner replacements every 2,000-4,000 operating hours, elevating total cost of ownership.
- Pneumatic conveying substitution:Integrated grinding-classification systems with inline pneumatic transport are displacing standalone ball mills in mineral processing circuits, eroding installed base stickiness.
Strategic Opportunities
- Vietnam's limestone-rich north:Underpenetrated domestic pulverizer manufacturing capacity creates openings for foreign suppliers to localize assembly and reduce import duty exposure.
- Dual carbon retrofit mandates:China's MEE incentives for electric drive conversion in heavy industry are creating bundled upgrade contracts combining pulverizer mechanical overhaul with motor replacement.
- Digital predictive maintenance convergence:Vibration monitoring systems married to cloud analytics platforms enable remote rotor balancing and wear forecasting, opening recurring revenue streams.
Industry Challenges
- Cross-functional commissioning expertise:Integrated pulverizer-emissions control systems require technicians fluent in both mechanical alignment and continuous emissions monitoring calibration, a skill combination concentrated among aging specialist workforces.
- Legacy DCS integration friction:Modern variable-frequency drive pulverizers must interface with 1990s-era distributed control systems common in US Midwest coal plants, extending commissioning timelines and requiring custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mill Pulverizer Market |
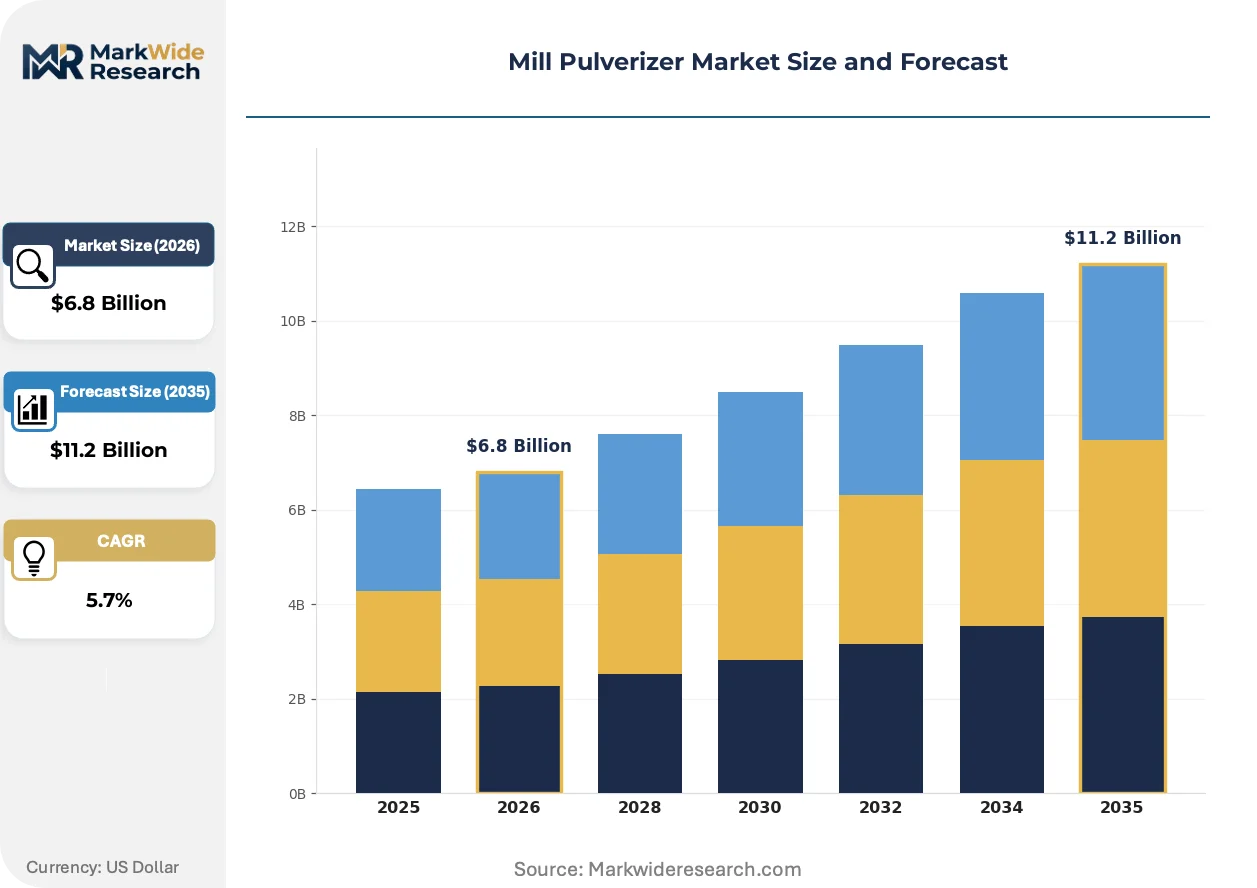
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic, Hammer Mill, Ball Mill, Disc Mill End User: Food Processing, Pharmaceuticals, Chemical Manufacturing, Mineral Processing Technology: Mechanical, Electric, Pneumatic, Hydraulic Application: Grinding, Mixing, Homogenizing, Powder Coating |
| Companies Covered | Williams Patent Crusher & Pulverizer Co., Hosokawa Micron, Babcock & Wilcox, American Pulverizer Company, Mitsubishi Heavy Industries, Bradley Pulverizer Company, DP Pulveriser Industries, Metso Outotec, Rockland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mill Pulverizer Market Shifts & Advancements
Material science advances in grinding media and real-time process analytics are compressing maintenance intervals while expanding the addressable particle size range, reshaping how end-users evaluate total cost of ownership.
Ceramic-matrix composite grinding discs are absorbing impact loads from high-silica feedstock while maintaining dimensional stability across temperature swings. Cement producers in Indonesia and Vietnam are retrofitting these into existing hammer mill housings to extend wear part life. The technology is absorbing maintenance budget allocations that previously flowed to chromium alloy replacements, compressing supplier margins on consumables.
China's GB 31573-2015 particulate emission standard revisions are compelling cement plants to specify baghouse-integrated pulverizer discharge designs. Equipment vendors must now engineer sealed transfer chutes and negative-pressure mill housings as standard rather than optional features. Southeast Asian export-oriented manufacturers are adopting these specifications preemptively to maintain access to Chinese EPC contractor procurement lists.
Buyer consolidation among multinational cement producers is consolidating specification authority at regional engineering centers. Procurement decisions that previously devolved to plant-level maintenance managers now route through centralized technical committees in Singapore and Dubai. Indian and Chinese pulverizer suppliers are responding by establishing local application engineering offices to maintain technical dialogue with these concentrated decision nodes.
Mill Pulverizer Market Segmentation
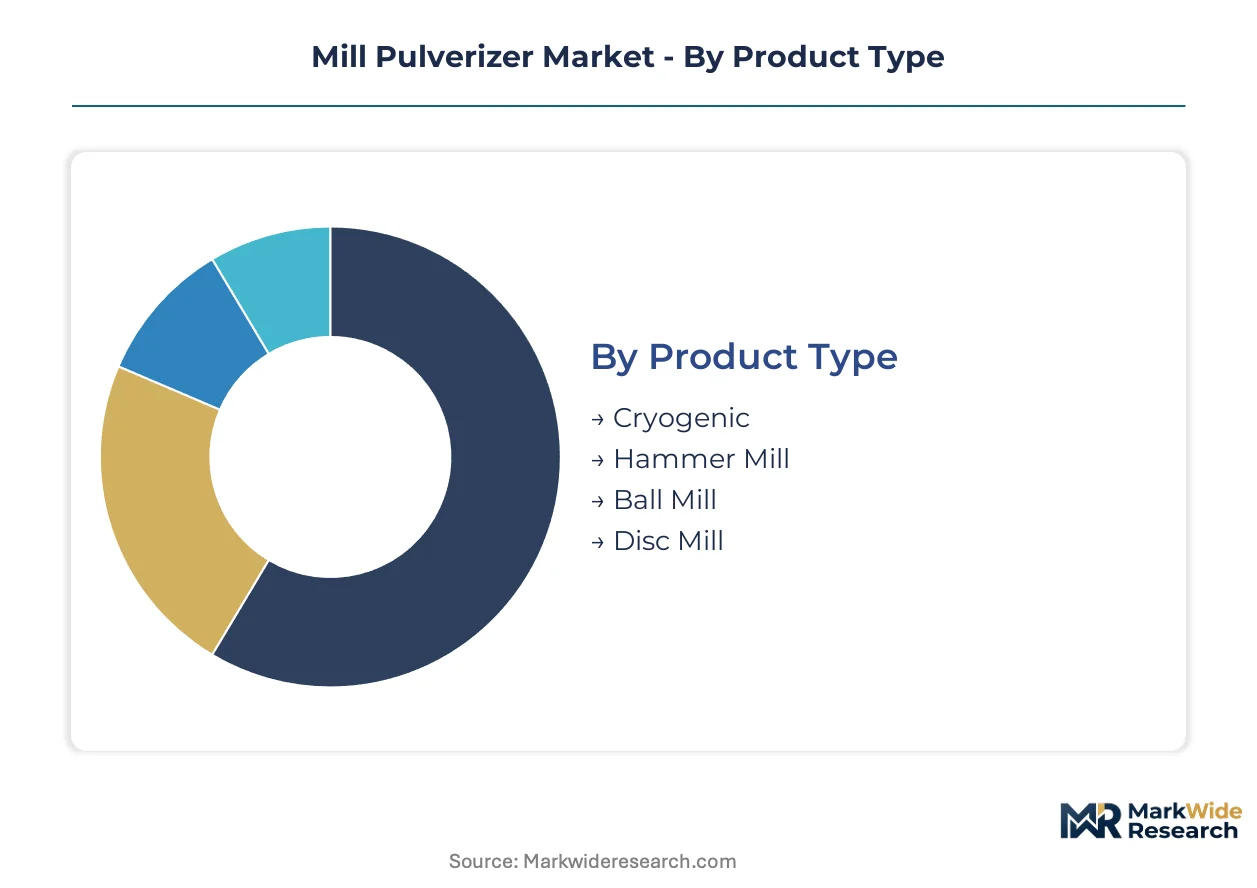
Mill pulverizer procurement patterns diverge sharply between high-volume commodity applications and precision-driven premium segments. Equipment specifications, maintenance intervals, and supplier relationships vary fundamentally across these divides, requiring vendors to maintain distinct product architectures and service models.
Product Type:
Hammer mills dominate volume shipments while cryogenic systems command premium positioning through specialized thermal engineering.
- Hammer Mill:Rotating hammers fracture abrasive feedstock at 1,800-3,600 RPM. Indonesia's clinker grinding corridor pulls heavy shipments for limestone processing, though high-silica abrasion forces disc replacements every 2,000-4,000 hours.
- Cryogenic:Liquid nitrogen injection maintains sub-zero temperatures for heat-sensitive compounds. Pharmaceutical formulators in Japan and South Korea specify these systems for API processing where thermal degradation risks batch integrity.
- Ball Mill:Mature mineral processing technology retains installed base in legacy circuits. Pneumatic conveying integration is eroding standalone deployments.
- Disc Mill:Ceramic-matrix composite discs are extending wear life in high-silica cement applications. Southeast Asian retrofit demand is absorbing maintenance budgets previously allocated to chromium alloy replacements.
Mature deployment sits with Ball Mill. Newer deployment is concentrated in Cryogenic.
End User:
Pharmaceutical and food processing specifications diverge from mineral processing through contamination control and thermal sensitivity requirements.
- Mineral Processing:Throughput reliability determines contract awards in copper and gold circuits. Metso Outotec competes on mean-time-between-failures metrics in Chilean and Australian concentrator projects.
- Pharmaceuticals:Hosokawa Micron leverages micron-scale classification expertise to serve powder specifications. REACH compliance redirects grinding media sourcing toward certified South African and Turkish suppliers with constrained spot availability.
- Food Processing:Cryogenic configurations process spices and flavor compounds without volatile oil loss. Japanese and South Korean adoption is climbing the fastest among food safety-conscious manufacturers.
- Chemical Manufacturing:Integrated emissions control systems satisfy EPA Maximum Achievable Control Technology standards. US coal-fired utilities face mandated pulverizer upgrades to meet particulate thresholds.
Procurement authority concentrates in Chemical Manufacturing through multinational engineering centers. Specification complexity expands most quickly in Pharmaceuticals.
Technology:
Electric drive retrofits are displacing mechanical systems under China's dual carbon mandates, while pneumatic integration reduces footprint in new installations.
- Mechanical:Legacy coal pulverization systems anchor Babcock & Wilcox's utility-scale position. Aging distributed control systems in US Midwest plants require custom protocol gateways for integration.
- Electric:China's MEE incentives create bundled upgrade contracts combining mechanical overhaul with motor replacement. Variable-frequency drives interface with 1990s-era DCS through extended commissioning timelines.
- Pneumatic:Inline grinding-classification systems with pneumatic transport displace standalone ball mills. Footprint reduction and maintenance interval compression drive mineral processing adoption.
- Hydraulic:High-torque applications in dense mineral feedstock retain niche deployment. Energy efficiency disadvantages limit expansion beyond specialized comminution circuits.
Installed base stickiness remains strongest in Mechanical. Conversion momentum clusters in Electric.
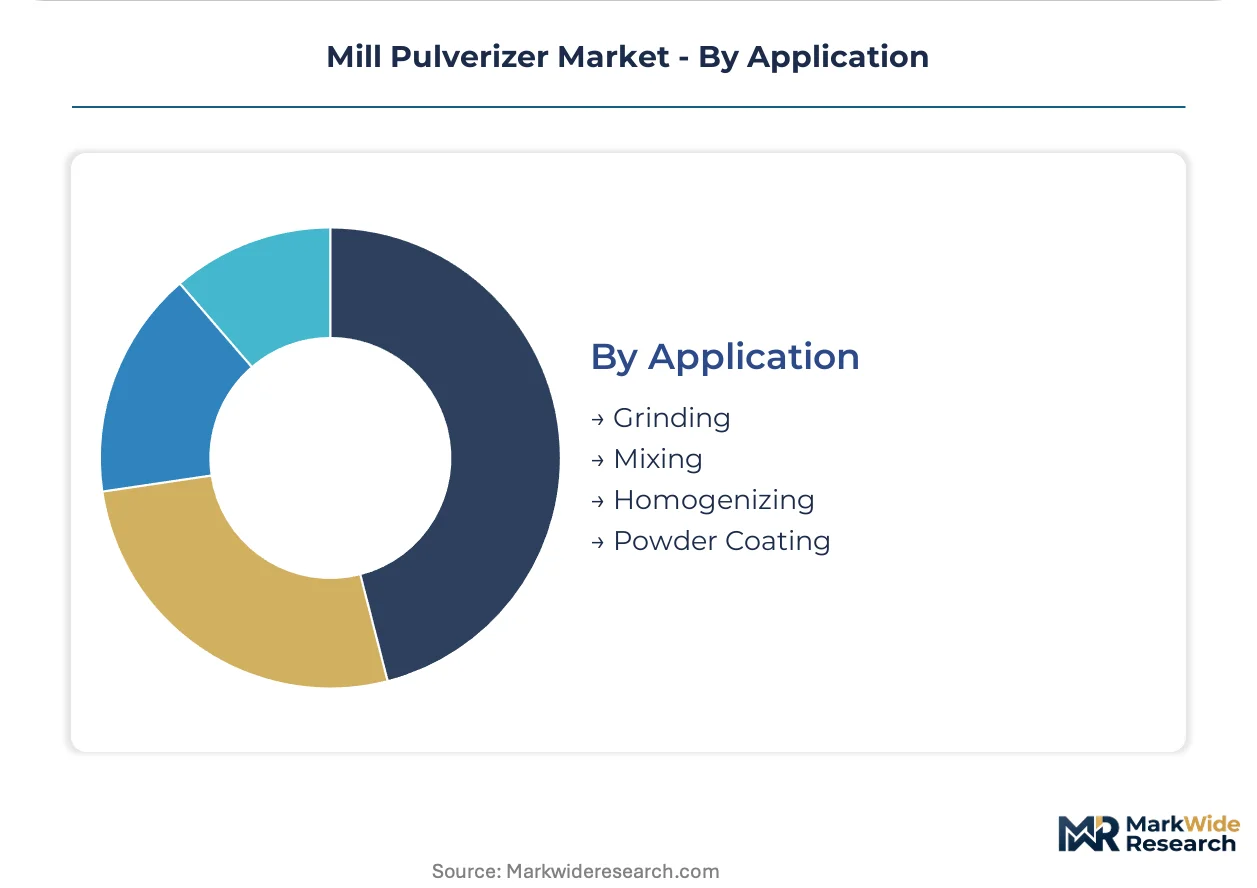
Application:
Grinding applications absorb the majority of capital allocation while powder coating specifications demand precise particle distribution control.
- Grinding:Cement raw material preparation and coal pulverization constitute core demand. China's GB 31573-2015 particulate standards compel baghouse-integrated discharge designs as standard features.
- Powder Coating:Controlled particle distribution ensures uniform film thickness in automotive and appliance finishes. Electrostatic application requirements specify tight micron ranges.
- Mixing:Multi-component feedstock homogenization serves chemical manufacturing batch consistency. Integrated pulverizer-mixer systems reduce transfer losses.
- Homogenizing:Dairy and food applications require shear-controlled cell disruption. Thermal management distinguishes equipment specifications from abrasive mineral processing.
Revenue concentration sits with Grinding. Specification complexity is expanding most rapidly in Powder Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone deposits across Indonesia's Java belt are pulling pulverizer procurement toward Southeast Asian fabrication centers. China's GB emission standards and US EPA mandates are compressing equipment replacement cycles in divergent regulatory directions.
United States
Midwest coal-fired utilities drive pulverizer retrofit demand under EPA Maximum Achievable Control Technology enforcement. Aging distributed control systems from the 1990s require custom protocol gateways for electric drive integration. Ohio River Valley power clusters concentrate procurement authority among regional engineering contractors.
China
Cement capacity expansion along the Yangtze River Delta absorbs hammer mill shipments for clinker grinding circuits. MEE dual carbon mandates accelerate bundled contracts combining mechanical overhaul with motor replacement. Shandong Province industrial zones specify baghouse-integrated discharge designs under revised GB 31573-2015 standards.
Germany
REACH compliance redirects grinding media sourcing toward certified Turkish and South African suppliers with constrained spot availability. Ruhr industrial heritage sites host specialized technicians fluent in emissions monitoring calibration. Bavarian mineral processing equipment exporters serve Eurasian project pipelines.
Indonesia
Domestic cement producers expand grinding capacity along Java's northern coast to serve regional infrastructure projects. High-silica limestone feedstock forces disc replacements every 2,000-4,000 operating hours. Surabaya engineering offices concentrate multinational procurement decision nodes.
Japan
Pharmaceutical formulators in Osaka and Tokyo prefectures adopt cryogenic pulverization for heat-sensitive API processing. METI industrial efficiency guidelines favor sub-zero grinding systems for volatile oil retention in food applications. Nagoya manufacturing clusters supply ceramic-matrix composite disc retrofits to Southeast Asian cement plants.
Mill Pulverizer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital predictive maintenance and cryogenic specialization. The supplier base stratifies across utility-scale systems, precision pharmaceutical equipment, and mineral processing reliability contracts. Three archetypes dominate: emissions-integrated platform vendors, micron-scale classification specialists, and wear-part consumables suppliers. Competitive moves cluster on electric drive retrofit bundling and ceramic-matrix composite technology licensing.
Among precision-tier specialists, Hosokawa Micron exemplifies micron-scale classification expertise serving pharmaceutical powder specifications. Babcock & Wilcox anchors utility-scale positioning through coal pulverization systems with integrated emissions controls. Metso Outotec occupies mineral processing circuits where throughput reliability metrics determine contract awards in Chilean and Australian concentrator deployments.
| Leading Market Players |
|---|
| Williams Patent Crusher & Pulverizer Co. |
| Hosokawa Micron |
| Babcock & Wilcox |
| American Pulverizer Company |
| Mitsubishi Heavy Industries |
| Bradley Pulverizer Company |
| DP Pulveriser Industries |
| Metso Outotec |
| Rockland |
| Others |
Supply & Pricing Matrix
EPA-mandated pulverizer upgrades across US Midwest coal utilities are compressing procurement timelines and forcing suppliers to absorb expedited engineering costs, tightening margins on emissions-integrated systems while elevating pricing power for vendors with certified retrofit expertise.
Pricing Analysis
Warranty and service bundling separates premium-tier pulverizer vendors from commodity suppliers, with extended rotor-life guarantees and predictive maintenance subscriptions commanding 15-25% price premiums over bare-equipment transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth, with REACH-compliant grinding media sourcing adding cost layers in European markets. Cost compression in standard-tier hammer mills is intensifying because Indonesian cement producers are consolidating procurement through Surabaya-based engineering centers. Chemical manufacturing buyers exhibit lowest price sensitivity due to EPA compliance deadlines, while Southeast Asian cement grinding operations demonstrate highest sensitivity to total cost of ownership metrics.
Supply Chain Analysis
Regional distribution centers in Shanghai, Rotterdam, and Singapore anchor hub-and-spoke patterns for spare parts fulfillment, with ceramic-matrix composite disc inventories concentrated in Nagoya manufacturing clusters. Manufacturing draws from China, Germany, and Japan for precision-machined housings; chromium alloy grinding media sources from South Africa and Turkey under REACH constraints. Single-source vulnerability sits with liquid nitrogen cryogenic system components, where Japanese suppliers control specialized heat exchanger fabrication. Distribution runs through OEM-direct channels for utility-scale contracts and authorized distributor networks for aftermarket wear parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician scarcity for integrated emissions-pulverizer commissioning is propping equipment pricing and extending lead times for complex retrofit contracts.
For Market Incumbents: Deepen captive supply of ceramic-matrix composite grinding discs through backward integration into Japanese material science partnerships, defending against pneumatic conveying substitution in mineral processing circuits. Expand Surabaya application engineering headcount to maintain technical dialogue with centralized procurement committees at multinational cement producers. For New Entrants and Emerging Players: Enter via cryogenic pulverizer specialization for pharmaceutical API processing in South Korea, where METI efficiency guidelines favor sub-zero grinding adoption and incumbent presence remains thin. Pursue bundled electric drive retrofit contracts in Shandong Province industrial zones under China's MEE dual carbon incentives. For Investors and Strategic Acquirers: The window for entry favors digital predictive maintenance platform developers with vibration-to-cloud analytics capabilities, as recurring revenue streams from remote rotor balancing displace traditional consumables-dependent models. Watch for inflection when ceramic-matrix composite disc adoption rates in Indonesian cement plants cross threshold penetration triggering incumbent licensing deals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic-Matrix Composites | Captures maintenance budget shifts from chromium alloy replacements in Indonesian limestone processing. |
| Electric Drive Retrofit Bundling | Combines mechanical overhaul with motor replacement under China's MEE dual carbon mandates. |
| Digital Predictive Maintenance Platform | Enables remote rotor balancing and wear forecasting through cloud analytics integration. |
| Cryogenic System Specialization | Serves pharmaceutical API processing in Japan and South Korea where thermal sensitivity dictates specifications. |
| Regional Application Engineering Localization | Positions technical dialogue with Singapore and Dubai centralized procurement committees. |
Research Methodology
Multi-period observation of pulverizer procurement volumes, emissions retrofit timelines, and grinding media sourcing patterns anchored the trend analysis, supplemented by interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and EPC contractor engineering leads. Secondary validation drew from EPA enforcement databases, China's MEE policy circulars, customs trade records for grinding media alloys, and SEC filings from listed heavy equipment manufacturers. Bottom-up equipment shipment tracking and top-down cement capacity expansion models were triangulated against regional regulatory compliance deadlines.
Input-output matrices mapped pulverizer demand across product type, end-use industry, technology architecture, and regional regulatory cluster, with value projections developed over the projection horizon through installed base replacement cycle analysis and new capacity absorption rates. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated China's GB 31573-2015 revision implementation pace and REACH compliance transition timelines for grinding media specifications.
Revisions become necessary when China's MEE accelerates dual carbon retrofit mandates beyond modeled adoption curves or when ceramic-matrix composite disc manufacturing scales faster than baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Excavator Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Broaching Machine Market