
 Europe Construction Machinery Rental Market | 2026-2036
Europe Construction Machinery Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Machinery Rental Market Foresight
Stage V emission compliance is collapsing the residual value calculus for owned diesel fleets across European job sites. Ashtead Group leverages its Sunbelt network density to capture cross-border project flows, while Loxam Group anchors its position through captive maintenance services that extend equipment uptime. Boels Rental differentiates via urban depot saturation that positions it for same-day availability in Benelux construction corridors.
Europe construction machinery rental denotes the commercial provision of mobile equipment including excavators with operating weights from 1 to 90 tonnes, all-terrain cranes reaching 300-tonne lift capacity, and telematics-integrated forklifts for temporary use without capital transfer of ownership. The model serves commercial contractors seeking balance-sheet flexibility and compliance risk transfer. Excavators generate the deepest rental revenue pools given their ubiquity across construction projects and roadworks, while short-term rental structures command premium daily rates during peak seasonality. Infrastructure developers increasingly specify lease-to-own arrangements for long-dated civil works, shifting margin capture from pure rental yield toward residual value participation.
EU Green Deal targets and Stage V emission standards enforced by national regulators reshape fleet procurement toward electric and hybrid alternatives, compressing diesel asset lifecycles. ECHA REACH restrictions on hydraulic fluids and noise ordinances from municipal authorities further constrain equipment specification. Stakeholders must monitor battery swap infrastructure rollout and carbon border adjustment mechanics to calibrate fleet composition against tightening operational constraints.
Market Dynamics
Stage V emission standards are compressing diesel equipment residual values while accelerating rental fleet electrification across European job sites, forcing capital deployment toward battery-integrated excavators and telematics-enabled uptime guarantees.
Growth Catalysts
- EU Green Deal fleet mandates:National regulators in Germany and France are enforcing emission thresholds that make rental compliance transfer preferable to ownership risk, pulling contractors toward outsourced electrified fleets.
- Urban infrastructure density:Benelux corridor roadworks and Nordic tunnel projects generate concentrated short-term demand spikes that favor flexible rental structures over fixed asset bases.
- Battery swap infrastructure:Emerging depot networks in the Netherlands and Denmark are reducing electric equipment downtime, enabling rental providers to guarantee utilization rates previously reserved for diesel units.
Market Restraints
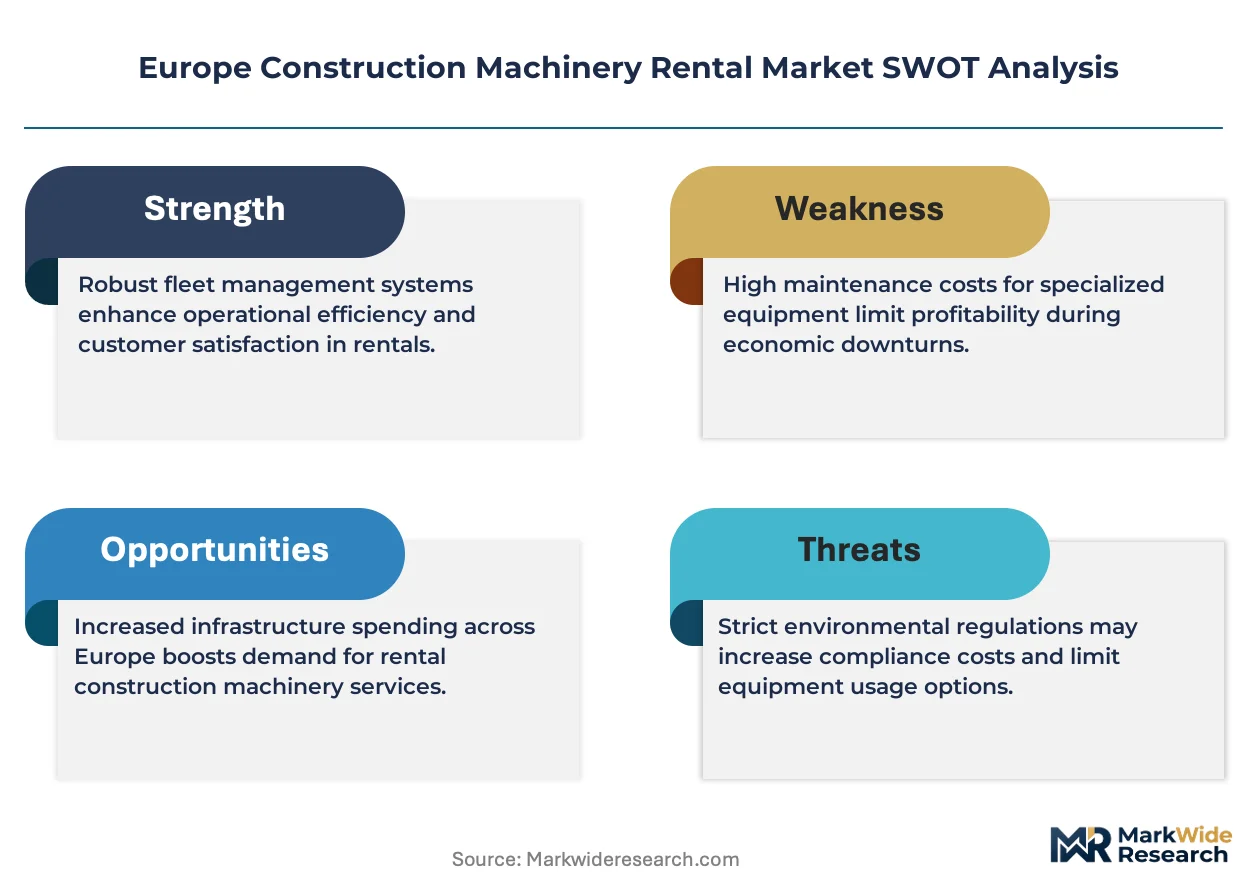
- Lithium-ion supply concentration:Battery cell sourcing dependence on Asian manufacturers creates procurement bottlenecks for European rental fleet electrification timelines.
- Stage V retrofit economics:ECHA REACH compliance costs for hydraulic fluid disposal and exhaust after-treatment systems erode margins on legacy diesel assets still under lease.
- Skilled technician scarcity:High-voltage maintenance certification requirements outpace vocational training output in France and Italy, constraining fleet turnaround capacity.
Strategic Opportunities
- Polish and Romanian civil expansion:EU cohesion fund infrastructure allocations in Eastern European member states create underpenetrated rental demand for earthmoving and roadwork equipment.
- Lease-to-own residual capture:Long-dated German rail and energy transition projects enable rental providers to structure contracts retaining equipment ownership through residual value participation.
- Carbon border adjustment alignment:CBAM reporting requirements on embedded construction equipment emissions position rental fleets with verified low-carbon sourcing as preferred suppliers to ESG-mandated developers.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly middleware development to unify diesel-hour meters with electric-vehicle state-of-charge data across mixed rental portfolios.
- Cross-border certification friction:Divergent national interpretations of CE marking and Stage V type-approval create equipment mobility barriers between German, Austrian, and Swiss alpine construction zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Machinery Rental Market |
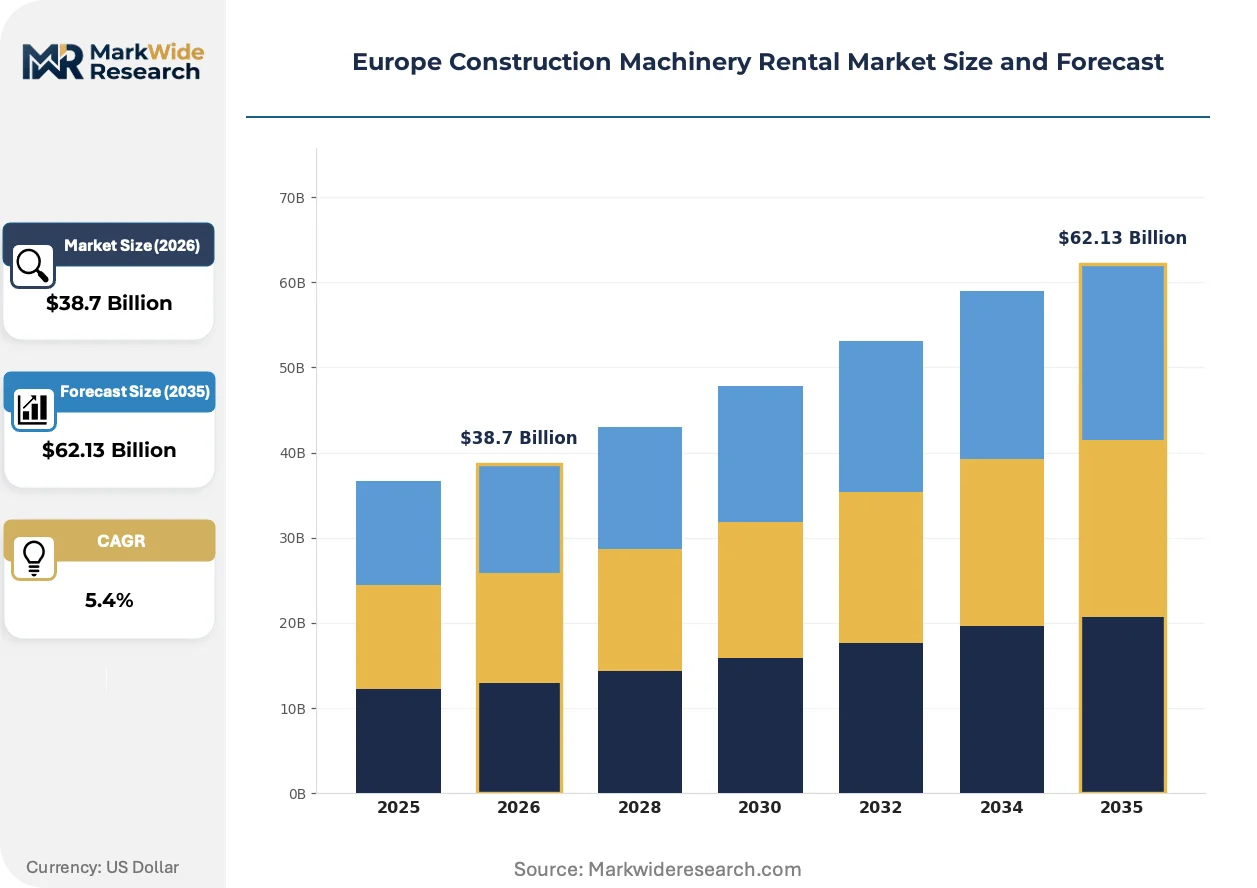
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Forklifts End User: Commercial Contractors, Residential Builders, Infrastructure Developers, Industrial Users Service Type: Short-Term Rental, Long-Term Rental, Lease-to-Own, Maintenance Services Application: Construction Projects, Roadworks, Demolition, Landscaping |
| Companies Covered | Ashtead Group, Cramo, Loxam Group, Mateco Group, Ramirent, Boels Rental, Zeppelin Rental, HKL Baumaschinen, Kiloutou Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Machinery Rental Market Shifts & Advancements
Electrification and digital fleet management are converging to redefine equipment utilization economics, with rental providers competing on real-time availability guarantees rather than asset ownership transfer.
Telematics-integrated battery systems are miniaturizing powertrain footprints in compact excavator classes below 10 tonnes, enabling urban contractors in Amsterdam and Copenhagen to deploy zero-emission units through narrow site access points previously requiring diesel mini-excavators. German municipal procurement frameworks now specify telematics-enabled electric units for inner-city utility works, compressing the operational cost gap between rented electric and owned diesel alternatives.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant recovery infrastructure investment in mobile crane fleets, forcing rental providers to retrofit or replace auxiliary climate systems in all-terrain units above 100-tonne capacity. French and Italian crane operators face the steepest compliance timelines, with national environment agencies mandating documented refrigerant handling certification for all leased equipment crossing regional borders.
Outcome-based availability contracts are displacing traditional daily-rate structures in Nordic road maintenance segments, with Swedish and Norwegian transport agencies specifying guaranteed uptime percentages rather than equipment specifications. Rental providers absorb utilization risk through predictive maintenance algorithms, shifting contractor procurement evaluation from hourly cost to project-completion reliability metrics in high-season asphalt paving windows.
Europe Construction Machinery Rental Market Segmentation
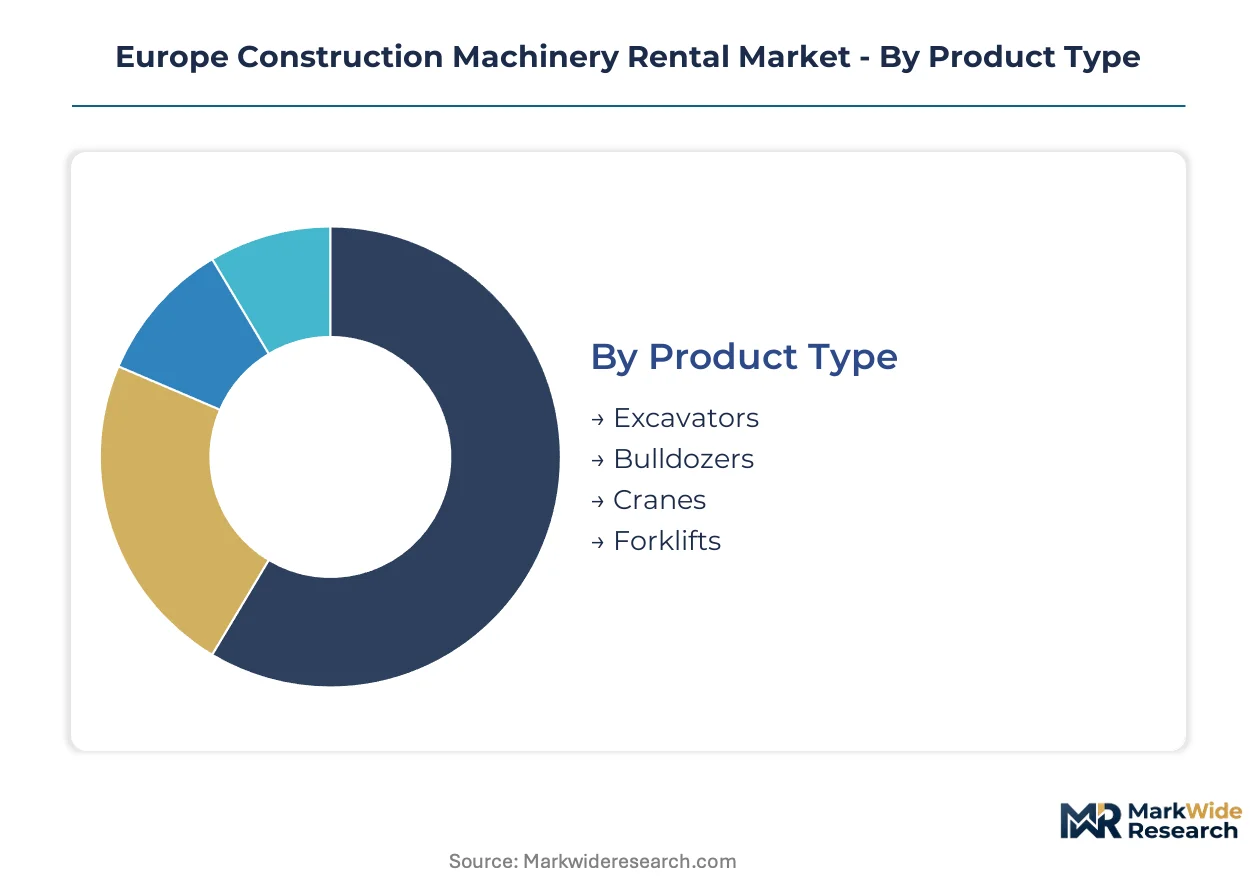
Equipment rental portfolios in Europe stratify around utilization economics and regulatory risk transfer. Contractors select segments based on project duration, emission compliance exposure, and residual value uncertainty.
Product Type:
Substitution pressure from electrified alternatives is most acute in compact equipment classes where battery powertrains now match diesel performance.
- Excavators:Operating weights span 1 to 90 tonnes with hydraulic systems optimized for trenching and material handling. German urban infrastructure corridors and Nordic roadworks generate concentrated demand for sub-10-tonne electric units where Stage V compliance costs favor rental over ownership.
- Cranes:All-terrain configurations reach 300-tonne lift capacity with telescopic booms and counterweight systems. French and Italian operators face accelerated F-Gas Regulation timelines for auxiliary climate systems, pushing rental uptake to transfer refrigerant compliance risk.
- Bulldozers:Tracked earthmovers with blade capacities optimized for grading and site preparation. Benelux landfill and remediation projects drive short-term rental for specialized crawler configurations.
- Forklifts:Telematics-integrated material handlers with electric variants dominating indoor logistics applications. Warehouse construction spikes in Polish distribution corridors sustain fleet utilization.
Excavators retain volume leadership; cranes hold the steepest expansion curve as energy transition projects demand heavier lift capacity.
End User:
Margin capture varies sharply by balance-sheet sophistication and procurement centralization.
- Commercial Contractors:Mid-sized construction firms with project portfolios spanning 6-24 month cycles. German and French commercial operators increasingly outsource fleet management to lock in emission-compliant equipment availability.
- Infrastructure Developers:Long-dated civil works sponsors with ESG-mandated procurement frameworks. Lease-to-own structures appeal to rail and energy transition developers seeking residual value participation.
- Residential Builders:Small-scale developers with intermittent equipment needs. UK housing construction volatility drives spot rental for mini-excavators and compact loaders.
- Industrial Users:Manufacturing and logistics operators with seasonal maintenance windows. Automotive plant shutdowns in Czech and Slovak industrial zones generate predictable rental demand.
Commercial contractors dominate transaction volume; infrastructure developers command the highest contract values per engagement.
Service Type:
Contract structure selection tracks project certainty and capital constraint severity.
- Short-Term Rental:Daily or weekly rates with immediate equipment availability. Peak seasonality in Nordic asphalt paving compresses pricing power during constrained supply windows.
- Long-Term Rental:Multi-year agreements with fixed monthly rates and maintenance inclusion. German municipal utility works favor 3-5 year structures to align with budget cycles.
- Lease-to-Own:Rental payments applied toward eventual ownership transfer. Polish and Romanian EU cohesion fund projects use this structure to circumvent capital expenditure approval delays.
- Maintenance Services:Captive repair and uptime guarantees bundled with equipment access. Loxam Group anchors market position through depot-based technician networks extending equipment availability.
Short-term rental retains transaction frequency leadership; lease-to-own is climbing fastest in Eastern European expansion corridors.
Application:
Site-specific operational constraints dictate equipment specification and rental duration.
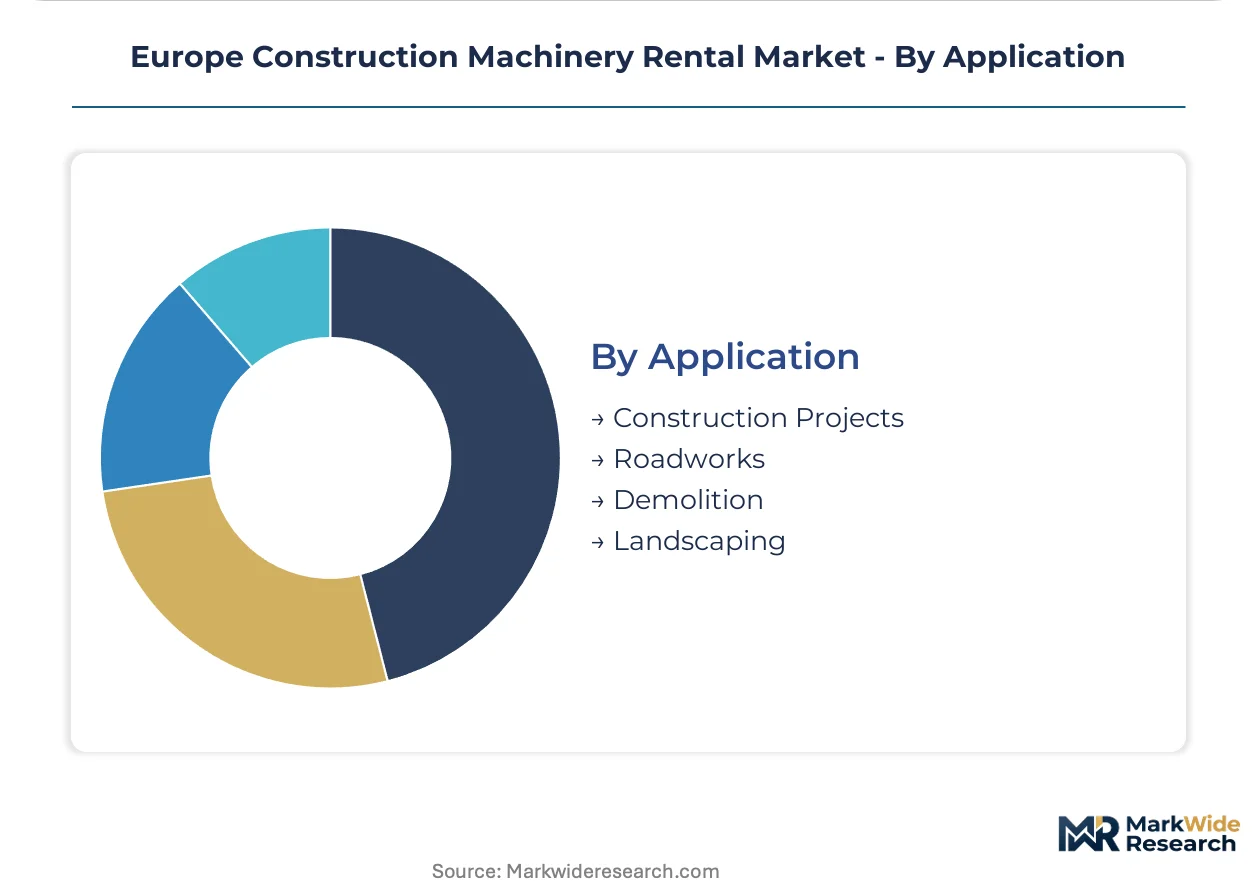
- Construction Projects:General building activity spanning residential, commercial, and mixed-use development. Amsterdam and Copenhagen zero-emission zones mandate electric excavators for inner-city utility works.
- Roadworks:Highway maintenance, tunnel boring, and bridge construction. Swedish and Norwegian transport agencies specify outcome-based availability contracts with guaranteed uptime percentages.
- Demolition:Structural dismantling with specialized attachments and dust suppression systems. German brownfield remediation sites require Stage V-compliant units with documented emission histories.
- Landscaping:Site preparation and environmental restoration with compact equipment. Dutch water management projects sustain seasonal demand for amphibious excavators.
Roadworks retain fleet deployment scale; construction projects are gaining share fastest as urban densification accelerates equipment turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rental fleet networks cluster around German industrial corridors and Nordic infrastructure corridors where EU Green Deal enforcement creates compliance-driven outsourcing demand. Depot density determines same-day availability premiums across Benelux urban construction zones.
Germany
Municipal utility works in Berlin and Hamburg drive demand for sub-10-tonne electric excavators with telematics integration. KBA enforces Stage V emission certification for equipment crossing federal state borders. The Rhine-Ruhr industrial corridor hosts the densest rental depot networks serving energy transition construction projects.
France
Rail infrastructure expansion and nuclear maintenance programs sustain long-term crane rental contracts with uptime guarantees. ANSM enforces refrigerant handling certification under EU F-Gas Regulation timelines for mobile crane fleets. The Île-de-France region concentrates demand for compact electric equipment in Paris metropolitan utility tunnels.
United Kingdom
Housing construction volatility and infrastructure pipeline delays generate spot rental demand for mini-excavators and compact loaders. HSE workplace safety mandates drive maintenance service bundling to transfer equipment inspection liability. The Southeast England corridor anchors cross-border fleet mobility serving Channel Tunnel-linked projects.
Netherlands
Amsterdam and Rotterdam zero-emission zones mandate electric excavators for inner-city utility works with immediate compliance deadlines. National environment agencies enforce noise ordinances that compress diesel equipment operating windows. Battery swap infrastructure rollout in Randstad depots reduces electric equipment downtime below diesel refueling intervals.
Poland
EU cohesion fund road and rail allocations create underpenetrated demand for earthmoving fleet expansion in Warsaw and Kraków construction corridors. National regulators align procurement frameworks with EU Green Deal emission thresholds for public infrastructure tenders. Silesian industrial zone automotive plant maintenance windows generate seasonal forklift rental demand.
Europe Construction Machinery Rental Market Competitive Landscape
Concentration sits with integrated depot-network operators commanding urban availability premiums and cross-border fleet mobility. Three structural tiers define competitive positioning: multinational platform operators with telematics-integrated fleets, regional specialists with captive maintenance technician networks, and national scale players leveraging municipal procurement relationships. Dominant competitive moves include depot density expansion in zero-emission zones and predictive maintenance algorithm deployment to guarantee uptime percentages.
Within the multinational platform tier, Ashtead Group and Loxam Group exemplify archetypes competing on network coverage and compliance risk transfer. Boels Rental occupies a position among Benelux-focused operators leveraging urban depot saturation for same-day availability guarantees. Cramo and Ramirent represent Nordic specialists where outcome-based contracts with transport agencies emphasize project-completion reliability over hourly rate competition.
| Leading Market Players |
|---|
| Ashtead Group |
| Cramo |
| Loxam Group |
| Mateco Group |
| Ramirent |
| Boels Rental |
| Zeppelin Rental |
| HKL Baumaschinen |
| Kiloutou Group |
| Others |
Supply & Pricing Matrix
EU Green Deal emission thresholds gate both supplier qualification and price differentiation across European rental fleets. Contractors face compliance cost transfers that stratify rental rates by equipment certification tier, while supply-side battery sourcing constraints tighten margin structures for electrified asset categories.
Pricing Analysis
Stage V emission standards dictate the pricing tier structure across diesel and electric equipment categories. Three-tier pricing structure across premium, standard, and economy levels separates telematics-integrated electric excavators from Stage V-compliant diesel units and legacy pre-certification fleets. Price differentiation centers on certification grade and after-sales uptime guarantees. Cost compression in standard-tier diesel rentals is intensifying because ECHA REACH hydraulic fluid disposal requirements erode residual lease economics. Residential builders exhibit highest price sensitivity, while infrastructure developers prioritize availability premiums over rate minimization.
Supply Chain Analysis
Germany and the Netherlands anchor depot network density and battery swap infrastructure deployment for electric fleet logistics. Fleet procurement draws from Asian lithium-ion cell manufacturers, European hydraulic component specialists, and Nordic telematics platform providers. Single-source vulnerability concentrates in battery cell supply chains where procurement timelines extend equipment delivery windows. Distribution runs through depot-based hub networks with cross-border fleet mobility serving alpine and corridor construction zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal fragmentation creates niche entry points for specialized operators as compliance complexity outpaces incumbent fleet turnover capacity. Demand-side emission mandates splinter procurement requirements across national regulatory interpretations.
For Market Incumbents: Fortify depot density in zero-emission zones to capture municipal utility contract premiums. Extend captive technician certification for high-voltage maintenance to constrain turnaround capacity for emerging competitors. Battery swap infrastructure investments in Randstad and Rhine-Ruhr corridors defend position against asset-light platform entrants. For New Entrants and Emerging Players: CE marking fast-track services for Polish and Romanian EU cohesion fund projects unlock white-space penetration where incumbent networks remain sparse. Target underpenetrated Eastern European roadwork corridors with lease-to-own structures that circumvent capital expenditure approval delays. Anchor go-to-market through carbon border adjustment alignment to capture ESG-mandated developer procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional depot networks consolidating across Benelux and Nordic markets. Five-to-ten year viability frames rental electrification capex cycles against residual value capture from lease-to-own structures. Monitor battery swap infrastructure rollout velocity as inflection indicator for electric fleet utilization parity with diesel alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Expansion | Urban depot saturation in Amsterdam and Copenhagen zero-emission zones commands same-day availability premiums. |
| Backward Integration into Battery Logistics | Captive battery swap infrastructure reduces electric equipment downtime below diesel refueling intervals. |
| Predictive Maintenance Platform Deployment | Telematics-integrated uptime algorithms enable outcome-based contracts with Swedish transport agencies. |
| CE Marking Fast-Track Certification | Accelerated type-approval reduces equipment mobility barriers between German and Austrian alpine zones. |
| Lease-to-Own Structure Development | Residual value participation in Polish rail projects shifts margin capture from pure rental yield. |
Research Methodology
Initial hypotheses were tested against primary input from rental fleet operations directors, municipal procurement officers, and high-voltage maintenance technicians and refined through secondary validation. Primary interviews encompassed depot network managers, EPC contractor equipment planners, and EU regulatory compliance consultants. Secondary sources included KBA type-approval registries, ECHA REACH substance databases, national customs equipment import records, and municipal tender documentation. Bottom-up equipment deployment estimates triangulated against top-down construction expenditure forecasts.
Variance decomposition across equipment type, powertrain architecture, contract duration tier, and national regulatory cluster shaped projection reliability bands. Segmentation dimensions modeled encompass product category, end-user sophistication, service structure, and application site constraints. CAGRs were derived from equipment fleet growth rates correlated with construction output indices and electrification capex cycles. Battery swap infrastructure deployment schedules and Stage V enforcement timelines constituted industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and lithium-ion supply availability; material deviation would warrant model refresh. Forecasts reflect assumptions regarding national regulatory alignment and cohesion fund allocation continuity. Recalibration cycles align with material shifts in battery cell procurement economics and cross-border certification harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
North America Drilling Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
United States Crane Market
Construction Equipment
Piling Machine Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Concrete Chain Saw Market