
 Casting Equipment Market | 2026-2036
Casting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Casting Equipment Market Analysis
Digital twin integration is rewriting how foundries optimize cycle times and defect rates before physical trials. Bühler Group leverages its Swiss engineering heritage to dominate premium die casting cell configurations. Yizumi Holdings Co., Ltd. anchors its competitive position through aggressive R&D spending on large-structural aluminum casting platforms. Frech GmbH specializes in hot-chamber zinc systems that sustain margin pools in European automotive supply chains.
Casting equipment encompasses machinery engineered to shape molten metal into precise components through controlled filling, solidification, and ejection processes, typically operating at clamping forces from 100 to 4,000 tons and temperatures exceeding 700°C for aluminum alloys. Die casting commands the largest installed base among product types, while vacuum casting technology is capturing disproportionate investment from aerospace producers seeking porosity reduction in titanium and nickel superalloy components. Pressure casting systems generate the deepest margin pools due to their complexity and aftermarket service attach rates.
EPA emissions standards and OSHA foundry safety regulations in the United States compel equipment upgrades toward enclosed pouring and fume extraction architectures. REACH compliance in Europe restricts certain mold release chemistries, redirecting R&D toward water-based and inorganic alternatives. Stakeholders must monitor how China's MEE enforcement of dual carbon targets reshapes energy-intensive foundry investment cycles across Asia-Pacific supply nodes.
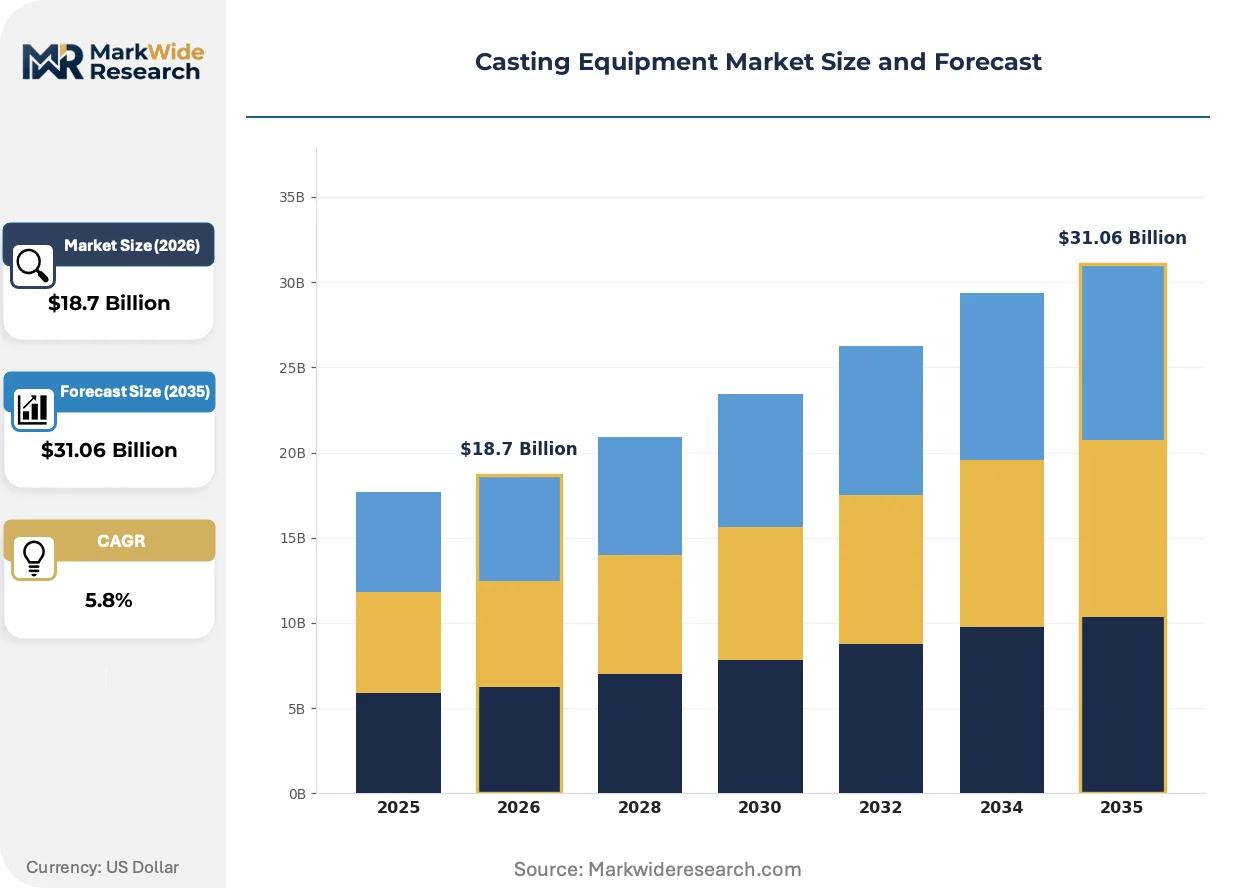
Market Dynamics
Automotive OEM lightweighting mandates are compressing traditional sand casting cycles and forcing capital redeployment toward high-pressure die casting architectures capable of producing large structural aluminum components.
Growth Catalysts
- EPA emissions standards:United States foundries must retrofit enclosed pouring and fume extraction systems, creating replacement demand for legacy open-architecture equipment.
- Aluminum structural battery housings:Electric vehicle platforms require single-piece castings exceeding 1,000 tons clamping force, pulling investment toward mega-casting cell configurations.
- Stuttgart-Munich supplier belt:Germany's concentrated automotive supplier ecosystem sustains premium equipment procurement volumes for hot-chamber and cold-chamber systems.
Market Restraints
- Scrap aluminum price volatility:Input cost swings compress foundry margins and delay capital equipment replacement cycles.
- MEE enforcement variance:China's provincial implementation of dual carbon targets creates uneven investment timelines across Asia-Pacific supply nodes.
- Thermal spray coating substitution:Near-net-shape additive processes displace some precision casting applications in aerospace repair segments.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic OEM localization mandates create greenfield foundry investment windows for die casting equipment suppliers.
- Digital twin convergence:Physics-based simulation platforms merge with IoT sensor networks to enable predictive maintenance service contracts.
- REACH-compliant water-based release agents:European regulatory pressure on mold release chemistries opens formulation innovation partnerships between equipment and consumables providers.
Industry Challenges
- Multi-physics simulation expertise:Foundries lack personnel capable of calibrating digital twin models against actual thermal and flow behavior.
- Legacy SCADA integration:Brownfield facilities struggle to retrofit Industry 4.0 connectivity onto 1990s-era machine controllers without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casting Equipment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Casting, Sand Casting, Investment Casting, Shell Molding Application: Aerospace, Automotive, Industrial Machinery, Art Technology: Gravity Casting, Vacuum Casting, Pressure Casting, Cold Chamber End User: Manufacturers, Automotive OEMs, Aerospace Producers, Foundries |
| Companies Covered | Shibaura Machine, L.K. Technology Holdings Limited, Bühler Group, UBE Machinery Inc., Yizumi Holdings Co., Ltd., Norican Group, Frech GmbH, Italpresse Gauss, Idra Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casting Equipment Market Emerging Trajectories
Equipment intelligence layers are overtaking mechanical specifications as the primary competitive differentiator, with software-defined process control displacing fixed-parameter operation across foundry floors.
Vacuum-assisted die casting is migrating from aerospace specialty applications into premium automotive structural components. Tier 1 suppliers in Germany and Japan are adopting these systems for aluminum battery tray production. The technology is migrating from porosity-sensitive titanium and nickel superalloy work toward high-volume aluminum programs, compressing the traditional quality-cost tradeoff in automotive supply chains.
China's MEE enforcement of dual carbon targets is mandating energy consumption audits and carbon intensity disclosures for foundry operations. Equipment purchasers must now document kWh-per-ton metrics in procurement specifications. Cold-chamber die casting lines with regenerative thermal oxidizers are capturing disproportionate attention in Jiangsu and Guangdong provinces.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete modules for spare parts, remote monitoring, and field engineering. German automotive suppliers are driving this shift through multi-vendor fleet standardization efforts. The model is most visible in Stuttgart's supplier ecosystem, where centralized procurement functions negotiate monitoring subscriptions separately from mechanical service agreements.
Casting Equipment Market Segmentation
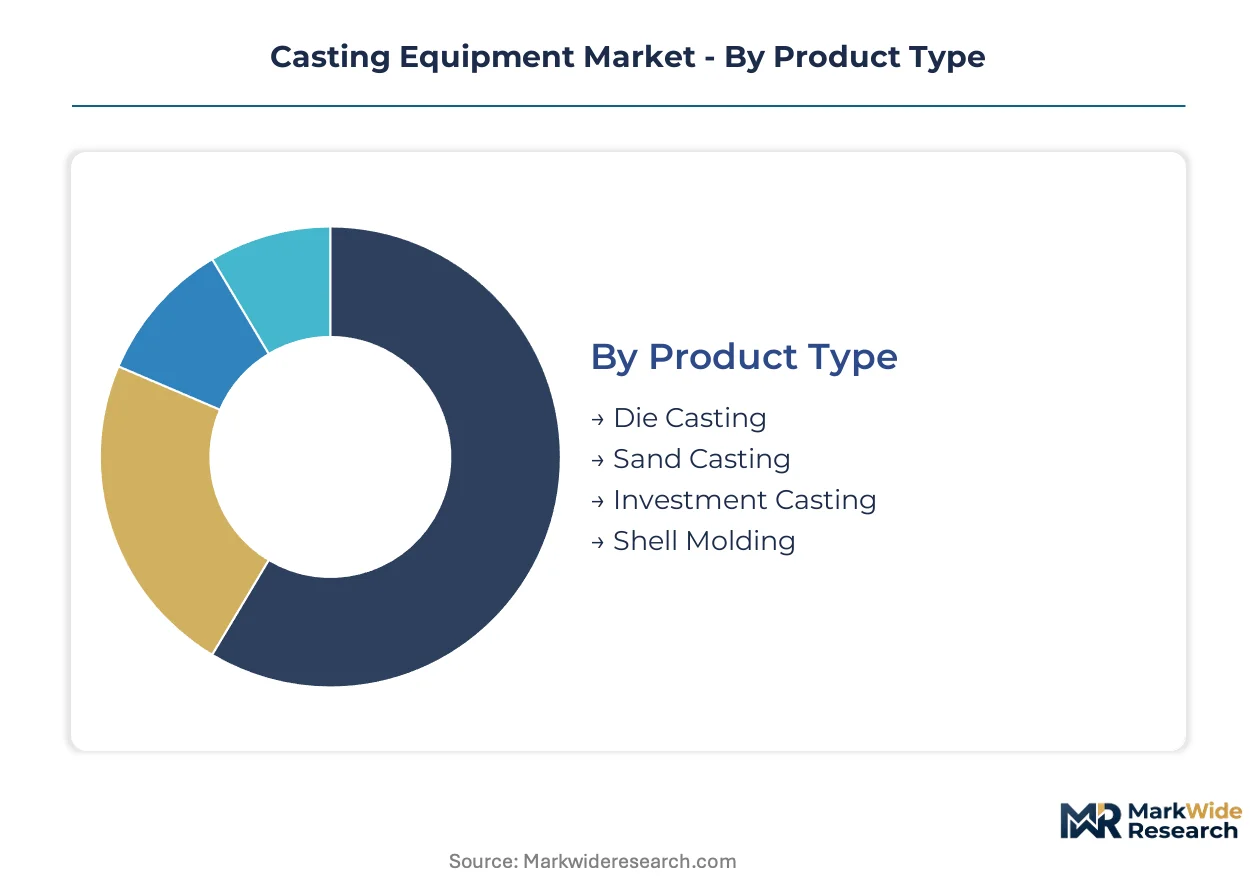
Casting equipment segmentation reveals divergent service intensity profiles across product architectures. Die casting cells demand continuous calibration support and consumables replenishment, while sand casting installations prioritize periodic rebuild cycles over embedded telemetry.
Product Type:
After-sales service intensity varies dramatically across equipment architectures, with pressure-based systems generating recurring revenue streams through die lubrication systems and thermal management component replacement programs.
- Die Casting:High-pressure systems operating at 1,000-4,000 tons clamping force dominate automotive structural component production. Germany's Stuttgart-Munich supplier belt sustains premium procurement for aluminum battery tray manufacturing, though mega-casting cell adoption compresses traditional multi-piece assembly demand.
- Sand Casting:Green sand and chemically bonded systems retain cost advantages for iron engine blocks and transmission housings. India's PLI scheme for automotive localization is pulling greenfield investment toward mechanized mold handling equipment in Pune and Chennai industrial corridors.
- Investment Casting:Ceramic shell processes enable complex aerospace geometries in nickel superalloys.
- Shell Molding:Resin-bonded sand techniques deliver dimensional precision for medium-volume ferrous castings.
Die casting holds the largest share; momentum sits with investment casting as aerospace OEMs reshore critical superalloy component supply.
Application:
End-use concentration shapes equipment specification priorities, with aerospace demanding vacuum-assisted porosity control while automotive prioritizes cycle time compression.
- Automotive:OEM lightweighting mandates are forcing capital redeployment from sand casting toward high-pressure die casting architectures capable of producing single-piece aluminum structural components exceeding 1,000 tons clamping force.
- Aerospace:Titanium and nickel superalloy work demands vacuum-assisted systems with porosity thresholds below 0.5 percent. Japan's METI-funded R&D consortia are advancing ceramic mold materials for directional solidification turbine blades.
- Industrial Machinery:Pump housings and valve bodies sustain mid-tier equipment demand across standard cold-chamber configurations.
- Art:Bronze sculpture and architectural metalwork preserve manual techniques with minimal automation penetration.
Automotive commands dominant equipment procurement volumes; aerospace applications are climbing the fastest on unit value metrics.
Technology:
Process physics determine capital intensity and operating cost structures, with pressure differentials directly correlating to energy consumption and die wear rates.
- Pressure Casting:Multi-stage intensification systems achieve near-net-shape precision in zinc and magnesium alloys. China's MEE enforcement of dual carbon targets is mandating kWh-per-ton documentation for high-pressure line approvals in Jiangsu province.
- Vacuum Casting:Reduced atmosphere filling eliminates gas porosity in titanium aerospace castings. Germany's KBA-certified suppliers are migrating this technology into premium automotive battery tray production.
- Gravity Casting:Tilt-pour and static pouring systems dominate aluminum wheel manufacturing.
- Cold Chamber:Horizontal shot sleeve configurations separate molten metal contact from injection mechanisms.
Pressure casting retains the deepest margin pools; vacuum systems are gaining share fastest as quality thresholds tighten across automotive and aerospace supply chains.
End User:
Procurement sophistication diverges between integrated manufacturers with captive engineering capabilities and independent foundries relying on equipment vendor technical support.
- Automotive OEMs:Volkswagen, BMW, and Mercedes-Benz are internalizing mega-casting cell operation for electric vehicle platforms. EPA emissions standards compel enclosed pouring architecture retrofits at US-based captive foundries.
- Aerospace Producers:Pratt & Whitney and Rolls-Royce maintain stringent NADCAP certification requirements for investment casting equipment. REACH compliance redirects mold release chemistry R&D toward water-based formulations.
- Foundries:Independent operators prioritize equipment flexibility across multiple alloy systems.
- Manufacturers:General industrial users span pump, valve, and construction equipment suppliers with heterogeneous specification demands.
Automotive OEMs drive the steepest expansion trajectory; foundries represent the most price-sensitive procurement segment with extended replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment exports flow disproportionately toward China's Yangtze River Delta foundry clusters, while Japanese suppliers anchor demand across Southeast Asian automotive supply nodes. Equipment trade corridors concentrate where OEM lightweighting mandates intersect with regulatory enforcement timelines.
United States
EPA emissions standards and OSHA foundry safety regulations compel enclosed pouring retrofits at legacy open-architecture facilities. The Inflation Reduction Act's clean manufacturing provisions accelerate capital replacement cycles in Michigan and Ohio industrial corridors. Detroit's automotive supplier ecosystem sustains premium procurement for high-pressure die casting cells serving electric vehicle platforms.
Germany
KBA-certified suppliers drive vacuum-assisted die casting adoption for aluminum battery tray production across Stuttgart and Munich. REACH compliance redirects mold release chemistry R&D toward water-based formulations. Baden-Württemberg's concentrated automotive supplier belt generates sustained demand for hot-chamber and cold-chamber system upgrades.
China
MEE enforcement of dual carbon targets mandates kWh-per-ton documentation for foundry equipment approvals in Jiangsu and Guangdong provinces. NMPA energy-efficiency mandates tighten operational parameters for aluminum casting lines. The Yangtze River Delta anchors mega-casting cell deployment for domestic electric vehicle OEMs.
Japan
METI-funded R&D consortia advance ceramic mold materials for directional solidification turbine blades in aerospace applications. JIS standards certification requirements shape equipment specification priorities. Nagoya's industrial corridor concentrates investment casting demand from precision aerospace suppliers.
India
The PLI scheme for automotive localization creates greenfield foundry investment windows in Pune and Chennai industrial corridors. BIS equipment certification requirements structure procurement specifications for domestic OEMs. Maharashtra and Tamil Nadu anchor mechanized mold handling equipment deployment for iron engine block production.
Casting Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base stratifies between premium Swiss-German engineering houses and scale-driven Asian fabricators. Three archetypes dominate: technology-integrated solution providers, regional cost-optimized suppliers, and niche process specialists. Strategic moves concentrate on digital twin convergence partnerships and after-sales service unbundling.
Within the premium engineering tier, Bühler Group and Frech GmbH exemplify technology-integrated positioning through Swiss and German heritage respectively. Yizumi Holdings Co., Ltd. anchors the scale-driven archetype among Chinese equipment fabricators. These three occupy distinct competitive spaces—European precision engineering versus Asian manufacturing scale—without direct portfolio overlap in core product configurations.
| Leading Market Players |
|---|
| Shibaura Machine |
| L.K. Technology Holdings Limited |
| Bühler Group |
| UBE Machinery Inc. |
| Yizumi Holdings Co., Ltd. |
| Norican Group |
| Frech GmbH |
| Italpresse Gauss |
| Idra Group |
| Others |
Supply Flow & Price Mechanics
Swiss-German precision engineering clusters anchor premium die casting cell supply, concentrating margin capture among Bühler Group and Frech GmbH while Asian fabricators compete on standardized cold-chamber configurations. This upstream specialization creates divergent pricing power across equipment tiers, with digital twin-enabled systems commanding service-attach premiums that commodity fabricators cannot replicate.
Pricing Analysis
Legacy mechanical-only systems, current-generation IoT-enabled cells, and next-gen autonomous die casting platforms occupy distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales bundling intensity. Cost compression in standard-tier cold-chamber equipment is intensifying because Chinese fabricators are expanding capacity in Jiangsu province. Independent foundries represent the most price-sensitive procurement segment, while captive automotive OEM operations prioritize total cost of ownership over unit price.
Supply Chain Analysis
Hon Hai Precision Industry and select German automotive supplier foundries hold disproportionate contract-manufacturing capacity for mega-casting cell deployment. Geographic supply concentration centers on China, Germany, and Japan, with each anchoring distinct technology tiers. Raw material dependencies draw from high-grade ductile iron for machine frames, copper alloys for thermal management components, and specialized hydraulic systems. Single-source vulnerability in precision shot sleeve manufacturing creates chokepoint exposure. Distribution runs through direct OEM sales teams for premium configurations and regional distributor networks for standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbents. NMPA energy-efficiency mandates and EPA emissions standards create certification barriers that new entrants cannot rapidly replicate.
For Market Incumbents: Pre-empt emerging Asian competitors by deepening captive service capabilities in Stuttgart-Munich supplier ecosystems. Accelerate digital twin convergence partnerships before standard-tier fabricators close the software gap. Vertical integration into regenerative thermal oxidizer technology strengthens positioning against MEE enforcement variance in Chinese provinces. For New Entrants and Emerging Players: Build out India PLI scheme corridors in Pune and Chennai where greenfield foundry investment exceeds established service infrastructure. Target mechanized sand casting equipment for iron engine block production, the most penetrable segment given localization mandates. Pursue BIS certification partnerships as the primary go-to-market angle to overcome procurement specification barriers. For Investors and Strategic Acquirers: Capital is best deployed toward technology-integrated solution providers with embedded software revenue streams and aftermarket service unbundling capabilities. Long-term viability favors vendors capturing predictive maintenance subscription economics rather than pure equipment transaction models. Watch for MEE enforcement acceleration in Jiangsu and Guangdong as the signal indicating carbon-intensity disclosure mandates will spread to additional provinces.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Convergence Partnership | Physics-based simulation platforms from Siemens and Ansys enable predictive maintenance service contracts for foundry operators. |
| Backward Integration into Thermal Management Components | In-house production of regenerative thermal oxidizers addresses MEE kWh-per-ton mandates in Chinese foundry clusters. |
| REACH-Compliant Release Agent Formulation | Water-based mold release chemistry partnerships with ECHA-registered suppliers secure European automotive procurement specifications. |
| Mega-Casting Cell Capacity Expansion | 4,000-ton clamping force configurations serve Volkswagen and BMW single-piece aluminum structural component programs. |
| India PLI Localization Joint Venture | Domestic OEM mandates in Maharashtra and Tamil Nadu create captive demand for mechanized mold handling equipment. |
Methodological Framework
The analysis maps die casting, sand casting, investment casting, and shell molding segments, each validated through foundry operations directors, OEM procurement teams, aftermarket service heads, and equipment engineering leads. Primary interviews with plant managers at Stuttgart-Munich supplier facilities and Tier 1 automotive procurement officers combined with secondary validation from EPA emissions filings, NMPA energy-efficiency disclosures, MEE carbon intensity audits, and SEC equipment supplier 10-K filings. Bottom-up equipment shipment tracking and top-down foundry capital expenditure analysis provide triangulation.
Assumption sets held regulatory enforcement timelines and aluminum price bands within observed ranges while varying electric vehicle platform adoption rates and aerospace reshoring intensity. Segmentation dimensions modeled include product architecture, clamping force tier, end-use industry concentration, and regional regulatory cluster across the projection horizon. CAGRs derive from equipment replacement cycle analysis and greenfield investment pipeline tracking, with specific inputs from NMPA efficiency mandate compliance deadlines and EPA retrofit obligation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported fabricators or sudden REACH restriction expansion would shift outcomes. Quarterly review of MEE provincial enforcement variance, scrap aluminum price volatility, and mega-casting cell adoption rates at domestic Chinese EV OEMs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
North America Mobile Crane Market
Construction Equipment
Felling Heads Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
India Crane Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
United States Crane Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Asia-Pacific Road Marking Machine Market