
 Construction Pump Market | 2026-2036
Construction Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Pump Market Insights
Infrastructure firms is redrawing procurement patterns across the Construction Pump landscape. Xylem leverages its vertical integration in dewatering systems to capture municipal-scale projects across multiple continents. Grundfos anchors its position through R&D intensity in energy-efficient circulator technology for building services. KSB dominates heavy-duty slurry applications with manufacturing scale that few competitors match.
A construction pump is a mechanical device engineered to move fluids, slurries, or viscous materials through pressurized discharge lines at flow rates typically ranging from ten to several thousand gallons per minute, using impeller, piston, or peristaltic action to overcome elevation head and friction losses. Its primary industrial purpose is to enable continuous material transfer in concrete placement, groundwater removal, and grout injection where gravity-fed systems prove inadequate. Centrifugal pumps lead the pump type category due to their versatility across clean water and light slurry duties, while diaphragm configurations command margin pools in abrasive mining and oilfield services where seal longevity determines total cost of ownership. Electric technology is gaining fastest within the technology dimension as site electrification and battery storage advance, though diesel engine variants still occupy remote locations lacking grid connectivity.
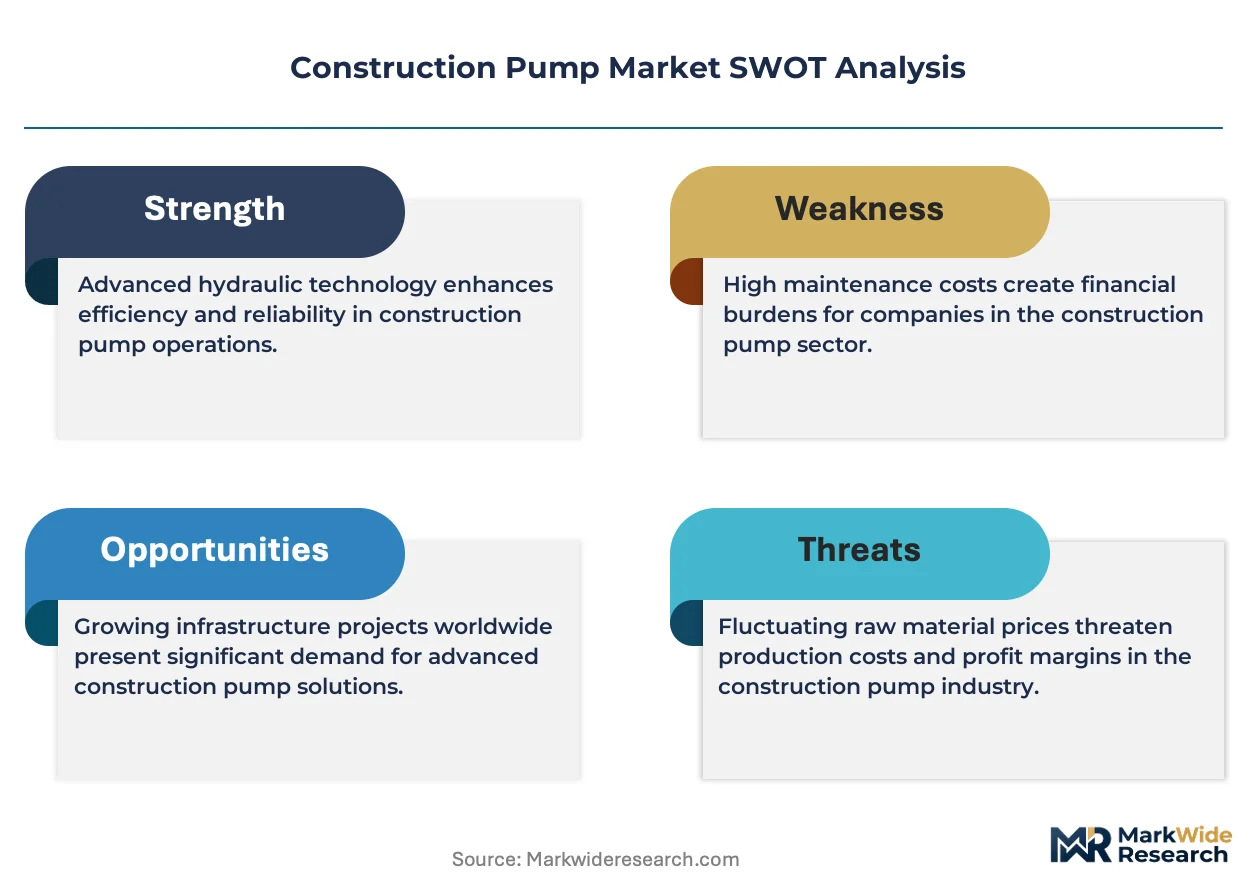
EPA tailpipe emissions rules and OSHA noise exposure limits are reshaping equipment specification sheets for North American contractors, forcing manufacturers to redesign power trains and acoustic enclosures. The EU Green Deal and F-Gas Regulation are accelerating phase-out of refrigerant-dependent cooling systems in pump drive packages sold across Europe. China's MEE enforces discharge water quality standards that elevate demand for closed-loop dewatering systems with integrated filtration. Stakeholders must monitor how rapidly battery energy density improvements translate into cordless high-pressure concrete placement at commercial scale.
Market Dynamics
EPA tailpipe emissions rules and OSHA noise exposure limits are forcing North American contractors to rewrite equipment specification sheets, accelerating the phase-out of diesel-powered pumps in favor of electric and battery-backed alternatives across concrete placement and dewatering operations.
Growth Catalysts
- China's MEE discharge standards:The Ministry of Ecology and Environment enforces water quality mandates that elevate demand for closed-loop dewatering systems with integrated filtration in municipal-scale projects.
- Site electrification infrastructure:Battery storage density improvements and grid-tied job sites enable cordless high-pressure concrete placement systems to replace diesel variants in urban construction zones.
- Megacity water management schemes:State-backed urban renewal projects in Shanghai and Shenzhen require heavy slurry transfer capacity for subway tunneling and foundation dewatering at unprecedented scale.
Market Restraints
- Steel and rare-earth input volatility:Permanent magnet motors and high-grade pump housings face cost pressure from concentrated Chinese supply chains for neodymium and specialty alloys.
- EU F-Gas Regulation friction:The phase-out of refrigerant-dependent cooling systems in pump drive packages forces European manufacturers to redesign thermal management architectures mid-cycle.
- Technical ceiling on cordless pressure:Current lithium-ion energy density limits cordless concrete pumps to mid-rise applications, excluding high-rise commercial towers from electrification.
Strategic Opportunities
- India's PLI scheme for construction equipment:Production-linked incentives for domestic manufacturing create localized assembly advantages for dewatering pump OEMs targeting South Asian infrastructure tenders.
- Solar-powered remote deployment:Photovoltaic array integration with diaphragm pumps opens oilfield services and mining dewatering in grid-deficient regions of Australia and the Middle East.
- Rental channel digitization:IoT-enabled fleet management platforms allow equipment lessors to unbundle after-sales service and capture recurring revenue from predictive maintenance subscriptions.
Industry Challenges
- Electrification technician scarcity:The shift from mechanical diesel drivetrains to battery-electric powertrains demands skills in high-voltage systems and thermal management that legacy pump service networks lack.
- Certification timeline compression:UL and CE marking requirements for new electric pump architectures extend product launch cycles while competitors race to secure first-mover positioning in municipal procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Pump Market |
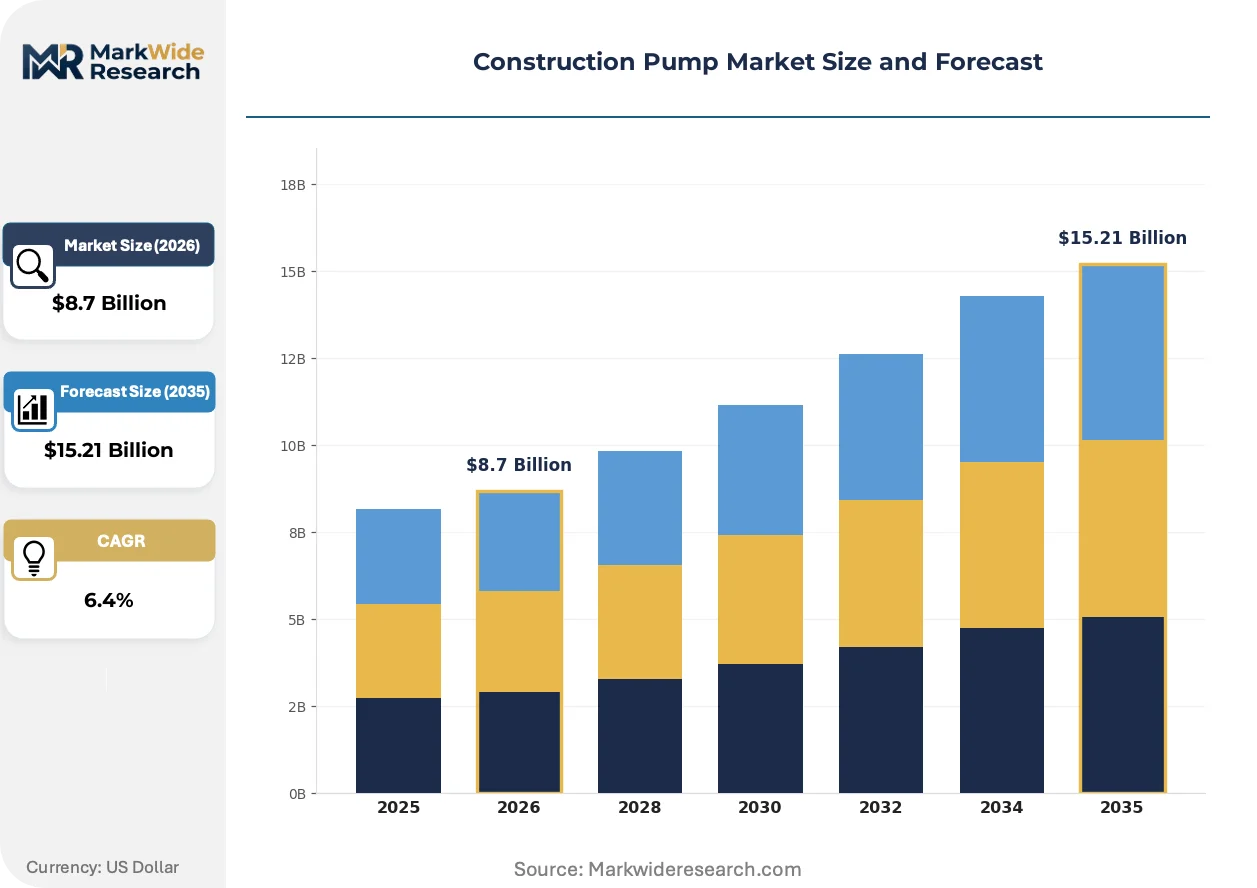
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pump Type: Centrifugal, Diaphragm, Peristaltic, Piston, Rotary Vane Technology: Hydraulic, Electric, Diesel Engine, Pneumatic, Solar Powered Application: Concrete Placement, Dewatering, Slurry Transfer, Grouting, Fire Protection End User: General Contractors, Infrastructure Firms, Mining Operators, Oilfield Services |
| Companies Covered | Xylem, Grundfos, KSB, Flowserve, Sulzer, ITT, Atlas Copco, Tsurumi Manufacturing, Ebara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Pump Market Trends and Innovations
Electrification is fragmenting established technology hierarchies across the construction pump landscape. Manufacturers now face parallel development tracks for diesel, hybrid, and fully electric architectures while buyers recalibrate total cost of ownership models around energy and maintenance rather than upfront capital.
Modular battery swap systems are fragmenting the traditional unitary pump design paradigm. Rental fleet operators in Germany and California are adopting standardized battery packs that detach from pump chassis, enabling continuous operation through hot-swapping rather than charging downtime. This architecture compresses asset utilization metrics and forces OEMs to redesign frame geometries around interoperability standards.
EPA Tier 4 Final and Stage V emissions standards in the US and EU are eliminating small diesel engines from compact concrete pump categories. Manufacturers respond with electric drivetrains for urban job sites and dual-fuel hybrids for transitional markets, while the regulatory drag affects most severely the sub-50-horsepower portable segment where electrification economics first reach parity.
Specification authority is migrating from general contractors to municipal procurement offices with embedded sustainability mandates. Water authorities in Denmark and Singapore now require ISO 14001-certified manufacturing and embedded carbon disclosures in tender documentation, displacing traditional price-per-horsepower evaluation frameworks with lifecycle assessment scoring that favors regional suppliers with transparent supply chains.
Construction Pump Market Segmentation
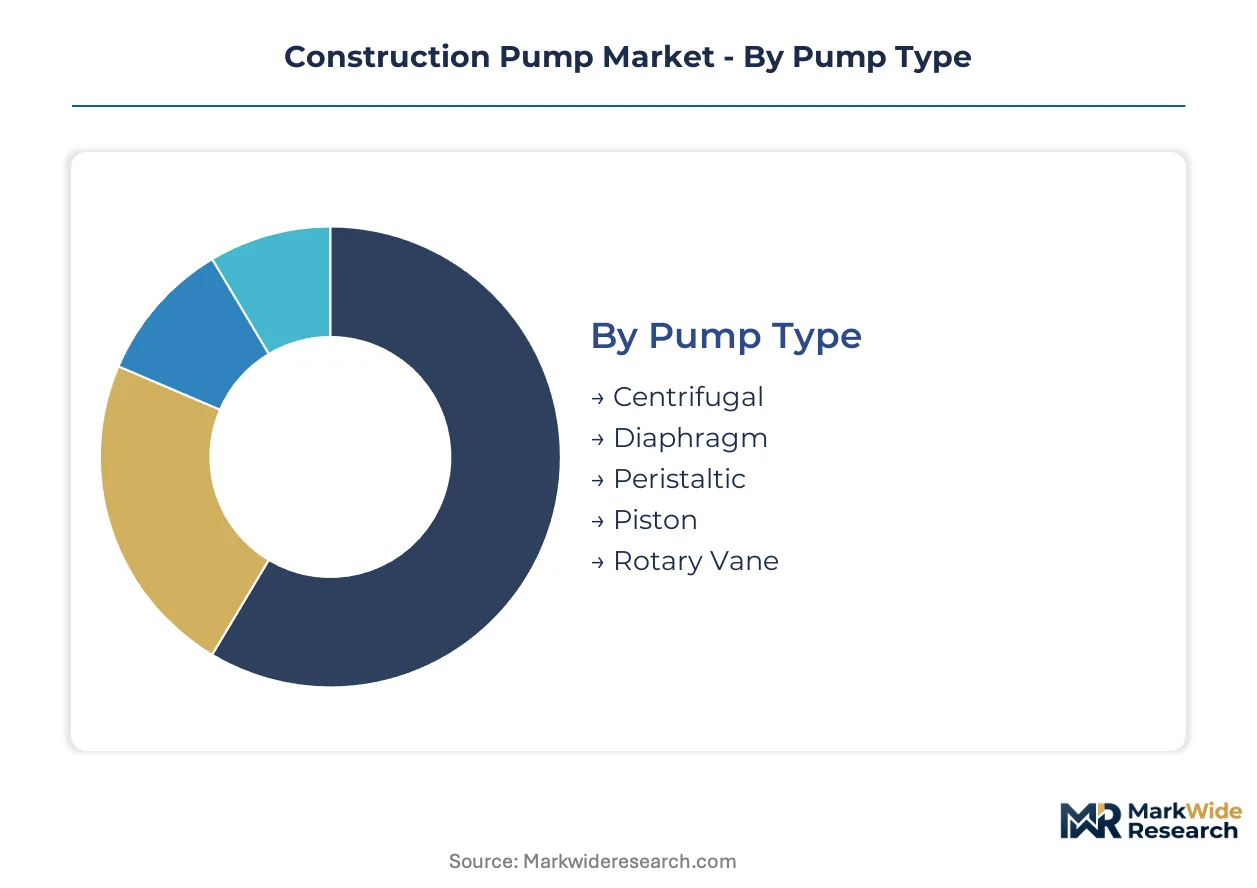
Construction pump procurement channels diverge sharply by segment. Municipal infrastructure tenders favor electric centrifugal systems with certified energy ratings. Mining and oilfield contractors source abrasive-duty diaphragm pumps through specialized distributors with field service capabilities.
Pump Type:
Channel mix varies by impeller geometry and sealing architecture. Centrifugal and diaphragm pumps flow through equipment rental networks and OEM-direct municipal contracts. Peristaltic, piston, and rotary vane configurations concentrate in specialized mining and industrial distribution.
- Centrifugal:Impeller-driven units handle clean water and light slurry at high flow rates with minimal maintenance. Demand clusters in China's state-backed urban renewal schemes where dewatering volume requirements exceed ten thousand gallons per minute. EPA discharge mandates accelerate specification of closed-loop configurations with integrated filtration.
- Diaphragm:Positive-displacement systems with elastomeric membranes isolate abrasive fluids from mechanical components. Mining operators in Australia and Chile specify these for tailings transfer where seal longevity determines total cost of ownership. The segment commands margin pools unavailable to centrifugal alternatives.
- Peristaltic:Hose-compression mechanisms suit precise chemical dosing and viscous grout injection.
- Piston:Reciprocating plungers deliver ultra-high pressures for concrete placement in high-rise construction.
- Rotary Vane:Eccentric rotor designs handle medium-viscosity fluids in compact mobile configurations.
By volume, Centrifugal leads. By growth pace, Diaphragm is ahead.
Technology:
Cost tier stratification separates premium electric architectures from economy diesel variants. Battery-electric systems carry capital premiums of forty to sixty percent over comparable diesel units but deliver operating cost advantages in grid-connected urban environments.
- Electric:Grid-tied and battery-backed drivetrains eliminate tailpipe emissions for OSHA-compliant urban job sites. Shanghai and Shenzhen infrastructure authorities now mandate electric concrete placement within municipal core zones. Battery swap standardization in German rental fleets compresses asset utilization metrics.
- Diesel Engine:Compression-ignition powertrains retain dominance in remote locations lacking grid connectivity. Australian mining contractors and Middle East oilfield services specify these for off-grid dewatering where solar array deployment proves uneconomical. EPA Tier 4 Final and EU Stage V regulations eliminate sub-fifty-horsepower variants from compact categories.
- Hydraulic:Fluid-power transmission suits high-torque concrete pumping with precise boom control.
- Pneumatic:Compressed-air drive eliminates ignition risk in explosive atmospheres.
- Solar Powered:Photovoltaic integration with diaphragm pumps opens grid-deficient regions for autonomous dewatering.
By installed base, Diesel Engine leads. By expansion trajectory, Electric climbs fastest.
Application:
Customer type determines specification authority and channel access. Municipal water authorities issue dewatering tenders with embedded sustainability mandates. General contractors retain concrete placement procurement autonomy.
- Dewatering:Groundwater removal systems range from compact six-inch portable units to municipal-scale stationary installations. China's MEE enforces discharge water quality standards that elevate demand for closed-loop configurations with integrated filtration. Singapore and Denmark water authorities require ISO 14001-certified manufacturing and embedded carbon disclosures.
- Concrete Placement:High-pressure boom pumps and trailer-mounted line pumps enable continuous material transfer where gravity-fed systems fail. Battery energy density limits currently restrict cordless variants to mid-rise applications, excluding high-rise commercial towers from full electrification.
- Slurry Transfer:Abrasive fluid handling for tunneling and mining operations.
- Grouting:Precision injection of cementitious and chemical grouts for ground stabilization.
- Fire Protection:Standby pump systems for construction site sprinkler and hydrant supply.
By revenue concentration, Dewatering leads. By specification intensity, Concrete Placement dominates.
End User:
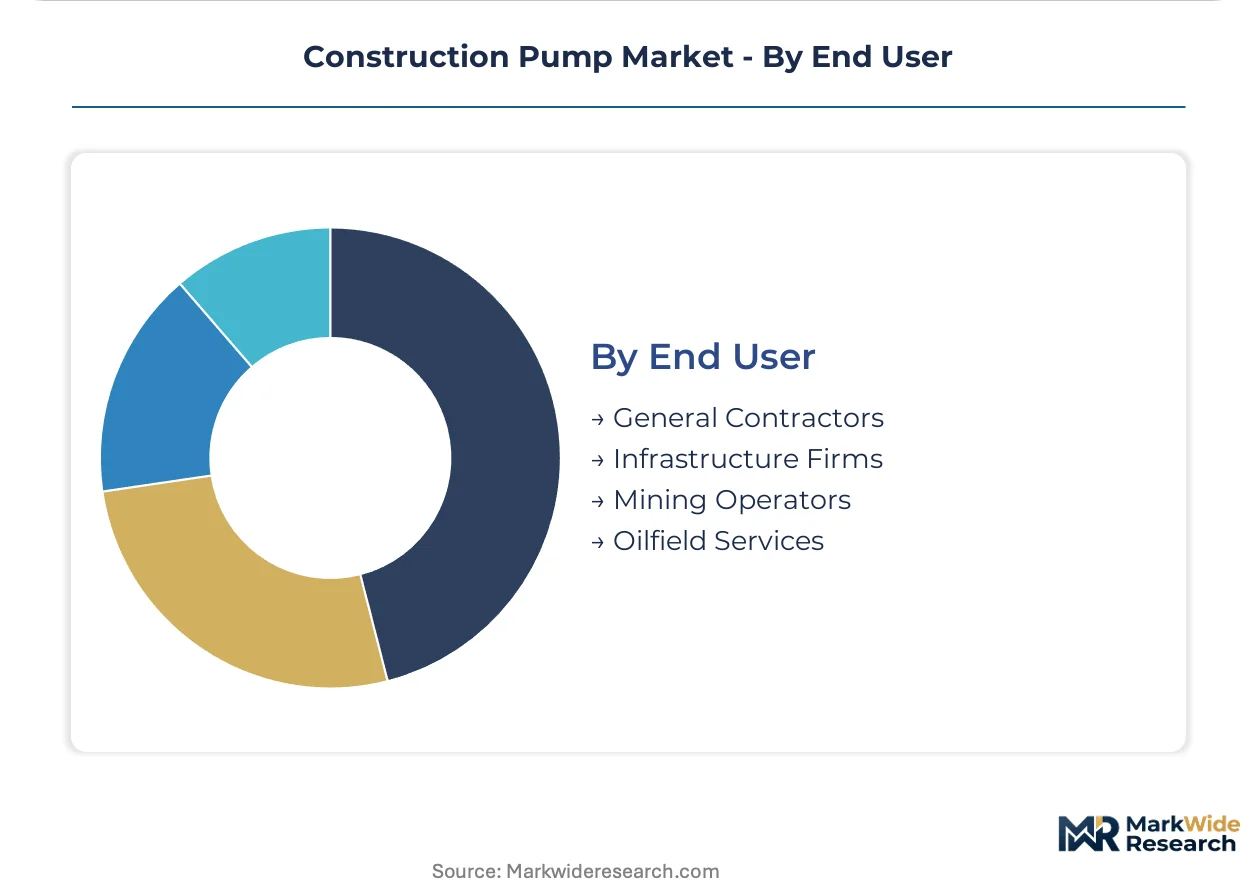
Maturity gradients separate consolidated infrastructure firms from fragmented general contracting. Mining operators and oilfield services exhibit procurement sophistication with lifecycle cost models. General contractors retain price-sensitive spot purchasing.
- Infrastructure Firms:State-backed and municipal-scale developers operate through framework agreements with embedded electrification mandates. These buyers recalibrate total cost of ownership models around energy and maintenance rather than upfront capital. Specification authority is migrating from project managers to procurement offices with sustainability scoring systems.
- Mining Operators:Surface and underground extraction companies demand slurry pumps with mean-time-between-failure metrics measured in thousands of hours. Australian and Chilean copper producers specify diaphragm configurations for tailings transfer with field service support from specialized distributors.
- General Contractors:Project-based builders source portable concrete and dewatering equipment through rental channels.
- Oilfield Services:Well stimulation and production support contractors specify high-pressure pumping packages.
By contract value, Infrastructure Firms lead. By replacement frequency, Mining Operators drive aftermarket volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure procurement offices concentrate purchasing authority across five national markets where state-backed urban renewal and emissions mandates reshape equipment specifications. Municipal-scale tenders now embed electrification requirements that filter vendor eligibility.
United States
EPA Tier 4 Final standards eliminate sub-fifty-horsepower diesel pumps from compact concrete categories. OSHA noise exposure limits force acoustic enclosure redesigns for urban job sites. Texas and California infrastructure authorities mandate electric dewatering systems for municipal core projects.
China
State-backed megacity water management schemes in Shanghai and Shenzhen drive slurry transfer capacity expansion. MEE discharge quality standards elevate closed-loop dewatering with integrated filtration. Yangtze River Delta manufacturing clusters supply permanent magnet motors for battery-electric pump architectures.
Germany
EU Stage V emissions regulations phase out compact diesel variants. Battery swap standardization across rental fleets in Bavaria and North Rhine-Westphalia compresses asset utilization metrics. Municipal procurement offices require ISO 14001-certified manufacturing with embedded carbon disclosures.
India
PLI scheme production-linked incentives attract domestic assembly investment for South Asian infrastructure tenders. BIS energy efficiency standards reshape specification sheets for dewatering equipment. Maharashtra and Gujarat industrial corridors concentrate manufacturing capacity for municipal-scale centrifugal systems.
Australia
Mining operators in Western Australia and Queensland specify diaphragm pumps for tailings transfer with mean-time-between-failure metrics measured in thousands of hours. Grid-deficient remote sites drive photovoltaic integration with autonomous dewatering systems. National renewable energy targets accelerate solar-powered deployment in Pilbara iron ore operations.
Construction Pump Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive pump divisions alongside specialized fluid-handling pure-plays. Consolidation pressure concentrates share among scale-driven manufacturers with backward integration into permanent magnet motors and specialty alloys. Two strategic archetypes dominate: integrated infrastructure technology providers with municipal framework agreements, and abrasive-duty specialists serving mining lifecycle contracts. Competitive moves center on battery-electric platform development and rental channel digitization through IoT-enabled fleet management.
Within the diversified industrial tier, Xylem and Grundfos occupy positions exemplifying vertical scope across dewatering and building services applications. KSB anchors the heavy-duty slurry segment with manufacturing scale that matches Australian and Chilean mining procurement frameworks. These three entities represent the archetype spectrum from municipal electrification mandates to abrasive-fluid lifecycle contracting.
| Leading Market Players |
|---|
| Xylem |
| Grundfos |
| KSB |
| Flowserve |
| Sulzer |
| ITT |
| Atlas Copco |
| Tsurumi Manufacturing |
| Ebara |
| Others |
Pricing and Supply Chain Analysis
Long-term municipal framework agreements with embedded electrification mandates lock in supply access for battery-electric pump architectures while anchoring price visibility across multi-year procurement cycles. China's permanent magnet motor clusters and German battery swap standardization create divergent cost structures that OEMs must navigate when bidding on state-backed infrastructure tenders.
Pricing Analysis
Cost-plus contracts with steel and rare-earth indexation dominate municipal procurement frameworks for centrifugal and diaphragm pump categories. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates infrastructure firms with ISO 14001 mandates from price-sensitive general contractors renting portable equipment. Pricing pressure stems from lithium-ion battery cost volatility and neodymium supply concentration, compressing margins on cordless concrete placement systems. Mining operators exhibit lowest price sensitivity due to lifecycle total cost of ownership models, while spot-rental general contractors drive aggressive rate negotiations.
Supply Chain Analysis
China anchors permanent magnet motor and specialty alloy production for electric pump drivetrains, while Germany and the United States concentrate precision casting and hydraulic component manufacturing. Supply chains draw from concentrated neodymium processing, high-grade stainless steel forging, and elastomeric membrane compounding. Single-source vulnerability in Chinese rare-earth refining creates exposure to export restriction shocks. Distribution runs through equipment rental networks with embedded service contracts for municipal-scale dewatering projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction pump markets sit in early-cycle expansion as site electrification infrastructure reaches cost-parity tipping points for urban concrete placement and dewatering operations.
For Market Incumbents: Consolidate manufacturing scale in permanent magnet motor supply chains through backward integration or captive offtake agreements with Yangtze River Delta suppliers. Deepen municipal framework positioning by pre-certifying electric architectures for China's MEE discharge standards and EU Stage V compliance, neutralizing emerging pure-play battery-electric entrants. For New Entrants and Emerging Players: UL and CE marking fast-tracks for cordless high-pressure concrete placement systems unlock first-mover positioning in mid-rise commercial segments excluded from incumbent diesel lock-in. White-space concentrates in Indian PLI scheme manufacturing zones and Australian solar-powered remote dewatering for Pilbara mining operations. Go-to-market should anchor on rental fleet digitization partnerships with predictive maintenance subscription bundling. For Investors and Strategic Acquirers: Capital is best deployed toward abrasive-duty diaphragm specialists with Australian and Chilean mining lifecycle contracts and proven mean-time-between-failure metrics. Long-term viability hinges on electrification technician training infrastructure and battery swap interoperability standard adoption. Signal to watch: municipal procurement offices embedding cordless concrete placement mandates in megacity water management tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Development | Shanghai and Shenzhen infrastructure authorities now mandate electric concrete placement within municipal core zones. |
| Backward Integration into Permanent Magnet Supply | Yangtze River Delta manufacturing clusters control neodymium processing for motor architectures. |
| Rental Channel Digitization | IoT-enabled fleet management platforms allow German lessors to capture predictive maintenance subscription revenue. |
| Solar-Powered Remote Deployment | Photovoltaic integration opens Australian Pilbara and Middle East oilfield dewatering for autonomous operation. |
| Certification Pre-Investment | ISO 14001 and embedded carbon disclosures displace price-per-horsepower evaluation in Denmark and Singapore tenders. |
Research Methodology
A spread of perspectives from municipal procurement officers, mining maintenance directors, rental fleet operators, and pump OEM product managers converged on the working assumptions driving electrification adoption curves. Primary fieldwork combined structured interviews with aftermarket service heads and plant engineers at infrastructure firms across China, Germany, and Australia, validated against secondary sources including EPA enforcement databases, EU ETS transaction registries, and Chinese MEE discharge compliance filings. Bottom-up unit economics for battery-electric versus diesel pump total cost of ownership triangulated against top-down infrastructure investment flow estimates.
Pump type, technology architecture, application segment, and end-user procurement sophistication shaped the analytical framework across the projection horizon. CAGRs derived from segment-level adoption curves weighted by municipal electrification mandate intensity and mining lifecycle contract renewal patterns. Industry-specific inputs included lithium-ion energy density improvement trajectories and rare-earth price index volatility bands.
Underlying assumptions cover battery cost decline continuity, regulatory enforcement persistence, and infrastructure stimulus allocation stability, with deviation risk concentrated in trade policy shifts affecting permanent magnet supply chains and technician training pipeline bottlenecks. Recalibration cycles align with material shifts in municipal procurement framework updates and battery swap standardization adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hybrid Excavator Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Dock Door Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Global Cut and Bend Equipment Market