
 Press Fit Machines Market | 2026-2036
Press Fit Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Press Fit Machines Market Analytics
German machine tool builders is pivoting toward servo-electric press fit platforms to capture demand from automotive electrification programs. Schuler Group leverages its stamping heritage to anchor high-tonnage electric press supply for European OEMs. AIDA sustains competitive positioning through R&D intensity in servo motor integration for precision assembly cells. Komatsu dominates Asian distribution channels for heavy-duty hydraulic press fit systems serving industrial manufacturing.
Press fit machines apply controlled axial force to mechanically join components without thermal processes, typically achieving interference fits with tolerances of 0.01-0.05 mm for bearing and pin assemblies. Electric press fit systems lead technology adoption due to energy recovery capabilities and programmable force-displacement curves that improve joint quality traceability. CNC technology commands premium positioning in aerospace and electronics verticals where multi-axis positioning and real-time feedback are mandatory. Hybrid mechanical-servo architectures represent the fastest-growing segment as manufacturers seek to bridge cost gaps between conventional hydraulic and full-electric platforms.
EU machinery safety directives enforced by national regulators in Germany and Italy mandate CE marking and ISO 12100 compliance for press equipment deployed in automated lines. China's SAMR enforces GB standards for industrial machinery safety that shape product certification requirements for equipment imports. Japan's METI promotes JIS-aligned energy efficiency benchmarks that accelerate servo technology substitution. Stakeholders must monitor evolving battery assembly specifications from automotive OEMs that redefine force and cleanliness requirements for press fit operations.
Market Dynamics
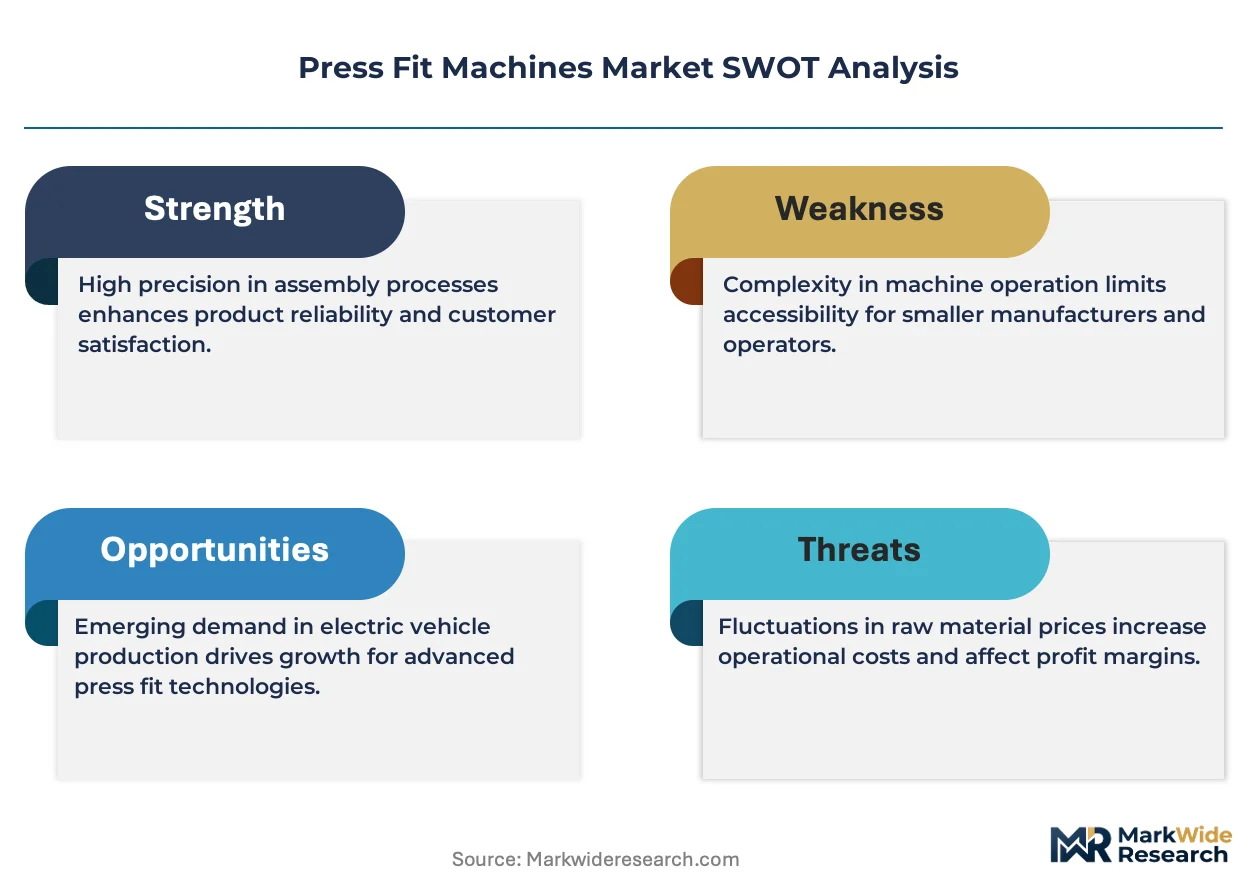
Servo-electric press fit technology is absorbing capital allocation from hydraulic systems as EU energy efficiency directives mandate measurable power consumption reductions across automated assembly lines.
Growth Catalysts
- EU Machinery Directives:CE marking and ISO 12100 compliance requirements under Germany's national enforcement framework compel automotive OEMs to upgrade legacy hydraulic presses with programmable force-displacement systems.
- Electric Powertrain Assembly:Battery pack manufacturing lines in Germany and Japan require precision interference fits for busbar and cell module joining, creating dedicated demand for CNC-controlled press platforms.
- China's Industrial Corridors:Domestic equipment makers in Yangtze River Delta and Pearl River Delta manufacturing clusters scale servo-electric capacity to serve precision metal joining for electronics and automotive suppliers.
Market Restraints
- Servo Motor Cost Volatility:Rare earth magnet supply concentration in Chinese processing facilities creates input cost instability for full-electric press system manufacturers.
- Technical Force Limitations:Electric drive architectures face tonnage ceilings above 500 kN that hydraulic systems still dominate for heavy-duty industrial forging applications.
- Regulatory Certification Friction:Divergent GB standards enforcement by China's SAMR versus EU CE marking requirements force dual certification investments for equipment exporters.
Strategic Opportunities
- Hybrid Architecture Adoption:Mechanical-servo press combinations bridge cost-performance gaps for mid-tier manufacturers transitioning from hydraulic infrastructure.
- Aerospace Precision Demand:Multi-axis CNC press fit systems with real-time feedback capture premium positioning in airframe fastener and bearing assembly applications.
- India's PLI Scheme:Production-linked incentives for automotive component manufacturing attract press fit equipment deployment to emerging assembly corridors near Chennai and Pune.
Industry Challenges
- Servo Control Engineering Talent:Shortage of programmers capable of optimizing force-displacement curves for varied interference fit specifications constrains system integrator capacity.
- Legacy Hydraulic Integration:Retrofitting existing press lines with electric drives requires custom mechanical interface engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Press Fit Machines Market |
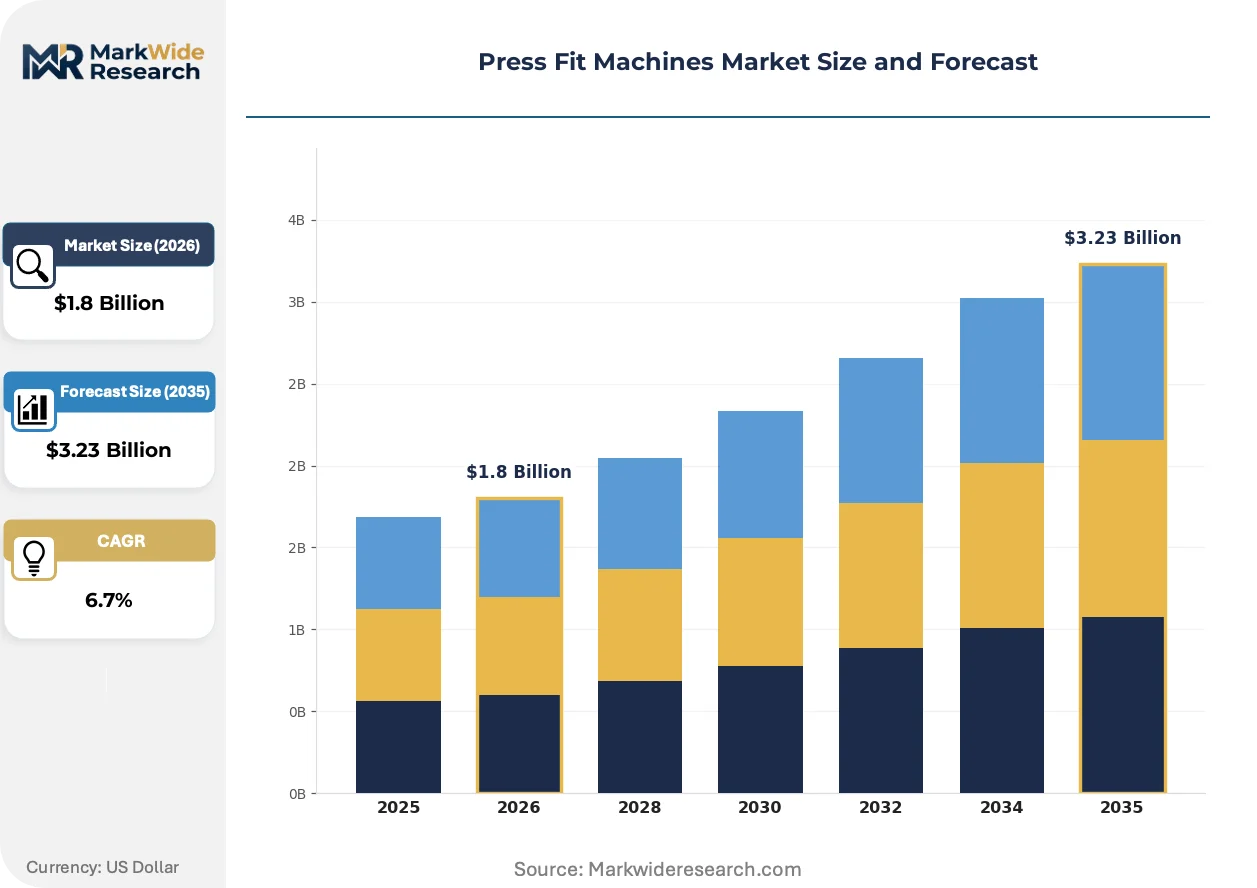
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Press Fit, Hydraulic Press Fit, Pneumatic Press Fit, Electric Press Fit Industry Vertical: Automotive, Electronics, Aerospace, Industrial Manufacturing Application: Assembly, Fabrication, Installation, Maintenance Technology: Mechanical, Servo, CNC, Hybrid |
| Companies Covered | Schuler Group, AIDA, Komatsu, Stamtec, Amada Press System, Nidec Minster, SMS Group, Macrodyne Technologies, Bruderer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Press Fit Machines Market Evolving Landscape
Active force monitoring and energy recovery systems are redefining quality assurance protocols in precision assembly, compressing the performance gap between premium electric platforms and conventional mechanical alternatives.
Servo-electric press architecture is absorbing R&D investment from equipment manufacturers seeking programmable process control. Automotive battery assembly lines in Germany and Japan deploy these systems for traceable joint formation. The technology is absorbing market share from hydraulic alternatives by enabling real-time force-displacement logging that satisfies OEM quality audit requirements.
REACH chemical restrictions and EU F-Gas Regulation are phasing out hydraulic fluids with high environmental impact quotients in European manufacturing facilities. Industrial press operators face mandatory fluid substitution timelines that accelerate electric platform evaluation. German automotive tier suppliers are responding with capital allocation shifts toward servo-electric procurement specifications.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Aerospace and electronics manufacturers now source force monitoring software and predictive maintenance analytics from specialized third-party providers rather than bundled OEM contracts. This pattern is most visible in Japan's precision equipment user base, where METI energy efficiency benchmarking drives independent performance verification demands.
Press Fit Machines Market Segmentation
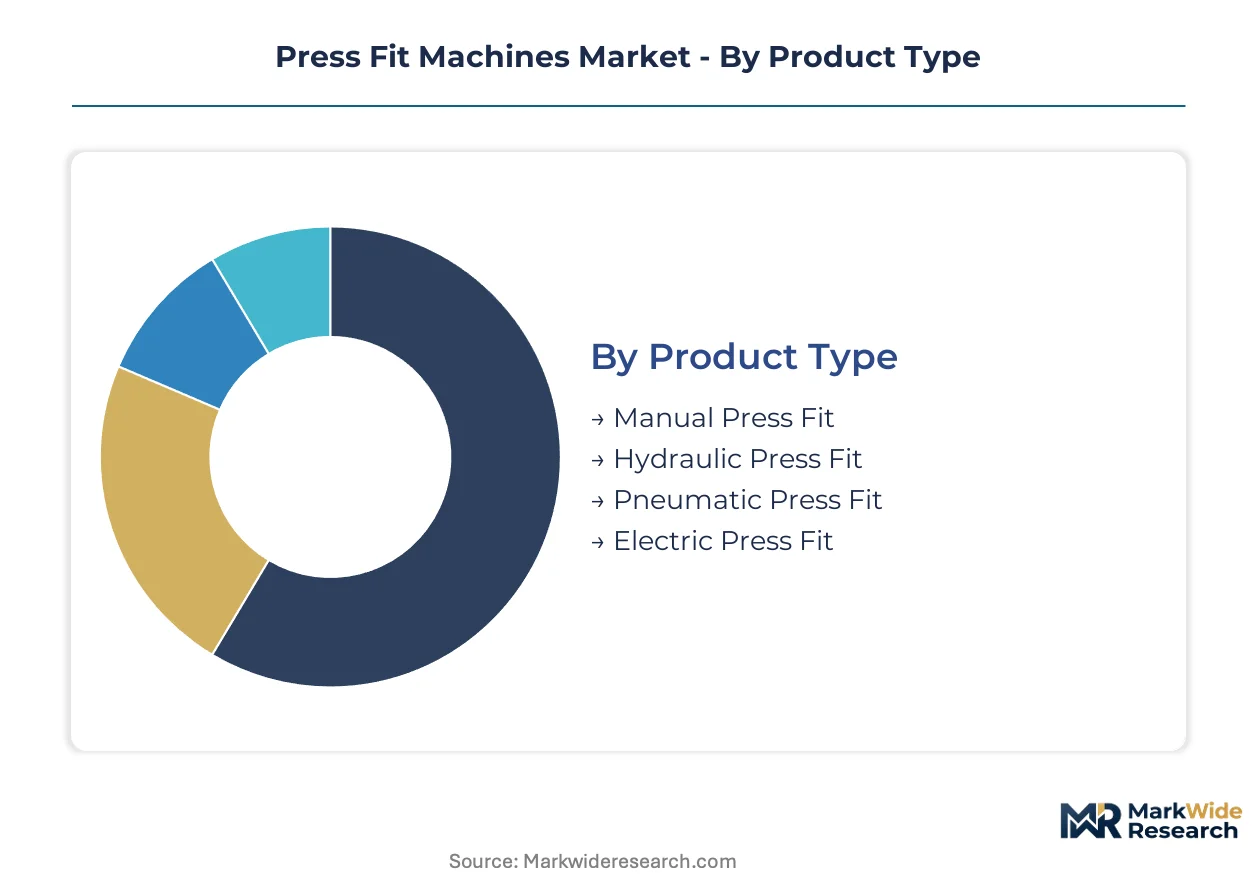
Press fit machine procurement decisions hinge on force precision requirements, energy compliance mandates, and joint traceability standards that vary sharply across manufacturing verticals. Segmentation reveals where certification burdens concentrate and which technology platforms capture capital allocation from automotive electrification and aerospace precision programs.
Product Type:
CE marking under EU machinery directives and ISO 12100 compliance requirements apply differentially across product categories, with full-electric systems facing the most stringent energy efficiency verification protocols.
- Electric Press Fit:Servo motor architectures deliver programmable force-displacement curves with real-time feedback logging. Battery assembly lines in Germany and Japan specify these systems for busbar joining where joint traceability satisfies OEM audit requirements.
- Hydraulic Press Fit:Fluid power systems dominate applications above 500 kN where electric drives face technical force ceilings. REACH chemical restrictions and EU F-Gas Regulation are phasing out high-impact hydraulic fluids, accelerating platform substitution timelines in European facilities.
- Pneumatic Press Fit:Compressed air systems serve cost-sensitive mid-tier manufacturers with lower precision requirements.
- Manual Press Fit:Operator-actuated equipment persists in maintenance operations and low-volume fabrication shops.
Electric press fit sits at the top of the volume ranking, with hybrid architectures climbing the fastest as manufacturers bridge cost gaps from legacy hydraulic infrastructure.
Industry Vertical:
End-use concentration determines margin structure, with aerospace and electronics commanding premium positioning while automotive electrification programs drive volume scaling.
- Automotive:Electric powertrain assembly lines in Germany and Japan require precision interference fits for cell module and busbar joining. OEM procurement specifications now mandate programmable force-displacement logging that disqualifies conventional mechanical platforms.
- Aerospace:Multi-axis CNC press fit systems with active force monitoring capture premium positioning for airframe fastener and bearing assemblies where real-time feedback is mandatory.
- Electronics:Miniaturized component joining demands sub-0.01 mm tolerance control in precision assembly cells.
- Industrial Manufacturing:Heavy-duty forging applications sustain demand for high-tonnage hydraulic systems.
Automotive anchors absolute revenue concentration, with aerospace expanding most quickly on precision certification requirements.
Application:
Process stage determines system specification complexity, with assembly operations requiring the most sophisticated force monitoring capabilities.
- Assembly:Automated production lines deploy servo-electric and CNC platforms for traceable joint formation. China's Yangtze River Delta and Pearl River Delta manufacturing clusters scale capacity for precision metal joining in electronics and automotive supplier operations.
- Fabrication:Component forming operations utilize hybrid mechanical-servo architectures to balance cost and performance.
- Installation:Field deployment scenarios favor portable pneumatic and manual systems.
- Maintenance:Repair operations sustain demand for versatile equipment across all technology platforms.
Assembly commands the largest equipment deployment base, with fabrication gaining share fastest on hybrid technology adoption.
Technology:
Architecture selection determines energy recovery potential, programming flexibility, and compliance with evolving efficiency mandates from Japan's METI and EU regulatory frameworks.
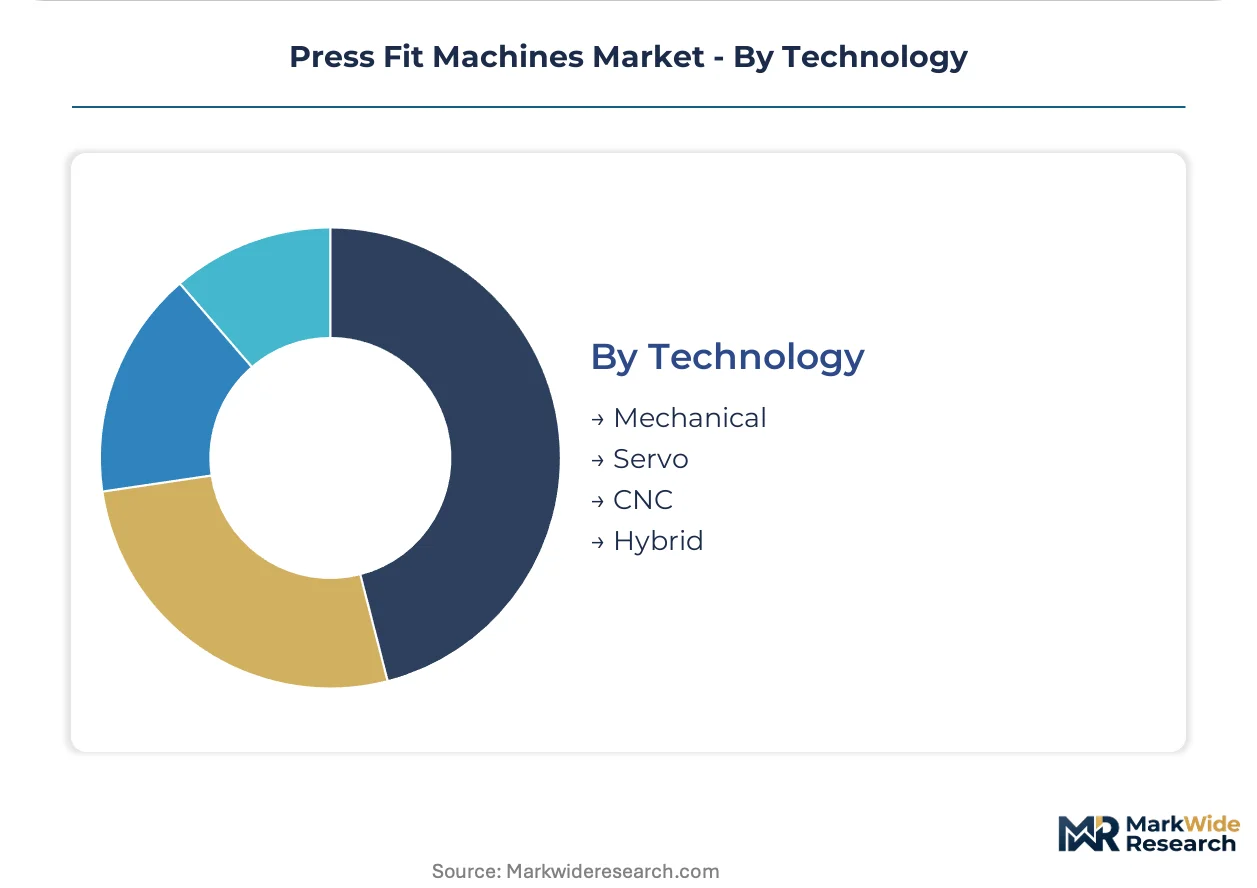
- Servo:Full-electric systems with regenerative drives absorb R&D investment from equipment manufacturers seeking programmable process control. METI-aligned energy efficiency benchmarks accelerate substitution for hydraulic alternatives.
- CNC:Computer numerical control platforms with multi-axis positioning serve aerospace and electronics verticals where real-time feedback is mandatory.
- Hybrid:Mechanical-servo combinations bridge cost-performance gaps for mid-tier manufacturers transitioning from hydraulic infrastructure.
- Mechanical:Conventional architectures persist in cost-sensitive applications with lower precision requirements.
Servo technology leads absolute deployment, with hybrid systems showing the steepest expansion trajectory on capital efficiency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the premium electric press fit segment while China's domestic fabricators scale capacity for mid-tier precision joining, revealing a bifurcated geography where regulatory stringency and manufacturing scale pull demand in different directions.
Germany
Automotive electrification programs from BMW and Volkswagen drive specification upgrades for battery module assembly lines. The KBA enforces machinery safety compliance that accelerates CE-marked servo-electric procurement. Stuttgart and Munich industrial corridors host tier-one suppliers retrofitting hydraulic press lines with programmable force-displacement systems.
China
Domestic equipment makers in the Yangtze River Delta and Pearl River Delta manufacturing clusters expand servo-electric production for electronics and automotive component joining. SAMR enforces GB standards for industrial machinery safety that shape import certification requirements. Shenzhen and Suzhou precision metalworking hubs absorb capacity from local press fit machine builders.
Japan
Electric powertrain assembly investments from Toyota and Honda sustain demand for CNC-controlled press platforms with real-time feedback logging. METI promotes JIS-aligned energy efficiency benchmarks that accelerate hydraulic-to-electric technology substitution. Nagoya and Osaka industrial zones concentrate battery cell module joining operations for export markets.
United States
Aerospace manufacturers in the Pacific Northwest and Southeast specify multi-axis CNC press fit systems for airframe fastener assemblies. OSHA machinery safety requirements intersect with FAA quality traceability mandates for defense contractor supply chains. Boeing suppliers in Washington State and Alabama anchor precision assembly equipment procurement.
India
Production-linked incentives under the PLI scheme attract automotive component manufacturers to emerging assembly corridors near Chennai and Pune. BIS certification requirements for industrial machinery create compliance entry barriers for equipment imports. Tamil Nadu and Maharashtra industrial zones scale press fit deployment for domestic EV supply chain localization.
Press Fit Machines Market Competitive Landscape
German and Japanese producers anchor the premium technology tier; Chinese fabricators hold volume positions in cost-optimized segments. The vendor base clusters around three strategic archetypes: heritage stamping equipment builders pivoting to servo-electric architectures, hydraulic system specialists defending heavy-tonnage applications, and precision automation integrators capturing aerospace and electronics verticals. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into hybrid mechanical-servo platforms.
Within the heritage equipment tier, Schuler Group and AIDA exemplify the transition from mechanical stamping heritage toward programmable electric press systems. Komatsu occupies a position among heavy-duty hydraulic specialists serving industrial forging applications above electric force ceilings. These three anchors represent distinct competitive vectors: European premium electric, Japanese precision automation, and Asian heavy-tonnage fluid power.
| Leading Market Players |
|---|
| Schuler Group |
| AIDA |
| Komatsu |
| Stamtec |
| Amada Press System |
| Nidec Minster |
| SMS Group |
| Macrodyne Technologies |
| Bruderer |
| Others |
Value Network & Pricing Analysis
Servo-electric press fit technology migration simultaneously compresses energy operating costs and concentrates procurement leverage among buyers with scale to justify programmable force-displacement systems. EU energy efficiency directives and Japan's METI benchmarks reshape supplier cost structures while rewarding early technology adopters with audit-compliant joint traceability.
Pricing Analysis
Capacity additions in China's Yangtze River Delta and Pearl River Delta manufacturing clusters are reshaping price floors for mid-tier servo-electric press fit equipment. Three-tier pricing structure across premium CNC-controlled, standard programmable electric, and economy hydraulic platforms differentiates on certification grade and real-time feedback capability. Cost compression in standard electric tiers is intensifying because domestic Chinese fabricators scale servo motor integration capacity. Automotive tier suppliers in Germany exhibit lowest price sensitivity due to OEM mandate compliance requirements, while mid-tier industrial manufacturers in India show highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive electrification programs, while distributor networks serve fragmented maintenance and fabrication end-users across industrial manufacturing. Manufacturing concentrates in Germany for premium electric platforms, Japan for precision CNC systems, and China for cost-optimized servo architectures. Rare earth magnet processing for servo motors draws from Chinese refining facilities, precision ball screws from Japan and Taiwan, and high-grade steel forgings from German and Austrian mills. Single-source vulnerability in rare earth magnet supply creates structural risk for full-electric press system manufacturers. Distribution runs through authorized integrators for complex CNC deployments and direct procurement for high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The press fit machines market functions as a regulatory compounder where EU machinery safety directives and Japan's METI energy efficiency benchmarks continuously elevate compliance thresholds that disqualify legacy hydraulic platforms from qualified supplier lists.
For Market Incumbents: Deepen servo control engineering talent pools through targeted acquisition of motion control specialists in Germany and Japan to offset programmer shortages constraining system integrator capacity. Expand captive production of precision force sensors and linear encoders to reduce exposure to single-source component vulnerabilities from Asian electronics suppliers. Fortify aftermarket service revenue through unbundled predictive maintenance analytics contracts that aerospace and electronics manufacturers increasingly prefer over bundled OEM agreements.
For New Entrants and Emerging Players: Capture hybrid mechanical-servo architecture demand from mid-tier manufacturers in India's PLI-subsidized automotive corridors near Chennai and Pune, where capital constraints delay full-electric transitions. Target precision electronics assembly applications in China's Shenzhen and Suzhou hubs with sub-0.01 mm tolerance positioning systems that domestic equipment makers have not yet scaled. Deploy direct sales teams with force-displacement curve optimization expertise rather than competing through distributor price competition.
For Investors and Strategic Acquirers: Valuations sit cheapest among hydraulic system specialists defending heavy-tonnage industrial forging applications above electric force ceilings, where technology substitution risk is mispriced. Long-term viability over the next decade hinges on successful servo-electric platform transitions or niche dominance in forging applications where electric architectures face persistent technical barriers. Monitor battery assembly specification releases from European and Japanese automotive OEMs as the critical inflection signal for force and cleanliness requirement escalations that reshape equipment qualification standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Development | Programmable force-displacement curves satisfy EU energy efficiency directives and OEM audit requirements. |
| Hybrid Architecture Launch | Mechanical-servo combinations bridge cost gaps for mid-tier manufacturers transitioning from hydraulic infrastructure. |
| Backward Integration into Force Sensing | In-house production of precision sensors reduces single-source vulnerability from Asian electronics suppliers. |
| Predictive Maintenance Analytics Unbundling | Independent software contracts capture aerospace and electronics manufacturers seeking METI-aligned performance verification. |
| Geographic Expansion to India PLI Corridors | Production-linked incentives attract automotive component manufacturers to emerging assembly zones near Chennai and Pune. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and servo control programmers grounded qualitative findings in operational realities of press fit equipment deployment. Secondary validation drew from SEC filings of listed machinery manufacturers, German KBA machinery safety enforcement records, Japan's METI energy efficiency benchmarking reports, and Chinese SAMR GB standards documentation. Bottom-up equipment shipment tracking and top-down automotive and aerospace capital expenditure analysis provided triangulation across data sources.
Bottom-up modeling aggregated segment-level equipment shipments by technology architecture, force rating tier, and end-use vertical across the projection horizon. Segmentation dimensions included product type, industry vertical, application stage, and technology platform, with additional granularity on certification tier and regional regulatory cluster. CAGRs derived from regression analysis of historical capital expenditure patterns and forward-looking OEM electrification program disclosures. Forecast inputs incorporated battery assembly line deployment timelines from German and Japanese automotive manufacturers and REACH chemical restriction phase-out schedules affecting hydraulic fluid substitution.
Underlying measurement precision varies by segment; electric press fit and CNC-controlled platforms carry tighter precision than manual and pneumatic equipment due to structured procurement reporting from large automotive and aerospace buyers. Forecasts reflect assumptions regarding technology substitution rates, regulatory enforcement intensity, and rare earth magnet supply stability that warrant periodic reassessment. Periodic stress-testing of base assumptions against actual OEM qualification specification releases and SAMR enforcement patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Crane Rail Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Mortar Testing Equipment Market