
 Electric Hot Chamber Die Casting Machines Market | 2026-2036
Electric Hot Chamber Die Casting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Hot Chamber Die Casting Machines Market Insights
Direct sales from European equipment builders to Asian foundries is tilting toward localized service partnerships. Buhler AG leverages its Swiss engineering heritage to sustain premium positioning in high-pressure systems. Oskar Frech GmbH anchors German precision standards across vacuum-casting installations. Yizumi Precision Machinery competes aggressively on automation-integrated control systems for Chinese domestic buyers.
Electric hot chamber die casting machines inject molten zinc, magnesium, or lead alloys into hardened steel dies at clamping forces ranging from 50 to 1,000 metric tons, producing near-net-shape components for mass production. The equipment eliminates external melting furnaces by submerging the injection mechanism directly within the alloy bath, reducing thermal loss and cycle times. High-pressure product types dominate volume shipments to automotive structural parts applications, while vacuum technology commands margin pools in aerospace-grade electrical housings. Sensor integration and automation technologies attract replacement demand as foundries modernize legacy mechanical control systems.
EPA emissions standards in the United States restrict volatile compound release from molten metal baths, compelling foundries to upgrade sealed-chamber designs. REACH and RoHS frameworks in Europe limit cadmium and lead content in cast alloys, reshaping material specifications for consumer goods producers. ISO quality certifications govern machine safety and repeatability benchmarks across export markets. Stakeholders must monitor how dual carbon goals in China and evolving EU machinery directives recalibrate capital equipment procurement criteria.
Market Dynamics
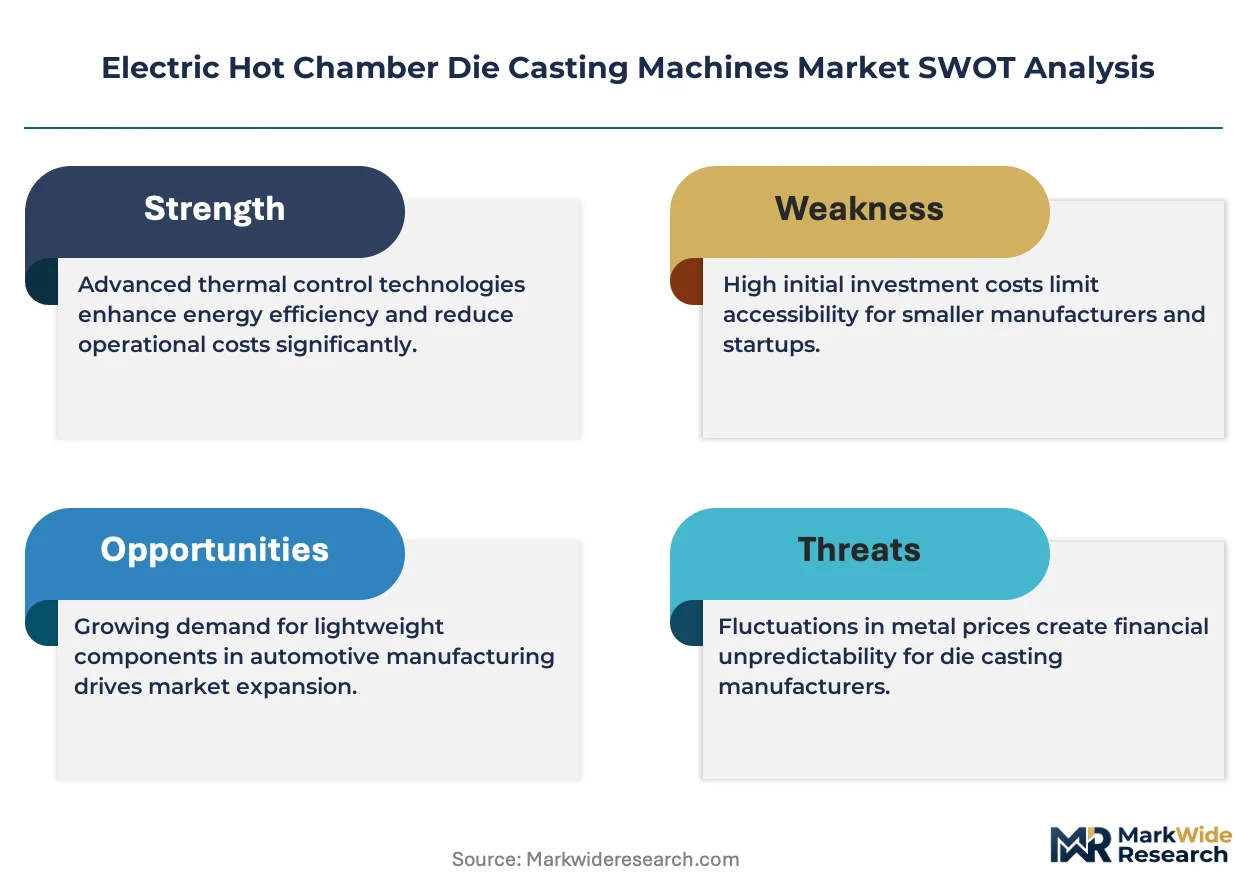
EPA emissions standards and China's dual carbon goals are forcing foundries to retire mechanical-control machines in favor of sealed-chamber electric systems, compressing replacement cycles from fifteen years toward seven.
Growth Catalysts
- Automotive structural parts demand:OEMs in China and Vietnam require high-pressure zinc and magnesium castings for lightweight engine housings as fuel-efficiency mandates tighten.
- REACH alloy restrictions:European consumer goods manufacturers are eliminating cadmium and lead from cast alloys, accelerating vacuum-casting upgrades to maintain export certification.
- Sensor-integrated automation:Real-time thermal monitoring and predictive maintenance modules are cutting cycle times and scrap rates in mass-production environments.
Market Restraints
- Copper and steel input volatility:Hardened die materials and electrical components face commodity price swings that compress equipment margins.
- German-Swiss supply concentration:Premium high-pressure system engineering remains concentrated among Central European builders, creating procurement bottlenecks for Asian foundries.
- Mechanical control obsolescence:Legacy hydraulic systems in installed bases lack retrofit pathways to sealed-chamber EPA compliance, stranding capital.
Strategic Opportunities
- Indian domestic manufacturing:PLI scheme incentives for automotive component production are creating first-time demand for automated hot-chamber systems in Pune and Chennai clusters.
- Aerospace electrical housings:Vacuum-casting technology is penetrating aviation connector and avionics enclosure applications previously served by machined aluminum.
- EU Green Deal machinery directives:Energy-efficiency benchmarking and circular-economy requirements are favoring electric over hydraulic drive systems in procurement specifications.
Industry Challenges
- Control systems integration:Foundry engineers face skill gaps merging legacy mechanical workflows with automation-integrated electric platforms.
- ISO safety certification timelines:Repeatability and interlock testing for export markets extends delivery schedules by four to six months.
- Aftermarket service localization:European equipment builders struggle to deploy qualified technicians across dispersed Asian foundry clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Hot Chamber Die Casting Machines Market |
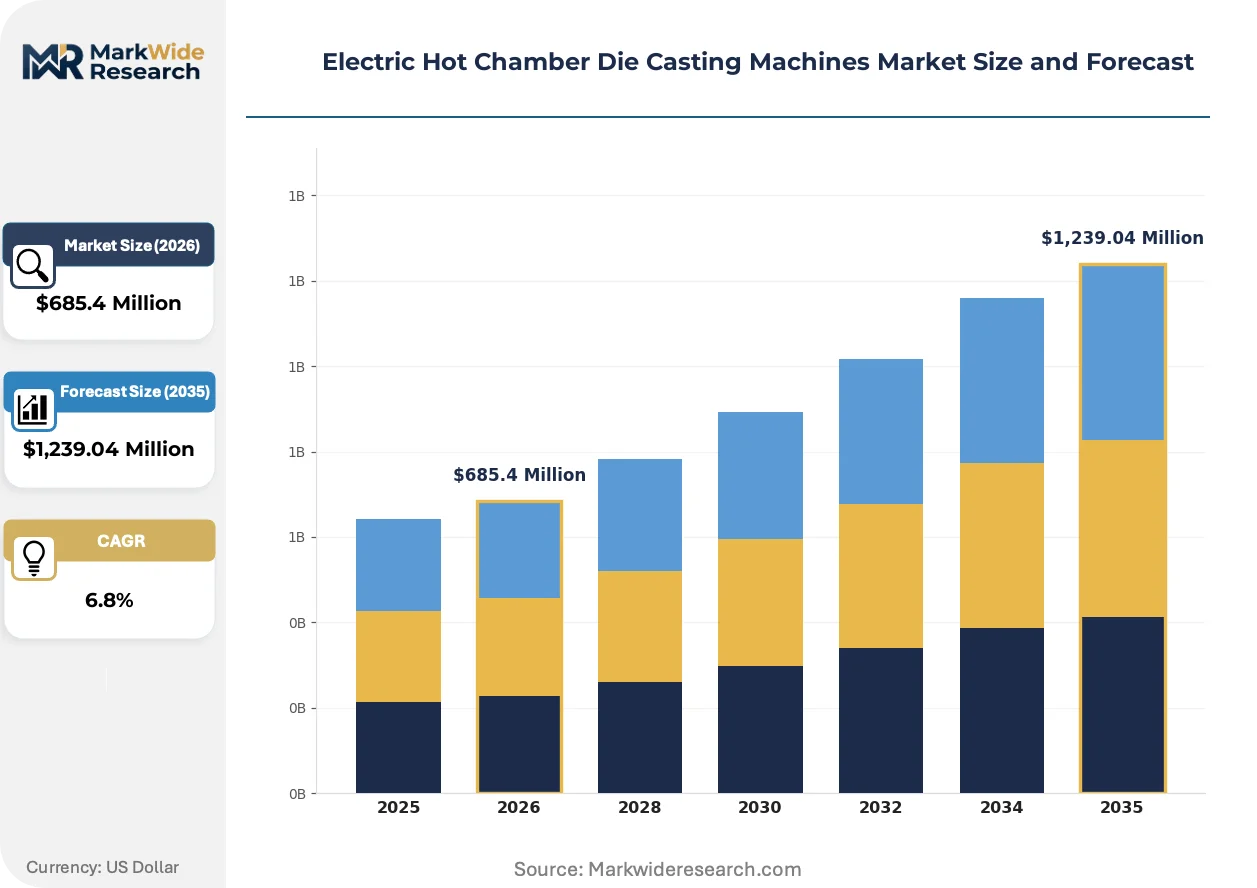
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Pressure, High Pressure, Vacuum, Gravity End User: Automotive, Aerospace, Electronics, Consumer Goods Application: Engine Components, Structural Parts, Decorative Items, Electrical Housings Technology: Heat Exchanger, Sensor Integration, Automation, Control Systems |
| Companies Covered | Buhler AG, Oskar Frech GmbH, UBE Machinery Inc., Toshiba Machine Co., Ltd., Yizumi Precision Machinery Co. Ltd., Shibaura Machine, Suzhou Sanji Die-Casting Automation System Co., Idra Group, L.K. Technology Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Hot Chamber Die Casting Machines Market Trends and Innovations
Automation convergence and regulatory sealing requirements are collapsing the traditional separation between melting, injection, and quality-control functions in die-casting operations.
Servo-electric injection systems are collapsing hydraulic actuator dominance in clamping force ranges below 400 metric tons. Automotive tier-one suppliers in Germany and Japan are adopting these platforms for zinc consumer-electronics chassis production. The technology is collapsing maintenance intervals and energy consumption benchmarks that previously favored mechanical-hydraulic hybrids.
EPA volatile-compound restrictions are mandating sealed-chamber designs that eliminate external furnace exposure. US foundries serving plumbing and hardware markets are retrofitting bath-submerged injection mechanisms to maintain operating permits. The rule is compressing equipment replacement decisions as grandfathered mechanical systems lose compliance eligibility.
Buyer concentration among Chinese automotive OEMs is forcing European equipment builders to unbundle premium engineering from localized service contracts. Foundry procurement teams in Guangdong and Zhejiang now demand Mandarin-language automation interfaces and domestic spare-part inventories. The shift is visible most acutely in high-volume engine-component contracts where Swiss and German suppliers must partner with Chinese system integrators to maintain account access.
Electric Hot Chamber Die Casting Machines Market Segmentation
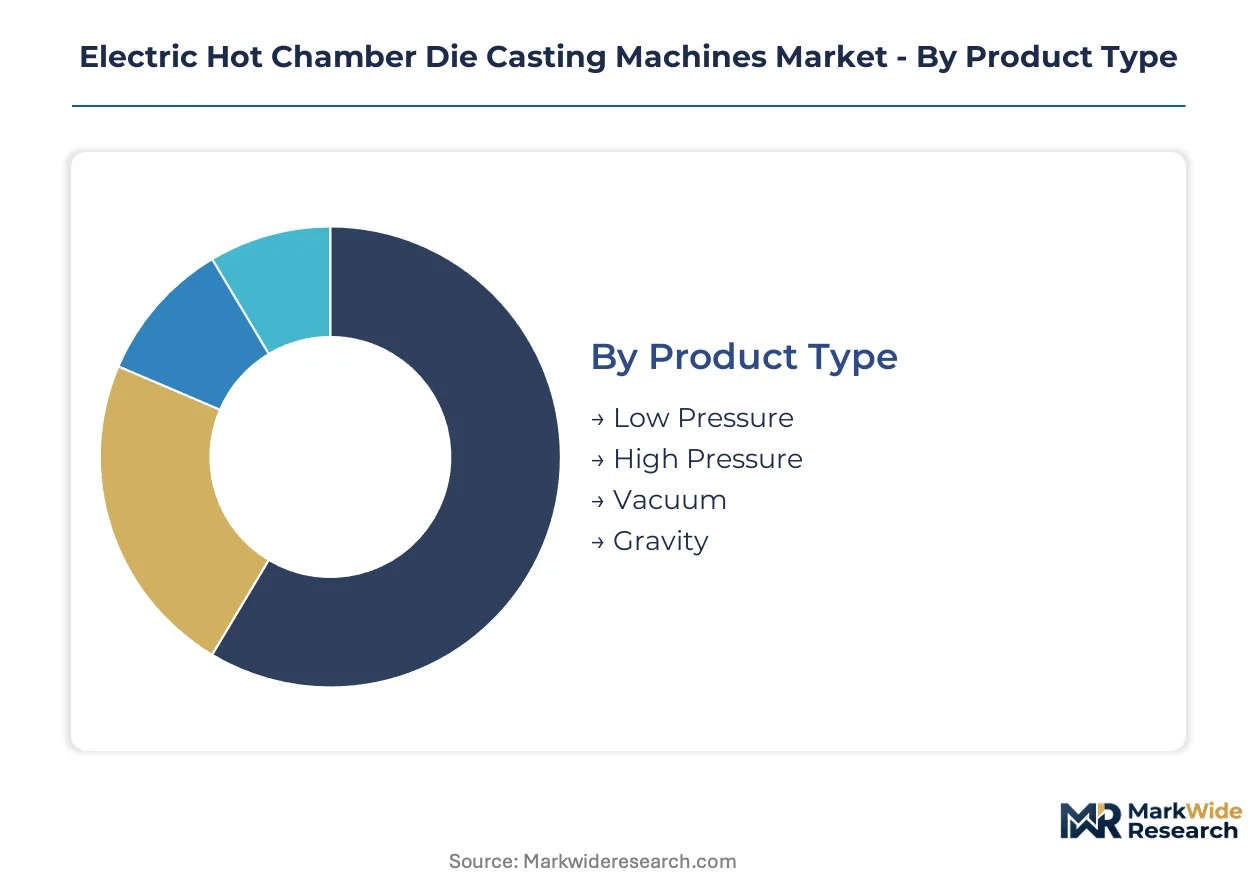
Electric hot chamber die casting machines serve distinct operational profiles across pressure regimes, end-use industries, and automation tiers. Cycle-time requirements and alloy compatibility vary sharply between automotive mass production and aerospace precision runs, forcing suppliers to engineer modular platforms rather than universal systems.
Product Type:
Cycle times compress most dramatically in high-pressure zinc casting for automotive structural parts, while vacuum systems extend production windows to achieve aerospace-grade porosity standards. Low-pressure and gravity configurations occupy intermediate positions on the speed-precision spectrum.
- High Pressure:Clamping forces between 200 and 1,000 metric tons inject molten zinc or magnesium at velocities exceeding 50 meters per second. Chinese automotive OEMs in Guangdong and Zhejiang provinces concentrate procurement for engine housing production as domestic fuel-efficiency mandates tighten. Equipment replacement cycles here compress toward seven years under EPA sealed-chamber compliance deadlines.
- Vacuum:Chamber evacuation before injection eliminates gas porosity in thin-wall aerospace electrical housings and medical device enclosures. European avionics suppliers in Germany and France drive specification upgrades as REACH cadmium restrictions reshape alloy portfolios. The technology commands premium margins but extends cycle times by 40-60 percent versus atmospheric methods.
- Low Pressure:Controlled metal rise from pressurized crucibles suits thicker-section automotive components where internal integrity outweighs surface finish requirements.
- Gravity:Unpressurized pour systems serve decorative hardware and plumbing fixture foundries with minimal automation integration.
High Pressure anchors the volume base while Vacuum gains share at the steepest rate.
End User:
Cost tiers separate capital-intensive automotive procurement from electronics and consumer goods segments where equipment utilization rates drive purchasing decisions.
- Automotive:Tier-one suppliers deploy 24/7 production schedules requiring predictive maintenance modules and Mandarin-language control interfaces. Indian PLI scheme incentives are creating first-time demand clusters in Pune and Chennai as domestic component manufacturing expands.
- Electronics:Zinc alloy chassis for consumer devices demand rapid die changeover and sub-30-second cycle times. Japanese and Korean contract manufacturers prioritize servo-electric injection systems below 400 metric tons for smartphone and laptop housing production.
- Aerospace:Avionics enclosure specifications require vacuum-casting certification and ISO repeatability documentation extending delivery timelines.
- Consumer Goods:Plumbing hardware and decorative fixture foundries operate legacy mechanical systems facing EPA emissions compliance deadlines.
Automotive dominates capital deployment while Electronics expands most quickly on automation-integrated replacement demand.
Application:
Volume concentration in engine components contrasts with margin structure in electrical housings where material purity certifications command pricing power.
- Engine Components:Cylinder heads, transmission housings, and oil pans require high-pressure magnesium casting with real-time thermal monitoring. Vietnamese foundries serving Japanese OEM transplant operations are upgrading from hydraulic to sealed-chamber electric systems.
- Electrical Housings:Connector bodies and avionics enclosures demand vacuum-cast aluminum-zinc alloys with RoHS-compliant chemistry. German aerospace suppliers specify electromagnetic shielding performance driving alloy innovation.
- Structural Parts:Door frames and seat brackets prioritize crashworthiness over cosmetic finish in automotive safety cell assemblies.
- Decorative Items:Faucet handles and hardware trim emphasize surface quality achievable through gravity or low-pressure methods.
Engine Components anchors the volume base while Electrical Housings climbs the fastest on aerospace certification requirements.
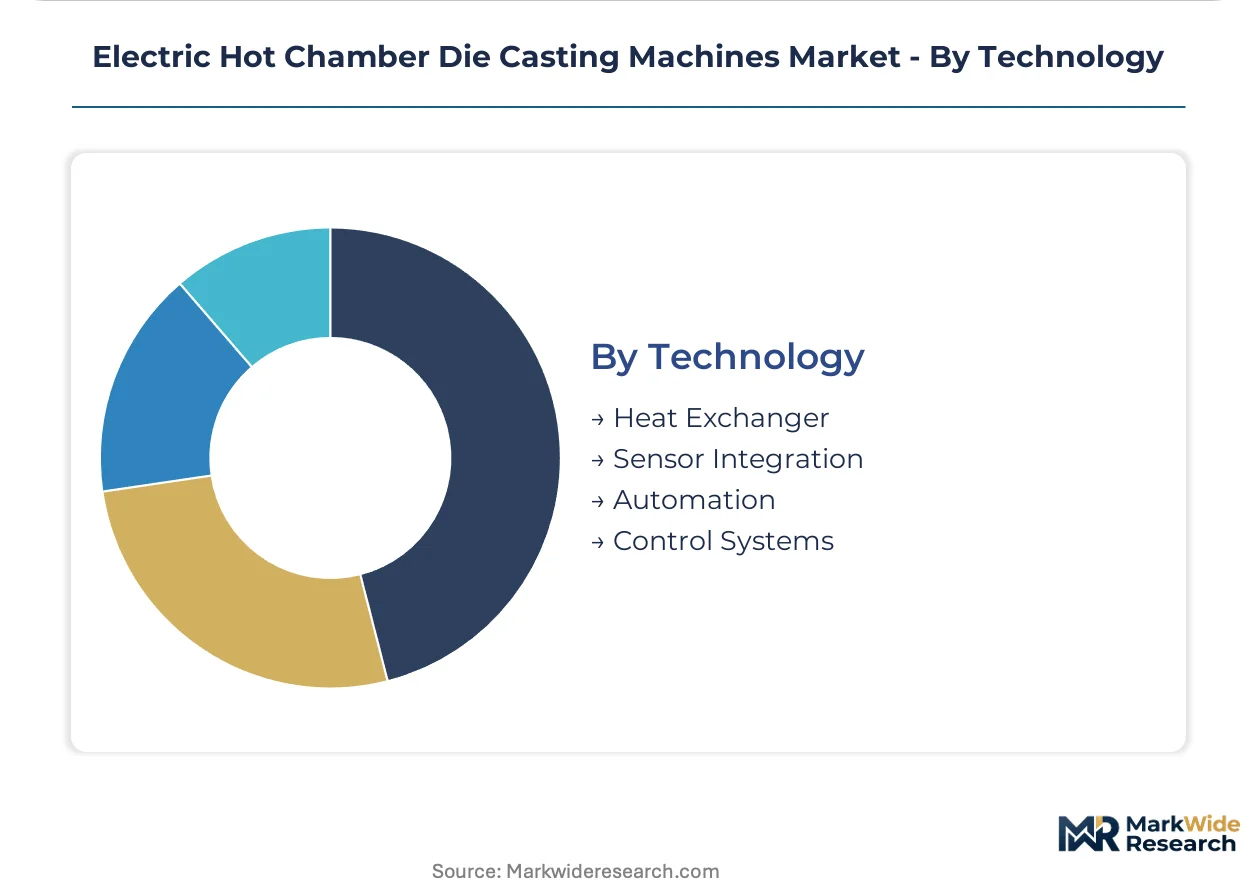
Technology:
Supply concentration in control systems integration creates bottlenecks as foundries merge legacy mechanical workflows with automation platforms.
- Sensor Integration:Real-time bath temperature, injection velocity, and die thermal mapping enable predictive maintenance and scrap reduction. Chinese domestic equipment builders compete aggressively on integrated sensor packages against European premium positioning.
- Automation:Robotic die spraying, part extraction, and quality inspection collapse labor content in high-volume operations. German automotive tier-one suppliers specify fully automated cells for zinc electronics chassis production.
- Control Systems:PLC and servo-electric architectures replace hydraulic actuators in clamping force ranges below 400 metric tons.
- Heat Exchanger:Thermal management subsystems maintain alloy bath stability within ±2°C for repeatability certification.
Sensor Integration anchors the volume base while Automation gains share at the steepest rate on foundry labor cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium Swiss and German engineering commands pricing power that Chinese domestic manufacturers undercut by 30-40 percent on comparable tonnage ratings. Foundry procurement teams in Asia-Pacific balance total cost of ownership against sealed-chamber compliance mandates.
China
Guangdong and Zhejiang automotive OEMs concentrate high-pressure equipment procurement for engine housing production as domestic fuel-efficiency mandates tighten. MEE enforcement of dual carbon goals accelerates retirement of mechanical-control systems toward seven-year replacement cycles. Foundry clusters in Shenzhen and Ningbo demand Mandarin-language automation interfaces and domestic spare-part inventories.
Germany
REACH cadmium and lead restrictions reshape alloy specifications for consumer goods exporters serving European markets. Tier-one automotive suppliers in Bavaria and Baden-Württemberg specify fully automated cells for zinc electronics chassis production. Stuttgart and Munich engineering centers anchor vacuum-casting certification for aerospace electrical housing contracts.
United States
EPA volatile-compound emissions rules compress equipment replacement decisions as grandfathered mechanical systems lose operating permits. Plumbing and hardware foundries in Ohio and Michigan retrofit bath-submerged injection mechanisms to maintain compliance eligibility. Detroit-area automotive suppliers integrate predictive maintenance modules for 24/7 structural parts production.
India
PLI scheme incentives for automotive component manufacturing create first-time demand clusters in Pune and Chennai. BIS quality certifications govern machine safety benchmarks for export-oriented foundries. Domestic OEMs in Maharashtra and Tamil Nadu upgrade from hydraulic to sealed-chamber electric systems for lightweight engine component programs.
Vietnam
Japanese OEM transplant operations in northern industrial zones drive high-pressure magnesium casting demand for transmission housings. Foundries in Hai Phong and Bac Ninh provinces modernize legacy mechanical controls to meet customer ISO repeatability requirements. Supply chain localization mandates accelerate procurement of automation-integrated platforms from regional distributors.
Electric Hot Chamber Die Casting Machines Market Competitive Landscape
Swiss-German precision engineering specialists and Chinese automation-integrated manufacturers split the market along premium-versus-scale fault lines. Central European builders concentrate high-pressure system engineering above 400 metric tons, while Asian competitors dominate servo-electric ranges below that threshold. Three archetypes define competitive positioning: heritage engineering houses, automation-integrated domestic champions, and diversified industrial conglomerates. Geographic expansion through localized service partnerships and technology licensing agreements represent the dominant competitive vectors.
Among heritage engineering houses, Buhler AG and Oskar Frech GmbH exemplify premium positioning anchored in Swiss and German precision standards. Yizumi Precision Machinery Co. Ltd. occupies a position within the automation-integrated tier, competing aggressively on control system localization for Chinese domestic buyers. These three entities represent the strategic spectrum from premium export engineering to domestically optimized scale production.
| Leading Market Players |
|---|
| Buhler AG |
| Oskar Frech GmbH |
| UBE Machinery Inc. |
| Toshiba Machine Co., Ltd. |
| Yizumi Precision Machinery Co. Ltd. |
| Shibaura Machine |
| Suzhou Sanji Die-Casting Automation System Co. |
| Idra Group |
| L.K. Technology Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam container freight corridors transmit steel and copper alloy cost volatility directly into equipment pricing, amplifying the spread between Swiss-German precision engineering premiums and Chinese automation-integrated alternatives while compressing margins on mid-tier configurations.
Pricing Analysis
Configured-to-order pricing for vacuum-casting systems with aerospace certification commands substantial premiums over standard high-pressure zinc casting platforms. Three-tier pricing structure across premium, standard, and economy levels separates sealed-chamber EPA-compliant systems from legacy mechanical units and entry-level Chinese domestic equipment. Price differentiation hinges on ISO repeatability certification and Mandarin-language automation interface bundling. Pricing pressure stems from commodity input volatility in hardened die steels and servo-electric actuators. Tier-one automotive suppliers in Guangdong demonstrate lowest price sensitivity, while Indian PLI-scheme entrants in Pune exhibit highest cost consciousness.
Supply Chain Analysis
Contract manufacturing concentration rests with Guangdong and Zhejiang-based system integrators holding capacity for automation retrofit packages, while German and Swiss heritage builders retain in-house production of precision injection mechanisms above 400 metric tons. Geographic supply concentration centers on China, Germany, and Switzerland for complete machine builds, with Japan and South Korea contributing servo-motor and sensor subsystems. Raw material dependencies draw from Swedish tool steel, Chilean copper cathode, and rare-earth magnet supply chains. Single-source vulnerability concentrates in high-pressure hydraulic manifold castings from Bavarian specialist foundries. Distribution runs through regional equipment distributors with localized service technicians for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric hot chamber die casting machinery sits in early-cycle expansion as EPA sealed-chamber mandates and China's dual carbon goals force seven-year replacement cycles on fifteen-year mechanical installed bases.
For Market Incumbents: Harden defensive positions by deepening backward integration into servo-electric actuator production and securing captive supply of hardened die steel inventories. Swiss-German heritage builders must accelerate Mandarin-language control system localization to neutralize Yizumi's automation-integrated threat in Guangdong procurement decisions. Capacity addition in Chennai and Pune service hubs addresses Indian PLI-scheme demand clusters before domestic Chinese competitors establish aftermarket presence. For New Entrants and Emerging Players: Pursue white-space opportunities in Vietnamese high-pressure magnesium casting for Japanese OEM transplant operations, where supply chain localization mandates outpace European service deployment capabilities. Indian domestic automotive component manufacturing represents the most penetrable geography, with first-time automated hot-chamber demand creating category-formation windows. Go-to-market positioning should emphasize predictive maintenance modules and robotic die-spraying integration rather than competing on base equipment tonnage ratings. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-integrated specialists with sensor-platform software stacks over pure-play mechanical engineering houses. Long-term viability across the projection horizon rests on control system localization capabilities and aftermarket service network density. Acquisition target archetype: mid-tier Chinese equipment builders with established domestic spare-part inventories and Mandarin-language HMI platforms. Signal to watch: BIS certification timelines for Indian export-oriented foundries as inflection indicator for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed-Chamber Retrofit Program | EPA compliance deadlines in Ohio and Michigan foundries sustain replacement demand for bath-submerged injection mechanisms. |
| Servo-Electric Platform Migration | German automotive tier-one suppliers adopt sub-400-ton electric clamping for zinc electronics chassis production. |
| Mandarin Localization Partnership | Swiss and German heritage builders partner with Shenzhen system integrators to maintain Guangdong account access. |
| Indian Service Hub Establishment | Pune and Chennai clusters under PLI schemes require qualified technicians for 24/7 production support. |
| Vacuum-Casting Certification Investment | German aerospace suppliers specify electromagnetic shielding performance for avionics enclosure contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foundry maintenance directors, OEM procurement teams, automotive tier-one supplier plant engineers, and aftermarket service heads at regional distributors. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified industrial conglomerates, machinery export registration databases, and ISO certification registries. Foundry association technical bulletins and EPA compliance guidance documents provided regulatory context. Bottom-up equipment shipment tallies by tonnage class and top-down capital expenditure surveys across automotive and aerospace end-uses were triangulated to establish market sizing.
Calibration against historical replacement cycle data and regulatory compliance deadline schedules anchored the analytical framework across the modeling period. Segmentation dimensions modeled include pressure regime, automation tier, end-use industry, and regional production cluster. CAGRs were derived from installed base age profiles, emissions mandate phase-in schedules, and alloy specification shifts under REACH and RoHS frameworks. Industry-specific forecast inputs incorporated MEE enforcement intensity for dual carbon goals and PLI scheme disbursement trajectories for Indian automotive component manufacturing.
Macroeconomic conditions sit as an overlay; deviation in copper and steel commodity price indices, container freight rates, and automotive OEM production schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology substitution elasticities. Quarterly review of EPA operating permit renewal data, BIS certification issuance rates, and Chinese domestic equipment builder automation patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Crane Rail Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Walform Machines Market
Construction Equipment
Truck Crane Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Hybrid Construction Equipment Market