
 Pulp Cells Market | 2026-2036
Pulp Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Cells Market Analytics
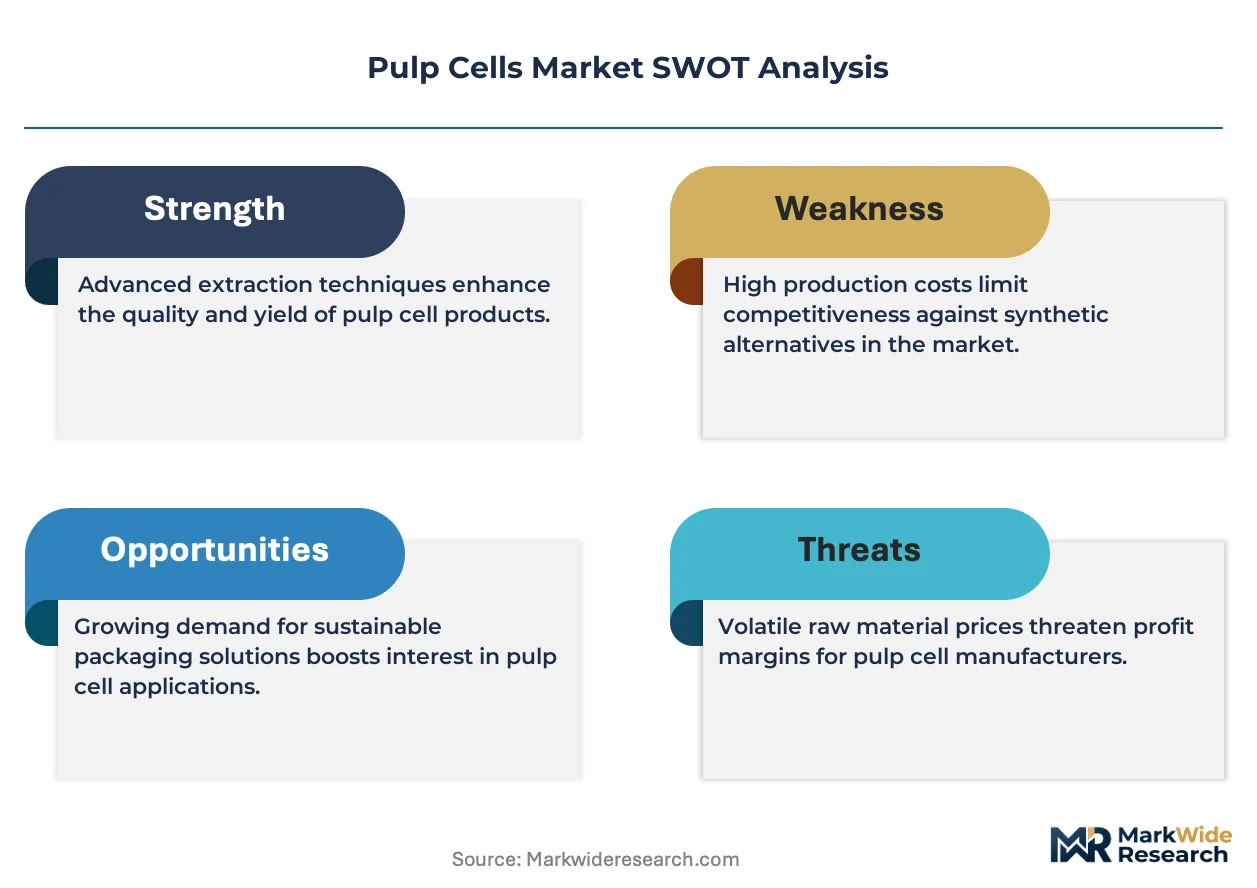
Biodegradable packaging is repositioning pulp cells from commodity paper feedstock to engineered material solutions for molded trays and protective shipping formats. Thermo Fisher Scientific leverages its life sciences distribution infrastructure to supply specialized cell culture media for pulp cell propagation protocols. Merck KGaA anchors European supply through its bioscience division, sustaining quality certifications that pharmaceutical and food-contact packaging buyers require. STEMCELL Technologies competes on specialized media formulations, differentiating its portfolio for researchers developing lignocellulosic cell lines.
Pulp cells comprise living plant cell cultures derived from wood or agricultural fiber sources, maintained in nutrient media at controlled temperature and pH to sustain viability for downstream processing into cellulose matrices, bioactive extracts, or fermentation substrates. These cultures enable the production of consistent, high-purity cellulosic material without full tree harvesting, serving applications from textile fiber regeneration to construction panel binders. Pulp fibers dominate current volume as the foundational raw material stream, while pulp chemicals capture concentrated margin pools where enzymatic treatments and specialty additives command premium positioning. Pulp sheets are gaining traction in packaging applications where flat-sheet consistency replaces traditional roll-stock for automated forming equipment.
FDA food-contact regulations and EPA chemical safety frameworks govern pulp cell-derived materials entering US consumer goods supply chains, while REACH and the EU Green Deal establish stricter carbon intensity thresholds for European market access. ISO 17025 laboratory accreditation requirements shape quality assurance protocols for suppliers serving multinational brand owners. Stakeholders must monitor evolving biodegradability certification standards and regional chemical restriction timelines to align capacity investments with compliant product portfolios.
Market Dynamics
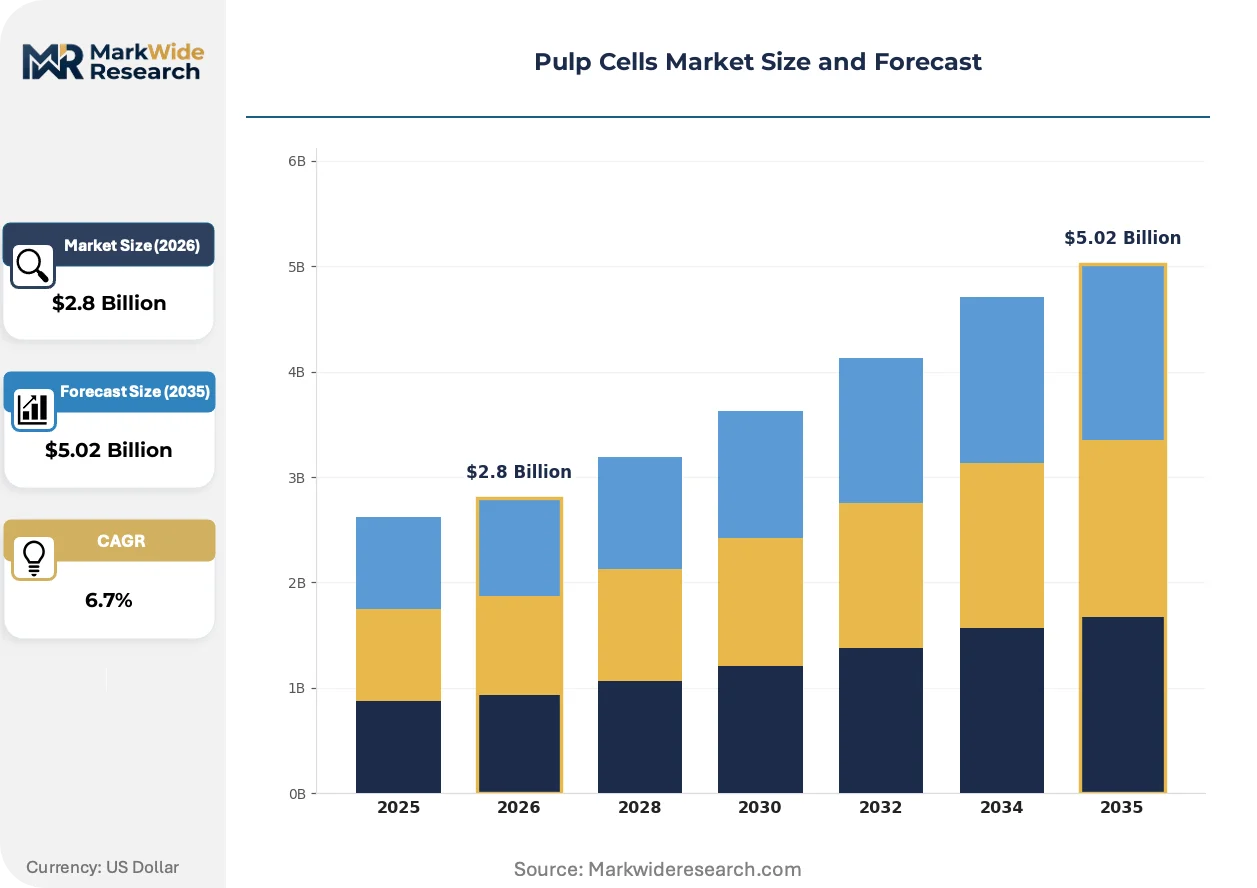
The EU Green Deal's carbon intensity thresholds are forcing packaging manufacturers to reengineer supply chains around cellulosic feedstocks, converting pulp cells from commodity inputs into certified compliance assets that determine market access.
Growth Catalysts
- REACH chemical restrictions:European manufacturers face binding limits on petroleum-derived packaging additives, redirecting R&D budgets toward enzymatic pulp cell treatments that satisfy ECHA substance authorization protocols.
- Molded fiber packaging:Food service and electronics protective formats are absorbing engineered pulp sheets at triple-digit volume multiples versus conventional roll-stock, driven by automated thermoforming equipment retrofits.
- German automotive mandates:BMW and Mercedes-Benz recycled content specifications for interior trim and shipping dunnage have created guaranteed offtake agreements that de-risk pulp cell cultivation facility investments.
Market Restraints
- Culture media cost volatility:Specialized nutrient formulations derived from pharmaceutical-grade soy peptone and yeast extracts fluctuate with agricultural commodity indices, compressing margins for propagation facility operators.
- Single-source bioreactor dependency:Stainless steel fermentation vessel fabrication concentrates in Chinese and German industrial clusters, exposing capacity expansion timelines to 14-18 month equipment backlogs.
- Enzymatic hydrolysis yield ceilings:Current cellulase cocktail efficiencies plateau at 65-70% lignocellulosic conversion, requiring larger bioreactor volumes than theoretical process models assume.
Strategic Opportunities
- India PLI scheme for bioplastics:Central government production-linked incentives for cellulosic material manufacturing offer 15-20% cost offsets for pulp cell-derived molded products serving domestic FMCG distribution.
- Construction panel binders:Cross-laminated timber and medium-density fiberboard producers are testing living pulp cell cultures as self-healing adhesive matrices that reduce formaldehyde resin dependence.
- Direct-to-brand cultivation contracts:Nestlé and Unilever sustainability procurement teams are bypassing traditional paper merchant intermediaries to secure dedicated pulp cell capacity with embedded carbon accounting.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory quality certification for cell viability assay standardization requires 18-24 month validation cycles that delay commercial shipments to pharmaceutical packaging buyers.
- Contamination control infrastructure:Maintaining axenic culture conditions across multi-thousand liter bioreactor trains demands capital expenditure for cleanroom expansion and automated sterilization systems that mid-scale facilities struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Cells Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulp Fibers, Pulp Sheets, Pulp Chemicals, Pulp Boards Application: Textiles, Construction, Packaging, Biodegradable Products End User: Manufacturers, Exporters, Retailers, Distributors Delivery Mode: Wholesale, Direct Sales, Online Channels, Custom Orders |
| Companies Covered | Lonza Group AG, Thermo Fisher Scientific Inc., Merck KGaA, STEMCELL Technologies, Fujifilm Cellular Dynamics, Sartorius AG, Ori Biotech, REPROCELL, Advanced Cell Technology and Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Cells Market Evolving Landscape
Bioreactor automation and distributed cultivation networks are fragmenting production geography away from centralized pulp mill complexes toward smaller facilities proximate to end-use manufacturing clusters.
Single-use bioreactor systems utilizing flexible film liners rather than stainless steel vessels are decentralizing pulp cell propagation capacity. Specialty chemical distributors are retrofitting regional warehouses with 500-2000 liter disposable cultivation units that serve local packaging converters. This hardware shift collapses minimum efficient scale thresholds and enables just-in-time cellulosic material supply chains that bypass traditional commodity pulp trading desks.
REACH authorization timelines for novel enzymatic processing aids are compressing product development cycles. ECHA's 2023 updated guidance on cellulase enzyme classification requires expanded toxicological dossiers that add 12-18 months to formulation commercialization. German and Dutch biotechnology suppliers are responding by pre-submitting master files that downstream pulp cell processors can reference, creating a shared regulatory infrastructure that reduces per-product compliance burdens.
Brand-led sustainability scorecards are reshaping supplier selection criteria beyond unit cost. Nestlé's packaging procurement team now weights verified carbon intensity metrics at 35% of vendor evaluation matrices, displacing traditional volume-discount negotiations. This behavioral shift concentrates contract awards among pulp cell suppliers with embedded life-cycle assessment capabilities and third-party biodegradability certifications, most visible in German and French consumer goods supply chains where retailer plastic reduction pledges have hardened into binding sourcing requirements.
Pulp Cells Market Segmentation
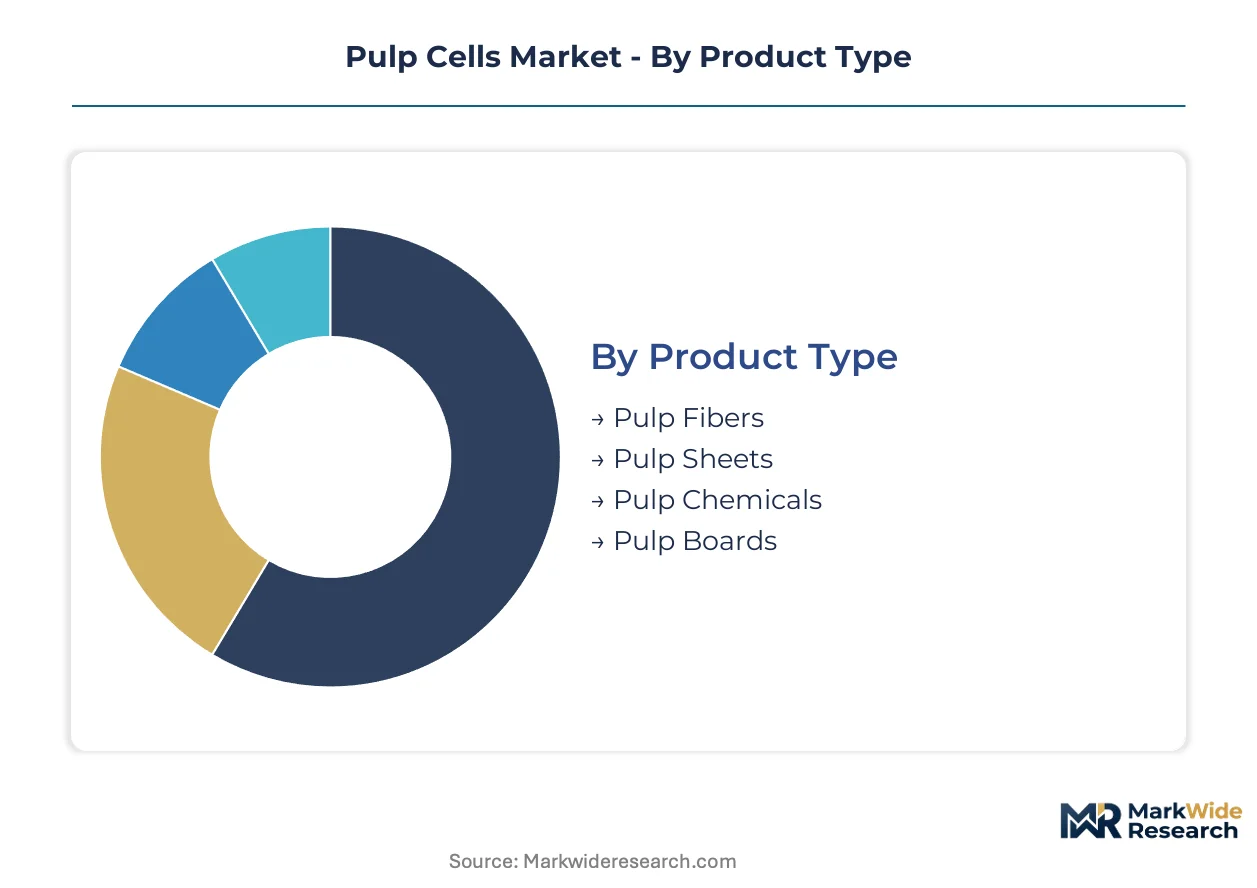
Pulp cell segmentation reveals how engineered material specifications diverge from commodity paper markets. Buyers select product formats based on automated processing compatibility, regulatory compliance requirements, and carbon accounting traceability.
Product Type:
Customization intensity varies from standardized bulk fibers to precision-engineered chemical formulations requiring batch certification.
- Pulp Fibers:Raw cellulosic strands derived from wood or agricultural residues serve as feedstock for paper mills and textile regenerators. German automotive suppliers specify recycled fiber content thresholds for interior trim applications under BMW and Mercedes-Benz procurement mandates.
- Pulp Sheets:Flat-sheet formats with calibrated moisture content and grammage enable direct feeding into automated thermoforming equipment. Food service packaging converters in France and the Netherlands absorb engineered sheets at accelerating rates as retailer plastic reduction pledges harden into binding requirements.
- Pulp Chemicals:Enzymatic treatments and specialty additives command premium positioning in pharmaceutical-grade applications.
- Pulp Boards:Rigid panel formats substitute for petroleum-derived substrates in construction and protective shipping dunnage.
Leading the category by volume: Pulp Fibers. Growing fastest: Pulp Sheets.
Application:
End-use concentration follows regulatory pressure gradients, with packaging and biodegradable products absorbing capacity as construction and textiles mature.
- Packaging:Molded fiber trays, protective inserts, and food-contact containers absorb the majority of pulp cell volume. EU Green Deal carbon intensity thresholds and REACH chemical restrictions redirect R&D budgets toward enzymatic treatments that satisfy ECHA substance authorization protocols.
- Biodegradable Products:Single-use items and compostable consumer goods require certified cellulosic inputs with verified end-of-life degradation pathways. Nestlé and Unilever sustainability procurement teams bypass traditional paper merchant intermediaries to secure dedicated pulp cell capacity with embedded carbon accounting.
- Textiles:Regenerated cellulosic fibers for apparel and industrial fabrics compete with synthetic alternatives on moisture management and dye affinity.
- Construction:Cross-laminated timber and medium-density fiberboard producers test living pulp cell cultures as self-healing adhesive matrices reducing formaldehyde resin dependence.
Dominant by procurement volume: Packaging. Steepest expansion trajectory: Biodegradable Products.
End User:
Channel structure reflects supply chain control preferences, with manufacturers seeking direct cultivation contracts while distributors aggregate fragmented converter demand.
- Manufacturers:Brand-owned and contract packaging producers specify pulp cell quality parameters for automated production lines. Direct-to-brand cultivation contracts concentrate volume among suppliers with ISO 17025 laboratory accreditation and third-party biodegradability certifications.
- Distributors:Regional chemical and paper merchants aggregate demand from small and mid-scale converters lacking volume to justify direct supplier relationships. Specialty chemical distributors retrofit regional warehouses with disposable cultivation units serving local packaging converters.
- Exporters:Cross-border traders navigate divergent regulatory frameworks between EU REACH requirements and FDA food-contact regulations.
- Retailers:Private-label sustainability commitments drive specification of pulp cell-derived packaging for store-brand products.
Highest volume concentration: Manufacturers. Fastest relationship model evolution: Distributors.
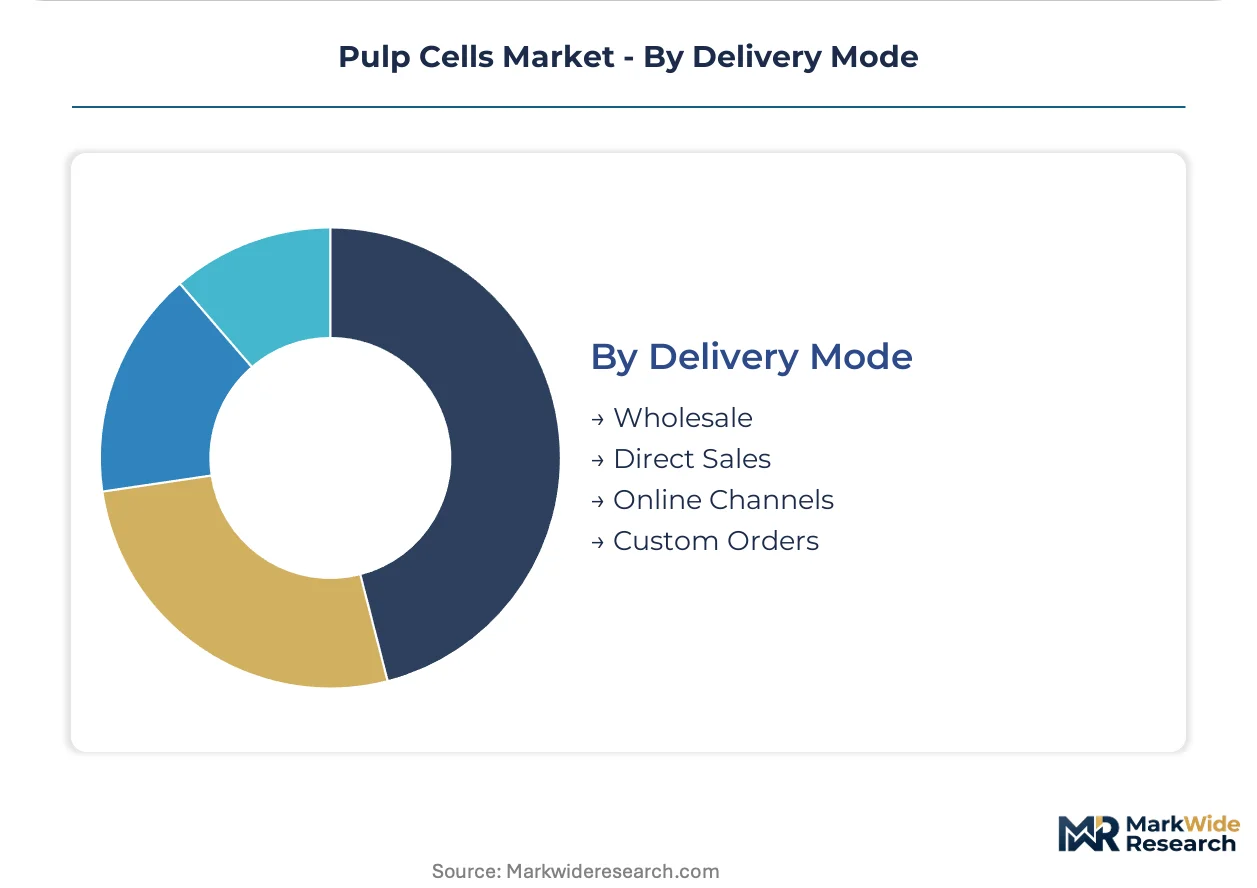
Delivery Mode:
Fulfillment complexity scales with customization requirements, from bulk wholesale to traceable custom batches with embedded carbon documentation.
- Wholesale:Bulk volume transactions dominate commodity fiber and sheet movements through established paper trading desks. Minimum efficient scale thresholds collapse as single-use bioreactor systems enable smaller regional facilities.
- Direct Sales:Large-volume manufacturers negotiate dedicated capacity with embedded life-cycle assessment capabilities. German and French consumer goods supply chains concentrate contract awards among suppliers with verified carbon intensity metrics.
- Online Channels:Digital procurement platforms aggregate spot demand from small converters and research institutions.
- Custom Orders:Specification-driven batches require axenic culture conditions and batch-specific viability documentation. Maintaining contamination control across multi-thousand liter bioreactor trains demands capital expenditure that mid-scale facilities struggle to finance.
Primary volume channel: Wholesale. Most rapidly evolving: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian pulp cell manufacturing capacity through the PLI scheme for bioplastics, while German industrial clusters anchor European engineered fiber production under EU Green Deal compliance mandates.
Germany
Automotive OEM procurement from BMW and Mercedes-Benz specifies recycled content thresholds for interior trim and shipping dunnage. REACH chemical restrictions and ECHA substance authorization protocols redirect R&D budgets toward enzymatic pulp cell treatments. The Baden-Württemberg and Bavaria industrial corridors host cultivation facilities serving direct-to-brand contracts with embedded carbon accounting.
United States
FDA food-contact regulations and EPA chemical safety frameworks govern materials entering consumer goods supply chains. Molded fiber packaging converters in the Midwest and Southeast absorb engineered pulp sheets for food service and electronics protective formats. The Pacific Northwest timber corridor sustains raw fiber supply integration with propagation facility networks.
India
Central government production-linked incentives offer 15-20% cost offsets for cellulosic material manufacturing serving domestic FMCG distribution. BIS quality standards and FSSAI food-contact specifications shape facility accreditation requirements. The Gujarat Special Economic Zone and Maharashtra industrial belt concentrate bioreactor installation capacity for regional packaging converter supply.
France
Retailer plastic reduction pledges from Carrefour and Auchan harden into binding sourcing requirements for molded fiber trays. EMA pharmaceutical packaging standards and EU Green Deal carbon intensity thresholds determine supplier selection criteria. The Île-de-France and Auvergne-Rhône-Alpes clusters coordinate enzymatic treatment R&D with Dutch biotechnology suppliers.
Netherlands
Specialty chemical distributors retrofit regional warehouses with single-use bioreactor systems serving local packaging converters. ECHA pre-submitted master files on cellulase enzymes reduce per-product compliance burdens for downstream processors. The Randstad logistics corridor enables just-in-time cellulosic material supply chains that bypass traditional commodity pulp trading desks.
Pulp Cells Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade cell culture media supply, while mid-scale regional propagators compete on customized lignocellulosic formulations. The competitive structure fragments across three strategic archetypes: diversified life sciences conglomerates with distribution infrastructure, specialized biotechnology media formulators, and contract cultivation operators serving direct brand relationships. Dominant competitive moves include capacity expansion through single-use bioreactor deployment and strategic partnerships for REACH-compliant enzymatic processing aid commercialization.
Among diversified life sciences conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions anchored by quality certifications that pharmaceutical and food-contact packaging buyers require. STEMCELL Technologies exemplifies the specialized media formulation archetype, competing on differentiated portfolios for researchers developing lignocellulosic cell lines. These three entities represent distinct competitive vectors: scale-driven distribution reach, European supply anchoring through bioscience divisions, and research-grade specialization respectively.
| Leading Market Players |
|---|
| Lonza Group AG |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| STEMCELL Technologies |
| Fujifilm Cellular Dynamics |
| Sartorius AG |
| Ori Biotech |
| REPROCELL |
| Advanced Cell Technology and Engineering |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers in China and India anchor upstream cultivation capacity, concentrating supply-side pricing power while private-equity-rolled-up European specialists enforce margin discipline through ISO 17025 certification premiums and direct-to-brand contract structures.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with pharmaceutical-grade pulp chemicals commanding 40-60% premiums over commodity fiber grades due to 18-24 month ISO 17025 accreditation timelines. Contract-based long-term offtake agreements dominate volume procurement from German automotive OEMs, while spot-market transactions serve smaller packaging converters with volatile agricultural commodity-indexed culture media costs. Price differentiation hinges on certification tier and vertical integration depth, with fully integrated cultivators capturing margin pools that merchant processors surrender to nutrient formulation suppliers. Food-contact packaging buyers exhibit highest price sensitivity as FSSAI and FDA compliance costs compound base material expenditures, whereas pharmaceutical packaging procurement teams prioritize batch traceability over unit economics.
Supply Chain Analysis
Returns of spent bioreactor liners and refurbishment flows for stainless steel vessels concentrate reverse logistics networks in Germany, China, and India, where equipment fabricators cluster. Raw material dependencies center on pharmaceutical-grade soy peptone, yeast extracts, and cellulase enzyme cocktails sourced from agricultural processing and Dutch biotechnology suppliers. Single-source bioreactor fabrication vulnerability exposes capacity expansion timelines to 14-18 month equipment backlogs. Distribution runs through specialty chemical distributors retrofitting regional warehouses with single-use cultivation units, bypassing traditional paper trading desks for just-in-time cellulosic material delivery to packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into culture media formulation represents the decisive vertical-integration race, as propagation facilities seek to decouple from agricultural commodity volatility and capture margin pools currently extracted by pharmaceutical-grade nutrient suppliers.
For Market Incumbents: Deploy single-use bioreactor systems to collapse minimum efficient scale thresholds and defend against distributed cultivation networks encroaching on regional converter relationships. Fortify ECHA pre-submitted master file portfolios to accelerate REACH-compliant enzymatic processing aid commercialization timelines. Anchor capacity expansion in Gujarat and Maharashtra special economic zones to leverage PLI scheme cost offsets serving Nestlé and Unilever direct-to-brand contracts. For New Entrants and Emerging Players: The premium-to-economy pricing gap in pharmaceutical-grade pulp chemicals offers white-space entry for specialized media formulators with differentiated lignocellulosic cell line portfolios. Target construction panel binder applications where cross-laminated timber producers test living pulp cell cultures as formaldehyde resin substitutes. Pursue retrofit partnerships with regional specialty chemical distributors seeking disposable cultivation unit deployment capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional propagators with established ISO 17025 laboratory accreditation in Baden-Württemberg and Bavaria industrial corridors. Long-term viability over the next decade rests on embedded carbon accounting capabilities and third-party biodegradability certifications that pharmaceutical and food-contact packaging buyers now mandate. Monitor ECHA authorization timeline compressions for novel enzymatic processing aids as early inflection signals for formulation commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Culture Media Formulation | Cultivation facilities decouple from agricultural commodity volatility while capturing margin pools from pharmaceutical-grade nutrient suppliers. |
| Single-Use Bioreactor Deployment | Specialty chemical distributors collapse minimum efficient scale thresholds and enable just-in-time supply chains bypassing traditional pulp trading desks. |
| REACH-Compliant Enzymatic Processing Aid Commercialization | German and Dutch biotechnology suppliers accelerate ECHA authorization timelines through pre-submitted master file infrastructure. |
| Direct-to-Brand Cultivation Contracts | Nestlé and Unilever sustainability procurement teams secure dedicated capacity with embedded carbon accounting and verified biodegradability certifications. |
| Construction Panel Binder Application Development | Cross-laminated timber and medium-density fiberboard producers reduce formaldehyde resin dependence through living pulp cell culture adhesive matrices. |
Research Methodology
SEC filings from Thermo Fisher Scientific and Merck KGaA, ECHA substance authorization databases, and EU Green Deal implementation guidance formed the secondary backbone, cross-referenced with primary interviews involving propagation facility operators, pharmaceutical packaging procurement managers, automotive Tier 1 supplier sustainability leads, and specialty chemical distribution channel heads. Bottom-up and top-down triangulation validated volume estimates across pulp fiber, sheet, chemical, and board product categories.
Bottom-up modeling aggregated segment-level demand from packaging, biodegradable products, textiles, and construction applications, while top-down analysis calibrated aggregate market expansion against EU Green Deal carbon intensity threshold enforcement and REACH chemical restriction timelines. Segmentation dimensions included product format, application end-use, delivery mode, and regional regulatory cluster. CAGRs derived from historical propagation facility capacity installation rates and enzymatic hydrolysis yield improvement trajectories.
Inputs from ECHA authorization databases and PLI scheme implementation records were available through the study window; gaps in real-time bioreactor utilization rates and proprietary culture media formulation costs introduce uncertainty bands around facility-level margin projections. Practitioners should monitor ECHA cellulase enzyme classification updates and German automotive OEM recycled content mandate revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
United Kingdom Collagen Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Bone Distractors Market
Biomaterials
Mushroom Materials Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Bone Substitutes Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
South America Collagen Market