
 Global Collagen and HA Based Biomaterial Market | 2026-2036
Global Collagen and HA Based Biomaterial Market Size, Share, and Industry Trends Forecast 2026-2036
Global Collagen and HA Based Biomaterial Market Foresight
Modularization of collagen and HA delivery formats is broadening buyer choice across surgical, injectable, and topical channels. Johnson & Johnson Services, Inc. leverages its orthopedic franchise to anchor demand for HA-based joint therapies. Sanofi competes through specialized dermal filler portfolios that integrate cross-linked hyaluronic acid matrices. Abbott Laboratories sustains R&D intensity in bioresorbable collagen scaffolds for cardiovascular applications.
Collagen and HA based biomaterials comprise extracellular matrix-derived proteins and glycosaminoglycans engineered into scaffolds, gels, and membranes with tunable porosity and degradation rates spanning 14 to 90 days. These materials serve primarily to support cell infiltration, tissue regeneration, and controlled therapeutic release in clinical and research settings. Composite hydrogels capture expanding margin pools as surgeons seek single-procedure solutions combining structural support with bioactive delivery. Aesthetic procedures occupy the fastest-growing application tier, propelled by cosmetic clinic adoption of minimally invasive HA injectables. Tissue engineering retains the largest volume footprint through biomedical research institute procurement of freeze-dried collagen scaffolds.
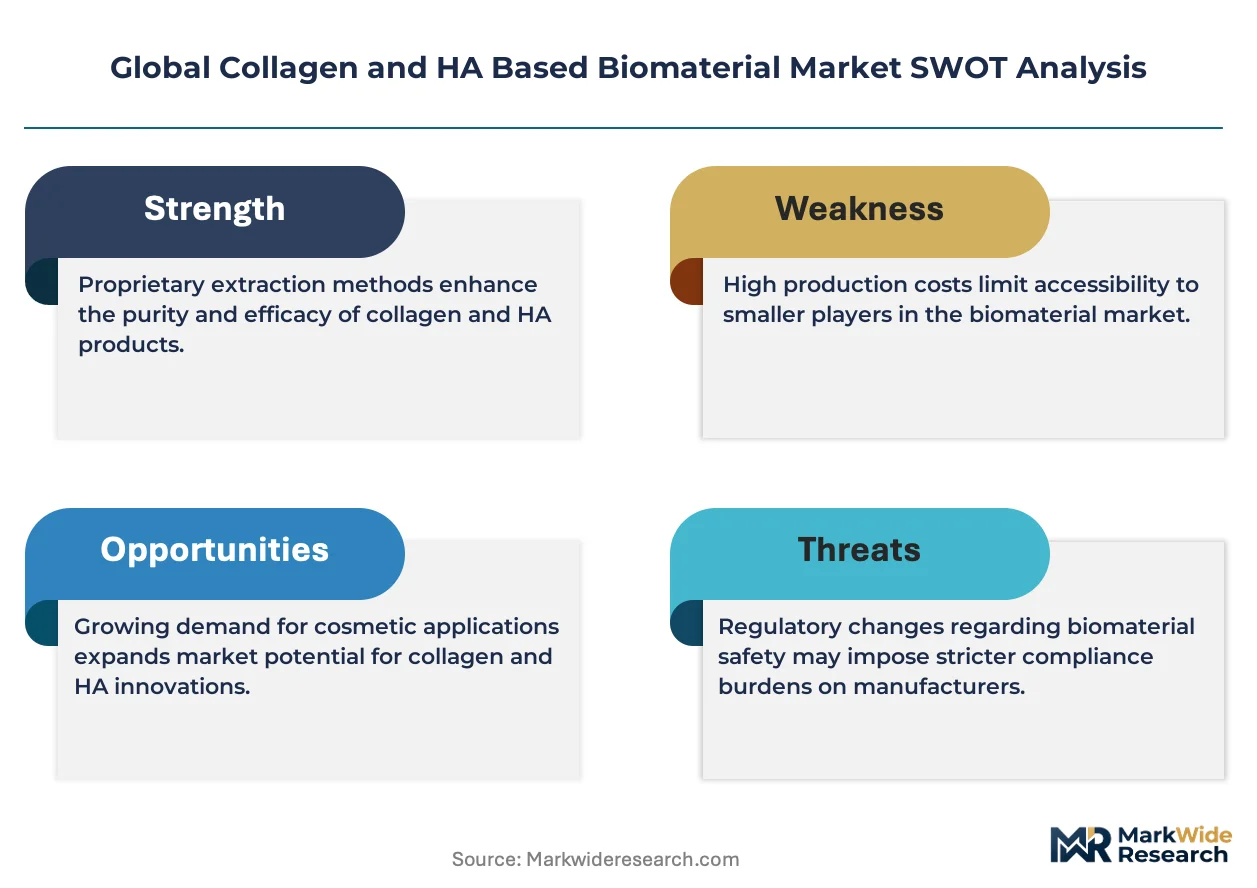
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 for collagen and HA implantable devices, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through EUDAMED. ISO 10993 provides the international biological evaluation framework that manufacturers must satisfy for market access across jurisdictions. Stakeholders must monitor how evolving FDA guidance on 3D bioprinted tissues and the EU AI Act's implications for automated quality inspection reshape compliance investment and competitive positioning.
Market Dynamics
Injectable HA formulations are compressing surgical intervention rates in orthopedic care while EU MDR biocompatibility mandates are forcing scaffold manufacturers toward centralized testing infrastructure.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance requirements through EUDAMED are accelerating clinical evidence generation for collagen-based implants.
- Minimally invasive joint therapies:Orthopedic centers in Germany are expanding same-day injection protocols for HA-based cartilage repair.
- Composite hydrogel engineering:University hospital polymer research clusters are driving single-procedure solutions that combine structural matrices with controlled therapeutic release.
Market Restraints
- Raw material volatility:Marine and bovine collagen sourcing faces price instability from fishery yield fluctuations and BSE-related import restrictions.
- Supply concentration:Cross-linking agent production for HA matrices clusters among Chinese specialty chemical manufacturers.
- Degradation rate control:Tunable scaffold lifespans spanning 14 to 90 days remain difficult to standardize across patient metabolic profiles.
Strategic Opportunities
- Cardiovascular scaffold adoption:Bioresorbable collagen patches for cardiac tissue reconstruction represent underpenetrated surgical application space.
- 3D bioprinting convergence:Automated layer-by-layer deposition of HA-collagen bioinks is opening patient-specific implant fabrication channels.
- Aesthetic clinic channel expansion:Minimally invasive dermal filler administration is shifting from hospital outpatient departments to dedicated cosmetic surgery centers.
Industry Challenges
- ISO 10993 compliance timelines:Biological evaluation framework completion for novel composite materials extends product development cycles by 18-24 months.
- Bioprinting technician scarcity:Qualified operators capable of calibrating collagen-HA bioink rheology remain concentrated in academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Collagen and HA Based Biomaterial Market |
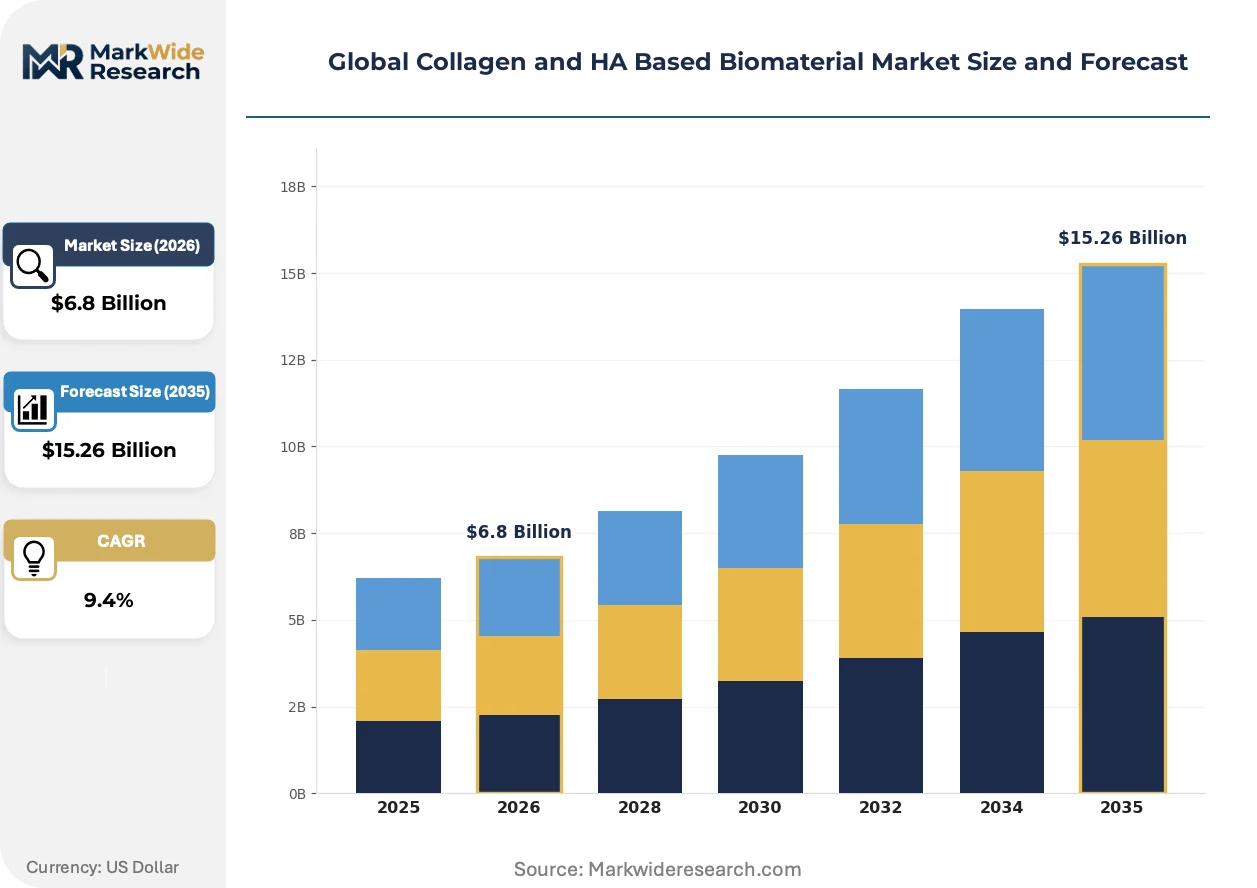
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen Scaffold, HA Gel, Composite Hydrogels, Collagen Membranes, HA Microspheres Application: Tissue Engineering, Wound Care, Drug Delivery, Orthopedic Repair, Aesthetic Procedures End User: Biomedical Research Institutes, Cosmetic Clinics, Orthopedic Centers, Pharmaceutical Companies, Regenerative Medicine Firms Technology: Cross-linking Methods, Freeze-drying, Electrospinning, 3D Bioprinting, Injectable Formulations |
| Companies Covered | Abbott Laboratories, Johnson & Johnson Services, Inc., Sanofi, Galderma Laboratories L.P., Allergan plc, Collagen Solutions Plc, Anika Therapeutics, Inc., Bausch Health Companies Inc., BioCell Technology LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Collagen and HA Based Biomaterial Market Shifts & Advancements
Point-of-care manufacturing capabilities are redrawing competitive boundaries between centralized scaffold producers and hospital-based tissue engineering labs.
Electrospun collagen nanofiber matrices with integrated HA gradients are decentralizing production of patient-matched wound dressings. Burn centers and plastic surgery units are installing compact electrospinning units for same-day scaffold fabrication. This distributed manufacturing model is compressing supply chain lead times from weeks to hours while raising questions about sterility assurance and batch consistency.
REACH substance registration requirements are tightening documentation burdens for collagen cross-linking agents imported into European Union member states. Chemical suppliers must now submit full toxicological dossiers for glutaraldehyde alternatives. German and French medical device manufacturers are responding by qualifying domestic cross-linker sources and accelerating enzymatic cross-linking method validation.
Cosmetic clinic procurement committees are consolidating vendor relationships around full-service HA filler portfolios that include injection training and adverse event management. Single-source contracting is displacing multi-supplier purchasing across aesthetic medicine practices. This concentration is most pronounced in South Korea and Brazil where clinic chains operate centralized procurement functions for dozens of satellite locations.
Global Collagen and HA Based Biomaterial Market Segmentation
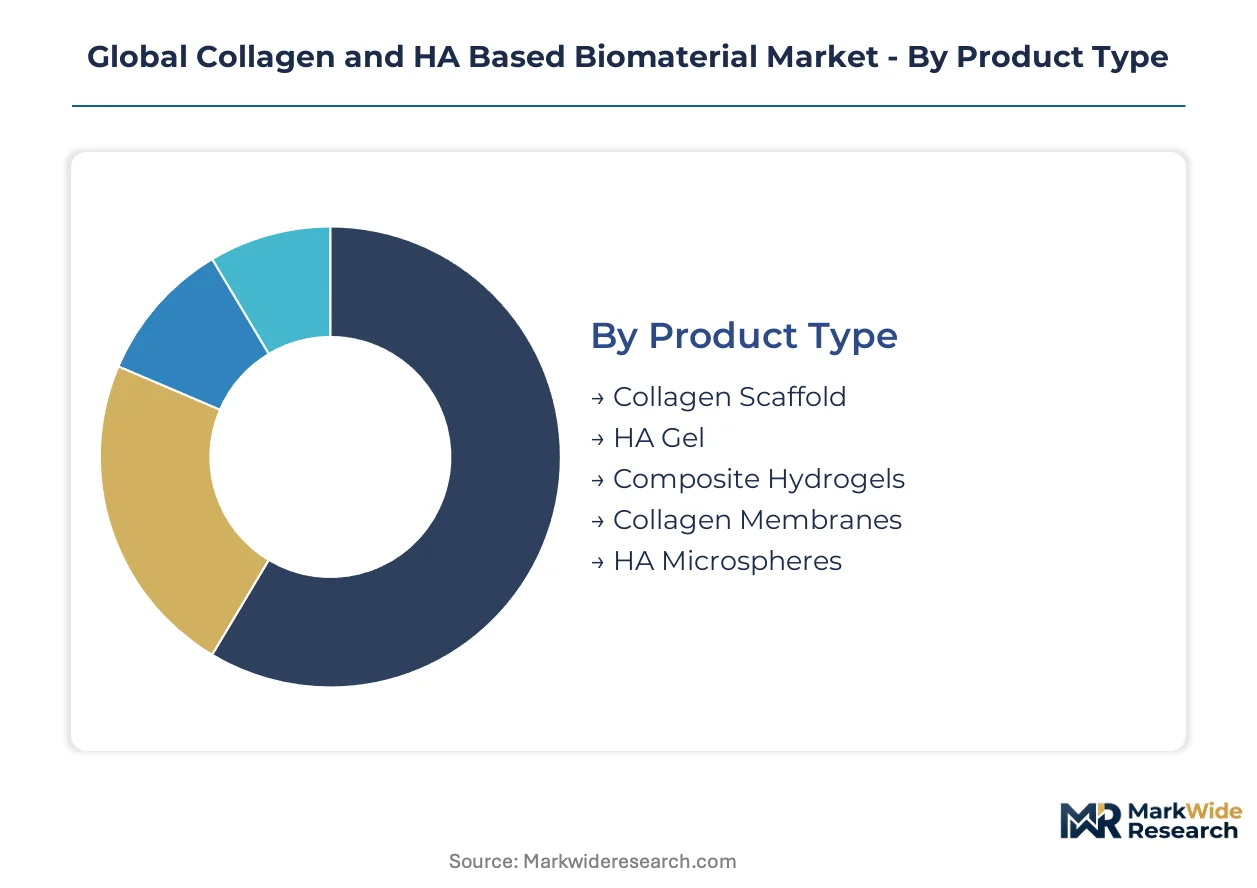
Collagen and HA biomaterial markets fragment across five distinct dimensions, each with divergent margin profiles and capital requirements. Product type determines manufacturing infrastructure intensity, while application dictates regulatory pathway complexity and reimbursement dynamics.
Product Type:
Capital intensity peaks with composite hydrogels requiring dual-compound synthesis and precision cross-linking equipment, while membrane production demands sterile casting facilities.
- Collagen Scaffold:Freeze-dried extracellular matrix structures with tunable porosity between 50-200 microns. German university hospitals and polymer research clusters drive procurement for cartilage regeneration protocols. ISO 10993 biological evaluation timelines extend development cycles by 18-24 months.
- HA Gel:Cross-linked hyaluronic acid matrices with viscoelastic properties tailored to tissue layer depth. Demand concentrates in South Korean and Brazilian cosmetic clinic chains consolidating around single-source vendor contracts. REACH registration requirements for cross-linking agents complicate European supply.
- Composite Hydrogels:Dual-network structures combining collagen structural support with HA-controlled therapeutic release. Same-day injection protocols at German orthopedic centers accelerate adoption.
- Collagen Membranes:Dense barrier layers for guided tissue regeneration. Burn centers in academic medical centers deploy compact electrospinning units for patient-matched fabrication.
- HA Microspheres:Degradable particulate carriers for sustained drug release. Pharmaceutical companies integrate these into injectable depot formulations.
Most installed capacity flows through HA Gel. Expansion is steepest in Composite Hydrogels.
Application:
Revenue concentration varies sharply by procedure reimbursement codes and regulatory clearance pathways, with aesthetic procedures commanding premium pricing per unit volume.
- Tissue Engineering:Scaffold-supported cell culture for organoid development and regenerative constructs. Biomedical research institutes in Germany and the United States procure freeze-dried collagen matrices in bulk for laboratory expansion. FDA 21 CFR Part 820 quality system requirements govern implantable device classifications.
- Aesthetic Procedures:Minimally invasive dermal filler injections and volume restoration. Cosmetic clinic chains in South Korea operate centralized procurement for dozens of satellite locations, displacing multi-supplier purchasing patterns.
- Wound Care:Electrospun nanofiber dressings with integrated HA gradients. Point-of-care manufacturing at burn centers compresses supply chain lead times from weeks to hours.
- Drug Delivery:Bioresorbable depots for controlled therapeutic release. Pharmaceutical companies validate enzymatic cross-linking methods to satisfy EUDAMED post-market surveillance.
- Orthopedic Repair:Injectable HA formulations for joint lubrication and cartilage protection. Same-day discharge protocols at German orthopedic centers reduce surgical intervention rates.
Tissue Engineering captures the largest procurement volume. Aesthetic Procedures are gaining share fastest.
End User:
Buying power consolidates around institutions with captive research funding or high-throughput surgical throughput, creating tiered supplier access.
- Biomedical Research Institutes:Academic and government laboratories procuring raw scaffold materials for experimental protocols. German polymer research clusters drive composite hydrogel specifications.
- Cosmetic Clinics:Dedicated aesthetic medicine practices with centralized vendor consolidation. South Korean clinic chains demand full-service portfolios including injection training.
- Orthopedic Centers:Hospital-based and ambulatory surgical facilities performing joint injection therapies. German university hospitals pioneer same-day HA protocols.
- Pharmaceutical Companies:Drug developers integrating biomaterials into combination product submissions. EMA and FDA dual-track submissions require harmonized biocompatibility dossiers.
- Regenerative Medicine Firms:Commercial cell therapy developers requiring GMP-grade scaffold materials. Qualification of domestic cross-linker sources accelerates in France and Germany.
Biomedical Research Institutes absorb the highest absolute volume. Cosmetic Clinics show the steepest expansion trajectory.
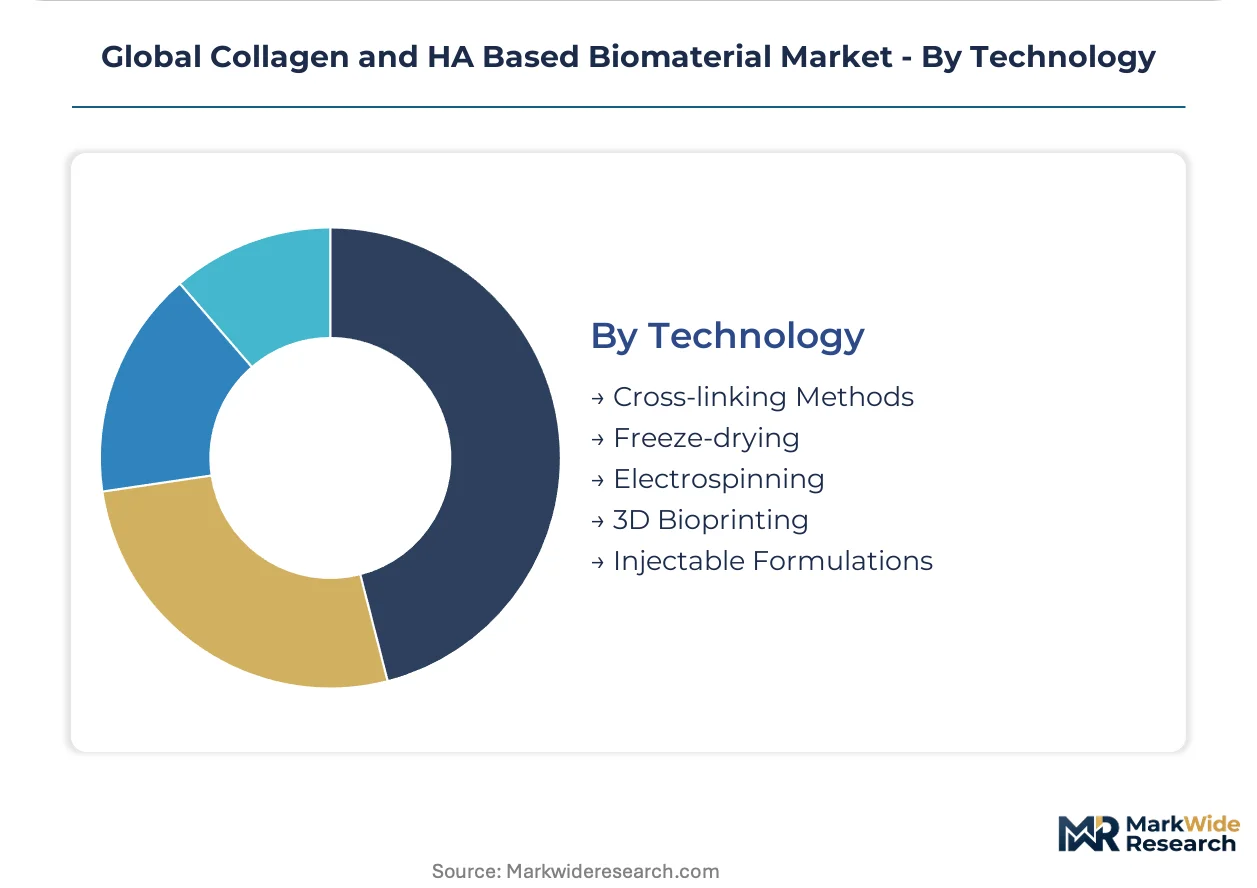
Technology:
Process innovation determines degradation rate precision and batch-to-batch consistency, with automated methods displacing manual fabrication.
- Cross-linking Methods:Chemical and enzymatic techniques stabilizing collagen and HA networks. ECHA REACH dossier requirements for glutaraldehyde alternatives drive method validation investment.
- Freeze-drying:Lyophilization protocols preserving scaffold porosity for cell infiltration. Biomedical research institutes specify 14-90 day degradation windows.
- Electrospinning:Electric field-driven nanofiber deposition for wound dressing matrices. Burn centers install compact units for distributed manufacturing.
- 3D Bioprinting:Layer-by-layer deposition of collagen-HA bioinks for patient-matched implants. Technician scarcity at academic medical centers constrains throughput.
- Injectable Formulations:Ready-to-use HA gels for office-based administration. Orthopedic centers in Germany expand same-day protocols.
Freeze-drying commands the most installed base. 3D Bioprinting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The collagen and hyaluronic acid biomaterial industry traces its commercial roots to mid-20th century European pharmaceutical laboratories, where bovine collagen extraction protocols first achieved medical-grade purity standards for wound closure applications.
United States
FDA 21 CFR Part 820 quality system requirements govern the largest installed base of orthopedic and aesthetic device manufacturing. Boston and San Diego biomedical clusters host concentrated regenerative medicine R&D operations. Massachusetts General Hospital and Stanford Medical Center drive early adoption of 3D bioprinted scaffold protocols for patient-matched implants.
Germany
University hospital polymer research clusters in Berlin and Munich specify composite hydrogel formulations for same-day joint injection protocols. EU Medical Device Regulation post-market surveillance through EUDAMED accelerates clinical evidence generation for collagen-based implants. Baden-Württemberg's medical technology corridor houses specialized cross-linking agent validation facilities serving domestic manufacturers.
South Korea
Cosmetic clinic chains operating centralized procurement functions for dozens of satellite locations displace multi-supplier purchasing patterns. MFDS regulates HA filler biocompatibility under medical device classification rules. Seoul Capital Area aesthetic medicine practices consolidate vendor relationships around full-service portfolios including injection training.
Switzerland
Swissmedic maintains stringent biological evaluation timelines for novel composite materials entering the Alpine market. Basel and Zurich host precision chemical manufacturing for enzymatic cross-linking methods. Domestic collagen sourcing from certified bovine herds supports pharmaceutical-grade scaffold production for export markets.
Brazil
ANVISA registration requirements for imported HA matrices create compliance barriers favoring local assembly partnerships. São Paulo clinic chains replicate South Korean vendor consolidation models across Latin America's largest aesthetic medicine market. Rio de Janeiro research institutes specialize in marine collagen extraction from regional fishery byproducts.
Global Collagen and HA Based Biomaterial Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification tiers and clinical evidence depth. The vendor base stratifies between diversified healthcare conglomerates with captive orthopedic franchises and specialized biomaterial houses focused on single therapeutic modalities. Three archetypes dominate: integrated device-pharma hybrids, pure-play scaffold specialists, and aesthetic-focused filler manufacturers. Capacity expansion into GMP-grade collagen sourcing and strategic partnerships for bioink formulation represent the dominant competitive vectors reshaping positioning.
Among diversified healthcare conglomerates, Johnson & Johnson Services, Inc. and Abbott Laboratories occupy positions spanning orthopedic, cardiovascular, and surgical application vectors. Sanofi exemplifies the pharmaceutical-origin archetype leveraging specialized dermal filler portfolios. Collagen Solutions Plc represents the pure-play scaffold specialist model concentrated on extracellular matrix engineering.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson & Johnson Services, Inc. |
| Sanofi |
| Galderma Laboratories L.P. |
| Allergan plc |
| Collagen Solutions Plc |
| Anika Therapeutics, Inc. |
| Bausch Health Companies Inc. |
| BioCell Technology LLC |
| Others |
Supply & Pricing Matrix
REACH substance registration requirements for collagen cross-linking agents gate qualified supply access and premium-tier pricing power, as German and French manufacturers now pay documented toxicological dossier costs to secure EU Medical Device Regulation-compliant sourcing while disqualifying non-compliant competitors from high-margin hospital procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade collagen scaffolds from research-grade matrices and commodity HA fillers. Certification tier under EU MDR and ISO 10993 compliance depth drive price differentiation, with validated enzymatic cross-linking methods commanding substantial premiums over glutaraldehyde alternatives. Cost compression in standard-tier HA gels is intensifying because South Korean clinic chains consolidate procurement volumes around single-source contracts. Research institutes exhibit highest price sensitivity due to grant-funded budgets, while regenerative medicine firms pay least attention to unit economics given cell therapy reimbursement rates.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States anchor hub-and-spoke patterns serving orthopedic centers and cosmetic clinic chains with temperature-controlled logistics. Marine collagen extraction from regional fisheries, bovine dermis sourcing from certified herds, and Chinese-manufactured cross-linking agents constitute critical input dependencies. Single-source vulnerability around specialty chemical intermediates creates structural risk exposure. Distribution runs through medical device distributors with GMP warehousing capabilities and direct-to-hospital contracts for high-value scaffold shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Medical Device Regulation post-market surveillance mandates through EUDAMED continuously deepen clinical evidence requirements and expand addressable demand for compliant biomaterial suppliers.
For Market Incumbents: Cement dominance by qualifying domestic cross-linker sources in Baden-Württemberg validation facilities and accelerating enzymatic method patent filings. Capacity addition in German polymer research corridors captures university hospital specification influence. Threat from 3D bioprinting startups with automated bioink deposition capabilities demands preemptive technician training partnerships with academic medical centers. For New Entrants and Emerging Players: Burn centers with point-of-care electrospinning infrastructure represent an underserved buyer archetype lacking qualified compact unit suppliers. Cardiovascular scaffold applications for cardiac tissue reconstruction offer the most penetrable surgical segment given limited incumbent focus. A go-to-market angle emphasizing same-day fabrication protocols with sterilization assurance documentation bypasses established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized scaffold specialists because ISO 10993 biological evaluation timelines create 18-24 month moats against rapid competitive entry. Five-to-ten year viability hinges on GMP-grade collagen sourcing consolidation. Acquisition target archetype: pure-play extracellular matrix engineering houses with validated freeze-drying protocols. Signal to watch: MFDS regulatory filings from Seoul-based cosmetic clinic suppliers indicating Asia-Pacific expansion capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EUDAMED registration accelerates German orthopedic center procurement decisions. |
| Hospital System Partnership | Berlin university hospital specifications cascade to satellite clinic networks. |
| Backward Integration into Collagen Sourcing | Swiss certified bovine herds secure pharmaceutical-grade scaffold supply chains. |
| Software Companion Development | Bioink rheology calibration tools address technician scarcity at academic centers. |
| Reimbursement Strategy | German same-day injection protocol codes expand addressable orthopedic volumes. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at scaffold manufacturers with secondary validation against FDA 510(k) filings, EUDAMED device registrations, hospital procurement databases, and ISO 10993 biological evaluation protocols. Bottom-up demand modeling from end-user consumption patterns triangulates against top-down supply-side capacity assessments across freeze-drying, electrospinning, and 3D bioprinting equipment installations.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology platform with regional regulatory cluster overlays. CAGRs derive from fitted growth curves calibrated to historical adoption rates of prior regenerative medicine modalities. Industry-specific forecast inputs incorporate EMA and FDA submission pipeline tracking plus German university hospital research grant award patterns.
Underlying measurement precision varies by segment; aesthetic procedure demand carries tighter precision than emerging cardiovascular scaffold adoption where clinical trial readouts remain pending. Forecasts reflect documented assumptions regarding EU MDR implementation timelines and REACH registration compliance rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Global Biomaterials Market
Biomaterials
South America Collagen Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Pulp Cells Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Scaffold Materials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
North America Chitosan Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market