
 Global Medical Engineered Materials Market | 2026-2036
Global Medical Engineered Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Engineered Materials Market Foresight
German polymer compounders is recalibrating capacity toward medical-grade resins as OEMs demand ISO 10993-compliant feedstock. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of high-purity polycarbonates for dialysis membranes. Evonik Industries AG anchors its medical portfolio on specialty PMMA and PEEK derivatives for orthopedic implants. Solvay S.A. differentiates through sulfone polymer expertise that dominates chronic blood-contacting applications.
Medical engineered materials encompass thermoplastics, elastomers, ceramics, and composites formulated to meet biocompatibility, sterilization resistance, and mechanical performance criteria for patient-contacting applications. These materials typically satisfy ISO 10993 cytotoxicity and USP Class VI standards while maintaining dimensional stability through gamma, ethylene oxide, or steam sterilization cycles. Polymers command the largest value share due to their processability across injection molding and extrusion platforms for disposable and durable devices. Ceramics represent the fastest-expanding category as zirconia and alumina formulations displace metal components in dental and joint reconstruction platforms. Bioactive glass occupies a concentrated margin pool where orthobiologic manufacturers command premium pricing for osteoconductive scaffolds.
FDA enforces 21 CFR Part 820 quality system regulations that mandate material traceability from raw resin through finished device, while EMA's Medical Device Regulation tightens notified body scrutiny of substance migration risks. REACH restricts phthalate plasticizers in blood bags and tubing, forcing reformulation toward citrate-based alternatives across European supply chains. Japan's PMDA maintains distinct biocompatibility testing protocols that create dual-qualification burdens for multinational material suppliers. Stakeholders must monitor evolving MDR substance disclosure requirements and FDA's anticipated harmonization with ISO 18562 for respiratory gas pathway devices.
Market Dynamics
FDA's tightening 21 CFR Part 820 traceability mandates and EMA's MDR substance disclosure requirements are forcing compounders to revalidate entire resin portfolios, compressing qualification timelines while OEMs demand faster material swaps.
Growth Catalysts
- ISO 18562 harmonization:FDA's anticipated alignment with respiratory gas pathway standards is accelerating biocompatibility testing investments across polymer suppliers serving ventilator and anesthesia device manufacturers.
- Chronic disease prevalence:Dialysis membrane demand is pulling high-purity polycarbonate consumption as home-based renal therapy expands patient treatment volumes.
- German precision clusters:Ludwigshafen-to-Tübingen supply corridors concentrate compounding expertise, reducing logistics costs for orthopedic implant OEMs sourcing PEEK and PMMA derivatives.
Market Restraints
- Specialty monomer concentration:Sulfolane and bisphenol-A feedstock for sulfone polymers concentrates among three Asian petrochemical complexes, exposing buyers to force majeure volatility.
- Dual-qualification burden:Japan's PMDA maintains distinct cytotoxicity protocols from ISO 10993, forcing redundant testing budgets for multinational material suppliers.
- Ceramic machining limits:Zirconia femoral heads require diamond grinding infrastructure that fewer than twelve contract manufacturers possess globally, capping orthopedic ceramic expansion.
Strategic Opportunities
- Brazil's ANVISA pathway:Mercosur harmonization is opening consolidated approval routes for medical-grade PVC compounders serving South American disposable device markets.
- Additive manufacturing convergence:Laser sintering of PEEK-OPTIMA is enabling patient-specific cranial implants, bypassing traditional injection molding tooling costs for low-volume reconstructions.
- EU Green Deal chemistry:REACH bio-based plasticizer mandates for phthalate replacement are creating first-mover advantages for citrate ester suppliers qualifying blood bag formulations.
Industry Challenges
- MDR technical documentation:Notified body backlogs extend substance migration study timelines from nine to twenty-four months, freezing new resin introductions.
- Gamma sterilization validation:Polymer yellowing and mechanical degradation after repeated irradiation cycles forces iterative reformulation that consumes R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Engineered Materials Market |
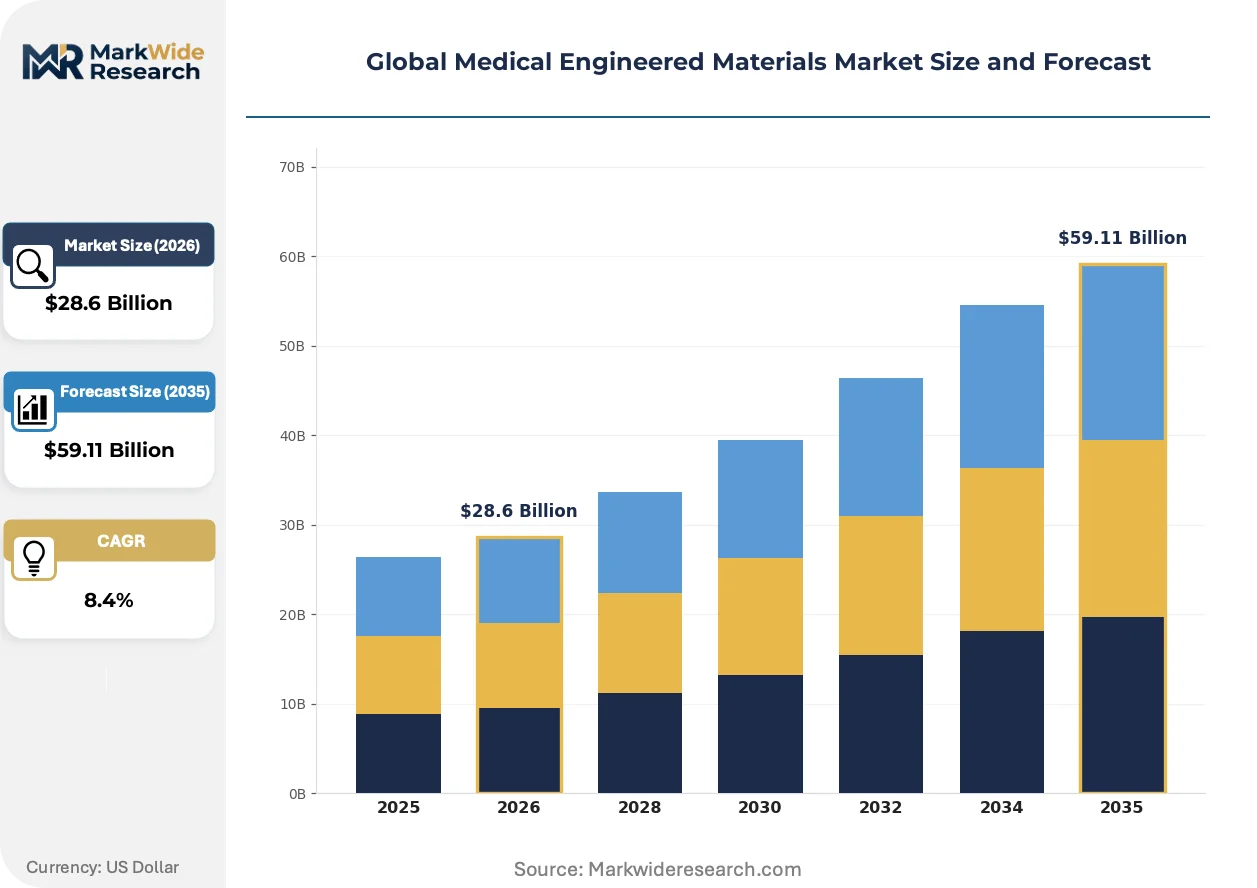
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymers, Ceramics, Composites, Bioactive Glass Therapy Area: Orthopedics, Cardiovascular, Dental, Wound Care End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Rehabilitation Centers Delivery Mode: Implantable Devices, Injectable Formulations, Coatings, Scaffolds |
| Companies Covered | BASF SE, Merck KGaA, Evonik Industries AG, Solvay S.A., Celanese Corporation, Covestro AG, Lonza Group AG, Arkema S.A., Royal DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Engineered Materials Market Shifts & Advancements
Automation of material qualification workflows and convergence of regulatory standards are compressing development cycles while bioactive formulations expand addressable indications beyond structural replacement.
Artificial intelligence-driven formulation screening is automating candidate polymer selection for targeted mechanical properties and biocompatibility profiles. Medical device OEMs including spinal implant manufacturers are piloting these platforms to halve traditional compounding iteration cycles. The technology is automating regulatory submission preparation by pre-populating ISO 10993 test matrices based on chemical structure predictions.
EMA's Medical Device Regulation substance disclosure requirements are mandating granular chemical composition reporting for all patient-contacting materials. Compounders must now document additive migration profiles down to 0.1% weight thresholds, forcing reformulation of legacy colorant packages. Blood-contacting device categories face the steepest compliance costs as notified bodies scrutinize plasticizer and stabilizer leachables.
Hospital procurement consortia are consolidating material specifications to reduce SKU complexity across disposable catheter and tubing portfolios. Group purchasing organizations now mandate single-resin platforms serving multiple device families, pressuring compounders to broaden property ranges within single grades. Germany's university hospital networks demonstrate this most acutely, where Rhineland procurement alliances negotiate pan-European supply agreements.
Global Medical Engineered Materials Market Segmentation
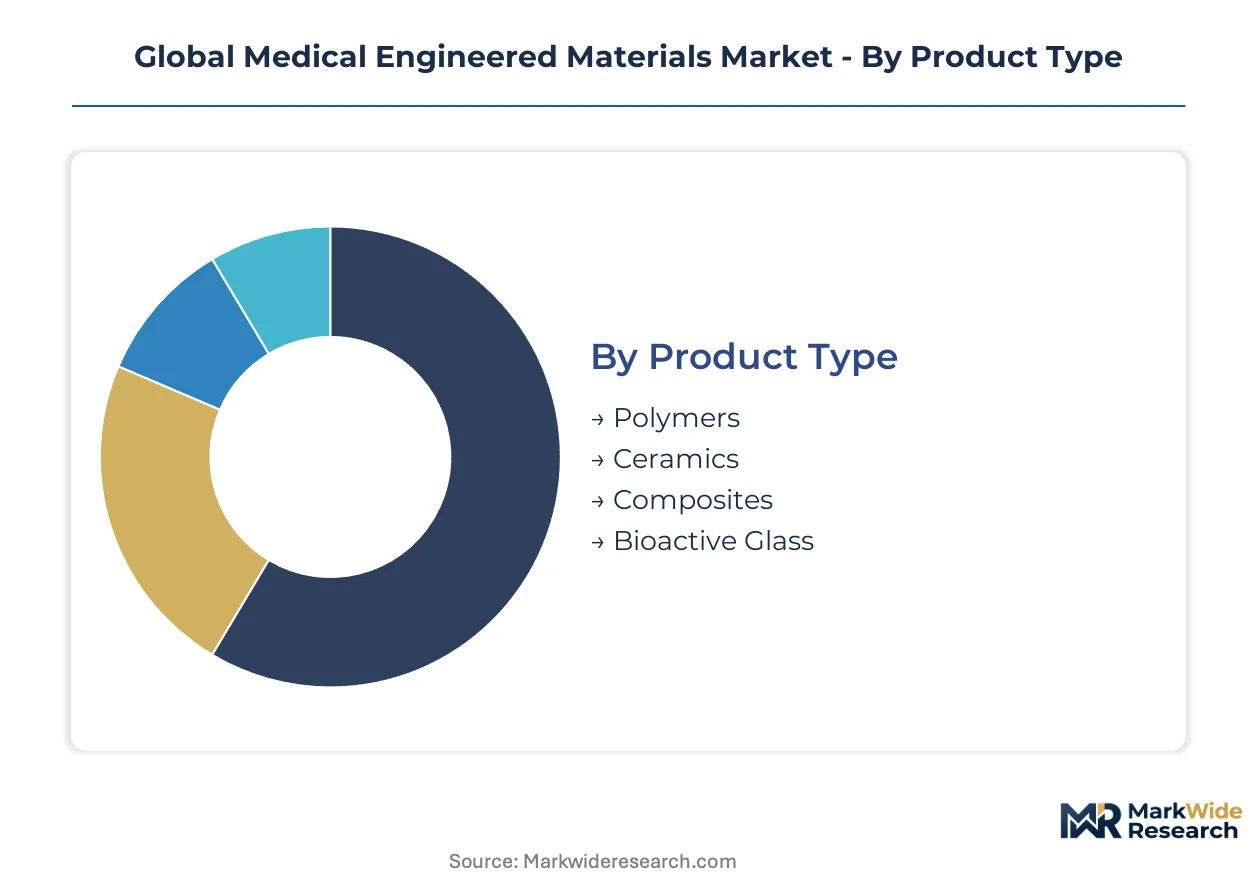
Medical engineered materials demand diverges sharply across therapy areas and delivery modes, with orthopedic OEMs prioritizing mechanical durability while cardiovascular manufacturers emphasize hemocompatibility. Segmentation reveals how formulation complexity and regulatory burden concentrate value in implantable polymers and bioactive ceramics.
Product Type:
Standardization dominates commodity thermoplastics while specialty polymers and ceramics command premium customization cycles extending qualification timelines.
- Polymers:Thermoplastics, elastomers, and high-performance resins formulated for ISO 10993 biocompatibility and gamma sterilization resistance. PEEK and polycarbonate derivatives anchor orthopedic and dialysis applications where German compounders at Ludwigshafen and Marl maintain captive supply chains for device OEMs.
- Ceramics:Alumina, zirconia, and bioinert oxide formulations machined to sub-micron tolerances for joint reconstruction and dental restorations. Japanese manufacturers in Aichi Prefecture concentrate diamond-grinding infrastructure for femoral heads, constraining global capacity expansion despite climbing demand from aging populations.
- Composites:Fiber-reinforced polymer matrices combining carbon or glass with biocompatible resins for load-bearing implants.
- Bioactive Glass:Silicate-based formulations engineered for osteoconduction in bone void fillers and tissue scaffolds.
Leading the category by volume: Polymers. Expanding most quickly: Ceramics.
Therapy Area:
Procedure volume and reimbursement density determine material specification intensity across surgical specialties.
- Orthopedics:Load-bearing implants, fixation hardware, and joint reconstruction platforms utilizing PEEK, cobalt-chrome, and ceramic-bearing surfaces. German trauma device clusters in Tuttlingen source sulfone polymers and PMMA derivatives through Rhineland supply corridors.
- Cardiovascular:Stent substrates, pacemaker encapsulants, and vascular graft materials requiring hemocompatibility validation. FDA's anticipated ISO 18562 harmonization accelerates respiratory gas pathway testing investments for polymer suppliers serving cardiac device manufacturers.
- Dental:Zirconia crowns, implant abutments, and composite resins for restorative and prosthetic applications.
- Wound Care:Absorbent foams, hydrogels, and antimicrobial dressings for acute and chronic lesion management.
Orthopedics generates the highest material consumption per procedure. Cardiovascular applications are climbing the fastest on structural heart device expansion.
End User:
Centralized procurement at hospital consortia versus fragmented purchasing at outpatient facilities reshapes material specification consolidation.
- Hospitals:Academic medical centers and tertiary care facilities performing complex implant procedures with stringent material traceability requirements. German university hospital networks consolidate Rhineland procurement alliances negotiating pan-European supply agreements for standardizing catheter and tubing portfolios.
- Ambulatory Surgery Centers:Outpatient facilities prioritizing cost-efficient disposable devices and streamlined sterilization protocols.
- Diagnostic Laboratories:Blood collection, processing, and analysis equipment manufacturers demanding USP Class VI compliant polymers.
- Rehabilitation Centers:Prosthetic and orthotic device fitting facilities sourcing patient-specific components.
Hospitals dominate procurement volume. Ambulatory Surgery Centers are gaining share fastest on outpatient migration.
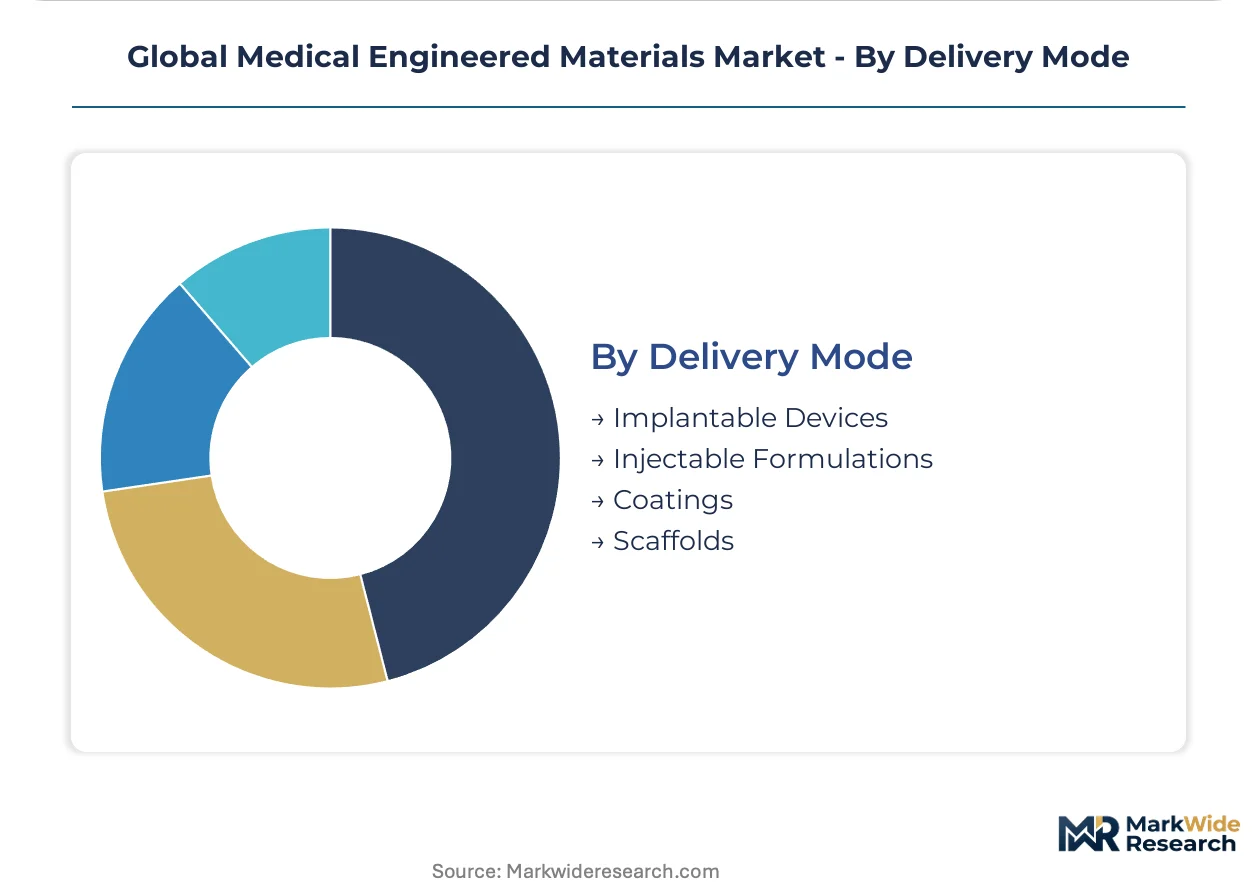
Delivery Mode:
Implant permanence and patient contact duration dictate regulatory classification and material qualification burden.
- Implantable Devices:Permanent and long-term temporary devices requiring comprehensive ISO 10993 biological evaluation and FDA 21 CFR Part 820 traceability. PEEK-OPTIMA laser sintering enables patient-specific cranial implants, bypassing traditional injection molding tooling costs for low-volume reconstructions.
- Injectable Formulations:Bioresorbable microparticles, hydrogels, and drug-device combination products. EMA's MDR substance disclosure mandates granular chemical composition reporting down to 0.1% weight thresholds, forcing reformulation of legacy colorant packages in polymer matrices.
- Coatings:Surface modifications for thromboresistance, antimicrobial properties, or drug elution on base substrates.
- Scaffolds:Three-dimensional porous structures supporting cell infiltration and tissue regeneration in orthobiologic applications.
Implantable Devices lead by revenue concentration. Scaffolds show the steepest expansion trajectory on regenerative medicine investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfolane and bisphenol-A feedstock for sulfone polymers concentrates among three Asian petrochemical complexes, exposing buyers to force majeure volatility while German precision clusters anchor European supply chains for high-purity medical resins.
United States
FDA's 21 CFR Part 820 quality system regulations mandate material traceability from raw resin through finished device, driving compounders to invest in batch-level documentation systems. The agency's anticipated harmonization with ISO 18562 for respiratory gas pathway devices accelerates biocompatibility testing investments. Greater Boston's medical device corridor concentrates dialysis membrane manufacturers sourcing polycarbonate from domestic compounders.
Germany
EMA's Medical Device Regulation tightens notified body scrutiny of substance migration risks, forcing reformulation of legacy colorant packages. REACH restrictions on phthalate plasticizers in blood bags compel citrate-based alternative adoption. The Ludwigshafen-to-Tübingen supply corridor concentrates PEEK and PMMA compounding expertise, reducing logistics costs for orthopedic implant OEMs in the Tuttlingen trauma device cluster.
Japan
PMDA maintains distinct biocompatibility testing protocols from ISO 10993, creating dual-qualification burdens for multinational material suppliers. METI supports domestic ceramic machining infrastructure for zirconia femoral heads. Aichi Prefecture concentrates diamond-grinding capacity for orthopedic ceramics, constraining global expansion despite aging population demand.
China
NMPA strengthens medical device material registration requirements under revised GB standards, extending qualification timelines for imported resins. MIIT promotes domestic sulfone polymer capacity to reduce feedstock import dependence. The Yangtze River Delta anchors contract manufacturing for global device OEMs seeking cost-competitive compounding alternatives.
Brazil
ANVISA leverages Mercosur harmonization to open consolidated approval routes for medical-grade PVC compounders. The national pharmaceutical regulator accelerates review timelines for disposable device materials meeting regional standards. São Paulo's medical device assembly corridor drives procurement of USP Class VI compliant polymers for catheter and tubing production.
Global Medical Engineered Materials Market Competitive Landscape
Global majors compete with regional champions across resin qualification and regulatory submission capabilities, producing a tiered structure where integrated petrochemical groups hold feedstock advantages while specialty compounders dominate application-specific formulations. Three archetypes populate the landscape: diversified chemical conglomerates with captive monomer supply, focused medical polymer specialists with deep ISO 10993 expertise, and regional compounders serving localized device manufacturing. Consolidation pressures intensify as M&A activity concentrates formulation capabilities and strategic partnerships distribute regulatory submission burdens across geographic markets.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype, combining petrochemical feedstock control with medical-grade purification capabilities. Solvay S.A. occupies a position within the specialty polymer tier, representing sulfone chemistry expertise for chronic blood-contacting applications. These three European entities anchor the premium resin segment where qualification timelines and regulatory documentation create defensive moats against commodity competitors.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Evonik Industries AG |
| Solvay S.A. |
| Celanese Corporation |
| Covestro AG |
| Lonza Group AG |
| Arkema S.A. |
| Royal DSM N.V. |
| Others |
Supply & Pricing Matrix
Family-owned German compounders operating along the Ludwigshafen-to-Tübingen corridor have consolidated medical-grade resin production through successive generational transfers, embedding supply discipline that resists spot-market volatility while preserving premium pricing power for ISO 10993-certified feedstock.
Pricing Analysis
Warranty-backed batch certification separates premium medical polymer pricing from standard industrial grades, with compounders bundling regulatory documentation and migration study guarantees into per-kilogram contracts. Price differentiation hinges on FDA master file status and EMA notified body pre-qualification, with gamma-sterilization validation adding further tiers. Cost compression in commodity polycarbonates is intensifying because hospital GPOs are consolidating SKU specifications, while orthopedic implant OEMs remain least price-sensitive due to liability exposure from material failures.
Supply Chain Analysis
Skilled polymer chemist shortages in Germany and Switzerland constrain sulfone polymer capacity expansion despite climbing demand from chronic blood-contacting device manufacturers. Feedstock draws from Chinese, South Korean, and Saudi petrochemical complexes for bisphenol-A and sulfolane monomers, creating single-source vulnerability when Asian force majeure events disrupt maritime lanes. Distribution runs through Rhineland logistics hubs serving Tuttlingen orthopedic clusters before radiating to pan-European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
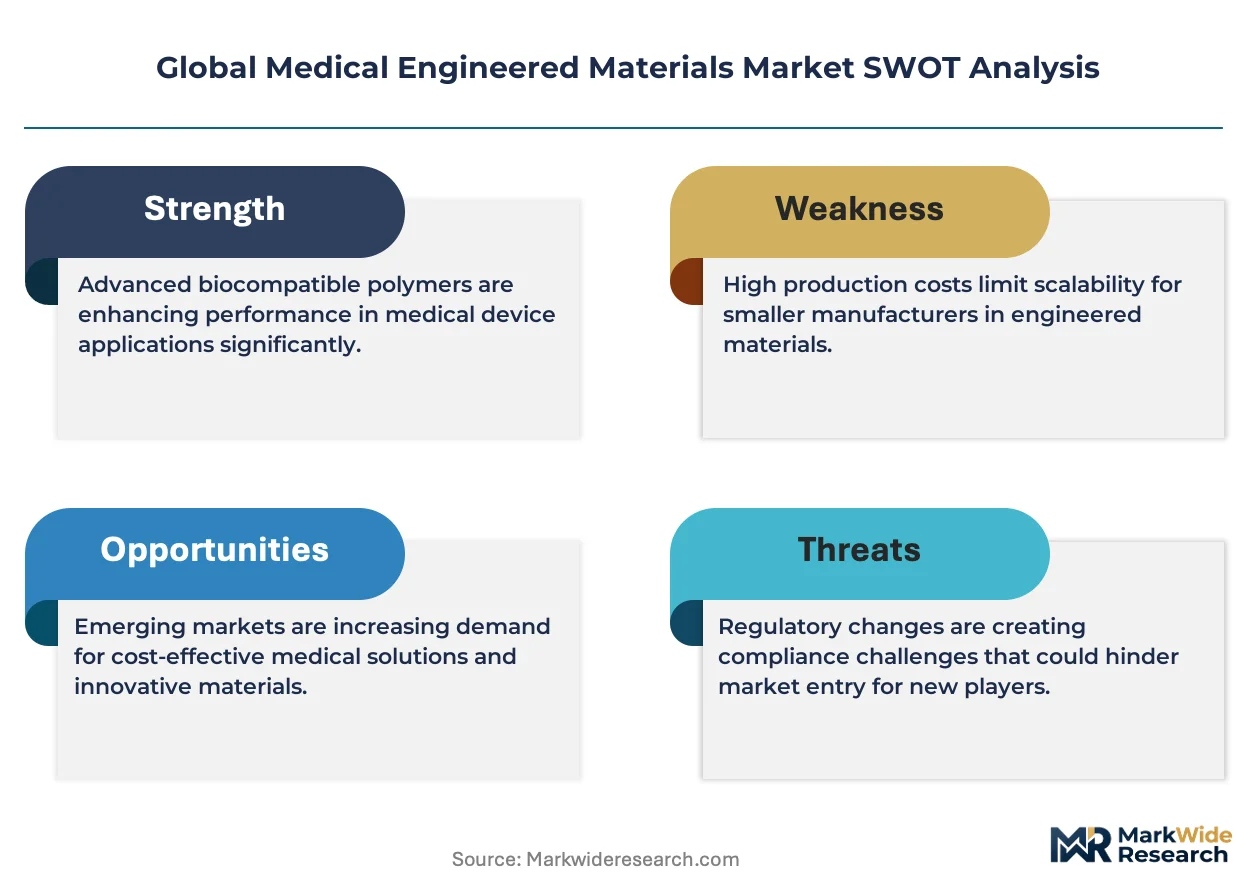
This market is a vertical-integration race where captive monomer supply determines margin defense against Asian feedstock volatility and regulatory requalification costs.
For Market Incumbents: Anchor market position through backward integration into high-purity bisphenol-A production or sulfone monomer synthesis, eliminating Asian feedstock exposure. Prioritize ISO 18562 pre-certification investments ahead of FDA harmonization to capture respiratory device polymer demand. Defend against laser-sintering PEEK specialists by locking exclusive supply agreements with cranial implant OEMs.
For New Entrants and Emerging Players: Enter via Brazil's ANVISA Mercosur harmonization pathway for medical-grade PVC compounders, where incumbent documentation gaps create white-space for USP Class VI-certified entrants. Target São Paulo catheter and tubing manufacturers with citrate-based phthalate replacement formulations ahead of REACH enforcement. Pursue toll-compounding partnerships with established German facilities to bypass 24-month MDR technical documentation backlogs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap ceramic machining specialists in Aichi Prefecture where diamond-grinding infrastructure scarcity concentrates value. Long-term viability centers on orthopedic ceramic demand from aging populations across Japan, Germany, and Italy. Monitor FDA-EMA regulatory harmonization announcements as inflection signals for polymer supplier consolidation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive bisphenol-A production insulates German compounders from Asian force majeure volatility. |
| FDA Master File Investment | Pre-submitted device master files accelerate OEM qualification timelines for implantable polymer grades. |
| Hospital GPO Partnership | Exclusive supply agreements with Rhineland procurement alliances lock in multi-year resin volumes. |
| Laser Sintering Qualification | PEEK-OPTIMA powder certification for patient-specific cranial implants bypasses tooling costs. |
| Citrate Ester Plasticizer Scale-Up | REACH-compliant blood bag formulations capture first-mover advantage in phthalate replacement. |
Research Methodology
Multi-period observation of FDA 510(k) submission volumes, EMA notified body designation changes, and German polymer import customs data anchored the trend analysis, supplemented by interviews with medical device regulatory affairs directors, polymer compounding plant managers, hospital GPO contracts managers, and orthopedic implant procurement leads. Secondary validation drew from FDA 21 CFR Part 820 inspection records, ECHA REACH substance restriction proposals, SEC 10-K resin segment disclosures, and German chemical industry association production statistics. Bottom-up resin consumption modeling triangulated against top-down device production forecasts across the analysis window.
Segment-weighting applied therapy-area procedure volumes, regulatory classification burden coefficients, and material intensity per device type across the projection horizon. Orthopedic, cardiovascular, dental, and wound care segments were modeled separately with end-user procurement consolidation patterns and delivery-mode permanence classifications as cross-cutting dimensions. CAGRs derived from regression against aging-population demographic trajectories, chronic disease prevalence curves, and reimbursement density indices without year-specific endpoint assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden MDR technical documentation requirement changes or gamma-sterilization protocol revisions. Material deviation in FDA-EMA harmonization timelines, Asian petrochemical complex force majeure frequency, or notified body capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Bioactive Materials Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Mushroom Materials Market
Biomaterials
Bone Substitutes Market
Biomaterials
Hydrogel Market
Biomaterials
North America Chitosan Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Global Absorbable Tissue Spacer Market