
 Global Medical Grade Collagen Market | 2026-2036
Global Medical Grade Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Grade Collagen Market Foresight
Recombinant human collagen is decoupling medical device economics from traditional animal sourcing constraints. Gelita AG leverages its century-old gelatin expertise to sustain integrated bovine collagen supply chains across European pharmaceutical corridors. Rousselot anchors premium porcine collagen output through controlled abattoir partnerships in France and Belgium. Nitta Gelatin Inc. dominates Asian marine collagen extraction with proprietary enzymatic hydrolysis protocols refined in Osaka manufacturing facilities.
Medical grade collagen denotes highly purified extracellular matrix protein isolated from mammalian or marine tissues, meeting stringent endotoxin thresholds below 0.5 EU/mL and viral safety validation per ISO 22442 standards. Manufacturers deploy acid-soluble and pepsin-soluble extraction methods to preserve triple-helix integrity for hemostatic and regenerative applications. Bovine collagen retains the largest revenue share in wound care matrices where immunogenicity profiles are well characterized through decades of clinical use. Marine collagen from cod and tilapia sources is expanding fastest in cosmetic surgery injectables as religious and cultural dietary restrictions limit porcine acceptance across Middle Eastern and Southeast Asian patient populations. Lyophilized powder delivery modes command superior margins due to extended shelf stability and customizable reconstitution protocols in hospital pharmacy compounding.
FDA enforces 21 CFR Part 1271 human cell and tissue regulations alongside ISO 22442 for animal tissue-derived medical devices, compelling manufacturers to maintain traceable veterinary health records from source herds. EMA's Medical Device Regulation and EFSA bovine spongiform encephalopathy monitoring protocols add compliance layers for European market access. Japan's PMDA requires viral inactivation validation studies under ICH Q5A guidelines for all xenogeneic collagen implants. Stakeholders must monitor evolving divergence between FDA and EMA standards for residual DNA limits, as harmonization gaps threaten to fragment formulation strategies across Atlantic markets.
Market Dynamics
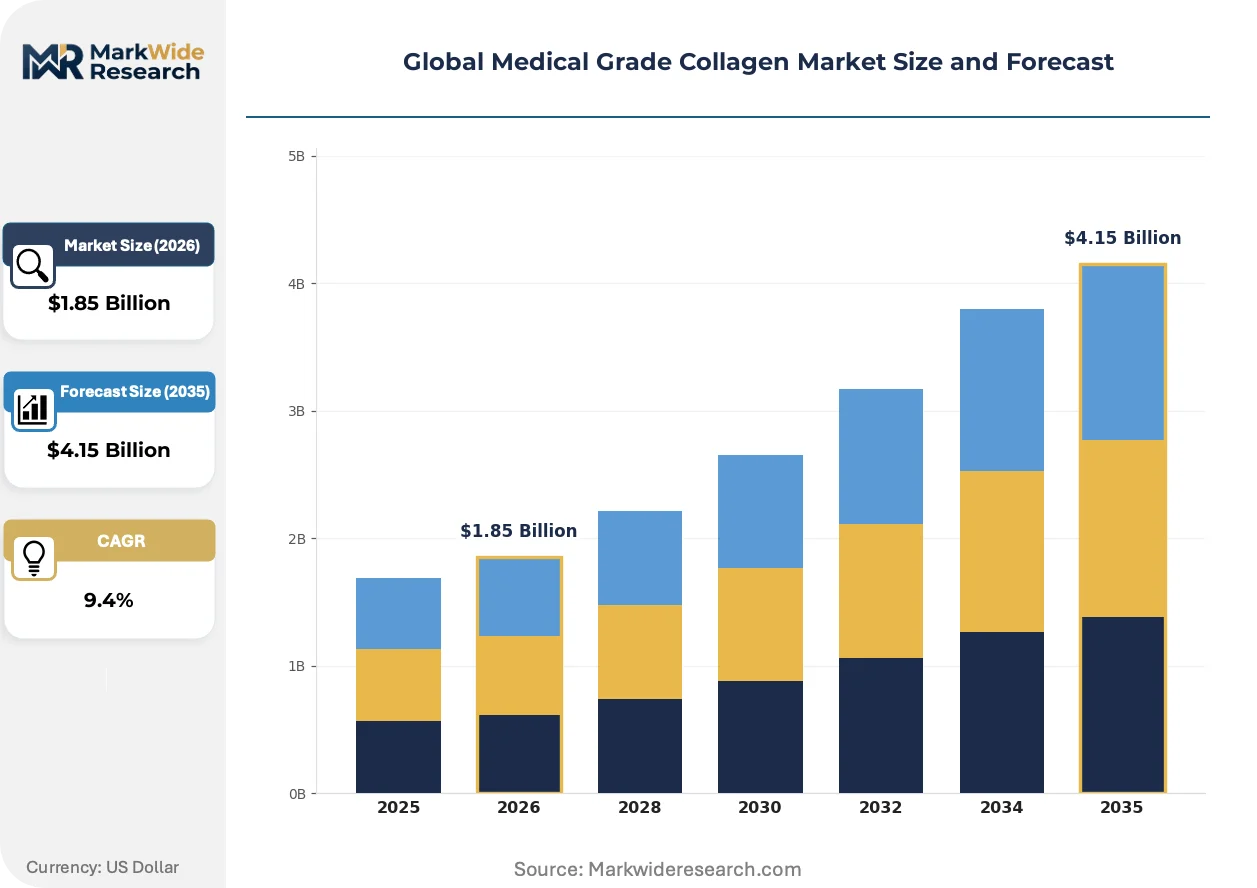
FDA's tightened sourcing documentation under 21 CFR Part 1271 is forcing manufacturers to restructure veterinary traceability systems, while orthopedic demand for biocompatible scaffolds accelerates volume absorption from regenerative medicine protocols.
Growth Catalysts
- EMA Medical Device Regulation:Harmonized CE marking pathways accelerate cross-border commercialization for collagen hemostats and wound matrices across German, French, and Belgian manufacturing corridors.
- Regenerative Orthopedics:Surgical protocol shifts toward extracellular matrix scaffolds in sports medicine and cartilage repair absorb larger bovine and recombinant collagen volumes for rotator cuff and meniscal applications.
- Marine Collagen Enzymatic Hydrolysis:Proprietary extraction protocols from cod and tilapia sources unlock Southeast Asian and Middle Eastern patient pools where religious dietary restrictions exclude porcine alternatives.
Market Restraints
- Bovine Spongiform Encephalopathy Traceability:EFSA monitoring protocols and ISO 22442 viral safety validation impose multi-year veterinary record retention costs on European abattoir partnerships.
- Recombinant Production Scale-Up:Yeast and plant-based expression systems face yield bottlenecks that constrain cost parity with established animal extraction methods for high-volume hemostatic applications.
- Residual DNA Divergence:Non-harmonized limits between FDA and EMA standards fragment formulation strategies, forcing dual-track validation studies for Atlantic market access.
Strategic Opportunities
- Japan PMDA Viral Inactivation Pathway:ICH Q5A validation studies for xenogeneic implants create first-mover advantage for manufacturers establishing Osaka and Tokyo clinical trial partnerships.
- Cosmetic Surgery Injectables:Marine-sourced collagen addresses unmet demand across Gulf Cooperation Council markets where halal certification requirements exclude conventional porcine fillers.
- Lyophilized Compounding Pharmacy Integration:Extended shelf stability and customizable reconstitution protocols enable direct hospital pharmacy supply relationships bypassing traditional distributor markups.
Industry Challenges
- Triple-Helix Preservation Expertise:Acid-soluble and pepsin-soluble extraction methods require specialized biochemical engineering talent scarce outside established gelatin manufacturing regions.
- Endotoxin Threshold Compliance:Sub-0.5 EU/mL purification demands capital-intensive chromatography and filtration infrastructure that mid-scale entrants struggle to amortize across limited product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Grade Collagen Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bovine Collagen, Porcine Collagen, Marine Collagen, Chicken Collagen Application: Wound Care, Tissue Engineering, Drug Delivery, Cosmetic Surgery End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Laboratories Delivery Mode: Injectables, Implants, Topical Gels, Lyophilized Powders |
| Companies Covered | Gelita AG, Rousselot, Nitta Gelatin Inc., Weishardt Group, Advanced BioMatrix, Inc., Collagen Matrix, Inc., Collagen Solutions Plc, Integra LifeSciences Corporation, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Grade Collagen Market Shifts & Advancements
Electrospun nanofiber collagen scaffolds are compressing healing timelines in chronic wound protocols, while regulatory divergence between FDA and EMA residual DNA standards forces parallel validation investments.
Recombinant human collagen expression systems are electrifying supply security for implantable device manufacturers. Biopharmaceutical contract manufacturers in Germany and Switzerland are adopting microbial and plant-based platforms at pilot scale. This electrifying shift enables decoupling from bovine and porcine sourcing constraints that dominate traditional extraction economics.
EMA's updated Medical Device Regulation enforcement through notified bodies in France and Germany is tightening post-market surveillance for animal-derived implants. Manufacturers now face unannounced audits of veterinary health records from source herds. Wound care matrix suppliers with integrated European abattoir partnerships are absorbing compliance costs faster than import-dependent competitors.
Hospital pharmacy compounding of lyophilized collagen powders is displacing pre-mixed syringe procurement in United States academic medical centers. Surgical suites in Boston, Houston, and Stanford clusters now specify customizable reconstitution protocols for hemostatic applications. This channel shift concentrates purchasing influence among pharmacy formulary committees and away from traditional surgical distributor networks.
Global Medical Grade Collagen Market Segmentation
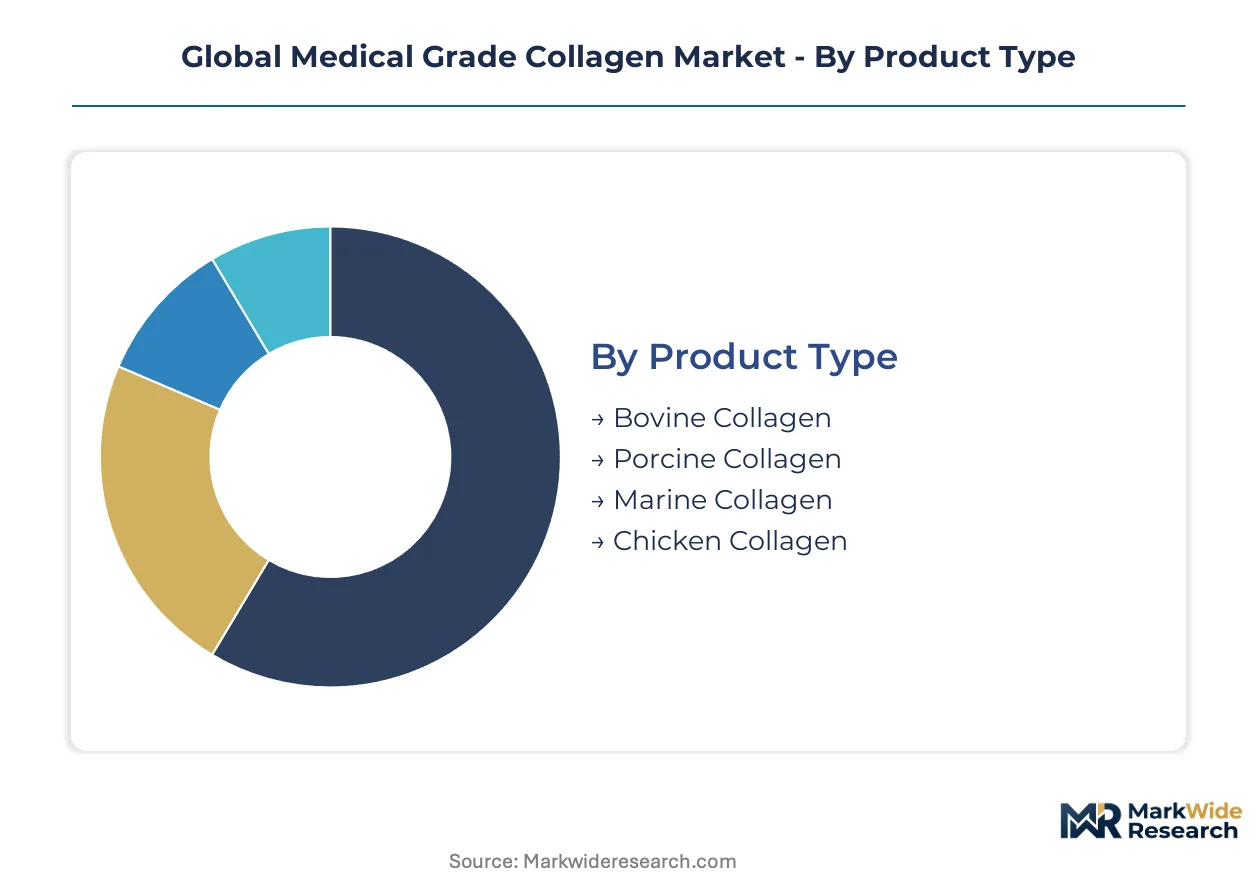
Medical grade collagen procurement patterns diverge sharply across sourcing species, clinical application, and institutional setting. Manufacturers configure extraction protocols and purification investments around the specific endotoxin thresholds and triple-helix integrity demands of each segment.
Product Type:
Species origin determines immunogenicity profiling costs, religious market access, and supply chain traceability burdens for buyers.
- Bovine Collagen:Acid-soluble and pepsin-soluble extraction from cattle hides and tendons yields hemostatic matrices with decades of FDA-validated safety data. Demand concentrates in United States orthopedic centers where EFSA BSE monitoring protocols and ISO 22442 viral validation have established trusted sourcing corridors from controlled German and Belgian abattoirs.
- Marine Collagen:Proprietary enzymatic hydrolysis of cod and tilapia skins preserves bioactive peptides for cosmetic injectables. Japanese and Southeast Asian manufacturers in Osaka and Singapore absorb largest volumes as halal certification requirements across Gulf Cooperation Council states exclude porcine alternatives.
- Porcine Collagen:Controlled French and Belgian abattoir partnerships yield premium dermal matrices with superior elasticity profiles for wound closure applications.
- Chicken Collagen:Avian sternal cartilage extraction supplies niche cartilage repair scaffolds in Korean and Taiwanese research corridors.
Bovine collagen leads volumes today; marine collagen is gaining share fastest.
Application:
Clinical use case dictates required purity grades, sterilization protocols, and reimbursement pathway complexity.
- Wound Care:Hemostatic sponges and chronic wound matrices absorb the largest bovine collagen volumes as United States hospital pharmacy formularies standardize on lyophilized formats with customizable reconstitution protocols.
- Cosmetic Surgery:Dermal fillers and reconstructive matrices command premium pricing as Gulf Cooperation Council and Southeast Asian clinics specify marine-sourced alternatives to satisfy religious dietary restrictions.
- Tissue Engineering:Electrospun nanofiber scaffolds for cartilage and tendon regeneration require triple-helix integrity preservation that concentrates demand among German and Swiss contract manufacturers with specialized biochemical engineering talent.
- Drug Delivery:Collagen-based microparticles and hydrogels for controlled release applications serve specialized compounding pharmacies in Boston and Stanford academic medical clusters.
Wound care leads volumes today; cosmetic surgery climbs the fastest.
End User:
Procurement scale and technical specification authority vary dramatically across institutional buyer types.
- Hospitals:Academic medical centers in Houston and Stanford clusters now specify direct lyophilized powder procurement for pharmacy compounding, bypassing traditional surgical distributor networks and concentrating purchasing influence among formulary committees.
- Ambulatory Surgical Centers:Outpatient facilities absorb pre-mixed injectable and implant formats where shelf stability and single-use packaging reduce inventory complexity.
- Research Laboratories:Osaka and Tokyo tissue engineering clusters drive pilot-scale demand for recombinant human collagen expression systems.
- Diagnostic Centers:Specialized imaging and biopsy applications utilize collagen-based contrast agent carriers in limited volumes.
Hospitals lead volumes today; ambulatory surgical centers are expanding most quickly.
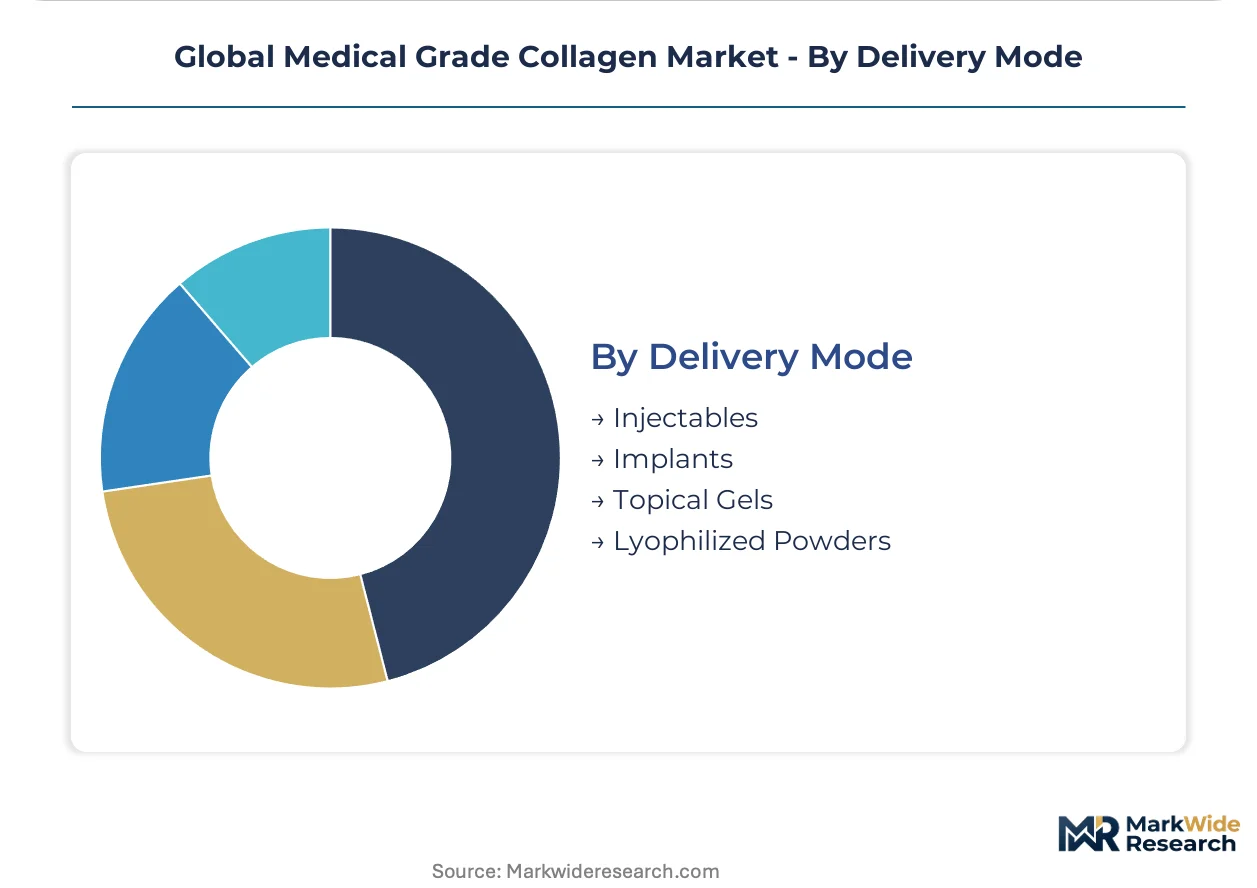
Delivery Mode:
Format selection determines shelf stability, margin structure, and channel access strategy for manufacturers.
- Lyophilized Powders:Extended stability and customizable reconstitution enable direct hospital pharmacy relationships with superior margin capture compared to pre-mixed alternatives.
- Injectables:Pre-filled syringes for cosmetic and orthopedic applications serve Gulf Cooperation Council and Japanese clinics requiring ready-to-use formats.
- Implants:Solid matrices for hernia repair and periodontal applications demand EMA MDR-compliant post-market surveillance infrastructure.
- Topical Gels:Burn care and dermatological applications utilize lower-purity grades with reduced endotoxin thresholds.
Lyophilized powders lead volumes today; injectables show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Houston-Stanford corridor commands United States wound care procurement as academic medical centers shift lyophilized collagen purchasing toward pharmacy formulary committees. FDA's 21 CFR Part 1271 enforcement tightens veterinary traceability documentation across implantable device supply chains. Germany anchors European bovine collagen extraction through controlled abattoir partnerships in Bavaria and North Rhine-Westphalia.
United States
Orthopedic centers in Houston and Stanford absorb expanding volumes of bovine-derived scaffolds for rotator cuff regeneration protocols. FDA enforces heightened sourcing documentation under 21 CFR Part 1271, compelling manufacturers to maintain multi-year veterinary health records. Massachusetts General and Mayo Clinic pharmacy committees now specify direct lyophilized powder procurement, bypassing traditional surgical distributor networks.
Germany
Bavarian gelatin manufacturers supply acid-soluble collagen to wound care matrix producers across the Rhine-Main pharmaceutical corridor. EMA Medical Device Regulation and EFSA bovine spongiform encephalopathy monitoring protocols impose traceability burdens on abattoir partnerships. Heidelberg and Freiburg tissue engineering clusters drive pilot-scale demand for electrospun nanofiber scaffolds requiring triple-helix integrity preservation.
Japan
Osaka manufacturers refine proprietary enzymatic hydrolysis protocols for marine collagen extraction from cod and tilapia sources. PMDA requires viral inactivation validation studies under ICH Q5A guidelines for all xenogeneic collagen implants. Tokyo academic medical centers partner with domestic suppliers to establish first-mover positions in recombinant human collagen expression systems.
France
Rousselot anchors premium porcine collagen output through controlled abattoir partnerships in the Champagne-Ardenne region. ANSM enforces EMA MDR post-market surveillance through unannounced audits of veterinary health records. Lyon and Paris cosmetic surgery clinics specify marine-sourced alternatives to satisfy Gulf Cooperation Council halal certification requirements for export-bound filler products.
United Kingdom
Cambridge and Oxford research corridors drive demand for recombinant collagen expression systems in regenerative medicine applications. MHRA alignment with EMA MDR standards streamlines CE marking pathways for collagen hemostats. London teaching hospitals concentrate purchasing influence among pharmacy formulary committees following the United States lyophilized powder procurement model.
Global Medical Grade Collagen Market Competitive Landscape
Global majors compete with regional champions across sourcing species and extraction methodology specialization. The vendor base stratifies between century-old gelatin manufacturers with integrated abattoir partnerships and biotechnology entrants developing recombinant expression platforms. Three archetypes dominate: integrated animal-derived processors, marine collagen enzymatic hydrolysis specialists, and recombinant human collagen platform developers. Capacity expansion in controlled abattoir networks and strategic partnerships for viral validation services constitute the primary competitive moves.
Within the integrated processor tier, Gelita AG exemplifies the century-old gelatin expertise archetype, while Rousselot occupies a position bridging French abattoir control with premium dermal matrix output. Nitta Gelatin Inc. represents the marine enzymatic hydrolysis specialist model refined in Osaka manufacturing facilities. These three anchors demonstrate how geographic proximity to source species and regulatory familiarity create defensible positioning against recombinant platform entrants.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| Nitta Gelatin Inc. |
| Weishardt Group |
| Advanced BioMatrix, Inc. |
| Collagen Matrix, Inc. |
| Collagen Solutions Plc |
| Integra LifeSciences Corporation |
| DSM |
| Others |
Supply & Pricing Matrix
Captive abattoir partnerships in Bavaria and Champagne-Ardenne anchor supply security and pricing power for integrated collagen processors, insulating them from spot-market volatility that squeezes import-dependent competitors.
Pricing Analysis
Input-cost pass-through from veterinary traceability compliance and chromatography infrastructure anchors contract-based long-term offtake structures. Price differentiation rests on ISO 22442 certification tier and endotoxin grade, with sub-0.5 EU/mL premium lots commanding substantial spreads over standard grades. Cost compression in mid-tier bovine collagen is intensifying as German and Belgian abattoir partnerships absorb EFSA BSE monitoring burdens faster than peripheral suppliers. Hospital pharmacy committees show lowest price sensitivity due to formulary control, while ambulatory surgical centers face acute margin pressure from distributor markups.
Supply Chain Analysis
Workforce availability in specialized biochemical engineering constrains capacity expansion in German, Swiss, and Japanese manufacturing corridors. Supply concentrates in Germany, Japan, and France, with raw material dependencies on controlled cattle herds, cod and tilapia skins, and pepsin enzyme supplies. Single-source vulnerability runs through the limited pool of abattoirs maintaining decade-long veterinary health records under FDA 21 CFR Part 1271. Distribution runs through direct hospital pharmacy relationships for lyophilized powders and surgical distributor networks for pre-mixed formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical grade collagen rests on lyophilized powder adoption shifting procurement toward pharmacy formulary committees, capturing distributor bypass savings and premium-tier positioning.
For Market Incumbents: Extend captive abattoir control through multi-year veterinary traceability contracts in Bavaria and Champagne-Ardenne, insulating against recombinant platform entrants. Deepen backward integration into pepsin-soluble extraction capacity to defend cost position as EMA MDR audit frequency intensifies. Prioritize Osaka and Tokyo clinical trial partnerships for PMDA viral inactivation validation to lock out Asian challengers. For New Entrants and Emerging Players: Hospital pharmacy compounding relationships offer the most penetrable channel, bypassing entrenched surgical distributor networks in Houston and Stanford clusters. Target Gulf Cooperation Council cosmetic surgery clinics with halal-certified marine collagen injectables, exploiting religious dietary restrictions that exclude incumbent porcine portfolios. Lead with customizable reconstitution protocols and extended shelf stability guarantees to differentiate from pre-mixed alternatives. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale enzymatic hydrolysis specialists because fragmented marine collagen extraction in Southeast Asia lacks integrated purification infrastructure. Long-term viability centers on recombinant human collagen platforms decoupling from animal sourcing constraints. Watch for FDA-EMA residual DNA harmonization failure as the inflection signal forcing dual-track validation investments that favor well-capitalized consolidators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR harmonization accelerates cross-border commercialization for collagen hemostats in French and German manufacturing corridors. |
| Hospital System Partnership | Direct lyophilized powder procurement with Massachusetts General and Mayo Clinic pharmacy committees bypasses distributor markups. |
| Backward Integration | Controlled abattoir partnerships in Bavaria secure multi-year veterinary traceability records under tightening FDA 21 CFR Part 1271 enforcement. |
| Reimbursement Strategy | Rotator cuff and meniscal scaffold protocols in orthopedic centers expand addressable volumes through regenerative medicine coverage expansion. |
| Regulatory Approval Pathway | ICH Q5A viral inactivation validation with PMDA creates first-mover positioning in Tokyo and Osaka tissue engineering clusters. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, secondary validation through FDA 510(k) filings and EMA MDR submissions, and trade data reconciliation — were triangulated against bottom-up volume builds and top-down market sizing. Conversations with GPO contracts managers, formulary directors, and gelatin manufacturing executives informed procurement pattern and pricing dynamics assessment. Secondary sources included ISO 22442 certification databases, hospital procurement records, and customs data on collagen peptide trade flows.
Data-stream reconciliation across species origin, application, and delivery mode dimensions shaped the analytical framework throughout the projection horizon. Segmentation modeling captured product type, clinical use case, institutional buyer, and geographic regulatory cluster variations. CAGRs were derived from weighted average growth trajectories across orthopedic scaffold absorption, cosmetic injectable expansion, and wound care matrix standardization trends, with viral validation timeline assumptions and recombinant platform scale-up curves as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA-EMA residual DNA harmonization gaps, recombinant production yield breakthroughs, and Gulf Cooperation Council halal certification adoption rates. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Hydrogel Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
US Heparin Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Scaffold Materials Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Biomaterials Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Pulp Cells Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Global Bioactive Materials Market