
 Global Implantable Biomaterial Market | 2026-2036
Global Implantable Biomaterial Market Size, Share, and Industry Trends Forecast 2026-2036
Global Implantable Biomaterial Market Foresight
Hospital procurement groups are reorganizing purchasing criteria around long-term implant performance and supplier certification depth. Medtronic leverages its cardiovascular implant portfolio to sustain premium positioning in polymer-based stent coatings. Johnson & Johnson anchors its orthopedic biomaterial supply through captive manufacturing networks. Zimmer Biomet differentiates via ceramic-on-ceramic bearing surfaces for hip reconstruction.
Implantable biomaterials encompass engineered substances designed for long-term integration with human tissue, including titanium alloys with porous surface architectures, hydroxyapatite-reinforced polyethylene composites, and cross-linked collagen scaffolds manufactured through electrospinning or 3D bioprinting processes. These materials serve to restore mechanical function, enable cellular infiltration, and minimize foreign body response in permanent or resorbable medical devices. Metal formulations dominate joint replacement applications due to fatigue resistance and osseointegration properties, while hydrogel segments expand fastest in tissue engineering as injectable delivery platforms gain clinical traction. Ceramic categories command margin concentration in dental implant abutments where aesthetic outcomes justify material premiums.
The FDA enforces biocompatibility standards under ISO 10993 guidelines for permanent implant contact devices, while the EU Medical Device Regulation mandates clinical evaluation reports and post-market surveillance for all class III implantable products. Japan's PMDA requires additional local bridging studies for novel biomaterial compositions, extending time-to-market for foreign manufacturers. Stakeholders must monitor evolving regenerative medicine classifications as cell-laden scaffolds blur boundaries between devices and advanced therapy medicinal products across jurisdictions.
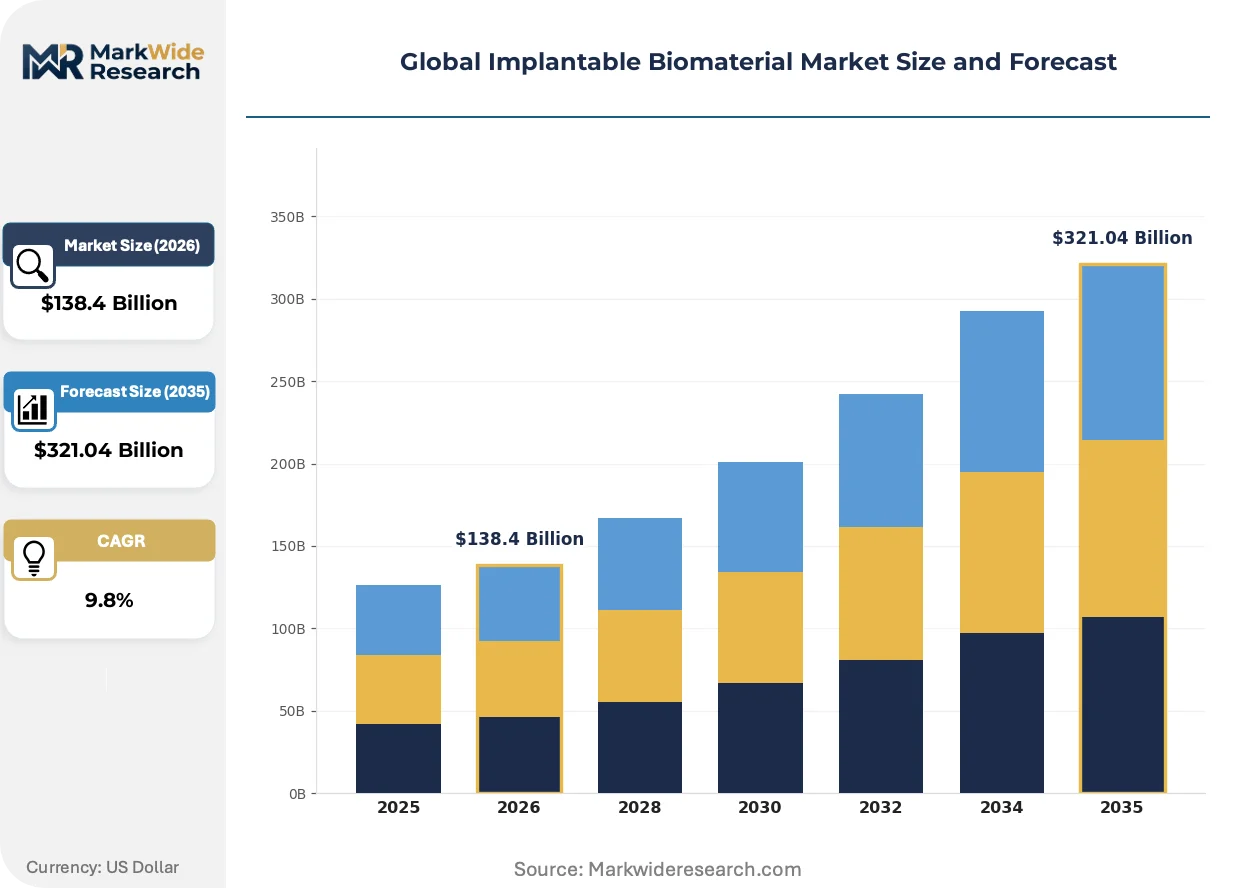
Market Dynamics
The implantable biomaterial sector is restructuring around polymer-ceramic hybrid formulations as orthopedic and cardiovascular OEMs phase out pure metal constructs in favor of modulus-matched composites that reduce stress shielding and extend implant longevity.
Growth Catalysts
- EU MDR biocompatibility mandates:The Medical Device Regulation's tightened testing protocols for permanent implant contact devices compel manufacturers to upgrade material characterization capabilities, accelerating certified supplier consolidation.
- Electrospun nanofiber scaffolds:Tissue engineering applications in Germany and China are absorbing collagen-polymer matrices for rotator cuff and cartilage repair, expanding addressable procedure volumes.
- Japan's PMDA bridging study requirements:Local clinical data mandates for novel compositions extend development timelines but create captive market positions for compliant foreign entrants.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese smelters control over 60% of aerospace-grade titanium feedstock, exposing implant manufacturers to alloy price volatility and export restriction risk.
- Cross-linked polyethylene oxidation:Gamma sterilization-induced free radical generation limits shelf life and complicates inventory management for hip bearing manufacturers.
- Silicone gel substitution in soft tissue:Hydrogel alternatives for breast and facial reconstruction are capturing volume in elective procedures, compressing traditional silicone implant margins.
Strategic Opportunities
- India's CDSCO fast-track pathway:The regulator's abbreviated review for materials with US FDA or EU MDR approval enables accelerated entry into joint replacement markets with localized cost structures.
- 3D bioprinted patient-specific scaffolds:Convergence of additive manufacturing with autologous cell seeding is opening orthopedic and maxillofacial applications previously served by off-the-shelf implants.
- Direct-to-hospital biomaterial consignment:Implant manufacturers are bypassing distributor networks to place inventory directly in US and German hospital sterile processing departments, capturing margin and utilization data.
Industry Challenges
- Biomaterial-tissue interface modeling:Computational simulation of foreign body response and fibrous encapsulation requires scarce expertise in multiphysics and immunology, constraining predictive design cycles.
- ISO 10993-18 chemical characterization backlog:Third-party toxicology laboratories face 12-18 month queues for extractables and leachables testing, delaying regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Implantable Biomaterial Market |
| Market Size in 2026 | $138.4 Billion |
| Market Size in 2035 | $321.04 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymer, Ceramic, Metal, Composite, Hydrogel Application: Orthopedic Devices, Cardiovascular Implants, Dental Implants, Tissue Engineering, Wound Care End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Research Institutions Product Form: Powder, Sheets, Fibers, Scaffolds, Coatings |
| Companies Covered | Medtronic, Johnson & Johnson, Zimmer Biomet, Stryker Corporation, BASF SE, Abbott Laboratories, Boston Scientific Corporation, Smith & Nephew, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Implantable Biomaterial Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing development cycles while fragmenting competitive positions between integrated material suppliers and specialized coating technology firms.
Surface-modified titanium alloys with porous trabecular architectures are bifurcating the joint replacement market. Orthopedic OEMs in the United States and Germany are adopting these constructs for revision hip and knee cases where osseointegration failure rates run highest. The technology is compressing market share for conventional plasma-sprayed coatings while elevating pricing power for suppliers with electron beam melting capabilities.
REACH restrictions on cobalt compounds are forcing reformulation of chromium-cobalt bearing alloys used in metal-on-metal hip constructs. The European Chemicals Agency's 2023 classification of cobalt as a Category 1B carcinogen triggered supply chain audits and alternative material qualification programs. Ceramic-on-ceramic and oxidized zirconium bearings are capturing volume in EU markets while US hospitals lag in substitution pace due to divergent liability exposure.
Hospital value analysis committees are consolidating vendor relationships around suppliers with vertically integrated quality systems. The purchasing pattern is displacing fragmented multi-source arrangements for standard implants in US metropolitan health systems. Academic medical centers in Boston and Cleveland are piloting single-source partnerships for polymer and ceramic bearing categories, transferring inventory risk to manufacturers through consignment structures.
Global Implantable Biomaterial Market Segmentation
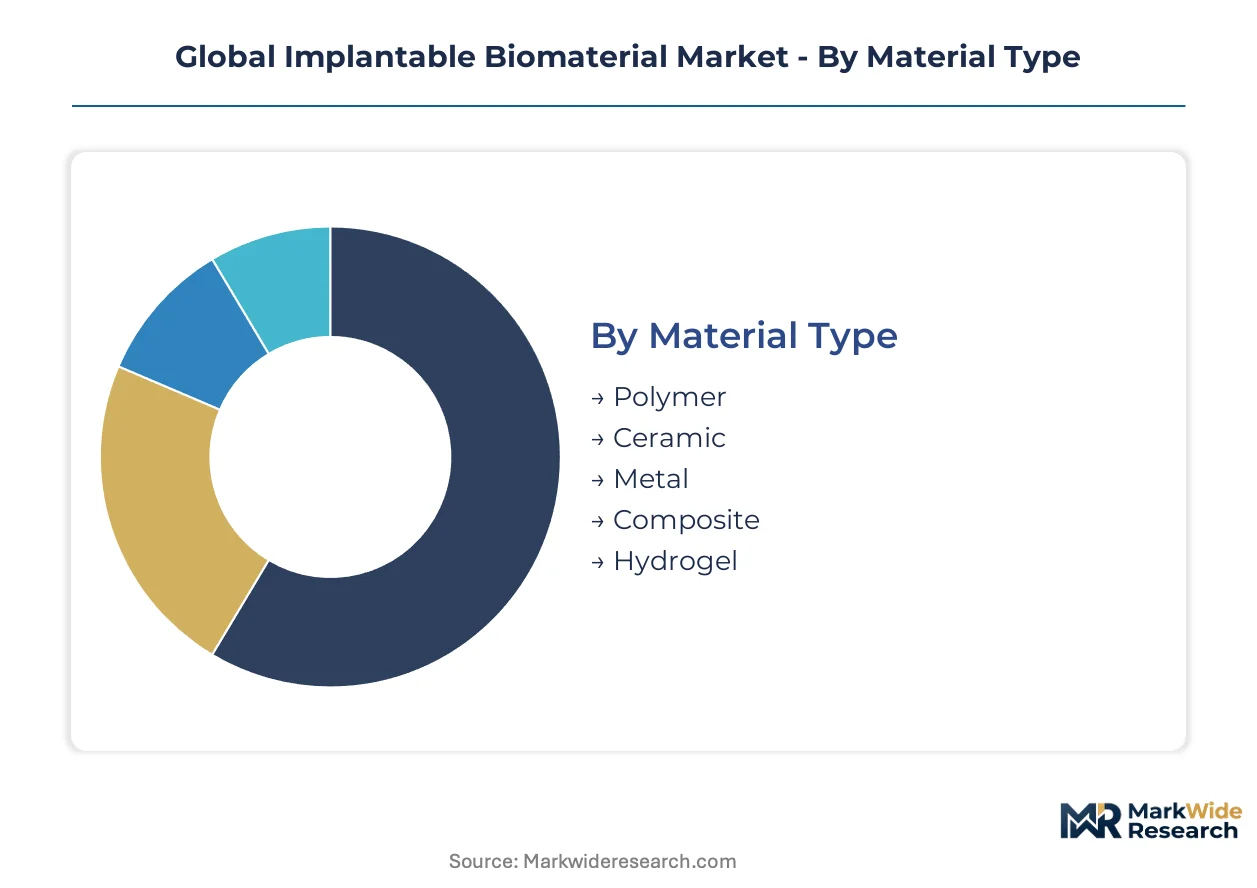
Segmentation in implantable biomaterials reveals how procurement channels, clinical workflows, and manufacturing constraints fragment demand across material grades and product geometries. Orthopedic OEMs, cardiovascular device firms, and hospital value analysis committees each impose distinct technical and commercial filters on supplier selection.
Material Type:
Channel flow diverges sharply: metals and ceramics move through long-term supply agreements with orthopedic OEMs, while hydrogels and select polymers reach hospitals via distributor networks for tissue engineering applications.
- Metal:Titanium alloys with porous surface architectures dominate fatigue-critical joint replacement applications. Demand concentrates in the United States and Germany where revision hip and knee volumes sustain premium pricing for electron beam melted constructs. OEMs qualify suppliers on ISO 10993-5 cytotoxicity pass rates and electron microscopy pore consistency.
- Polymer:Cross-linked polyethylene and PEEK formulations serve bearing surfaces and spinal fusion cages. Cardiovascular stent coating applications in Germany absorb specialized polymer grades with controlled degradation profiles. Procurement runs through consignment arrangements with US metropolitan health systems.
- Ceramic:Alumina and zirconia command margin concentration in dental implant abutments and hip bearing couples. REACH-driven cobalt substitution in the EU accelerates ceramic-on-ceramic qualification programs.
- Hydrogel:Injectable collagen and synthetic matrices expand in rotator cuff repair. Distribution flows through specialty clinic networks in China and Germany.
- Composite:Hydroxyapatite-reinforced polyethylene and polymer-ceramic hybrids reduce stress shielding in spinal and craniomaxillofacial plates. Development partnerships between material suppliers and 3D printing equipment manufacturers concentrate in the United States.
By volume, metal leads. By growth pace, hydrogel is ahead.
Application:
Cost tier stratification separates high-volume standard implants from patient-specific constructs, with tissue engineering commanding R&D premiums and wound care operating at compressed margins.
- Orthopedic Devices:Joint replacement, spinal fusion, and trauma fixation absorb the majority of titanium and polyethylene volumes. US and German hospital procurement groups consolidate vendor relationships around suppliers with captive forging and sterilization capabilities.
- Cardiovascular Implants:Stent coatings, pacemaker leads, and structural heart devices require polymer formulations with thromboresistant surface chemistries. FDA biocompatibility testing queues extend development timelines for novel compositions.
- Dental Implants:Titanium root fixtures and ceramic abutments serve aesthetic-driven elective procedures. Margin concentration justifies material premiums in Germany and Switzerland.
- Tissue Engineering:Electrospun scaffolds and 3D bioprinted matrices for cartilage and bone regeneration attract venture funding in Boston and Cleveland academic medical centers.
- Wound Care:Collagen dressings and antimicrobial hydrogels compete on cost in ambulatory settings. Distribution runs through group purchasing organizations with standardized formularies.
Orthopedic devices capture the largest revenue pool. Tissue engineering exhibits the steepest expansion trajectory.
End User:
Customer type determines packaging, sterilization validation, and inventory management requirements, with hospitals demanding consignment structures and research institutions accepting developmental material grades.
- Hospitals:Sterile processing departments in US metropolitan systems pilot single-source partnerships for bearing categories. Value analysis committees transfer inventory risk to manufacturers through direct consignment.
- Specialty Clinics:Orthopedic and dental practices in Germany absorb ceramic and polymer implants through distributor networks with same-day delivery guarantees.
- Ambulatory Surgery Centers:Cost pressure drives standard implant selection with limited customization. Group purchasing organization contracts dominate procurement.
- Research Institutions:Preclinical and clinical trial material supply requires batch-specific characterization data. CDSCO fast-track pathways in India attract contract research organization activity.
Hospitals account for the dominant procedure volume. Specialty clinics are gaining share fastest in elective dental and facial reconstruction.
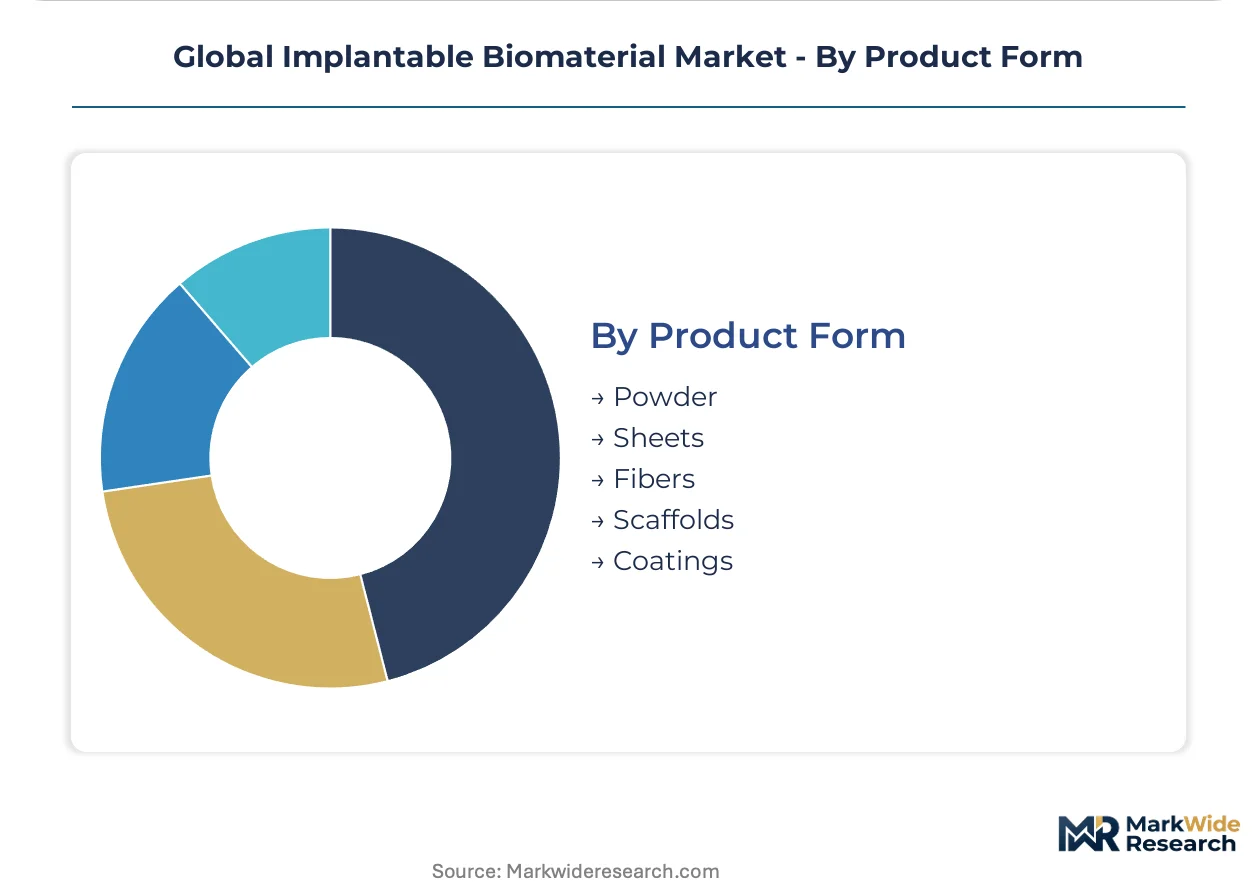
Product Form:
Manufacturing maturity separates commodity powder and sheet supply from specialized scaffold and coating capabilities with captive equipment requirements.
- Scaffolds:Electrospun nanofiber and 3D bioprinted architectures enable cellular infiltration in tissue engineering. Electron beam melting and selective laser sintering equipment concentration in the United States and Germany limits supplier entry.
- Coatings:Plasma-sprayed hydroxyapatite and polymer-based drug-eluting layers extend implant longevity. Porous trabecular titanium constructs are displacing conventional coating approaches in revision joint cases.
- Powder:Titanium and ceramic feedstocks for additive manufacturing face supply concentration from Russian and Chinese smelters. Aerospace-grade specification crossover exposes medical device firms to export restriction risk.
- Sheets:Collagen and synthetic membranes serve guided bone regeneration in dental and orthopedic applications. Gamma sterilization-induced oxidation limits shelf life.
- Fibers:Suture materials and textile scaffolds for ligament reconstruction compete on tensile strength and degradation profile matching.
Coatings lead by installed implant base. Scaffolds are climbing the fastest as patient-specific additive manufacturing gains clinical traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision ceramic bearings to US hospital systems while Chinese titanium processors supply alloy feedstock to orthopedic OEMs worldwide. Trade corridors link material science clusters with surgical implant demand centers across three continents.
United States
Revision hip and knee procedures drive titanium alloy consumption in metropolitan health systems. FDA biocompatibility testing under ISO 10993 guidelines extends clearance timelines for novel compositions. Boston academic medical centers pilot single-source partnerships for polymer bearing categories through direct consignment structures.
Germany
Electrospun nanofiber scaffolds for rotator cuff repair absorb collagen-polymer matrices from specialized suppliers. ECHA REACH restrictions on cobalt compounds force chromium-cobalt bearing reformulations. Stuttgart and Leipzig industrial clusters concentrate electron beam melting capabilities for porous titanium constructs.
China
Joint replacement volume expansion sustains demand for imported ceramic bearing couples and domestic titanium processing. NMPA registration pathways require local clinical data for novel biomaterial compositions. Yangtze River Delta manufacturers scale additive manufacturing feedstock production for export markets.
Japan
Pacemaker lead and structural heart device coatings require polymer formulations with thromboresistant surface chemistries. PMDA bridging study mandates extend development timelines for foreign entrants. Osaka medical device clusters maintain captive supply relationships with domestic material specialists.
India
CDSCO fast-track pathways for materials with US FDA or EU MDR approval accelerate joint replacement market entry. Maharashtra and Gujarat contract research organizations absorb preclinical biomaterial testing activity. Localized cost structures attract orthopedic OEMs seeking manufacturing diversification.
Global Implantable Biomaterial Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and captive manufacturing scale. The vendor base separates into integrated material suppliers with in-house forging capabilities and specialized coating technology firms with proprietary surface modification IP. Three archetypes dominate: diversified healthcare conglomerates with orthopedic portfolios, pure-play biomaterial specialists, and chemical majors with medical-grade polymer divisions. Competitive moves concentrate on strategic partnerships for 3D bioprinting capabilities and backward integration into titanium alloy feedstock.
Within the diversified healthcare tier, Medtronic and Johnson & Johnson exemplify integrated players with cardiovascular and orthopedic anchoring positions. Zimmer Biomet occupies a specialist position in ceramic-bearing surface technology. Among chemical and materials majors, BASF SE and Evonik Industries AG represent European-based suppliers with medical-grade polymer portfolios. These five entities span distinct competitive vectors: implant OEM integration, material science depth, and geographic manufacturing footprint.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Stryker Corporation |
| BASF SE |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Smith & Nephew |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Electron beam melting capacity utilization in Stuttgart and Leipzig industrial clusters shapes both titanium alloy availability floors and premium pricing for porous trabecular constructs. Scale concentration among German additive manufacturing equipment operators compresses margin negotiation space for orthopedic OEMs while elevating entry barriers for secondary suppliers.
Pricing Analysis
Prior-generation plasma-sprayed hydroxyapatite coatings trade at commodity rates against electron beam melted titanium premiums and next-generation polymer-ceramic hybrid price points still in clinical trial markup. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-5 certified suppliers from uncertified feedstock vendors and hospital-direct consignment partners. Pricing pressure stems from hydrogel substitution in soft tissue applications, compressing traditional silicone implant margins. Ambulatory surgery centers exhibit highest price sensitivity through group purchasing organization contracts, while academic medical centers in Boston and Cleveland absorb premium tiers for patient-specific scaffolds.
Supply Chain Analysis
Russia and China control aerospace-grade titanium sponge smelting, feeding German electron beam melting clusters and US orthopedic OEM forging operations. Medical device alloy production draws from concentrated feedstock sources, with cross-linked polyethylene resin supply anchored in Saudi petrochemical complexes and ceramic powder processing concentrated in Japanese industrial ceramics specialists. Single-source vulnerability runs through Russian export restriction exposure on titanium sponge. Distribution runs through direct-to-hospital consignment arrangements in US metropolitan health systems and distributor networks for German specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
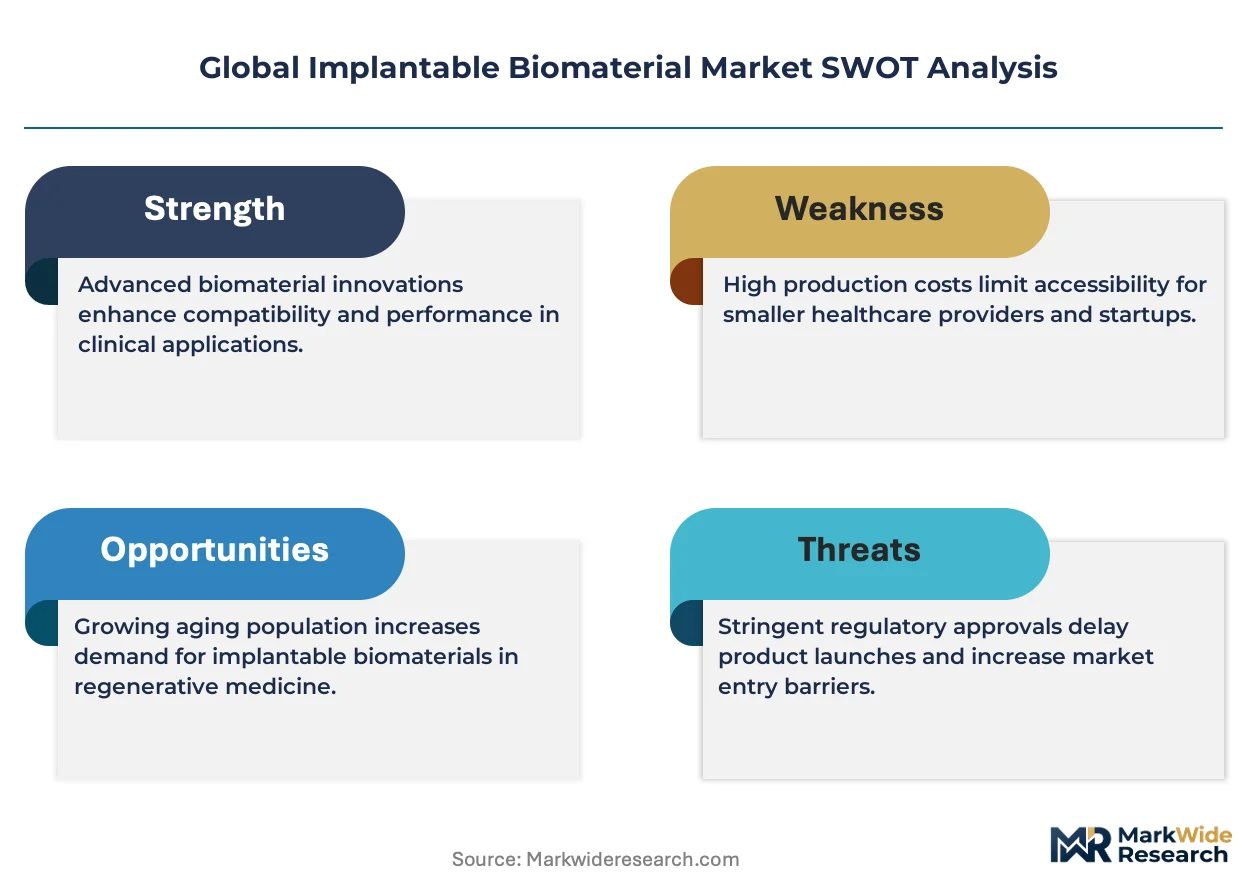
Regulatory entrenchment around ISO 10993 biocompatibility certification and EU MDR clinical evaluation requirements creates durable defensive moats for qualified suppliers. Switching costs for orthopedic OEMs amplify incumbent advantage.
For Market Incumbents: Secure captive titanium alloy feedstock arrangements through backward integration into sponge processing or long-term offtake contracts with Russian and Chinese smelters. Deepen electron beam melting capacity in Germany to preempt porous construct supply shortages. Hydrogel substitution in soft tissue reconstruction threatens silicone implant margins, demanding accelerated polymer-ceramic hybrid R&D investment. For New Entrants and Emerging Players: Post-market surveillance data aggregation services represent an under-served layer where incumbents lack dedicated platforms, creating white-space for specialized analytics vendors. India's CDSCO fast-track pathway offers the most penetrable regulatory entry point for materials with existing US FDA or EU MDR approval. Target contract research organizations in Maharashtra and Gujarat with preclinical testing partnerships as the anchor go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive manufacturing equipment operators with medical-grade certification and electrospun scaffold specialists with autologous cell seeding capabilities. Five-to-ten year viability hinges on regulatory harmonization momentum and biomaterial-tissue interface modeling breakthroughs. Acquisition targets should display ISO 10993-18 chemical characterization completion and electron microscopy pore consistency validation. The inflection signal to watch is FDA clearance velocity for 3D bioprinted patient-specific constructs.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evaluation Completion | Unlocks European market access for Class III implantable products ahead of competitors. |
| Backward Integration into Titanium Sponge | Reduces exposure to Russian and Chinese export restriction volatility. |
| Hospital System Direct Consignment | Captures margin and utilization data from US metropolitan health systems. |
| Electrospun Scaffold Platform Expansion | Addresses rotator cuff and cartilage repair demand in Germany and China. |
| CDSCO Fast-Track Registration | Accelerates joint replacement market entry through India's abbreviated review pathway. |
Research Methodology
The analysis maps metal alloy, polymer, ceramic, hydrogel, and composite sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists. Primary interviews with orthopedic OEM procurement leads and additive manufacturing equipment operators combined with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation reports, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include material type, application category, end-user archetype, and product form geometry. CAGRs derived from procedure volume trajectories, material intensity per implant, and pricing evolution by certification tier. Forecast inputs incorporated REACH regulatory restriction timelines and PMDA bridging study duration assumptions.
Underlying assumptions cover regulatory clearance velocity, raw material price stability, and hospital procurement consolidation pace, with deviation risk concentrated in titanium sponge export restrictions and ISO 10993-18 testing queue extensions. Recalibration cycles align with material shifts in EU MDR enforcement intensity and additive manufacturing equipment capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Pulp Cells Market
Biomaterials
Biomimetic Materials Market
Biomaterials
United Kingdom Collagen Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
North America Chitosan Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Mushroom Materials Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
South America Collagen Market