
 Mushroom Materials Market | 2026-2036
Mushroom Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Materials Market Foresight
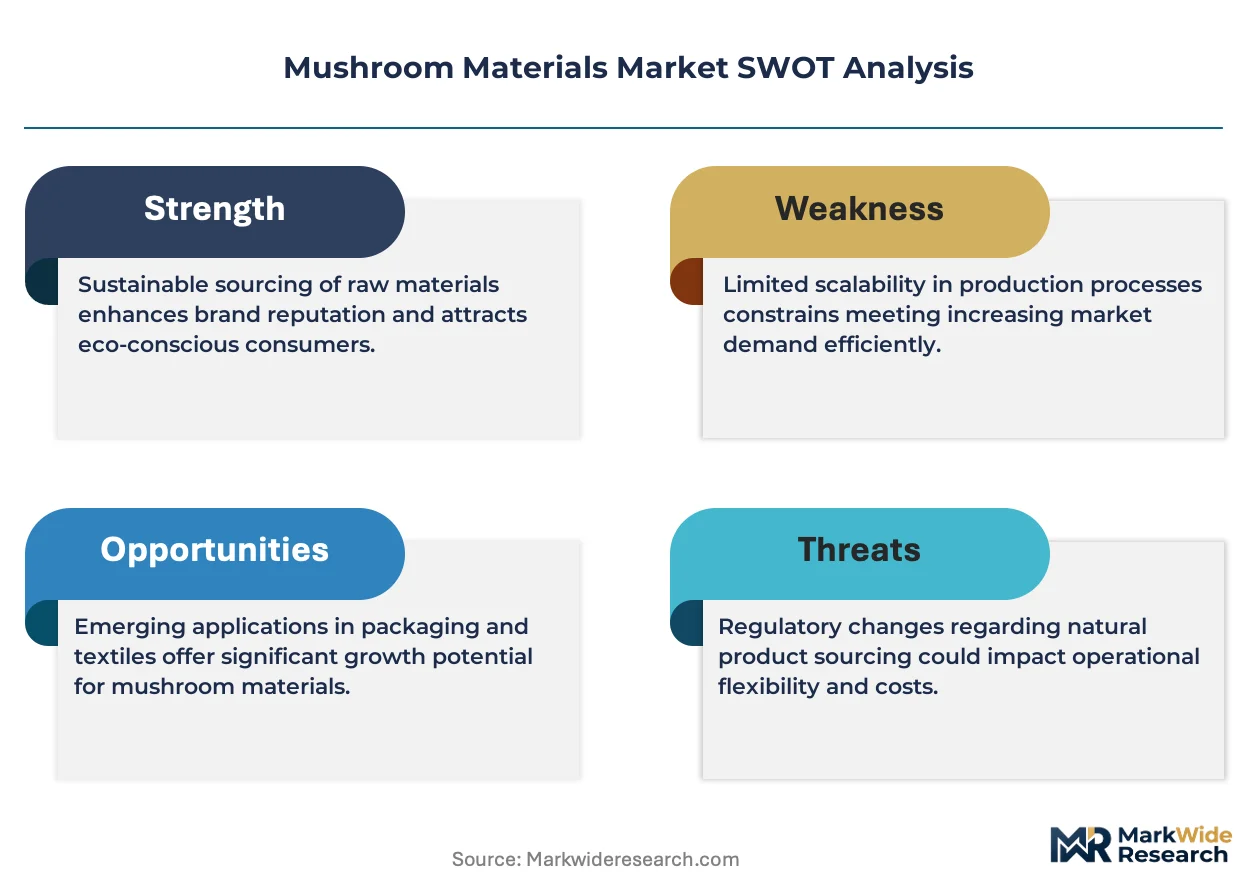
REACH compliance and the EU Green Deal are consolidating the cost-of-entry calculus for mushroom material suppliers seeking European market access. Ecovative Design leverages its proprietary mycelium cultivation platform to anchor North American production capacity. MycoWorks differentiates through high-performance mycelium leather targeting luxury fashion houses. Biohm specializes in construction-grade mycelium insulation that competes on thermal performance with conventional mineral wool.
Mushroom materials comprise engineered mycelium matrices grown on lignocellulosic substrates, typically achieving densities of 0.05–0.30 g/cm³ and compressive strengths comparable to expanded polystyrene foam; these biofabricated structures serve primarily as drop-in replacements for petroleum-derived foams, plastics, and synthetic textiles across packaging, building, and consumer goods sectors. Mycelium composites dominate current production volumes due to established cultivation protocols and shorter grow cycles, while textile fibers represent the fastest-expanding segment as fashion brands pursue regenerative supply chains. Thermal insulation applications capture concentrated margin pools where building energy codes tighten, whereas biodegradable packaging faces margin compression from competing paper and starch-based alternatives.
EMA and EFSA frameworks govern mycelium-derived products entering food-contact and biomedical channels, while REACH registration requirements dictate chemical safety documentation for substrate inputs and finished material formulations. The EPA regulates mycelium cultivation effluents and agricultural substrate sourcing under clean water and pesticide statutes in the United States. Stakeholders must monitor evolving compostability certification standards from ISO and national bodies, as interoperability between regional labeling regimes will determine cross-border product mobility and brand positioning.
Market Dynamics
The EU Green Deal's single-use plastic directives are compressing substitution timelines for petroleum-derived foams, forcing packaging converters to accelerate mycelium-based material qualification cycles and locking in demand trajectories across member states.
Growth Catalysts
- REACH compliance consolidation:Chemical safety documentation requirements under ECHA frameworks are raising barriers for conventional foam suppliers, creating regulated entry points for mycelium alternatives that bypass petrochemical registration pathways.
- Food service packaging substitution:Quick-service restaurant chains facing extended producer responsibility mandates are piloting mycelium containers for hot-fill applications, establishing performance baselines for thermal insulation and grease resistance.
- German industrial clustering:Concentrated sustainability mandates and available lignocellulosic feedstock in Baden-Württemberg and Bavaria are anchoring pilot-scale production facilities with direct converter relationships.
Market Restraints
- Substrate input volatility:Agricultural residue prices fluctuate with grain harvest cycles and competing bioenergy demand, compressing margin predictability for continuous cultivation operations.
- Grow cycle duration:Mycelium maturation requires 7-14 days under controlled humidity and temperature, limiting throughput scalability relative to instant-mold petroleum foams.
- Competing starch-based packaging:PLA and thermoplastic starch alternatives benefit from established composting infrastructure and lower per-unit production costs in high-volume runs.
Strategic Opportunities
- Construction insulation penetration:Building energy code tightening in France and the Netherlands is opening specification opportunities for mycelium boards competing against mineral wool on thermal performance metrics.
- Fashion textile convergence:Luxury leather goods houses are qualifying mycelium-derived materials for accessory lines, creating premium pricing anchors distinct from commodity packaging applications.
- ISO compostability harmonization:Emerging interoperability between national labeling regimes will reduce cross-border certification burdens and accelerate brand positioning in multi-market distribution.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation-scale mycelium cultivation requires specialized expertise in fungal genetics and sterile operation protocols that outpaces current vocational training pipelines.
- Legacy equipment integration:Conventional foam molding lines require retrofitting for mycelium substrate handling, creating capital friction for converters evaluating material switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Materials Market |
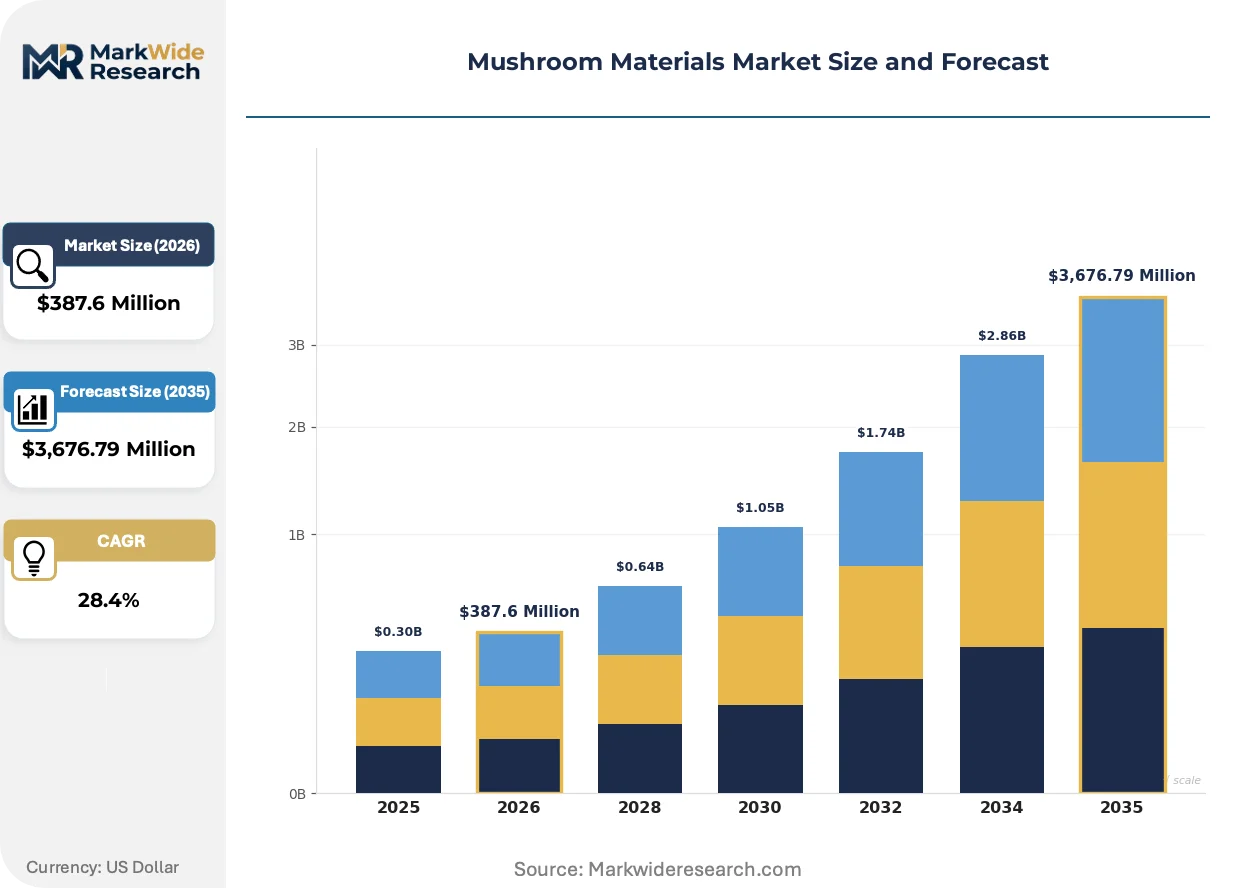
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $3,676.79 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mycelium Composites, Packaging Materials, Insulation Products, Textile Fibers End User: Construction, Fashion, Food Packaging, Automotive Application: Thermal Insulation, Biodegradable Packaging, Acoustic Panels, Furniture Technology: 3D Printing, Cultivation Techniques, Bioremediation Methods, Mold Casting |
| Companies Covered | Fungi Perfecti, Biohm, Ecovative Design, MOGU, Loop Biotech, MycoWorks, Mycelium, BioFab, Mushroom Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Materials Market Shifts & Advancements
Biomanufacturing platforms are converging with automated environmental controls to compress cultivation variability, while regulatory alignment and buyer procurement recalibration are redefining competitive positioning across value chain tiers.
Precision fermentation infrastructure is converging with machine-learning-driven climate optimization to standardize mycelium density and mechanical properties across batch runs. Packaging converters in Germany and the Netherlands are deploying these integrated systems for just-in-time foam replacement programs. The resulting yield predictability is converging with traditional manufacturing reliability benchmarks, enabling specification in automotive component trays previously reserved for expanded polypropylene.
EMA and EFSA frameworks are tightening substrate traceability requirements for mycelium products entering food-contact channels, mandating chain-of-custody documentation from agricultural sourcing through finished material sterilization. Industrial compounders serving European food packaging markets are restructuring supplier qualification protocols to preempt audit failures. The compliance burden falls most acutely on small-scale cultivators lacking integrated substrate processing capabilities, accelerating consolidation toward vertically controlled supply structures.
Brand sustainability officers are embedding compostability certification into supplier scorecards ahead of procurement committee reviews, displacing cost-per-unit as the primary vendor selection criterion. Quick-service restaurant chains with European footprint are requiring ISO 17088 or equivalent home-compostability validation for all new packaging introductions. This preference shift manifests most visibly in Nordic markets, where municipal organic waste collection infrastructure supports consumer-facing compostability claims with verifiable end-of-life pathways.
Mushroom Materials Market Segmentation
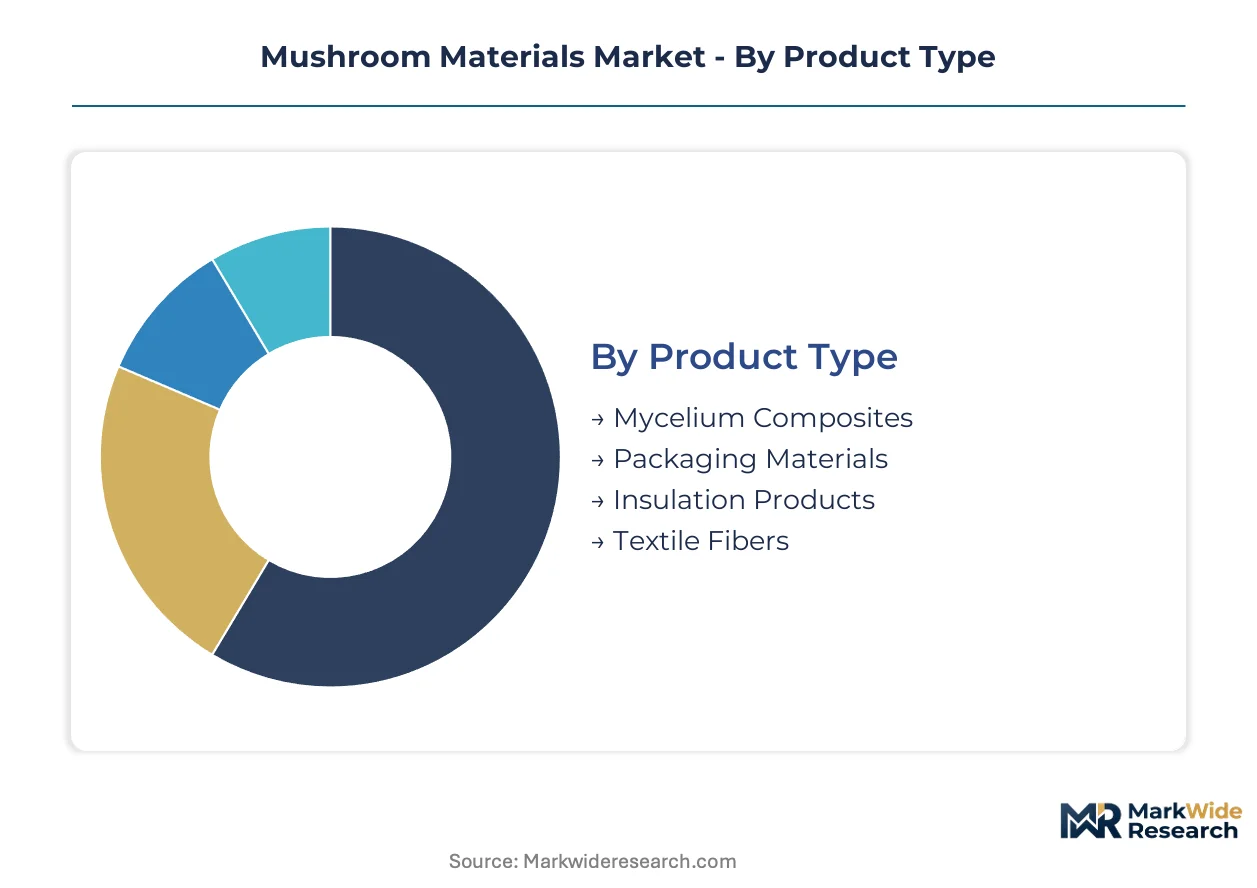
Mushroom materials command divergent price premiums across functional applications, with commodity foams competing on cost parity and luxury textiles extracting substantial markups. Segment boundaries blur as cultivators redirect mycelium matrices from packaging scrap toward construction insulation feedstock.
Product Type:
Volume production concentrates in commodity foams where scale economies dominate, while premium capture flows to specialized matrices with certified performance specifications.
- Mycelium Composites:Engineered matrices grown on lignocellulosic substrates achieve densities of 0.05–0.30 g/cm³ with compressive strengths matching expanded polystyrene. German automotive suppliers specify these for component trays requiring dimensional stability under humidity cycling.
- Textile Fibers:High-tensile mycelium filaments processed into leather alternatives command pricing multiples above commodity applications. Italian and French luxury houses qualify these materials for accessory lines where regenerative sourcing anchors brand positioning.
- Packaging Materials:Drop-in foam replacements for protective cushioning serve quick-service restaurant chains facing extended producer responsibility mandates.
- Insulation Products:Rigid boards compete against mineral wool on thermal performance metrics in French and Dutch building energy code compliance markets.
Today's leader: Mycelium Composites. Tomorrow's challenger: Textile Fibers.
End User:
Application maturity splits between established industrial procurement channels and emerging qualification cycles in discretionary consumer sectors.
- Construction:Building energy code tightening in France and the Netherlands drives specification for mycelium insulation boards. Thermal performance testing against mineral wool establishes technical credibility with mechanical contractors.
- Fashion:Luxury leather goods houses pilot mycelium-derived materials for accessory lines. Premium pricing anchors distinct from commodity packaging applications support regenerative supply chain narratives.
- Food Packaging:Quick-service restaurant chains pilot mycelium containers for hot-fill applications requiring grease resistance validation.
- Automotive:German OEMs qualify mycelium trays for component shipping, leveraging established sustainability scorecard integration.
Construction claims current procurement volume. Fashion offers the steepest expansion trajectory.
Application:
Functional performance requirements stratify segments between regulated building systems and discretionary consumer goods.
- Thermal Insulation:Rigid mycelium boards achieve R-values competitive with conventional mineral wool. French building energy code tightening creates specification pathways for bio-based alternatives in residential envelope applications.
- Biodegradable Packaging:Protective foam replacements face margin compression from competing starch-based alternatives. Nordic municipal composting infrastructure supports consumer-facing end-of-life claims.
- Acoustic Panels:Porous mycelium structures absorb mid-frequency sound in commercial interior applications.
- Furniture:Molded mycelium cores substitute for petroleum-derived foams in seating and case goods.
Thermal Insulation commands concentrated margin pools. Biodegradable Packaging scales fastest where composting infrastructure matures.
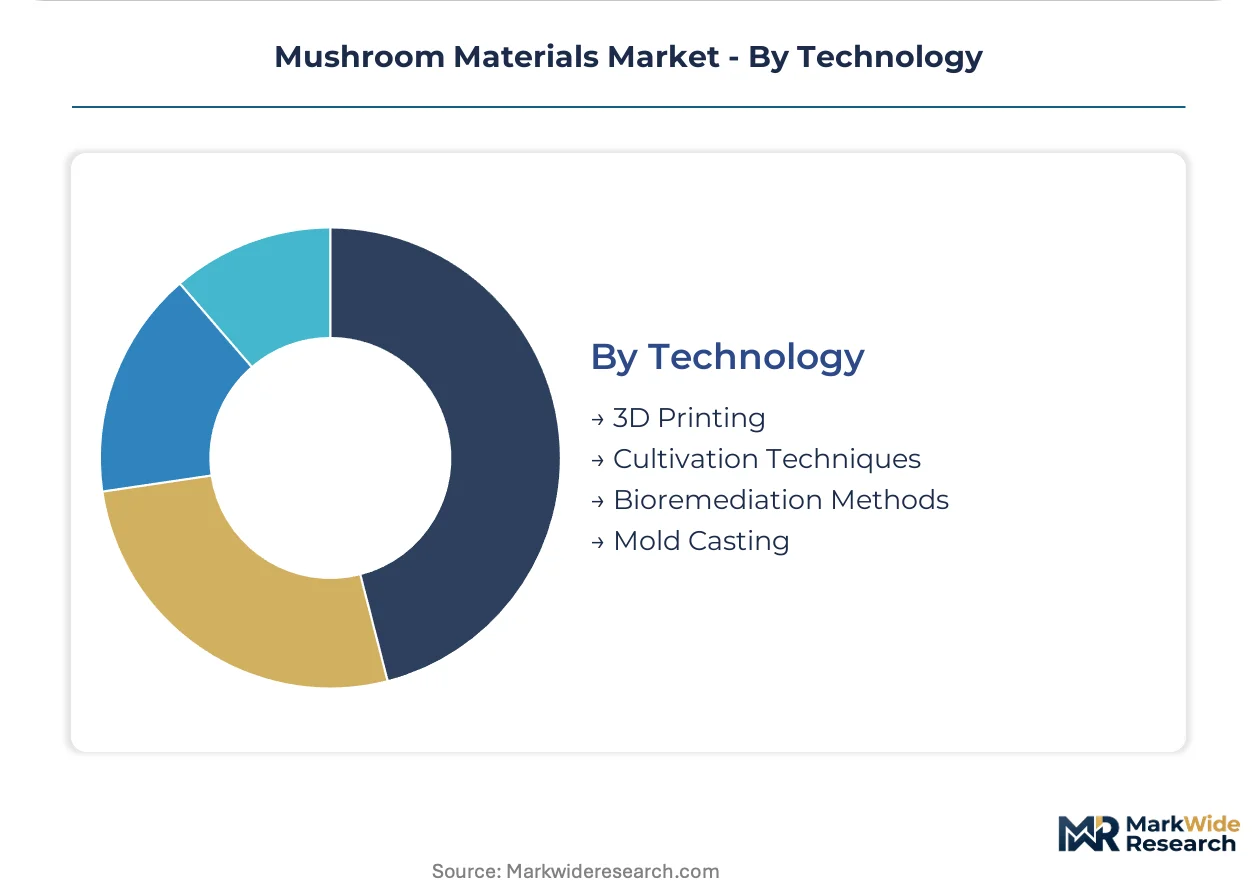
Technology:
Process control sophistication separates artisanal cultivation from industrial biomanufacturing platforms approaching pharmaceutical fermentation reliability.
- Cultivation Techniques:Controlled humidity and temperature protocols compress mycelium maturation to 7-14 days. Machine-learning-driven climate optimization standardizes density and mechanical properties across batch runs.
- 3D Printing:Extrusion-based deposition of living mycelium paste enables complex geometries impossible with conventional mold casting. Architectural prototyping applications exploit this geometric freedom.
- Mold Casting:Conventional foam molding lines require retrofitting for mycelium substrate handling, creating capital friction for converters.
- Bioremediation Methods:Mycelium matrices sequester heavy metals from industrial effluents, creating dual-value propositions in waste treatment applications.
Cultivation Techniques anchor current production. 3D Printing offers the most disruptive capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mycelium-based material production first achieved commercial scale in the United States during the early 2010s, with subsequent expansion into European industrial clusters responding to regulatory pressure on petroleum-derived foams. Geographic concentration now follows sustainability mandate intensity and available lignocellulosic feedstock supply chains.
Germany
Baden-Württemberg and Bavaria host the densest concentration of pilot-scale mycelium cultivation facilities in Europe, anchored by automotive supplier demand for sustainable component packaging. REACH compliance requirements under ECHA frameworks favor domestic producers with established chemical safety documentation protocols. Stuttgart-based packaging converters are qualifying mycelium trays for just-in-time delivery systems serving OEM assembly plants.
United States
New York State and California drive North American demand through quick-service restaurant chains piloting mycelium containers for hot-fill food applications. EPA regulations governing agricultural substrate sourcing and clean water compliance shape cultivation site selection. Ecovative Design's Green Island facility exemplifies integrated production platforms combining proprietary cultivation technology with regional lignocellulosic feedstock contracts.
France
Building energy code tightening in Île-de-France and Auvergne-Rhône-Alpes creates specification pathways for mycelium insulation boards competing against mineral wool. The national strategy for ecological transition accelerates public procurement preferences for bio-based construction materials. Lyon-based mechanical contractors are conducting thermal performance validation trials for residential envelope applications.
Netherlands
Randstad urban agglomerations combine dense food service sectors with mature municipal organic waste collection infrastructure supporting compostability claims. Extended producer responsibility frameworks for packaging waste drive converter qualification of mycelium foam replacements. Eindhoven Region biomanufacturing clusters integrate precision fermentation expertise from adjacent pharmaceutical sectors.
Italy
Lombardy and Tuscany luxury leather goods houses pilot mycelium-derived materials for accessory lines where regenerative sourcing anchors brand positioning. Italian textile traditions intersect with biofabrication innovation in Como and Florence industrial districts. MycoWorks' European market development activities concentrate on qualifying materials for high-fashion applications distinct from commodity packaging segments.
Mushroom Materials Market Competitive Landscape
The competitive structure tilts toward technology-anchored specialists rather than diversified chemical conglomerates, with entry barriers concentrated in proprietary cultivation protocols and sterile operation expertise. Player density remains moderate, with fewer than fifteen significant cultivators across North America and Europe. Two strategic archetypes dominate: integrated biomanufacturing platforms controlling substrate sourcing through cultivation, and materials science specialists licensing production technology to regional compounders. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as converters seek supply security for qualification programs.
Among North American technology originators, Ecovative Design and MycoWorks exemplify divergent specialization vectors within mycelium material production. Ecovative Design occupies a position anchored in packaging and protective foam applications, while MycoWorks represents the premium textile archetype targeting luxury goods substitution. European specialists including Biohm and MOGU sit within construction-grade material development, reflecting regional building energy code opportunities. These named entities serve as reference points for competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Fungi Perfecti |
| Biohm |
| Ecovative Design |
| MOGU |
| Loop Biotech |
| MycoWorks |
| Mycelium |
| BioFab |
| Mushroom Materials |
| Others |
Supply & Pricing Matrix
Fermentation-scale bioprocess engineers concentrated in Germany's Baden-Württemberg cluster command wage premiums that compress margin spreads between commodity packaging foams and certified construction-grade boards. Labor-cost differentials between sterile-operation specialists and conventional materials technicians propagate through three-tier pricing structures separating premium textile fibers from standard insulation products from economy protective packaging.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies mycelium materials by certification grade and volume commitment. ISO 17088 home-compostability validation anchors premium tiers for Nordic food-service applications, while unqualified commodity foams compete on per-unit cost against starch-based alternatives. Price erosion runs through economy packaging tiers as PLA alternatives exploit established composting infrastructure. Quick-service restaurant chains exhibit acute price sensitivity in high-volume procurement, whereas luxury fashion houses prioritize regenerative sourcing credentials over unit economics.
Supply Chain Analysis
REACH registration requirements and EFSA substrate traceability mandates gate supplier qualification for European food-contact channels, favoring vertically integrated cultivators with in-house agricultural residue processing. Production gravity centers on Germany, the United States, and the Netherlands, where lignocellulosic feedstock contracts and automotive OEM proximity converge. Supply chains draw from agricultural residue markets tethered to grain harvest cycles, creating commodity price volatility that compresses margin predictability. Single-source vulnerability concentrates in sterile-substrate preparation capabilities, where proprietary cultivation protocols limit qualified supplier pools. Distribution runs through packaging converters and direct compounder relationships rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mushroom materials market compounds steadily as EU Green Deal mandates compress substitution timelines for petroleum-derived foams across member states. Regulatory pressure on single-use plastics generates predictable demand trajectories that reward capacity positioning ahead of qualification cycles.
For Market Incumbents: Extend cultivation platform reliability through machine-learning-driven climate optimization that standardizes batch-to-batch mechanical properties. Deepen backward integration into agricultural residue preprocessing to buffer substrate price volatility and preempt REACH documentation gaps that disqualify smaller competitors from food-contact channels.
For New Entrants and Emerging Players: Launch via direct relationships with French and Dutch mechanical contractors seeking mycelium insulation alternatives for building energy code compliance. Target construction-grade rigid boards where mineral wool substitution creates specification white space absent from contested packaging segments. Qualify through thermal performance validation protocols rather than competing on compostability claims where starch-based alternatives dominate.
For Investors and Strategic Acquirers: Packaging converters with sustainability scorecard integration are the most active acquirer in this space, seeking captive supply security for automotive and food-service qualification programs. Acquisition targets should demonstrate sterile-operation expertise and established substrate sourcing contracts with 5-10 year viability horizons. Watch for EMA substrate traceability rulemaking as the inflection signal that accelerates consolidation toward vertically controlled supply structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Processing | Captive agricultural residue supply buffers price volatility and satisfies EFSA chain-of-custody mandates. |
| Machine-Learning Cultivation Optimization | Precision fermentation controls standardize density benchmarks required for automotive component tray specifications. |
| ISO 17088 Certification Investment | Home-compostability validation unlocks Nordic quick-service restaurant procurement committees. |
| Direct Converter Partnership Programs | Just-in-time foam replacement contracts with German automotive suppliers lock in volume commitments. |
| Luxury Fashion Material Qualification | Premium textile fiber positioning extracts pricing multiples distinct from commodity packaging applications. |
Research Methodology
Multiple input streams — cultivation facility operating data, substrate procurement contract terms, and regulatory filing documentation — were reconciled against converter qualification timelines and end-user procurement specifications. Primary interviews with bioprocess engineering directors, packaging converter procurement leads, and ECHA regulatory affairs specialists were validated through secondary sources including EU Green Deal implementation reports, REACH registration databases, and national building energy code amendments. Bottom-up facility capacity estimates and top-down segment demand projections were triangulated to constrain forecast variance.
Data-stream reconciliation across the projection horizon applied segmented growth models by product type, end-user industry, and regional regulatory cluster. Mycelium composite density specifications, thermal performance benchmarks against mineral wool, and compostability certification penetration rates informed segment-specific trajectory assumptions. CAGRs were derived from fitted adoption curves calibrated to substitution timelines under EU single-use plastic directives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in agricultural residue pricing or delays in ISO compostability standard harmonization. Model outputs reflect assumptions regarding cultivation cycle standardization and converter equipment retrofit rates. A model refresh is warranted upon material change in EFSA substrate traceability requirements or German automotive OEM sustainability scorecard weightings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
North America Chitosan Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Pulp Cells Market
Biomaterials
Europe Collagen Market
Biomaterials
Heparin Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Hydrogel Market