
 Europe Collagen Market | 2026-2036
Europe Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Collagen Market Analysis
Asset-light contract manufacturing and toll-processing arrangements is rewriting competitive entry barriers for mid-tier European collagen suppliers. GELITA AG leverages captive bovine and porcine raw material streams across German rendering networks to sustain margin control. Rousselot BV anchors its position through marine collagen specialization from North Atlantic fishing industry partnerships. Weishardt Group competes on hydrolyzed collagen capacity scaled through French and Irish processing facilities.
Collagen comprises a triple-helix protein structure rich in glycine, proline, and hydroxyproline amino acids, extracted through acid or alkaline hydrolysis of animal connective tissues or marine byproducts for gelling, emulsifying, and biomedical scaffold applications. Hydrolyzed collagen dominates volume throughput due to its cold-water solubility and neutral sensory profile in functional beverages. Gelatin retains mature, price-competitive positions in confectionery and pharmaceutical capsule applications where bloom strength specifications determine procurement. Nutraceuticals represents the fastest-expanding end-user channel as beauty-from-within and joint-health positioning drives peptide-grade demand.
EMA pharmaceutical-grade standards, EFSA novel food authorization pathways, and REACH chemical safety registration collectively elevate compliance costs for new collagen entrants while protecting incumbent quality positions. CSRD sustainability disclosure requirements are pressing processors to document supply chain traceability from slaughterhouse to hydrolysate. Stakeholders must monitor regulatory divergence between EU centralized approvals and member-state national health claims interpretations.
Market Dynamics
EMA pharmaceutical-grade standards and EFSA novel food authorization pathways are tightening entry barriers while CSRD sustainability disclosure requirements force processors to document slaughterhouse-to-hydrolysate traceability. These regulatory layers protect incumbent quality positions but fragment compliance costs across member states.
Growth Catalysts
- Beauty-from-within positioning:Nutraceutical brands are expanding peptide-grade collagen into functional beverages and gummies, driving cold-water solubility demand.
- EU Green Deal standards:Tighter extraction and processing requirements favor established German and French rendering networks with captive bovine supply.
- Joint-health formulations:Aging demographics in Italy and Spain are accelerating medical nutrition applications for hydrolyzed collagen.
Market Restraints
- Bovine raw material concentration:German and French rendering networks dominate supply, creating geographic dependency for mid-tier processors.
- Marine collagen input volatility:North Atlantic fishing industry byproduct availability fluctuates with seasonal quotas and climate patterns.
- Plant-based protein substitution:Pea and rice protein isolates are capturing share in mass-market functional foods where sensory neutrality matters less.
Strategic Opportunities
- Eastern European capacity gaps:Poland and Romania lack domestic hydrolyzed collagen production, creating import substitution potential for toll processors.
- Biomedical scaffold applications:Cross-linked collagen matrices for wound healing and tissue engineering command premium pricing outside commodity nutrition markets.
- CSRD-aligned traceability premiums:Early compliance with supply chain disclosure requirements enables certified-sustainable product tiering.
Industry Challenges
- Peptide characterization expertise:Molecular weight distribution analysis and bioactivity validation require specialized analytical chemistry talent scarce outside German and Dutch research clusters.
- Multi-jurisdictional authorization timelines:EFSA novel food approvals for innovative marine sources run 18-24 months, compressing first-mover windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Collagen Market |
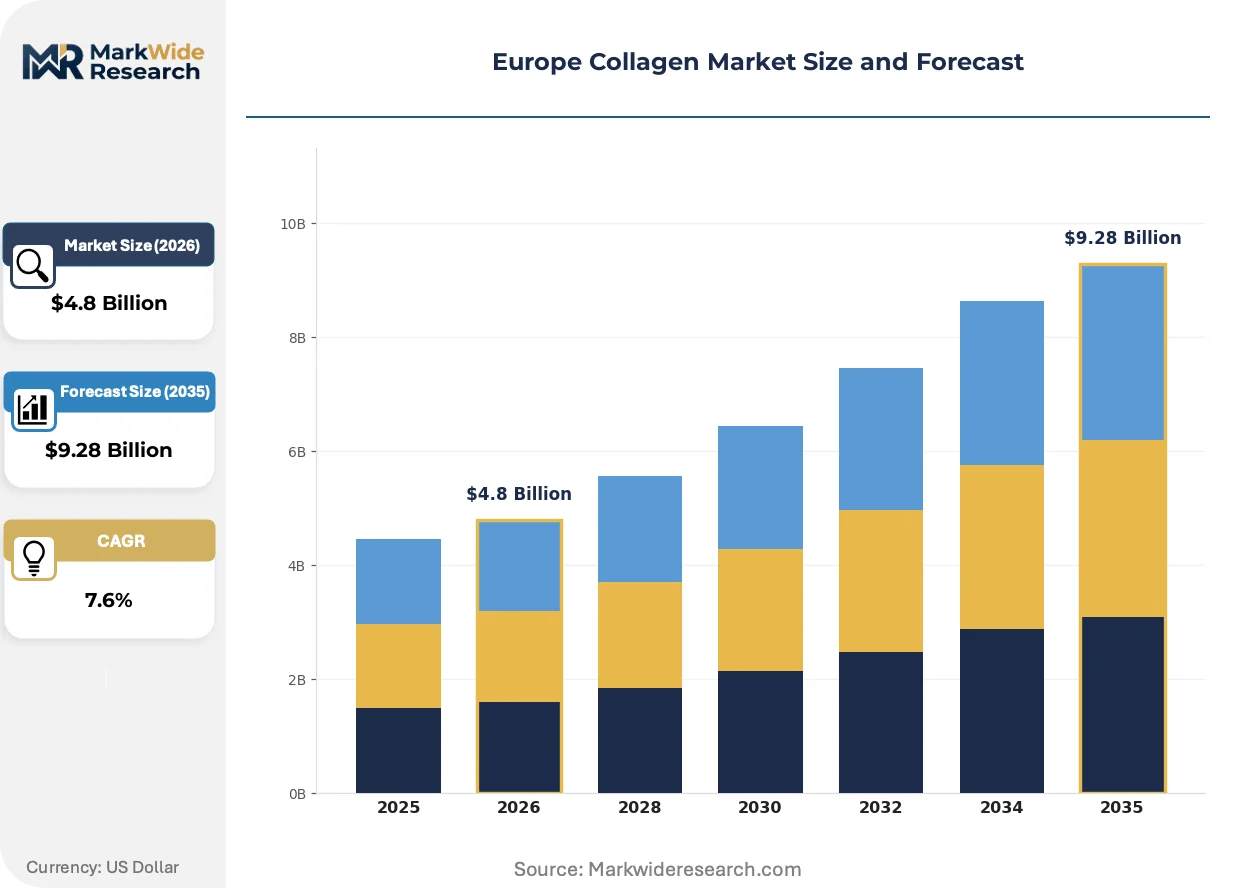
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Type I Collagen End User: Food & Beverage, Cosmetics, Healthcare, Nutraceuticals Application: Beauty Supplements, Joint Health, Bone Repair, Skin Care Form: Powder, Liquid, Capsules, Gel |
| Companies Covered | GELITA AG, Rousselot BV, Weishardt Group, Tessenderlo Group NV, Italgel S.r.l., Lapi Gelatine S.p.A., Ewald-Gelatine GmbH, Collagen Solutions Plc, PB Gelatins, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Collagen Market Emerging Trajectories
Enzymatic hydrolysis and precision fermentation are converging to reshape extraction economics. Processors are racing to reduce energy intensity while preserving triple-helix integrity for high-bloom applications.
Precision fermentation of recombinant collagen is hybridizing traditional animal-derived supply chains. Biotech startups in Netherlands and Denmark are scaling yeast-based production for cosmetic-grade applications. This technology is compressing reliance on rendered byproducts in premium segments where molecular consistency commands price premiums.
REACH chemical safety registration and F-Gas Regulation are tightening solvent recovery requirements for acid hydrolysis operations. Processors must retrofit facilities or shift to enzymatic alternatives. German and Belgian industrial clusters face the steepest capex burdens, accelerating consolidation among mid-cap toll processors.
Direct-to-brand contracting is displacing traditional ingredient distributor networks. Nutraceutical formulators in France and Italy are sourcing hydrolyzed collagen through long-term offtake agreements with named processors. This channel shift is most visible in peptide-grade segments where batch consistency and documentation depth determine supplier selection.
Europe Collagen Market Segmentation
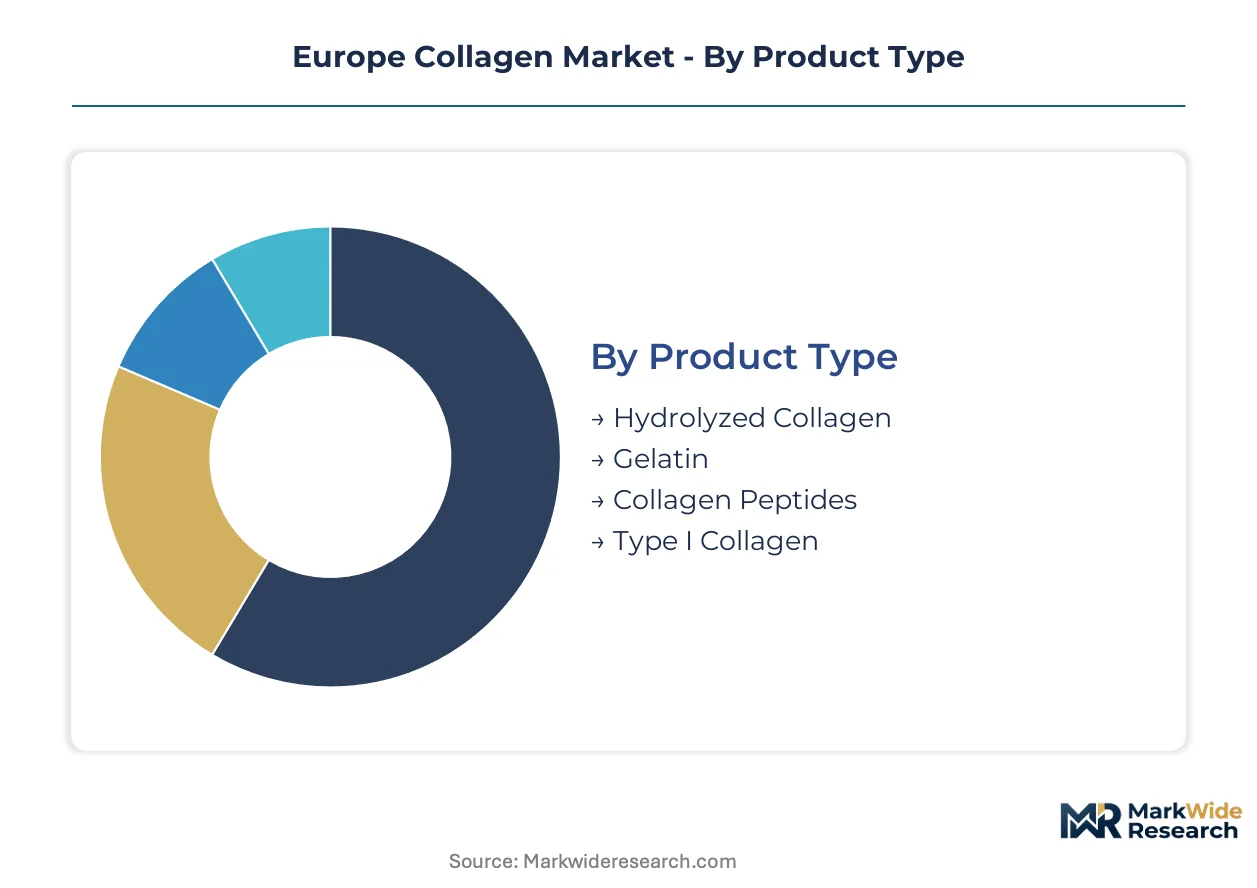
European collagen procurement patterns diverge sharply across product grades and end-use specifications. Formulators in Germany and France prioritize cold-water solubility and molecular weight consistency, while Italian and Spanish buyers emphasize sensory neutrality for mass-market applications.
Product Type:
Cost tier differentiation separates commodity-grade inputs from peptide-grade premiums across European rendering networks.
- Hydrolyzed Collagen:Partial enzymatic breakdown yields peptides under 10 kDa with complete cold-water solubility. German beverage formulators in Munich and Hamburg are specifying low-molecular-weight grades for clear functional drinks where turbidity rejection is absolute.
- Gelatin:Heat-reversible gelling protein extracted through acid or alkaline processing of bovine or porcine connective tissue, characterized by bloom strength measurements. French confectionery manufacturers in Lyon and Strasbourg anchor procurement around 150-250 bloom specifications for gummy and marshmallow applications.
- Collagen Peptides:Bioactive fractions standardized for specific physiological targets. Italian nutraceutical brands are driving specification tightening around dipeptide content for joint-health positioning.
- Type I Collagen:Triple-helix structural protein dominant in dermal and tendon tissue. Dutch biomedical processors in Leiden command premium pricing for pharmaceutical-grade isolates used in wound-healing matrices.
Hydrolyzed Collagen holds installed capacity. Collagen Peptides is rotating up the share rankings.
End User:
Application maturity determines margin capture, with established channels defending price positions while emerging segments extract specification premiums.
- Nutraceuticals:Peptide-grade hydrolysates positioned for beauty-from-within and mobility claims. French and Italian formulators in Paris and Milan are expanding gummy and stick-pack formats, driving demand for neutral-taste, rapid-dissolve grades that bypass traditional capsule delivery.
- Healthcare:Pharmaceutical-grade collagen for medical nutrition, wound care, and surgical applications. German hospital feeding protocols and Spanish geriatric care facilities are accelerating enteral nutrition specifications for hydrolyzed protein content.
- Food & Beverage:Gelatin and hydrolyzed collagen for functional fortification. Belgian and Dutch dairy processors are testing collagen enrichment in fermented beverages where protein stability intersects with clean-label positioning.
- Cosmetics:Topical and ingestible formats for skin elasticity claims. Swedish and Danish brands are sourcing marine-derived grades for premium positioning in Nordic markets with strong sustainability signaling requirements.
Food & Beverage holds installed capacity. Nutraceuticals is expanding most quickly.
Application:
Volume concentration clusters around mature use cases while emerging indications command development investment and regulatory navigation.
- Beauty Supplements:Ingestible formats targeting skin hydration and elasticity through collagen peptide bioavailability. German and French consumers in Berlin and Paris are driving subscription-model growth for powder and liquid daily doses.
- Joint Health:Medical nutrition and supplement positioning for osteoarthritis management and athletic recovery. Italian and Spanish aging populations in Rome and Barcelona are expanding over-the-counter pharmacy channel penetration for hydrolyzed collagen powders.
- Skin Care:Topical formulations leveraging collagen film-forming and moisture-retention properties. Swiss and Austrian dermocosmetic brands in Zurich and Vienna are specifying low-molecular-weight hydrolysates for serum compatibility.
- Bone Repair:Biomedical scaffold applications in orthopedic and dental surgery. Dutch and Belgian research hospitals in Rotterdam and Leuven are piloting cross-linked collagen matrices for guided tissue regeneration.
Joint Health holds installed capacity. Beauty Supplements is climbing the fastest.
Form:
Customer type preferences—direct-to-consumer brands versus industrial formulators—are reshaping format demand across European packaging hubs.
- Powder:Bulk hydrolyzed collagen for beverage fortification and supplement manufacturing. German and Polish toll processors in Frankfurt and Warsaw are scaling flexible packaging lines for private-label sports nutrition brands.
- Liquid:Ready-to-drink shots and vials for beauty and wellness positioning. French and Italian marketers in Lyon and Bologna are driving single-serve format innovation with stability challenges around peptide aggregation.
- Capsules:Hard-shell and soft-gel delivery for standardized dosing. Spanish and Portuguese pharmaceutical packagers in Barcelona and Lisbon maintain mature demand for gelatin capsule shells and collagen-filled supplements.
- Gel:Semi-solid preparations for topical and oral applications. UK and Irish cosmetic manufacturers in Manchester and Dublin are formulating marine collagen gels for premium skincare lines.
Powder holds installed capacity. Liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal incentives and CSRD disclosure mandates are concentrating investment in German, French, and Italian processing clusters. EMA pharmaceutical-grade standards and EFSA novel food pathways create regulatory moats that favor established rendering networks with documented traceability systems.
Germany
Hospital feeding protocols and medical nutrition specifications drive pharmaceutical-grade collagen demand from Bavarian geriatric care facilities. EMA standards enforcement tightens extraction facility compliance across North Rhine-Westphalia. Munich and Hamburg beverage formulators specify low-molecular-weight hydrolyzed grades for clear functional drinks.
France
Beauty-from-within gummy and stick-pack formats expand peptide-grade procurement from Parisian nutraceutical marketers. EFSA novel food authorization timelines compress first-mover windows for innovative marine sources. Lyon and Strasbourg confectionery manufacturers anchor gelatin procurement around 150-250 bloom specifications.
Italy
Aging demographics in Rome and Barcelona accelerate over-the-counter pharmacy channel penetration for joint-health hydrolyzed collagen powders. CSRD sustainability disclosure requirements press processors to document slaughterhouse-to-hydrolysate traceability. Milan formulators drive specification tightening around dipeptide content for mobility claims.
Netherlands
Leiden biomedical processors command premium pricing for pharmaceutical-grade Type I collagen isolates used in wound-healing matrices. REACH chemical safety registration elevates compliance costs for acid hydrolysis operations. Rotterdam research hospitals pilot cross-linked collagen matrices for guided tissue regeneration.
Poland
Domestic hydrolyzed collagen production gaps create import substitution potential for toll processors serving private-label sports nutrition brands. F-Gas Regulation tightens solvent recovery requirements for rendering operations. Warsaw toll processors scale flexible packaging lines for German and French brand outsourcing.
Europe Collagen Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement networks. German and French rendering networks dominate bovine raw material supply, creating geographic dependency for mid-tier processors. Three archetypes prevail: captive-supply integrated processors, marine-collagen specialists, and toll-processing scale operators. Consolidation accelerates through backward integration into rendering assets and long-term offtake contracting with nutraceutical formulators.
Within the integrated-processor tier, GELITA AG and Rousselot BV exemplify archetypes built on captive raw material control and marine specialization respectively. Weishardt Group occupies a position among hydrolyzed capacity specialists with French and Irish processing footprints. These three anchors demonstrate how supply security and specification depth determine supplier selection in peptide-grade segments.
| Leading Market Players |
|---|
| GELITA AG |
| Rousselot BV |
| Weishardt Group |
| Tessenderlo Group NV |
| Italgel S.r.l. |
| Lapi Gelatine S.p.A. |
| Ewald-Gelatine GmbH |
| Collagen Solutions Plc |
| PB Gelatins |
| Others |
Supply Flow & Price Mechanics
North Rhine-Westphalia's rendering network concentration gives German processors outsized leverage in peptide-grade contract negotiations with French and Italian nutraceutical formulators. This geographic supply lock-in compresses margin flexibility for mid-tier toll processors competing on specification depth.
Pricing Analysis
Certification level (EMA pharmaceutical-grade versus EFSA novel food tier) creates the primary spread between commodity hydrolysates and premium peptide grades. Three-tier pricing structure across premium, standard, and economy levels segments procurement: pharmaceutical-grade Type I isolates command top-tier positioning, nutraceutical peptide grades occupy mid-tier offtake agreements, and commodity gelatin feeds price-sensitive confectionery applications. Cost compression in standard-tier hydrolyzed collagen is intensifying because Polish and Romanian toll processors are undercutting Western European capacity on volume contracts. Food and beverage manufacturers show highest price sensitivity, while Dutch biomedical scaffold buyers demonstrate inelastic demand for documented traceability.
Supply Chain Analysis
Single-source vulnerability in North Atlantic marine byproduct availability dominates supply chain risk planning for Rousselot BV and marine-specialist competitors. German, French, and Irish rendering networks anchor 70% of European bovine collagen supply, with captive slaughterhouse partnerships in Bavaria and Normandy feeding acid hydrolysis operations. Raw material dependencies rest on porcine skin from Spanish abattoirs, bovine hide trim from German beef processing, and codfish skin from Norwegian Arctic fisheries. Distribution runs through direct-to-brand offtake agreements that displace traditional ingredient distributors in peptide-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against precision fermentation substitution as Dutch and Danish biotech startups scale yeast-derived recombinant collagen for cosmetic-grade applications.
For Market Incumbents: Insulate peptide-grade positioning by deepening captive bovine supply control through Bavarian rendering asset acquisition or long-term slaughterhouse offtake. Secure EMA pharmaceutical-grade certification moats before CSRD traceability requirements harden compliance barriers for mid-tier competitors. For New Entrants and Emerging Players: Poland and Romania's domestic hydrolyzed collagen production gaps offer import substitution entry points for toll processors serving German and French brand outsourcing. Target private-label sports nutrition brands in Warsaw and Krakow with flexible packaging capacity and rapid batch turnaround as the most penetrable wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among marine-collagen specialists with North Atlantic fishing industry partnerships locked into multi-year byproduct supply contracts. Long-term viability across the analysis window favors processors with backward integration into rendering assets and documented CSRD-aligned traceability systems. Watch EFSA novel food approval timelines for innovative marine sources as the signal for first-mover window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Assets | Bavarian and Normandy slaughterhouse partnerships secure bovine raw material supply against Polish toll processor competition. |
| CSRD-Aligned Traceability Certification | Early compliance enables premium product tiering for Swedish and Danish sustainability-signaling cosmetic brands. |
| Enzymatic Hydrolysis Facility Retrofit | REACH solvent recovery requirements force acid hydrolysis exit or capex burden in Belgian industrial clusters. |
| Direct-to-Brand Offtake Agreements | Paris and Milan nutraceutical formulators bypass distributors for peptide-grade batch consistency guarantees. |
| Marine Collagen Source Diversification | Norwegian Arctic and Mediterranean fishery partnerships reduce North Atlantic quota volatility exposure. |
Methodological Framework
A spread of perspectives from rendering plant managers, nutraceutical formulator procurement leads, EFSA regulatory affairs specialists, and Dutch biomedical R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation against EMA pharmaceutical-grade filing databases, REACH chemical safety registrations, CSRD sustainability disclosure frameworks, and customs trade data for collagen hydrolysate flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, molecular weight specification, and regional processing hub concentration. CAGRs derived from capacity expansion pipelines, offtake agreement visibility, and substitution elasticity parameters for plant-based protein isolates. Industry-specific inputs incorporated EFSA novel food approval velocity and F-Gas Regulation compliance cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by precision fermentation startups or sudden EFSA pathway accelerations for marine sources would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
United Kingdom Collagen Market
Biomaterials
Heparin Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Bone Distractors Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Nerve Repair Biomaterials Market