
 Hemostatic Gels Market | 2026-2036
Hemostatic Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostatic Gels Market Foresight
Modular tray configurations is rebalancing procurement decisions across surgical suites, as hospitals shift from bulk gel purchases to procedure-specific bundles containing pre-measured applicators and adjunct dressings. Baxter International leverages its integrated hospital supply contracts to anchor these bundled offerings in acute care settings. Ethicon competes through specialized formulations targeting minimally invasive procedures, while BD sustains channel control via direct distribution to surgical centers.
Hemostatic gels comprise biocompatible, flowable formulations—typically incorporating oxidized cellulose, gelatin matrices, or polysaccharide complexes—that activate coagulation cascades upon contact with bleeding tissue surfaces, with viscosity parameters engineered for specific anatomical access routes. These products serve the primary commercial purpose of intraoperative bleeding control across open, laparoscopic, and interventional procedures. Paste formulations dominate current volume due to established reimbursement codes and surgeon familiarity, while spray delivery systems represent the fastest-growing configuration as ambulatory surgical centers prioritize speed and reduced waste. Trauma care applications command premium pricing relative to routine dental procedures, where gauze-based alternatives retain cost-sensitive share.
FDA premarket notification requirements under 21 CFR 878.4490 govern absorbable hemostatic device classifications, while the EU Medical Device Regulation mandates clinical evidence thresholds that filter market entrants. ISO 10993 biocompatibility testing series shapes material selection and validation protocols across manufacturing operations. Stakeholders must monitor evolving sterilization validation standards and regional reimbursement divergence as determinants of portfolio prioritization and geographic deployment sequencing.
Market Dynamics
FDA's 21 CFR 878.4490 premarket notification pathway is compressing development timelines for absorbable hemostats while surgical centers demand procedure-specific configurations over bulk formulations.
Growth Catalysts
- EU MDR clinical evidence thresholds:Manufacturers accelerating biocompatibility validation under ISO 10993 series are securing faster CE marking access, opening premium pricing corridors in European surgical suites.
- Trauma care infrastructure:United States emergency departments are standardizing flowable hemostatic protocols for penetrating injury management, creating institutional purchasing momentum for advanced gel formulations.
- Polysaccharide complex engineering:Viscosity-tuned matrices enabling laparoscopic delivery are displacing conventional paste applications in minimally invasive procedure volumes.
Market Restraints
- Gelatin raw material volatility:Bovine and porcine-derived gelatin supply chains face price instability from livestock disease outbreaks, squeezing gross margins for matrix-based manufacturers.
- Reimbursement code fragmentation:Divergent HCPCS and CPT coding across US commercial and Medicare Advantage plans creates billing complexity that slows hospital formulary adoption.
- Mechanical hemostat substitution:Oxidized cellulose sheets and powder formats retain cost-sensitive share in open abdominal procedures where spray delivery offers limited advantage.
Strategic Opportunities
- Ambulatory surgical center channel expansion:Standalone ASCs in Texas and Florida are converting from hospital outpatient departments, creating direct purchasing relationships bypassing integrated delivery networks.
- IRB-approved real-world evidence pathways:FDA's expanded access programs for post-market surveillance are enabling label expansion through registry data rather than prospective trials.
- Chitosan-thrombin convergence:Hybrid biopolymer-enzyme formulations targeting coagulopathic patients are opening addressable populations beyond standard surgical candidates.
Industry Challenges
- Sterilization validation bottlenecks:Gamma versus e-beam radiation selection for terminal sterilization requires extensive endotoxin and pyrogen testing that extends validation cycles by 8-14 months.
- Formulary committee resistance:Hospital pharmacy and therapeutics committees demand head-to-head bleeding time data against established products, requiring costly prospective studies for tier placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostatic Gels Market |
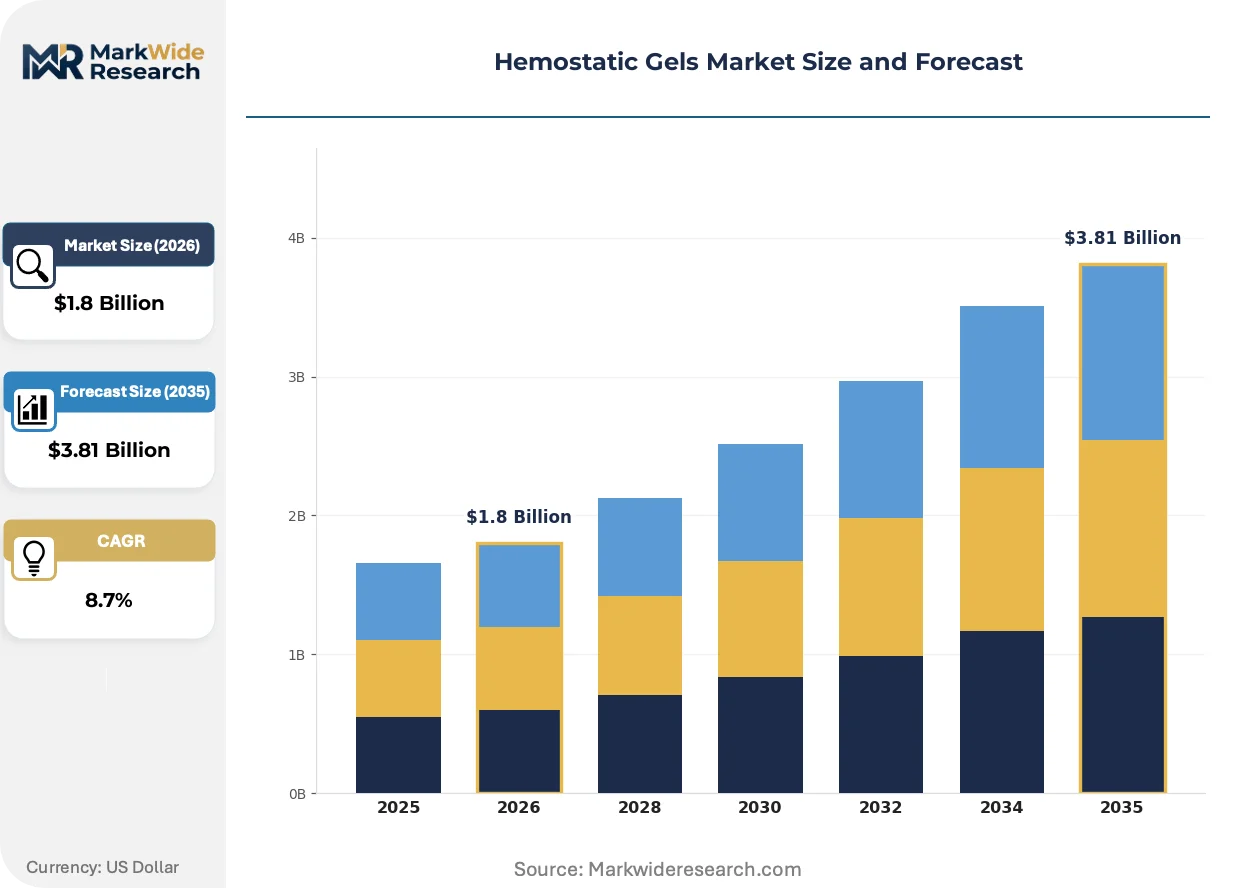
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paste, Gauze, Spray, Solution End User: Hospitals, Clinics, Emergency Rooms, Surgical Centers Application: Trauma Care, Surgical Procedures, Dental Procedures, Veterinary Distribution Channel: Online Retail, Direct Sales, Distributors, Pharmacies |
| Companies Covered | Ethicon, Baxter International, BD, Artivion, Medcura, Hemostasis LLC, GELITA Medical, Pfizer, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostatic Gels Market Shifts & Advancements
Delivery system miniaturization and real-time coagulation monitoring are converging to redefine intraoperative bleeding management protocols across surgical specialties.
Spray-applied hemostatic systems using pressurized carbon dioxide propellants are electrifying ambulatory procedure workflows. Surgical centers in high-volume cataract and arthroscopy markets are adopting these configurations to reduce waste from opened but unused syringes. The technology is electrifying procurement negotiations as manufacturers bundle applicators with single-use valves to lock in annual supply commitments.
MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market clinical follow-up data for legacy absorbable hemostats previously cleared under the Medical Devices Directive. German notified bodies are applying the most stringent interpretation, rejecting equivalence claims for formulations without five-year safety databases. Medium-tier suppliers are responding by withdrawing from EU markets rather than funding PMCF studies.
Hospital supply chain directors are consolidating hemostatic purchasing through integrated distribution agreements that wrap gels with adjunct products like surgical sealants and adhesion barriers. These arrangements displace standalone gel contracts in systems operating 15-plus operating rooms. The shift is most visible in California and New York health systems pursuing standardized consumable formularies across multiple facilities.
Hemostatic Gels Market Segmentation
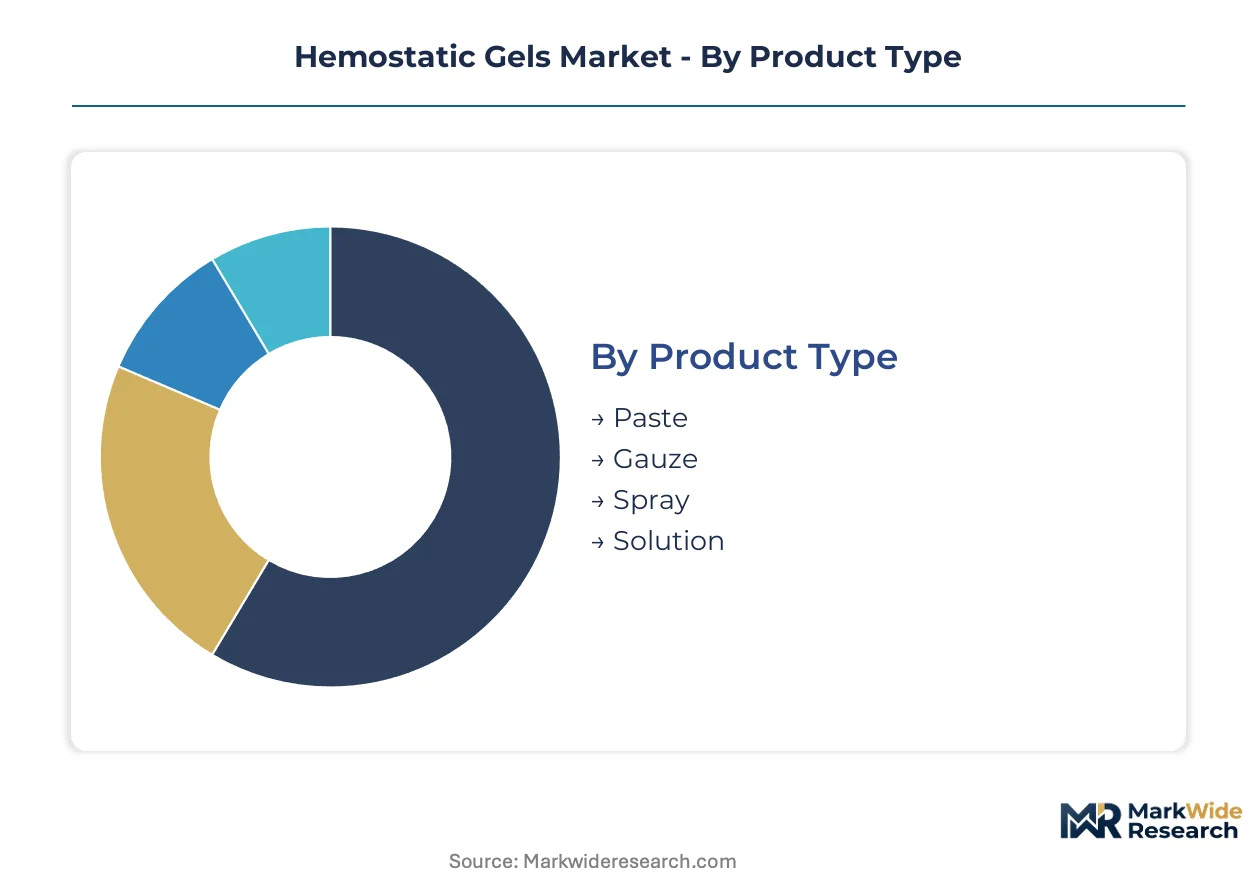
Hemostatic gel purchasing patterns diverge sharply across clinical settings, with trauma centers prioritizing rapid-deployment spray systems while ambulatory sites favor pre-measured paste units. Manufacturers calibrate viscosity, applicator design, and sterilization packaging to match these distinct operational workflows.
Product Type:
Procurement decisions in this category pivot on procedure speed requirements and waste minimization priorities.
- Paste:Pre-filled syringe formats with calibrated viscosity enable controlled extrusion during open abdominal procedures. United States hospital systems with integrated delivery networks negotiate annual contracts for bulk paste units, though opened-but-unused waste drives formulary scrutiny.
- Spray:Pressurized carbon dioxide propellant systems deliver atomized hemostatic coverage across irregular wound surfaces. Ambulatory surgical centers in Texas and Florida are converting to spray configurations to eliminate syringe waste in high-volume cataract and arthroscopy workflows.
- Gauze:Impregnated woven matrices provide mechanical compression combined with chemical hemostasis for field trauma applications.
- Solution:Flowable liquid formulations enable irrigation-based delivery through laparoscopic ports during minimally invasive procedures.
Paste leads volumes today; spray is gaining share fastest.
End User:
Facility scale and reimbursement structure determine whether buyers prioritize bulk efficiency or premium single-use convenience.
- Hospitals:Academic medical centers with Level I trauma certification maintain diversified hemostatic formularies spanning paste, spray, and gauze formats to address penetrating injury protocols.
- Surgical Centers:Standalone ASCs bypassing integrated delivery networks in high-growth Sun Belt markets negotiate direct manufacturer contracts for procedure-specific bundles.
- Emergency Rooms:United States emergency departments standardizing flowable hemostatic protocols for penetrating injury management generate institutional purchasing momentum.
- Clinics:Outpatient wound care clinics favor cost-conscious gauze-based alternatives for routine debridement procedures.
Hospitals dominate absolute spend; surgical centers are expanding most quickly.
Application:
Clinical urgency and bleeding severity create tiered pricing tolerance across use cases.
- Trauma Care:Penetrating injury management protocols in United States emergency departments command premium pricing for rapid-acting flowable formulations.
- Surgical Procedures:Laparoscopic and open operative settings drive volume demand for viscosity-tuned matrices enabling precise anatomical delivery.
- Dental Procedures:Extraction site management tolerates lower-cost gauze alternatives where bleeding control requirements are less acute.
- Veterinary:Companion animal surgical applications adopt human-formulation derivatives with modified biocompatibility testing protocols.
Surgical procedures anchor volume; trauma care commands the steepest price premiums.
Distribution Channel:
Supply chain control and purchasing autonomy shape channel selection across buyer types.
- Direct Sales:Integrated hospital supply contracts wrap hemostatic gels with adjunct sealants and adhesion barriers, displacing standalone purchases in multi-facility systems.
- Distributors:Regional medical-surgical distributors maintain inventory positions for mid-tier surgical centers lacking direct manufacturer relationships.
- Online Retail:Veterinary clinics and smaller outpatient settings utilize e-commerce procurement for standardized paste and gauze formats.
- Pharmacies:Retail pharmacy channels serve limited consumer-accessible dental and minor wound care applications.
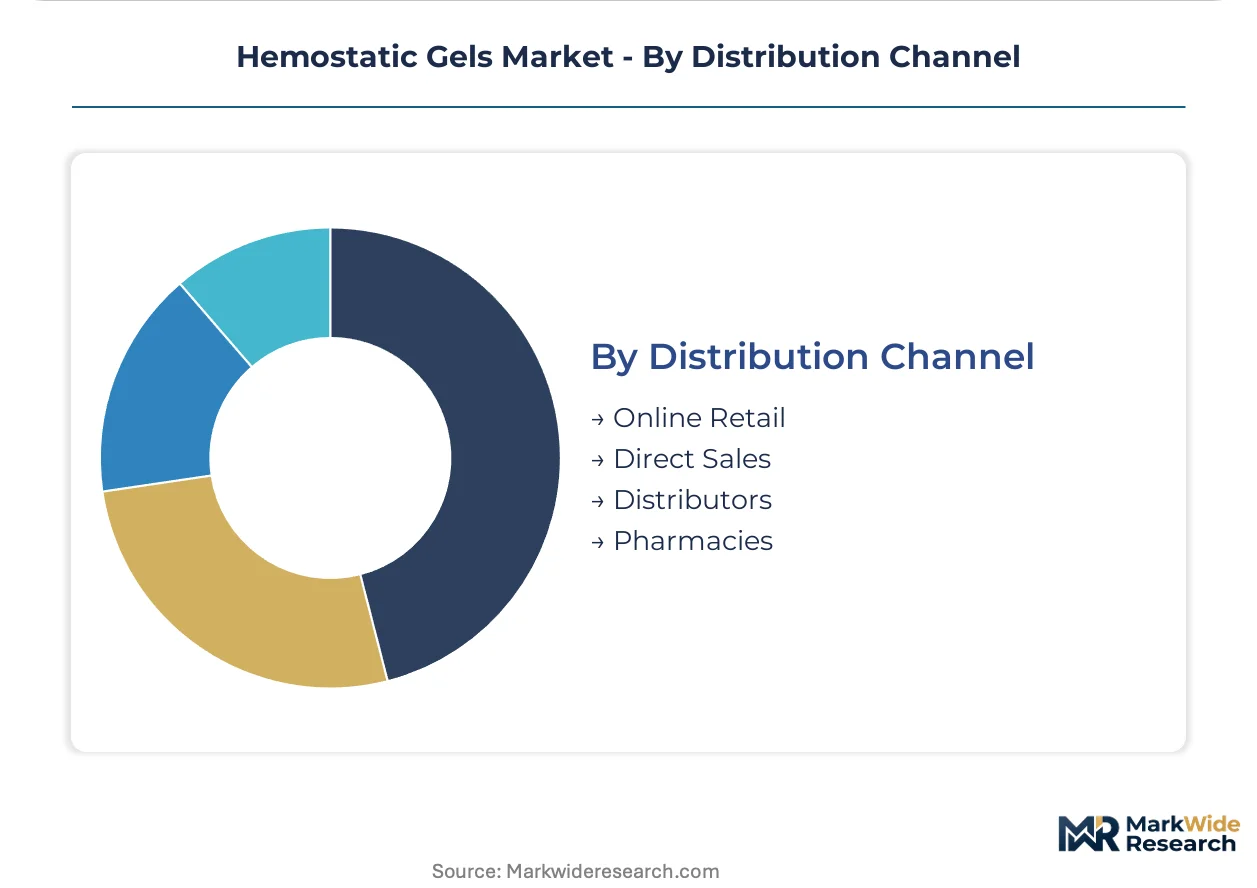
Direct sales capture the largest revenue pool; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hemostatic gel technology originated in German surgical research centers during the 1940s, with oxidized cellulose formulations first commercialized for battlefield trauma. The United States subsequently scaled manufacturing and established the regulatory frameworks that shaped modern product categories.
United States
Level I trauma centers in Houston, Baltimore, and Los Angeles drive institutional purchasing for rapid-deployment spray systems. FDA's 21 CFR 878.4490 premarket notification pathway compresses development timelines for absorbable hemostats. The Texas Medical Center cluster anchors procurement negotiations for bundled surgical consumables across multi-hospital systems.
Germany
Notified bodies in Berlin and Munich apply stringent MDR Article 10 interpretations for legacy device recertification. EMA's clinical evidence thresholds filter market entrants lacking five-year safety databases. The Baden-Württemberg medical technology corridor concentrates sterilization validation expertise for gelatin matrix manufacturers.
China
NMPA's medical device classification system creates dual-track approval pathways for imported versus domestic formulations. Yangtze River Delta surgical centers in Shanghai and Suzhou adopt viscosity-tuned matrices for laparoscopic procedure volumes. Local manufacturers leverage GB standards compliance to undercut pricing for paste formulations.
Japan
PMDA's pharmaceutical affairs law governs hemostatic devices with pharmacological action as combination products. Kansai region hospitals in Osaka prioritize pre-measured applicator bundles for minimally invasive workflows. METI's medical device industry revitalization program subsidizes domestic spray delivery system development.
India
CDSCO's medical device rules mandate registration for Class C and D hemostatic products effective 2023. Maharashtra's Mumbai-Pune corridor attracts contract manufacturing for gelatin-based matrices serving export markets. Government medical colleges in Delhi and Chennai establish flowable hemostatic protocols for trauma surgery training.
Hemostatic Gels Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and sterilization validation capabilities. The vendor base organizes into three tiers: integrated hospital supply contractors, specialized minimally invasive formulation developers, and regional distributors maintaining inventory positions for mid-tier surgical centers. Dominant competitive moves include bundled product wrapping with adjunct sealants and direct distribution relationships bypassing integrated delivery networks.
Within the integrated supply tier, Baxter International and Ethicon occupy positions anchoring hospital system contracts through procedure-specific bundles. BD exemplifies the direct distribution archetype, sustaining channel control via surgical center relationships. Among emerging technology developers, Medcura and Hemostasis LLC represent the specialized formulation segment targeting coagulopathic patient populations.
| Leading Market Players |
|---|
| Ethicon |
| Baxter International |
| BD |
| Artivion |
| Medcura |
| Hemostasis LLC |
| GELITA Medical |
| Pfizer |
| B. Braun |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates qualified supply access and premium-tier pricing corridors for absorbable hemostat manufacturers, filtering out uncertified competitors from institutional procurement channels while elevating validated formulations to trauma care premium tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies hemostatic gel procurement, with FDA-cleared spray delivery systems commanding trauma care premiums against cost-sensitive gauze alternatives for dental applications. Price differentiation hinges on sterilization validation depth and viscosity engineering precision for laparoscopic compatibility. Cost compression in paste formulations is intensifying because bovine gelatin supply volatility squeezes matrix-based manufacturers. Dental clinics exhibit highest price sensitivity, while Level I trauma centers absorb premium positioning for rapid-deployment configurations.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China anchor hub-and-spoke fulfillment patterns for hemostatic gel manufacturers serving multi-hospital systems. Raw material sourcing draws from bovine and porcine gelatin processors in North America, oxidized cellulose suppliers in Europe, and polysaccharide complex formulators in Asia. Single-source vulnerability concentrates in livestock-derived gelatin chains exposed to disease outbreak disruptions. Distribution runs through integrated hospital supply contracts wrapping gels with adjunct sealants, displacing standalone distributor relationships in large health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hemostatic gel procurement has shifted toward procedure-specific bundles with pre-measured applicators, rewarding manufacturers with sterilization validation depth and integrated supply contracts.
For Market Incumbents: To counter mechanical hemostat substitution in open abdominal procedures, anchor hospital system formularies through bundled surgical consumable contracts spanning sealants and adhesion barriers. Deepen backward integration into gelatin matrix production to insulate margins from livestock supply volatility. Prioritize CE marking pathway investments for MDR Article 10 compliance in German notified body jurisdictions. For New Entrants and Emerging Players: Capture standalone ambulatory surgical center direct purchasing relationships in Texas and Florida markets bypassing integrated delivery networks. Target spray delivery system white space in high-volume cataract and arthroscopy workflows where waste reduction drives conversion. Lead with procedure-specific bundle economics rather than standalone gel pricing. For Investors and Strategic Acquirers: Roll-up economics work for specialized formulation developers with ISO 10993 validation depth because sterilization expertise scarcity limits replication speed. Five-to-ten year viability favors hybrid biopolymer-enzyme platforms addressing coagulopathic populations outside standard surgical candidates. Monitor FDA expanded access program enrollment velocity as signal for label expansion feasibility without prospective trial costs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance unlocks German trauma center procurement channels previously restricted to legacy devices. |
| Hospital System Partnership | Integrated supply contracts with 15-plus OR systems displace distributor relationships through bundled consumable formularies. |
| Backward Integration | In-house gelatin matrix production insulates margins from bovine supply chain disease outbreak volatility. |
| Reimbursement Strategy | HCPCS code alignment across Medicare Advantage and commercial plans reduces hospital formulary committee adoption friction. |
| Software Companion Development | Real-time coagulation monitoring integration differentiates spray delivery systems in ambulatory surgical center workflows. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract reviews, regulatory filing assessments, and clinician workflow observations — were reconciled through structured primary interviews with hospital purchasing committee members, biomedical engineers, trauma surgeons, and sterilization validation specialists. Secondary validation incorporated FDA 510(k) clearances, EMA MDR submission databases, ISO 10993 biocompatibility test reports, and CMS Medicare reimbursement schedules. Bottom-up facility-level demand estimates and top-down market sizing triangulated volume and value outputs.
Data-stream reconciliation across product type, end-user facility scale, application urgency tier, and distribution channel configuration generated segment-level projections over the analysis window. CAGRs were derived from surgical procedure volume elasticity, trauma care infrastructure expansion rates, and ambulatory surgical center conversion patterns. Forecast inputs incorporated sterilization validation cycle durations, gelatin raw material price indices, and regional reimbursement code harmonization trajectories.
Regulatory pathway delays, livestock disease outbreak frequency, and ambulatory surgical center conversion velocity are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Hydroxyapatite Market
Biomaterials
US Heparin Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Global Biomaterials Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Chitosan Market