
 Passenger Car Accessories Market | 2026-2036
Passenger Car Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Car Accessories Market Outlook
REACH compliance is restructuring the cost-of-entry calculus for European aftermarket suppliers, forcing reformulation of plastics, adhesives, and textile treatments used in cabin accessories. Robert Bosch GmbH leverages its sensor-integration capabilities to compete in smart accessory modules that interface with vehicle CAN bus architectures. Denso Corporation anchors its position through captive manufacturing of climate-controlled storage and power-delivery accessories. Continental AG specializes in connected accessory ecosystems that merge infotainment extension hardware with cybersecurity protocols.
Passenger car accessories comprise add-on components and systems designed to enhance vehicle functionality, occupant comfort, aesthetic personalization, or protective utility, typically manufactured from polymer composites, technical textiles, formed metals, or electronic assemblies with specifications governed by OEM fitment protocols and aftermarket SAE/ISO dimensional standards. Their primary commercial purpose spans owner customization, fleet asset protection, residual value preservation, and technology extension beyond base vehicle configuration. Floor mats and seat covers represent mature, high-volume segments where margin pools concentrate in premium all-weather and custom-fit configurations, while roof racks and dash covers occupy faster-growing niches driven by outdoor recreation trends and UV-degradation awareness in sun-belt markets. Distribution through online retail channels is displacing traditional specialty store foot traffic, though dealerships retain leverage in integrated-solution bundling with new vehicle purchases.
The US EPA regulates VOC emissions from interior accessories under indoor air quality proxy standards, while China's SAMR enforces GB standards for material flammability and electrical accessory safety in aftermarket installations. The EU's F-Gas Regulation shapes demand for climate-controlled accessory systems by restricting refrigerant-dependent cooling technologies. Stakeholders must monitor divergence between OEM-integrated accessory architectures and regulatory treatment of standalone aftermarket installations as software-defined vehicle platforms tighten access protocols.
Market Dynamics
Software-defined vehicle architectures are tightening access protocols for aftermarket accessory integration, forcing suppliers to choose between OEM partnership certification or standalone low-connectivity product lines. This technical gatekeeping is redistributing margin pools toward CAN bus-compliant smart modules and away from passive cabin accessories.
Growth Catalysts
- EU Green Deal material mandates:Recycled polymer quotas and low-VOC coating requirements are accelerating supplier retooling toward sustainable interior accessory production, creating first-mover certification advantages.
- Fleet operator procurement expansion:Commercial vehicle operators are standardizing accessory bundling across vehicle classes to enforce brand consistency and asset protection protocols at scale.
- China's e-commerce aftermarket penetration:Domestic platforms are displacing traditional specialty retail through direct-to-consumer fitment tools and same-day installation networks.
Market Restraints
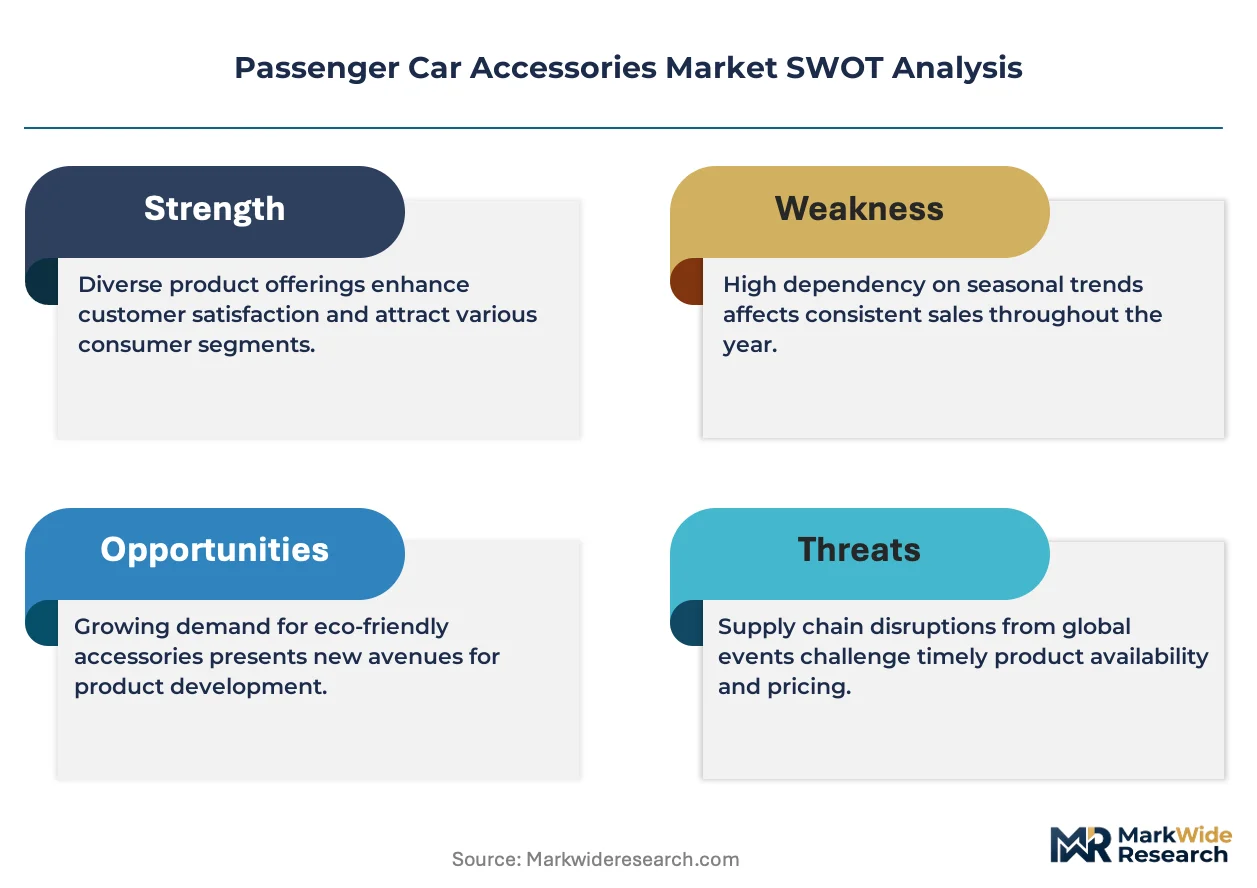
- REACH compliance cost escalation:European aftermarket suppliers face reformulation expenses for plastics, adhesives, and textile treatments that compress margins on entry-level product lines.
- Polymer feedstock volatility:Technical-grade polymer composite prices fluctuate with petrochemical input costs, exposing accessory manufacturers to margin squeeze during energy price spikes.
- CAN bus access restriction:OEM-controlled electronic architectures limit third-party smart accessory functionality to non-integrated power and data pathways.
Strategic Opportunities
- Climate-controlled storage systems:F-Gas Regulation restrictions on refrigerant-dependent cooling create market space for thermoelectric and phase-change alternatives in EU markets.
- Connected infotainment extension hardware:Cybersecurity protocol integration represents a white space for suppliers capable of merging hardware with encrypted data handling.
- Outdoor recreation accessory bundling:Roof rack and cargo management systems tied to adventure tourism are penetrating underdeveloped segments in Nordic and Alpine markets.
Industry Challenges
- Embedded software certification timelines:Smart accessory modules require cybersecurity validation against evolving OEM protocols, extending product development cycles.
- Legacy vehicle compatibility engineering:Suppliers must maintain parallel SKU lines for pre-CAN bus electrical architectures while developing next-generation connected products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Car Accessories Market |
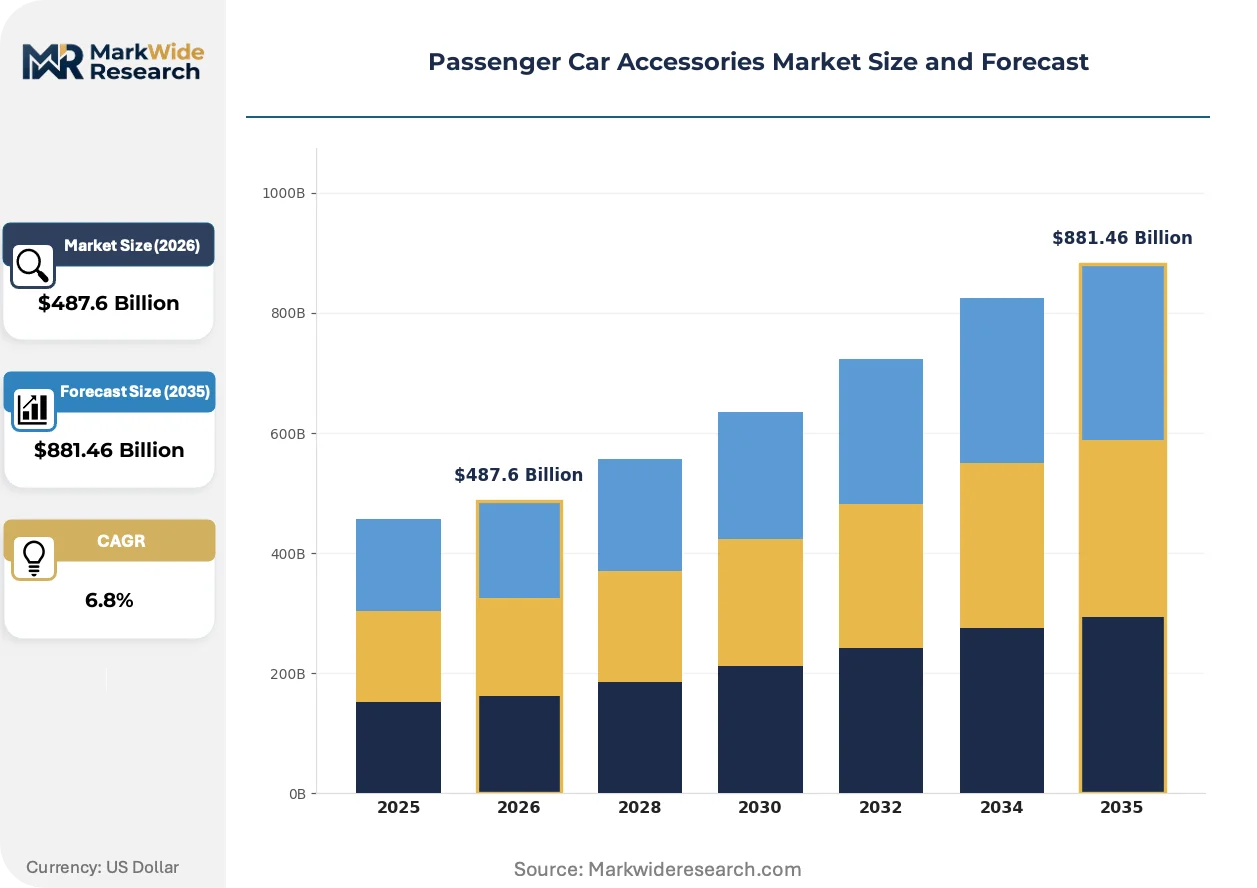
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Mats, Seat Covers, Roof Racks, Dash Covers Distribution Channel: Online Retail, Dealerships, Specialty Stores, Mass Merchants End User: Individual Consumers, Fleet Operators, Commercial Users, Car Enthusiasts Installation Type: DIY, Professional, Semi-Professional, Integrated Solutions |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, Lear Corporation, Magna International Inc., Faurecia SE, Valeo S.A., Covercraft Industries, Harman International Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Car Accessories Market Strategic Shifts
Integration complexity is the dominant force reshaping competitive positioning. Accessory suppliers must now engineer for electronic interoperability rather than purely mechanical fitment, elevating software competency alongside traditional polymer and metal forming capabilities.
Sensor-integrated smart modules are consolidating control functions previously handled by discrete cabin accessories. These assemblies combine occupancy detection, climate feedback, and power management into unified hardware that interfaces directly with vehicle bus architectures. Premium fleet operators and luxury OEM bundling programs are adopting these modules fastest. The technology is consolidating aftermarket demand into fewer, higher-value SKUs while marginalizing passive accessory categories.
REACH chemical restrictions are forcing systematic reformulation of interior accessory materials across European supply chains. ECHA substance candidate list expansions now cover flame retardants and plasticizers common in cabin textiles and formed polymer components. Aftermarket suppliers serving Germany and France are accelerating substitution programs for phthalate-based softeners and halogenated flame retardants. Technical textile manufacturers are pivoting toward bio-based polyurethane coatings to maintain market access.
Online retail channels are capturing share from specialty store networks through virtual fitment visualization and installation service bundling. Chinese consumers increasingly expect AR-enabled preview tools and doorstep technician dispatch as standard purchase components. Traditional brick-and-footprint distributors in North American and European markets are responding with hybrid click-and-collect models and certified installer partnerships. This channel migration is most visible in floor mat and seat cover categories where dimensional precision drives return rates.
Passenger Car Accessories Market Segmentation
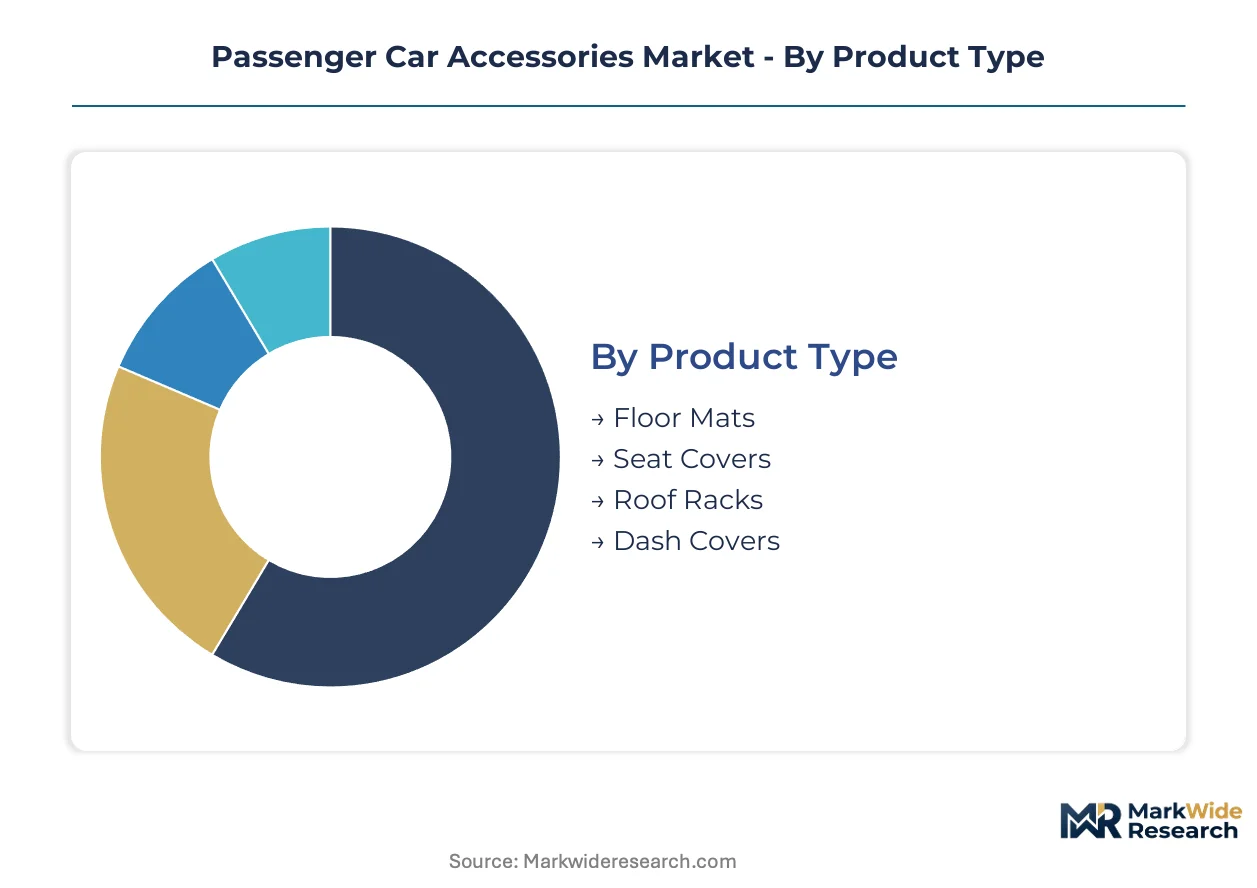
Segmentation in passenger car accessories reveals divergent certification burdens and margin structures. Product type determines material compliance requirements, while distribution channel shapes customer acquisition economics and installation complexity.
Product Type:
Floor mats and seat covers face REACH chemical restrictions on phthalates and flame retardants in EU markets. Roof racks and dash covers trigger GB standards compliance for material flammability and UV stability in China.
- Floor Mats:Polymer composites with anti-slip backing and retention anchoring systems dominate specification sheets. Demand concentrates in premium all-weather configurations across Germany and the US Midwest, where fleet operators standardize fitment for asset protection protocols. REACH reformulation costs compress margins on economy-tier rubber compounds.
- Seat Covers:Technical textiles with bio-based polyurethane coatings replace legacy phthalate-treated fabrics for ECHA compliance. China's domestic OEM bundling programs and aftermarket e-commerce platforms absorb the highest unit volumes, driven by residual value preservation consciousness among individual owners.
- Roof Racks:Aluminum extrusion and composite crossbar assemblies engineered for dynamic load ratings.
- Dash Covers:Formed polymer or textile wraps with UV-stabilized surfaces for cabin thermal management.
Leading the category by volume: floor mats. Growing fastest: roof racks, climbing on outdoor recreation accessory bundling.
Distribution Channel:
Channel selection determines installation service bundling requirements and return rate exposure. Online retail demands virtual fitment tools and technician dispatch networks, while dealerships leverage integrated-solution certification with OEM architectures.
- Online Retail:Direct-to-consumer platforms with AR-enabled preview tools and same-day installation networks reshape procurement patterns. China's e-commerce penetration leads globally, with domestic platforms displacing specialty store foot traffic through doorstep technician dispatch as standard purchase components.
- Dealerships:OEM-integrated accessory bundling with new vehicle purchases retains leverage in smart module categories requiring CAN bus certification. US dealership networks concentrate margin capture in climate-controlled storage and infotainment extension hardware with encrypted data handling protocols.
- Specialty Stores:Brick-and-footprint networks pivoting toward hybrid click-and-collect models and certified installer partnerships.
- Mass Merchants:High-volume, low-touch distribution for standardized fitment categories with minimal installation complexity.
Highest margin capture: dealerships in connected accessory categories. Most rapidly expanding: online retail, gaining share fastest in floor mat and seat cover segments where dimensional precision tools reduce return rates.
End User:
End user type dictates procurement scale and customization depth. Fleet operators enforce brand consistency protocols, while car enthusiasts drive specification complexity.
- Individual Consumers:Personalization and residual value preservation motivate accessory selection, with AR-enabled visualization tools reducing fitment uncertainty in online channels.
- Fleet Operators:Commercial vehicle operators standardize accessory bundling across vehicle classes for asset protection and brand consistency at scale, absorbing premium all-weather floor mats and climate-controlled storage modules fastest.
- Commercial Users:Utility-focused procurement emphasizing durability and warranty coverage.
- Car Enthusiasts:Specification-driven demand for custom-fit configurations and technology extension hardware.
Dominant procurement volume: individual consumers. Steepest expansion trajectory: fleet operators, accelerating standardization across vehicle classes.
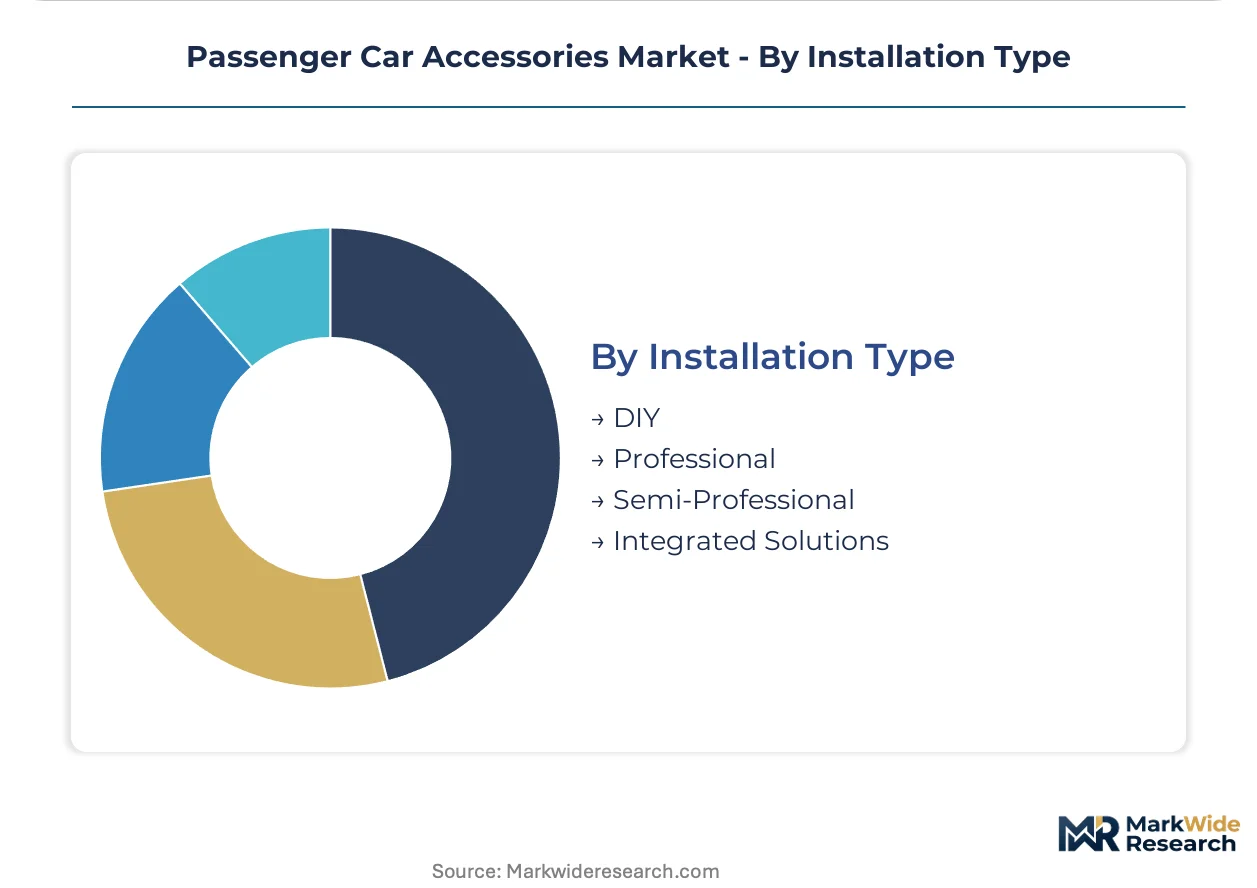
Installation Type:
Installation complexity correlates with electronic integration depth and warranty liability exposure. CAN bus-compliant smart modules require professional certification, while passive accessories tolerate DIY fitment.
- DIY:Tool-free fitment for passive cabin accessories like floor mats and dash covers, minimizing labor cost and enabling e-commerce penetration.
- Professional:Certified technician installation for CAN bus-integrated smart modules, climate-controlled storage systems, and cybersecurity protocol-enabled infotainment extensions, required for OEM warranty preservation.
- Semi-Professional:Dealer-trained installer networks for complex mechanical fitments without electronic integration.
- Integrated Solutions:Factory-installed accessory bundling with new vehicle purchases, capturing highest margin pools through OEM partnership certification.
Highest volume: DIY for passive categories. Margin concentration: integrated solutions, with professional installation expanding most quickly on software-defined vehicle architecture restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta concentrate accessory manufacturing capacity for export-oriented production. Germany's automotive clusters anchor European supply chains for precision-engineered cabin components. The United States, Japan, and India complete the geographic spread with distinct regulatory and demand profiles.
China
Domestic OEM accessory bundling and e-commerce platform penetration drive procurement volume concentration. SAMR enforces GB standards for material flammability and electrical safety in aftermarket installations. Shanghai and Suzhou industrial parks host thermoelectric cooling module production for climate-controlled storage systems.
Germany
Fleet operator standardization and premium vehicle customization sustain demand for CAN bus-compliant smart modules. REACH compliance through ECHA mandates reformulation of plastics, adhesives, and textile treatments. Stuttgart and Munich automotive clusters engineer connected infotainment extension hardware with embedded cybersecurity protocols.
United States
Outdoor recreation trends and UV-degradation awareness propel roof rack and cargo management adoption. EPA regulates VOC emissions from interior accessories under indoor air quality proxy standards. Michigan and Ohio manufacturing corridors supply all-weather floor mat configurations for fleet asset protection programs.
Japan
Residual value preservation consciousness and technology extension hardware demand shape consumer accessory selection. METI oversees JIS standards compliance for vehicle electronics integration. Nagoya and Osaka industrial zones specialize in sensor-integrated smart modules for luxury OEM bundling partnerships.
India
Aftermarket e-commerce penetration and individual owner customization expand addressable market depth. BIS certification requirements govern material safety and electrical accessory standards for domestic installations. Tamil Nadu and Gujarat automotive corridors manufacture cost-optimized seat cover textiles for regional export.
Passenger Car Accessories Market Competitive Environment
German producers anchor the premium-tier smart module segment; Asian specialists hold volume positions in passive cabin accessories. The market structure bifurcates between consolidated OEM-integrated system suppliers and fragmented aftermarket component fabricators. Three archetypes dominate: sensor-integration specialists, climate-control module manufacturers, and connected infotainment extension developers. Strategic moves concentrate on CAN bus certification partnerships and sustainable material substitution programs.
Within the sensor-integration tier, Robert Bosch GmbH and Denso Corporation exemplify the OEM-certified archetype. Continental AG occupies a position representing connected ecosystem development. These entities anchor the competitive structure through their respective specializations in electronic interoperability, climate-controlled storage, and cybersecurity-enabled hardware architectures.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Lear Corporation |
| Magna International Inc. |
| Faurecia SE |
| Valeo S.A. |
| Covercraft Industries |
| Harman International Industries |
| Others |
Value Chain & Pricing Dynamics
Polymer composite engineers concentrated in China's Yangtze River Delta manufacturing zones create labor-cost differentials that widen pricing-tier spreads between premium CAN bus-compliant modules and economy passive accessories. REACH reformulation expenses for European suppliers and GB standards compliance costs in China further stratify procurement economics across certification grades.
Pricing Analysis
Short lead-time premiums for OEM-certified smart modules run 15-25% above spot inventory pricing for passive cabin accessories. Three-tier pricing structure across premium, standard, and economy levels separates CAN bus-integrated climate-controlled storage from tool-fit floor mats and generic dash covers. Price differentiation hinges on cybersecurity protocol certification and volume-scale procurement from fleet operators. Cost compression in economy rubber compounds is intensifying because REACH-mandated phthalate substitutions erode margins on entry-tier floor mats. Fleet operators show least price sensitivity for integrated solutions; individual e-commerce buyers drive hardest bargain on seat covers.
Supply Chain Analysis
Reverse-logistics networks for AR-enabled fitment returns and textile refurbishment flow back through Suzhou and Shanghai consolidation hubs before resale into secondary markets. Manufacturing gravity centers on China, Germany, and the United States for distinct competency clusters. Raw material inputs draw from technical-grade polymer resins, aluminum extrusion billets, and bio-based polyurethane coatings. Single-source vulnerability concentrates in ECHA-compliant textile treatments from specialized German chemical suppliers. Distribution runs through direct-to-consumer platforms with technician dispatch networks displacing traditional specialty store wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer feedstock volatility and skilled electronics integration labor scarcity constrain capacity expansion, propping pricing power for certified suppliers across the analysis window.
For Market Incumbents: Hedge margin exposure by securing captive supply of REACH-compliant textile treatments through backward integration into coating chemistry partnerships. Accelerate CAN bus certification timelines with Stuttgart and Munich automotive clusters before OEM access protocols tighten further. Sensor-integrated module consolidation threatens passive accessory incumbents; defend through exclusive fleet operator bundling contracts. For New Entrants and Emerging Players: Begin with thermoelectric cooling modules for EU climate-controlled storage segments where F-Gas Regulation restrictions create white-space demand. Nordic and Alpine outdoor recreation accessory bundling offers lowest competitive density for roof rack and cargo management entry. Go-to-market leverage: AR-enabled fitment tools paired with doorstep installation networks on domestic Chinese platforms. For Investors and Strategic Acquirers: Re-rating potential sits with cybersecurity-enabled infotainment extension developers given OEM software-defined vehicle architecture rollouts. Long-term viability favors suppliers with dual competency in polymer forming and embedded systems engineering. Acquisition target archetype: mid-cap climate-control specialists with ECHA certification and thermoelectric IP. Signal to watch: fleet operator standardization announcements across vehicle classes.| Strategic Initiative | Industry Significance |
|---|---|
| CAN Bus Certification Partnership | Robert Bosch GmbH and Denso Corporation anchor OEM-integrated smart module supply through proprietary electronic interoperability protocols. |
| Sustainable Material Substitution Program | REACH-mandated bio-based polyurethane coatings replace legacy phthalate treatments to maintain ECHA market access for seat cover textiles. |
| Direct-to-Consumer Platform Launch | AR-enabled preview tools and same-day technician dispatch networks displace specialty store foot traffic in China's aftermarket. |
| Climate-Controlled Storage Expansion | Thermoelectric cooling alternatives capture EU market share as F-Gas Regulation restricts refrigerant-dependent technologies. |
| Cybersecurity Protocol Integration | Continental AG merges infotainment extension hardware with encrypted data handling to meet OEM software-defined vehicle requirements. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and dealership accessory managers. Secondary sources included ECHA substance candidate lists, SAMR GB standards documentation, EPA VOC emission proxies, and vehicle production databases. Bottom-up SKU-level volume estimates triangulated against top-down regional consumption models.
Data-stream reconciliation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster shaped the analytical framework. CAGRs were derived from regression-based trajectory fitting against historical penetration curves and regulatory implementation timelines. Industry-specific inputs encompassed fleet operator standardization announcements, e-commerce platform transaction velocities, and REACH reformulation cost pass-through assumptions.
Polymer feedstock price spikes, OEM access protocol tightening, and REACH chemical list expansion are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption S-curves. Practitioners should monitor ECHA substance candidate list updates, fleet procurement RFP releases, and OEM software architecture disclosure patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Stampings Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Ball Bearing Market