
 Tow Bar Market | 2026-2036
Tow Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Tow Bar Market Analytics
Class IV and V heavy-duty rating upgrades is rotating demand toward higher-load-capacity tow bars in North American and European aftermarket channels. Westfalia-Automotive GmbH leverages its German engineering heritage to dominate OEM supply agreements with premium European automakers. Curt Manufacturing LLC anchors its position through deep vertical integration into steel forging and powder-coat finishing operations. Thule Group AB differentiates via brand equity in outdoor recreation segments where consumers prioritize integrated rack-and-tow systems.
A tow bar is a rigid or articulating coupling device, typically fabricated from high-strength carbon steel or 6061-T6 aluminum alloy with rated capacities from 2,000 to 20,000 pounds, that connects a towing vehicle to a trailer or towed load through a standardized hitch receiver or flange mounting. Its primary function is to transmit tractive, braking, and lateral forces while maintaining geometric stability between vehicle and trailer. Detachable tow bars command premium positioning in European passenger car applications where parking convenience and aesthetic preservation drive replacement cycles. Steel remains the volume leader in frame-mounted applications for trucks and commercial vans, though aluminum gains share in SUVs where weight reduction directly improves fuel economy compliance.
ECE R55 type-approval administered by Germany's KBA shapes European product design by mandating dynamic and static load testing protocols. The US NHTSA enforces FMVSS rear impact and lighting integration standards that affect bumper-mounted system configurations. China's GB standards for automotive towing devices, overseen by SAMR, are converging toward UN-ECE technical harmonization. Stakeholders must monitor regulatory divergence between UN-ECE aligned markets and legacy national standards when configuring regional product portfolios and homologation budgets.
Market Dynamics
Homologation complexity is fragmenting product portfolios as manufacturers engineer parallel SKUs for ECE R55-aligned markets versus legacy national standards, compressing margin structures and elongating development cycles.
Growth Catalysts
- ECE R55 harmonization:UN-ECE technical alignment across 56 contracting parties streamlines type-approval for cross-border fleet operators, reducing duplicate testing costs for tow bar suppliers serving pan-European logistics networks.
- Aluminum 6061-T6 adoption:SUV manufacturers specify forged aluminum tow bars to meet fleet-average CO2 mandates, creating pull-through demand in aftermarket channels as owners seek weight-matched replacement components.
- Light truck fleet expansion:Commercial logistics providers in the United States are standardizing Class IV and V rated systems for last-mile delivery vehicles, anchoring volume procurement through national distributor networks.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs fluctuate with energy-intensive European smelter output, pressuring margin stability for forged-component manufacturers without captive melt shop capacity.
- Homologation timeline fragmentation:China's SAMR maintains GB standard divergence from UN-ECE protocols, forcing dedicated testing regimes for domestic-market SKUs and duplicating certification expenditure.
- Integrated hitch systems:OEMs in Germany increasingly factory-fit concealed receiver modules, constraining aftermarket attach rates for traditional bumper-mounted tow bar configurations.
Strategic Opportunities
- Electric vehicle towing packages:Range-conscious EV manufacturers in the United States seek lightweight aluminum coupling systems with integrated wiring harnesses, opening white space absent legacy supplier incumbency.
- Direct-to-installer e-commerce:Specialized automotive platforms bypass traditional distributor markups, capturing margin compression value for independent repair shops and mobile fitting services.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive parts attract capacity relocation from high-cost European forging operations, establishing export-competitive supply bases.
Industry Challenges
- Weld certification scarcity:Qualified aluminum TIG welders for aerospace-grade 6061-T6 fabrication command premium wages, constraining production scaling for lightweight tow bar programs.
- Homologation documentation burden:KBA-administered ECE R55 approval requires dynamic fatigue testing to 2 million cycles, extending product launch timelines and freezing engineering resources on legacy platform maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tow Bar Market |
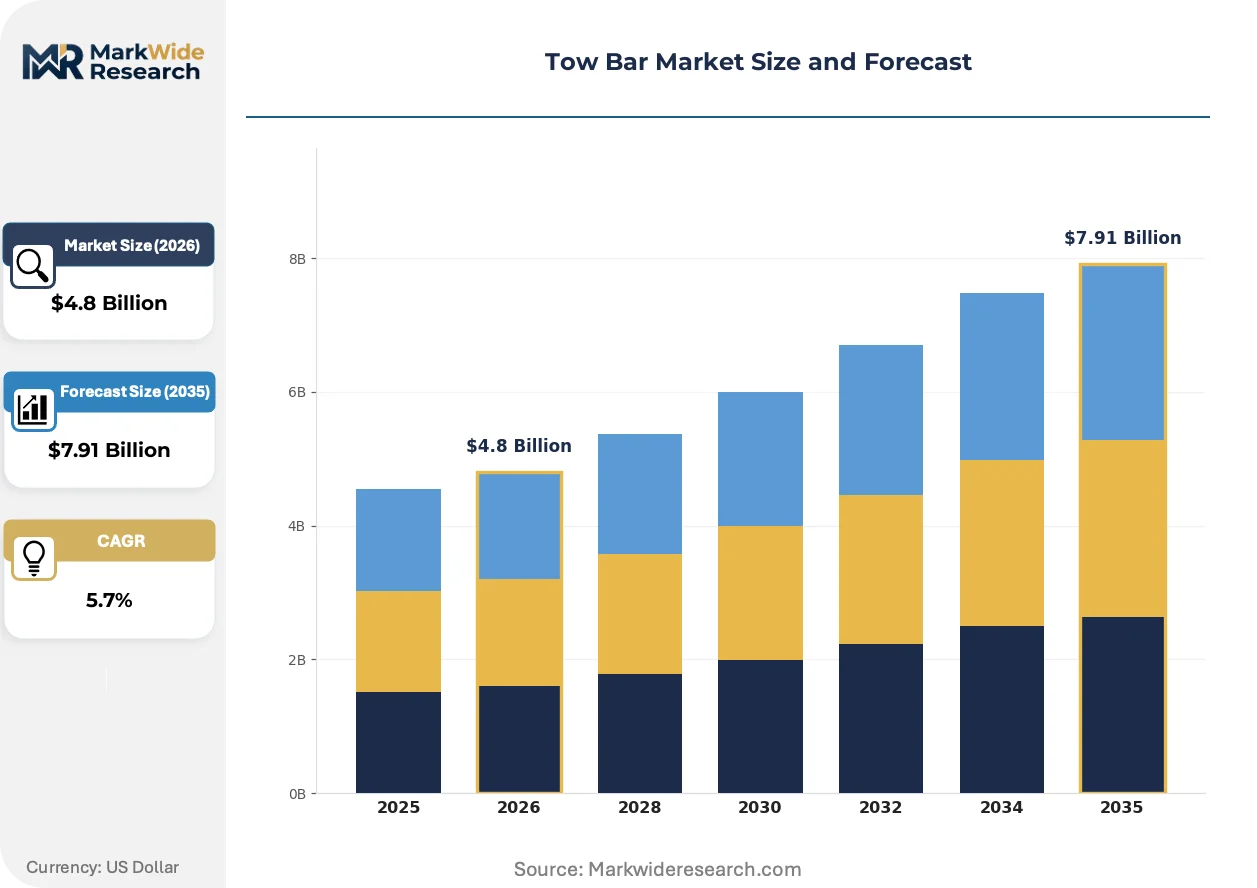
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed Tow Bars, Detachable Tow Bars, Retractable Tow Bars, Adjustable Tow Bars Vehicle Type: Passenger Cars, SUVs, Trucks, Vans Mounting Style: Frame Mounted, Bumper Mounted, Chassis Mounted, Above Bumper Material: Steel, Aluminum, Composite, Plastic |
| Companies Covered | Westfalia-Automotive GmbH, Hayman Reese, Curt Manufacturing LLC, Thule Group AB, ACPS Automotive GmbH, Bosal International N.V., Horizon Global, PCT Automotive Limited, Brink Group B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tow Bar Market Evolving Landscape
Material substitution and regulatory convergence are compressing traditional product lifecycles while opening new specification tiers for specialized applications. Three developments are restructuring competitive positioning.
Detachable swan-neck tow bars with integrated electrics are displacing fixed flange-mounted systems in European passenger car segments. German premium automakers specify these configurations for leasing fleet vehicles where residual value sensitivity demands invisible towing capability. The shift is compressing demand for traditional welded-steel permanent installations in compact SUV categories.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to zinc-nickel or organic coating systems for corrosion protection. European surface treatment suppliers are requalifying salt-spray performance to 720-hour specifications under revised ECHA guidance. Powder-coat finishing operations in Germany and Poland are capturing volume from electroplating shops facing compliance-driven capacity constraints.
Commercial fleet operators are consolidating procurement through national leasing companies rather than fragmented dealer networks. These aggregators specify standardized Class IV systems across mixed light-truck fleets, displacing individualized aftermarket selection. The pattern is most visible in United States logistics corridors where national rental chains negotiate multi-year supply agreements with direct manufacturer relationships.
Tow Bar Market Segmentation
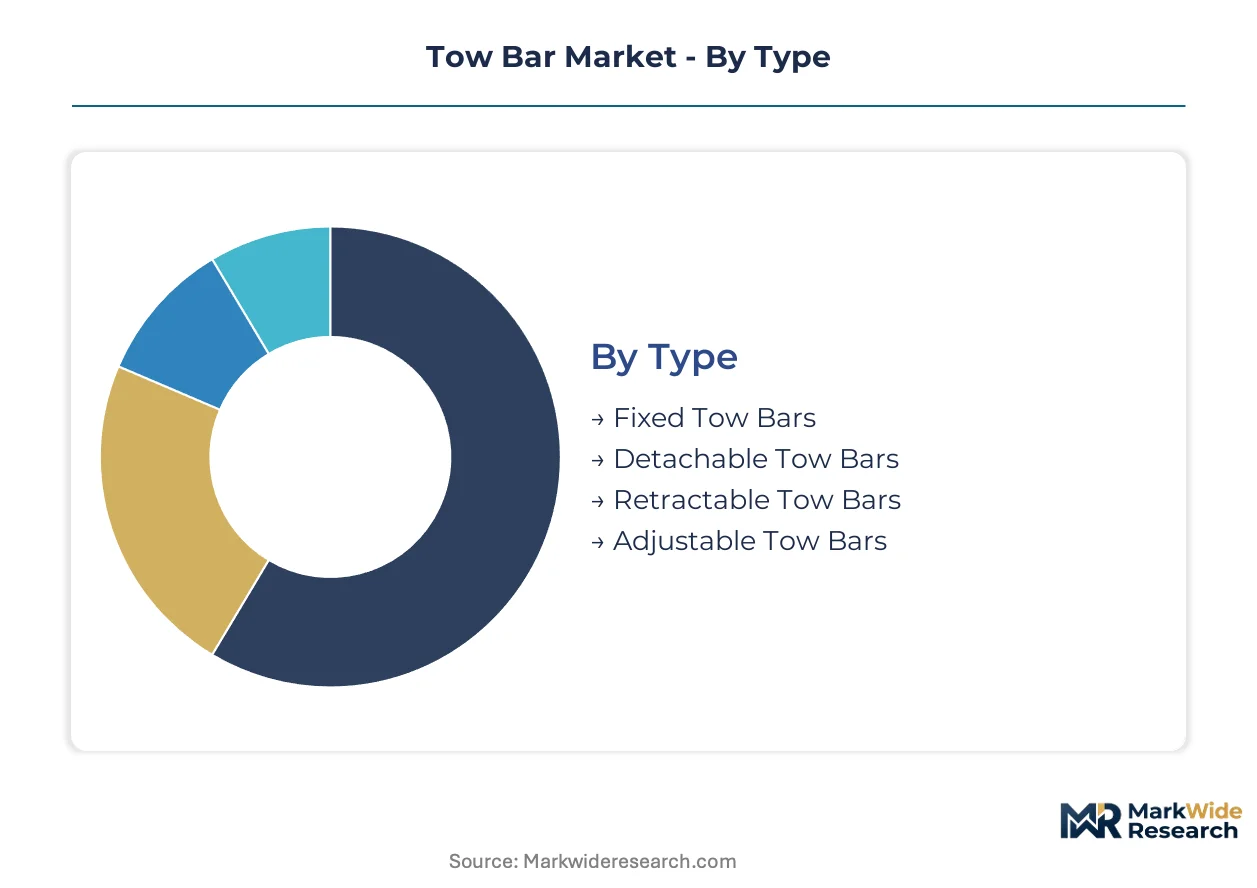
Tow bar procurement patterns diverge sharply across mounting configurations, vehicle architectures, and material specifications. Fleet operators and aftermarket distributors configure inventory depth around these axes to align with regional homologation requirements and end-use duty cycles.
Type:
ECE R55 type-approval protocols in Germany and UN-ECE aligned markets favor designs permitting rapid coupling verification, while FMVSS rear-impact standards in the United States prioritize fixed-structure crashworthiness.
- Fixed Tow Bars:Welded-steel permanent installations dominate commercial truck and van applications where load ratings exceed 10,000 pounds. United States logistics corridors anchor volume procurement through national leasing companies standardizing Class IV and V configurations.
- Detachable Tow Bars:Swan-neck designs with integrated electrics command premium positioning in European passenger car segments. German premium automakers specify these for leasing fleets where residual value sensitivity demands invisible towing capability.
- Retractable Tow Bars:Concealed receiver modules factory-fitted by OEMs constrain aftermarket attach rates.
- Adjustable Tow Bars:Height-variable configurations serve mixed-height trailer fleets in agricultural and construction sectors.
Fixed tow bars handle the majority of throughput; detachable tow bars are the fastest mover on share.
Vehicle Type:
Application-driven specification tiers separate high-cycle commercial duty from occasional recreational use.
- Passenger Cars:Compact sedan applications concentrate in European markets where detachable systems preserve bumper aesthetics. KBA-administered ECE R55 testing mandates 2 million cycle fatigue validation for these lighter-duty configurations.
- SUVs:Mid-size and full-size sport utility vehicles drive aluminum 6061-T6 adoption to meet fleet-average CO2 compliance. United States consumers pull weight-matched replacement components through aftermarket channels.
- Trucks:Light-duty and heavy-duty pickup segments standardize frame-mounted steel systems for fifth-wheel and gooseneck compatibility.
- Vans:Commercial delivery fleets in Germany and the United States specify integrated wiring harnesses for trailer lighting compliance.
Trucks generate the highest absolute unit volumes; SUVs are climbing the fastest on material-upgrade demand.
Mounting Style:
Structural integration depth determines crashworthiness certification pathways and installation labor economics.
- Frame Mounted:Direct chassis attachment distributes torsional loads across rail structures. Heavy-duty applications in the United States require FMVSS rear-impact compliance testing for bumper reinforcement compatibility.
- Bumper Mounted:Receiver tube integration through stamped bumper beams serves light-duty SUVs and crossovers. German OEMs increasingly factory-fit concealed variants, compressing aftermarket opportunity.
- Chassis Mounted:Commercial van upfitters in Europe specify these for auxiliary axle and tag-along trailer configurations.
- Above Bumper:Specialty applications for oversized recreational vehicles require elevated coupling heights.
Frame mounted systems carry the bulk of heavy-duty throughput; bumper mounted configurations face steepest share compression from OEM pre-installation.
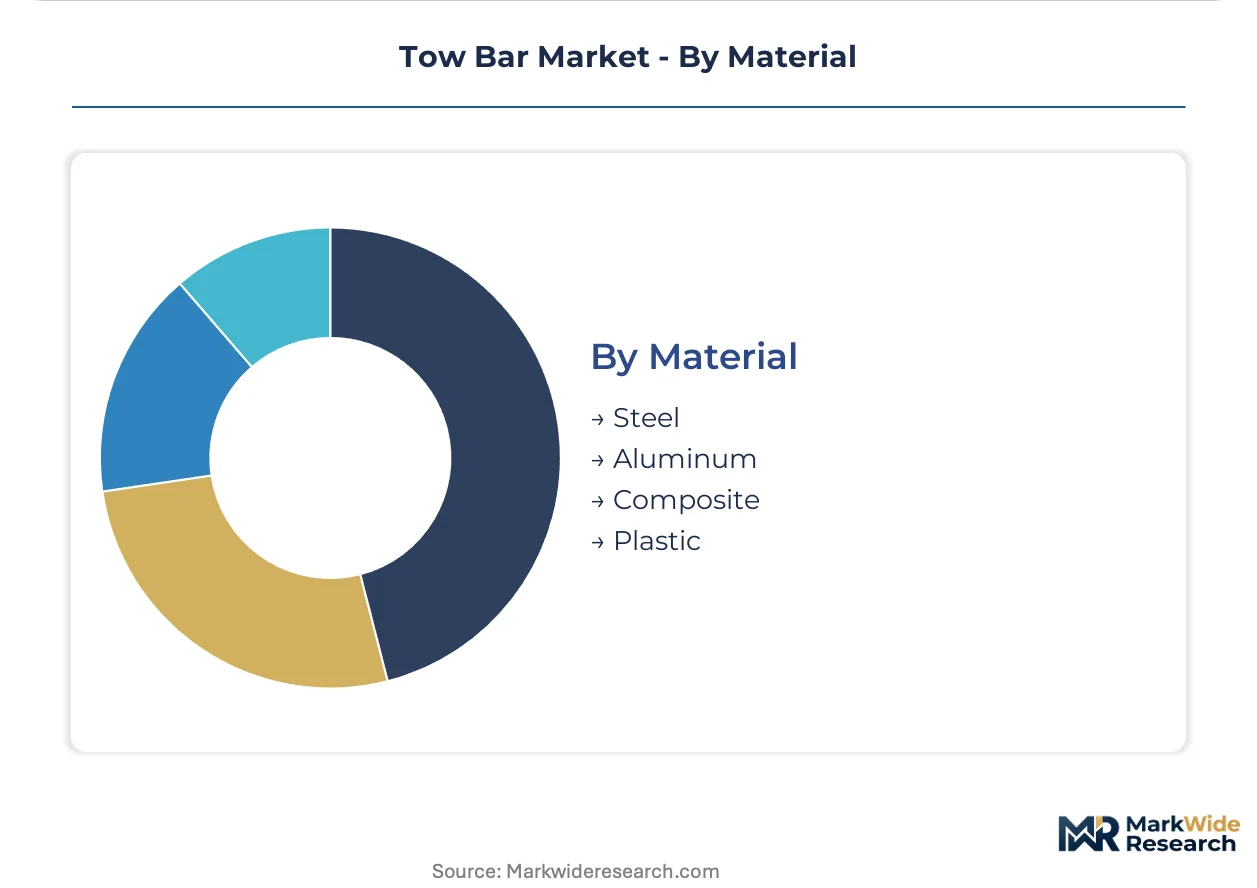
Material:
Weight-performance tradeoffs and coating compliance costs stratify procurement across end-use segments.
- Steel:High-strength carbon steel remains the volume leader in frame-mounted truck and commercial van applications. Hot-rolled coil price volatility pressures margin stability for forged-component manufacturers without captive melt capacity.
- Aluminum:6061-T6 forged alloys gain share in SUVs where mass reduction improves fuel economy compliance. Qualified TIG welders for aerospace-grade fabrication command premium wages, constraining production scaling.
- Composite:Glass-reinforced polymer trials focus on corrosion-resistant marine and coastal applications.
- Plastic:Decorative fascia and electrical housing components only; no structural load-bearing applications.
Steel maintains dominant throughput; aluminum is expanding most quickly on regulatory-driven weight reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forging capacity and automotive OEM supply chains concentrate in Germany, the United States, China, India, and Australia. Each market operates under distinct homologation regimes that shape product specifications and aftermarket penetration rates.
Germany
KBA-administered ECE R55 type-approval mandates 2 million cycle fatigue testing for passenger car tow bars, elevating engineering standards. The country's REACH substance restrictions on hexavalent chromium plating force conversion to zinc-nickel coating systems. North Rhine-Westphalia hosts dense clusters of surface treatment suppliers requalifying salt-spray performance to 720-hour specifications.
United States
NHTSA enforces FMVSS rear-impact standards that govern bumper-mounted system crashworthiness for light trucks and SUVs. Class IV and V heavy-duty rating upgrades drive procurement through national leasing companies standardizing fleet configurations. Michigan and Ohio anchor forging operations supplying frame-mounted steel systems for commercial logistics providers.
China
SAMR oversees GB standards for automotive towing devices that maintain divergence from UN-ECE protocols, forcing dedicated domestic-market SKUs. Light truck fleet expansion for last-mile delivery creates pull-through demand for higher-load-capacity systems. Yangtze River Delta manufacturing bases produce both steel and aluminum 6061-T6 configurations for domestic OEM supply.
India
PLI scheme production-linked incentives for advanced automotive components attract capacity relocation from European forging operations. BIS certification requirements for automotive towing devices are converging toward UN-ECE technical harmonization. Maharashtra and Gujarat host emerging export-competitive supply bases serving Middle Eastern and African markets.
Australia
ADR compliance standards for trailer coupling devices align closely with UN-ECE frameworks, facilitating import acceptance from certified suppliers. Recreational towing demand for caravans and boat trailers sustains aftermarket channel depth. Queensland and Western Australia concentrate specialist fabricators serving coastal corrosion-resistant applications.
Tow Bar Market Competitive Landscape
Concentration sits with German engineering-led OEM suppliers and North American vertically integrated manufacturers. The vendor base spans three tiers: premium European specialists commanding type-approval expertise, mid-scale regional fabricators serving fleet procurement, and emerging Asian producers capturing cost-sensitive export volumes. Strategic moves center on homologation documentation capabilities and backward integration into steel forging or aluminum TIG fabrication.
Among German-based specialists, Westfalia-Automotive GmbH and ACPS Automotive GmbH exemplify the premium engineering archetype anchored in ECE R55 certification leadership. Curt Manufacturing LLC represents North American scale-driven positioning through in-house production of forged components and powder-coat finishing operations. Thule Group AB occupies a distinct position linking tow bar specifications to outdoor recreation brand equity and integrated rack-and-tow system demand.
| Leading Market Players |
|---|
| Westfalia-Automotive GmbH |
| Hayman Reese |
| Curt Manufacturing LLC |
| Thule Group AB |
| ACPS Automotive GmbH |
| Bosal International N.V. |
| Horizon Global |
| PCT Automotive Limited |
| Brink Group B.V. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German forging houses lock in billet supply and freeze price visibility for ECE R55-certified tow bar manufacturers, insulating premium tier producers from hot-rolled coil volatility while exposing spot-market buyers to margin compression.
Pricing Analysis
ECE R55 dictates the pricing tier structure by stratifying certification-grade premiums across KBA-validated suppliers, standard-tier national fabricators, and uncertified import alternatives. Price differentiation hinges on homologation documentation depth and captive forging capacity, with OEM supply agreements commanding the widest spreads. Cost compression in standard-tier channels is intensifying because Chinese aluminum 6061-T6 forging capacity is expanding into European aftermarket segments. Fleet procurement through national leasing companies exhibits the lowest price sensitivity, while independent mobile installers face the highest.
Supply Chain Analysis
Inventory cycles for forged steel components stretch to twelve weeks, forcing aftermarket distributors to pre-position Class IV and V systems ahead of seasonal fleet renewal windows. Manufacturing gravity centers on Germany, the United States, and China, with raw material flows drawing from Ukrainian billet, Australian bauxite, and domestic hot-rolled coil. Single-source vulnerability concentrates in qualified aluminum TIG welding capacity for aerospace-grade 6061-T6 fabrication. Distribution runs through national automotive parts wholesalers with direct-to-installer e-commerce capturing incremental share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum 6061-T6 substitution and ECE R55 harmonization are accelerating product lifecycle compression, creating asymmetric opportunity for suppliers with captive homologation expertise.
For Market Incumbents: Shield margin position by securing captive forging capacity in Poland or India's PLI-eligible zones before raw material volatility escalates. Accelerate ECE R55 documentation archives to defend against emerging Chinese competitors with faster certification cycles but weaker dynamic testing capabilities. For New Entrants and Emerging Players: Direct-to-installer digital platforms represent the most penetrable service layer where incumbent distributors impose heavy markups on independent repair shops. Target mobile fitting services in United States logistics corridors with integrated wiring harness bundles and same-day fulfillment guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale German specialists with KBA type-approval pipelines and underutilized powder-coat finishing capacity. Watch for aluminum TIG welder wage inflation as the inflection signal that lightweight tow bar production scaling has hit structural constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive billet supply from Polish melt shops insulates margin from energy-driven European steel volatility. |
| ECE R55 Certification Pipeline Expansion | KBA-validated testing capacity in North Rhine-Westphalia accelerates product launch timelines for premium OEM contracts. |
| Direct-to-Installer E-Commerce Launch | Bypassing traditional distributor markups captures margin compression value from independent mobile fitting services. |
| Aluminum 6061-T6 Welding Capacity Addition | Qualified TIG fabrication cells address the binding constraint on lightweight tow bar production scaling. |
| India PLI-Eligible Manufacturing Footprint | Maharashtra and Gujarat supply bases serve Middle Eastern and African export markets with cost-competitive output. |
Research Methodology
Desk research of customs trade databases, vehicle production registries, and KBA type-approval filings preceded structured interviews with Tier 1 supplier procurement managers, aftermarket distributor operations heads, and mobile installation service owners. Primary fieldwork combined with secondary validation from IHS Markit registration data and SEC filings of listed automotive component manufacturers. Bottom-up unit demand estimates triangulated against top-down fleet penetration assumptions.
Variance decomposition across vehicle class, mounting configuration, material specification, and regional homologation cluster shaped the analytical framework throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to fleet replacement cycles and regulatory compliance deadlines. Industry-specific inputs included ECE R55 certification timelines, aluminum alloy spot pricing, and commercial leasing fleet standardization patterns.
Underlying assumptions cover stable ECE-FMVSS regulatory divergence, with deviation risk concentrated in SAMR's GB standard convergence timeline and European smelter energy cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Brake Pads Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Racing Motor Bike Seat Unit Market