
 Automotive Timing Chain Market | 2026-2036
Automotive Timing Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Timing Chain Market Analysis
Steel is restructuring cost-performance trade-offs across the Automotive Timing Chain landscape as alloy grades replace conventional carbon formulations in high-load camshaft drives. Schaeffler AG leverages its in-house steel metallurgy capabilities to anchor European OEM supply contracts for silent chain systems. BorgWarner Inc. competes through integrated cam-phaser and timing chain module architectures that reduce assembly complexity for North American light-truck platforms. Tsubakimoto B.V dominates precision roller manufacturing for Japanese passenger vehicle programs with sub-50-micron pitch tolerance control.
An automotive timing chain is a metal linkage mechanism that synchronizes crankshaft and camshaft rotation through precisely engineered pitch intervals, typically manufactured via multi-stage stamping, heat treatment, and shot-peening processes to achieve fatigue resistance exceeding 200 million cycles. Silent chain configurations command premium positioning in passenger vehicle applications where noise-vibration-harshness thresholds have tightened, while double row architectures retain volume leadership in commercial vehicle and heavy-duty truck segments where load distribution demands exceed single-row capacity. Roller chain deployments in the aftermarket channel face margin compression from low-cost Asian imports, contrasting with OEM captive supply arrangements that sustain higher value capture through specification-locked procurement.
The EPA enforces Corporate Average Fuel Economy standards that indirectly shape timing chain specification by penalizing powertrain friction losses, while NHTSA crashworthiness protocols influence packaging constraints that favor compact chain-drive layouts over belt alternatives. China's NMPA and MIIT jointly administer GB standards for engine noise emissions that mandate acoustic testing protocols affecting silent chain adoption rates in domestic vehicle production. Stakeholders must monitor regulatory divergence between Euro 7 preparation in Europe and evolving EPA rulemakings, as divergent friction-reduction timelines will fragment material and design roadmaps across major supply contracts.
Market Dynamics
Silent chain architectures are displacing conventional roller designs as OEMs in Germany and Japan prioritize noise-vibration-harshness reduction in passenger vehicle powertrains, restructuring procurement specifications across high-volume engine programs.
Growth Catalysts
- China NMPA noise-emission enforcement:Stricter GB standards for internal combustion engines mandate acoustic testing protocols that accelerate material upgrades toward silent chain configurations in domestic vehicle production.
- Hybrid vehicle localization:Hyundai and Kia in South Korea are expanding captive precision chain manufacturing for hybrid powertrains, creating pull-through demand for sub-50-micron tolerance control.
- Shot-peening process advances:Multi-stage heat treatment innovations achieving fatigue resistance beyond 200 million cycles are extending replacement intervals and strengthening OEM specification locks.
Market Restraints
- Alloy steel cost volatility:Specialized metallurgy grades replacing carbon formulations in high-load camshaft drives expose suppliers to nickel and chromium price swings that compress margin buffers.
- Japanese supply concentration:Precision roller manufacturing for passenger vehicle programs clusters with Tsubakimoto-level tolerance specialists, creating single-source vulnerability for Tier 2 module assemblers.
- Belt-drive substitution in compact engines:Timing belt systems retain cost advantage in sub-1.5L displacement categories where load demands do not justify chain-drive durability premiums.
Strategic Opportunities
- Aftermarket channel restructuring:Low-cost Asian import saturation in roller chain replacement creates white space for certified remanufacturing programs that capture margin through specification-locked distribution.
- EPA-NHTSA regulatory convergence:Corporate Average Fuel Economy friction penalties and crashworthiness packaging constraints jointly favor compact chain-drive layouts that reduce powertrain envelope dimensions.
- Commercial vehicle double-row expansion:Heavy-duty truck segments where load distribution exceeds single-row capacity present underpenetrated demand for hardened pin bushing architectures.
Industry Challenges
- Metallurgy talent scarcity:In-house steel alloy development capabilities at Schaeffler-level sophistication require specialized fatigue engineering expertise that concentrates in German and Japanese industrial clusters.
- Cam-phaser integration complexity:BorgWarner-type module architectures combining variable valve timing actuators with chain drives demand synchronized calibration protocols that extend validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Timing Chain Market |
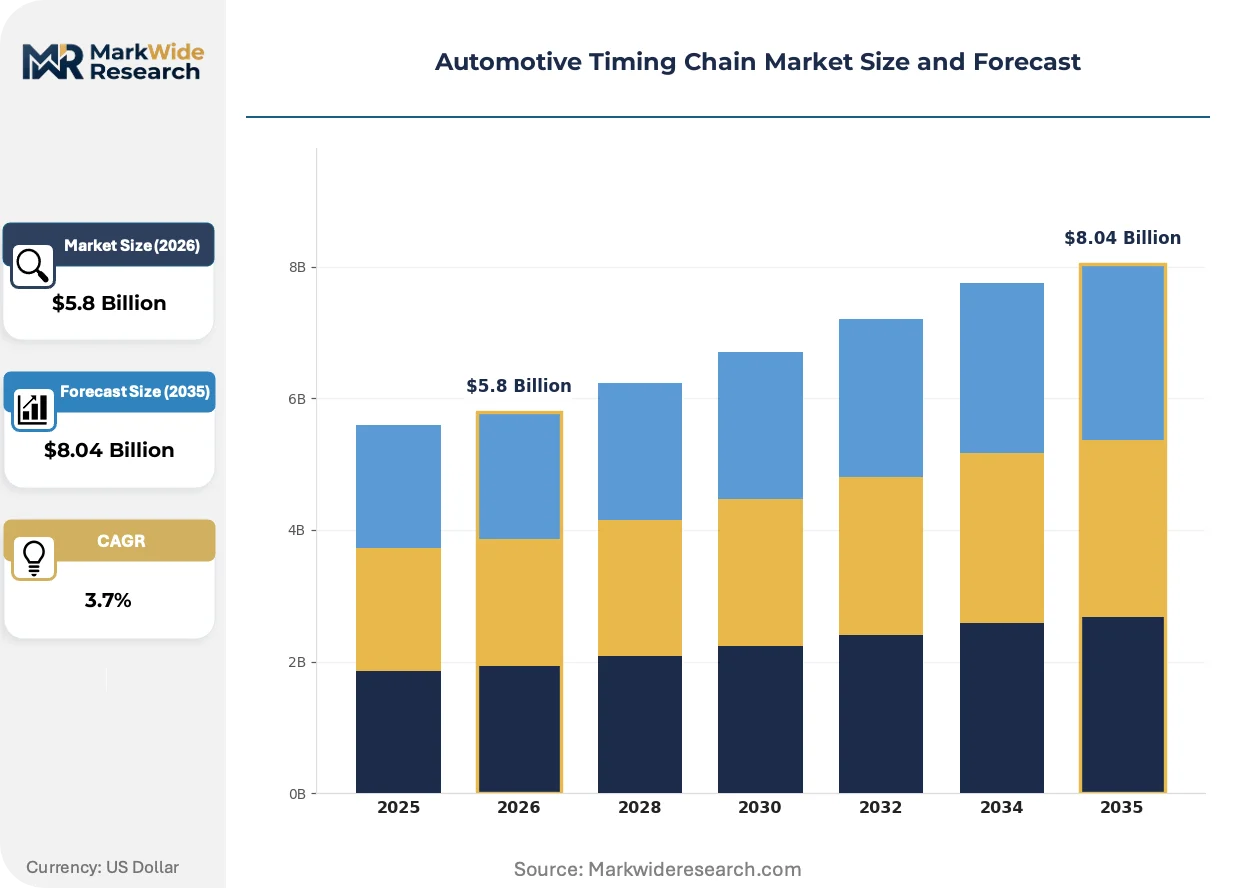
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Row, Double Row, Silent Chain, Roller Chain Material: Steel, Carbon Steel, Alloy Steel, Plastic Deployment: Aftermarket, Original Equipment Manufacturer, Hybrid, Electric End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Aisin Corporation, MAHLE GmbH, BorgWarner Inc., FAI Automotive plc, Dayco IP Holdings LLC, Continental AG, Tsubakimoto B.V, Renold Plc, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Timing Chain Market Emerging Trajectories
Material science breakthroughs and regulatory friction-reduction mandates are converging to redefine timing chain value propositions, compressing the traditional trade-off between acoustic performance and mechanical durability.
Advanced silent chain link-plate profiles incorporating curved tooth geometries are unifying noise suppression with tensile strength previously achievable only through roller chain bulk. Passenger vehicle OEMs in Germany are specifying these configurations for four-cylinder turbocharged programs where NVH thresholds have tightened. The technology is unifying formerly separate premium and standard-tier procurement categories into single-source qualification frameworks.
China's MIIT is administering updated GB standards for engine noise emissions that mandate third-party acoustic certification before homologation. Domestic manufacturers must retest existing chain suppliers against revised decibel thresholds, accelerating specification migration toward silent architectures. Japanese OEMs with joint-venture operations in China are transferring JIS-grade precision manufacturing protocols to comply.
Fleet operators and independent repair channels are consolidating purchases through certified distributor networks that bypass traditional jobber intermediaries. Large commercial vehicle fleets in North America now specify direct-to-installer contracts with documented fatigue-cycle traceability. This pattern concentrates procurement volume with suppliers offering serialized production-lot documentation.
Automotive Timing Chain Market Segmentation
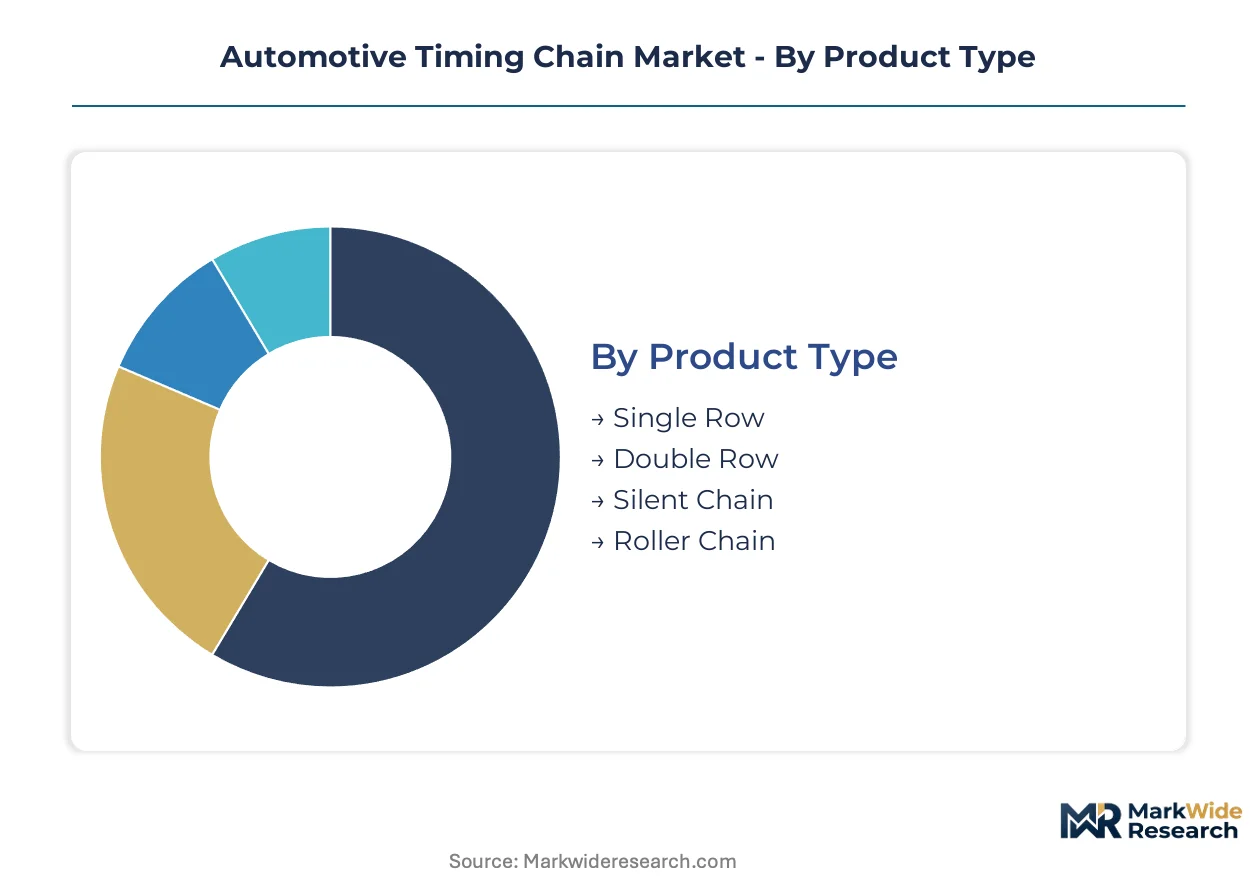
Timing chain procurement splits across four distinct axes that reshape supplier qualification frameworks. Product architecture determines noise-emission compliance paths, while material grade selection locks in fatigue-cycle performance. Deployment channel and end-use specifications further fragment pricing and certification requirements across the value chain.
Product Type:
Chain architecture directly determines NVH performance thresholds and load-bearing capacity in synchronized crankshaft-camshaft applications.
- Silent Chain:Curved tooth link-plate profiles integrate noise suppression with tensile strength previously requiring roller chain bulk. Demand concentrates in German and Japanese passenger vehicle programs where OEMs pursue quieter powertrain operation under tightening acoustic regulations.
- Double Row:Parallel chain strands distribute camshaft drive loads across redundant load paths, achieving durability margins for commercial vehicle duty cycles. Heavy-duty truck manufacturers in North America specify these configurations where single-row capacity proves insufficient for high-torque diesel architectures.
- Single Row:Compact envelope dimensions suit sub-2.0L displacement engines where packaging constraints favor minimal chain-drive footprints.
- Roller Chain:Conventional pin-bushing architectures retain aftermarket volume leadership despite margin compression from low-cost Asian imports.
Mature deployment sits with Roller Chain. Newer deployment is concentrated in Silent Chain.
Material:
Metallurgy grade selection structures cost-performance trade-offs and fatigue resistance specifications across OEM supply contracts.
- Alloy Steel:Nickel-chromium formulations replace carbon grades in high-load camshaft drives, achieving fatigue resistance exceeding 200 million cycles through multi-stage heat treatment. South Korean hybrid vehicle programs specify these grades for extended replacement intervals.
- Steel:Standard-grade metallurgy anchors volume production for mid-market passenger vehicles where specification-locked procurement sustains supplier margins.
- Carbon Steel:Baseline formulations face displacement in high-load applications as alloy grades penetrate premium engine programs.
- Plastic:Polymer link-plate prototypes target auxiliary drive applications where load demands permit non-metallic construction.
Volume concentration remains with Steel. Specification migration is accelerating toward Alloy Steel.
Deployment:
Channel configuration determines margin structure, certification requirements, and traceability documentation obligations.
- Original Equipment Manufacturer:Captive supply arrangements sustain higher value capture through specification-locked procurement and serialized production-lot documentation. Chinese domestic manufacturers must retest chain suppliers against revised NMPA decibel thresholds before homologation.
- Hybrid:Dual-powertrain architectures demand precision chain manufacturing with sub-50-micron pitch tolerance control. Hyundai and Kia in South Korea are localizing production for these programs.
- Aftermarket:Roller chain replacement faces margin compression from low-cost Asian imports, creating white space for certified remanufacturing programs.
- Electric:Reduced internal combustion content limits addressable chain applications to range-extender and hybrid-electric transitional architectures.
Margin protection concentrates with Original Equipment Manufacturer. Channel expansion is gaining share fastest in Hybrid.
End User:
Vehicle category dictates load distribution requirements, durability specifications, and replacement interval expectations.
- Passenger Vehicles:Four-cylinder turbocharged programs in Germany specify advanced silent chain configurations where NVH thresholds have tightened most aggressively. China's MIIT noise-emission enforcement accelerates material upgrades in this segment.
- Heavy-Duty Trucks:Load distribution demands exceed single-row capacity, creating underpenetrated demand for hardened pin bushing architectures with documented fatigue-cycle traceability.
- Commercial Vehicles:Fleet operators in North America consolidate purchases through certified distributor networks that bypass traditional jobber intermediaries.
- Two-Wheelers:Cost-sensitive displacement categories retain timing belt systems where load demands do not justify chain-drive durability premiums.
Specification leadership sits with Passenger Vehicles. Volume expansion is climbing the fastest in Heavy-Duty Trucks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate precision chain manufacturing capacity, attracting joint-venture investments from Japanese and German OEM suppliers seeking proximity to domestic vehicle assembly plants.
Germany
Passenger vehicle OEMs in Stuttgart and Munich specify silent chain architectures for four-cylinder turbocharged programs under tightening Euro 7 preparation timelines. The KBA enforces stricter noise-emission protocols that accelerate material upgrades from conventional roller designs. Baden-Württemberg's industrial corridor hosts Schaeffler AG's in-house steel metallurgy operations anchoring European supply contracts.
China
Domestic manufacturers in Shanghai and Changchun retest chain suppliers against revised NMPA decibel thresholds before homologation. The MIIT administers updated GB standards for engine noise emissions that mandate third-party acoustic certification. Joint-venture operations in the Yangtze River Delta transfer JIS-grade precision manufacturing protocols to comply with stricter thresholds.
Japan
Passenger vehicle programs in Toyota City and Yokohama pursue quieter powertrain operation through sub-50-micron pitch tolerance control. METI coordinates domestic noise-reduction targets that align with export market regulations. Aichi Prefecture's supplier cluster specializes in curved tooth link-plate profiles unifying noise suppression with tensile strength.
South Korea
Hyundai and Kia in Ulsan and Hwaseong localize precision chain production for hybrid vehicle programs requiring extended replacement intervals. The MFDS framework indirectly shapes component quality expectations through broader industrial standards enforcement. Gyeonggi Province's manufacturing belt concentrates captive supply arrangements for dual-powertrain architectures.
United States
Light-truck manufacturers in Detroit and Flint specify integrated cam-phaser and timing chain module architectures for North American platforms. The EPA enforces Corporate Average Fuel Economy standards that penalize powertrain friction losses, favoring compact chain-drive layouts. Michigan's automotive corridor sustains specification-locked procurement relationships with module suppliers.
Automotive Timing Chain Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive OEM supply arrangements sustaining higher value capture than aftermarket channels facing low-cost import saturation. The vendor base organizes around three archetypes: integrated module suppliers combining variable valve timing with chain drives, precision metallurgy specialists controlling in-house alloy development, and volume-focused fabricators serving replacement markets. Consolidation pressures favor backward integration into steel processing and upstream control over heat-treatment capacity.
Among German-based integrated suppliers, Schaeffler AG and Continental AG exemplify the metallurgy-forward archetype, while BorgWarner Inc. represents the module-integration tier. These three anchors demonstrate how geographic clustering around Stuttgart, Munich, and Auburn Hills concentrates differentiated capabilities rather than commoditized production.
| Leading Market Players |
|---|
| Aisin Corporation |
| MAHLE GmbH |
| BorgWarner Inc. |
| FAI Automotive plc |
| Dayco IP Holdings LLC |
| Continental AG |
| Tsubakimoto B.V |
| Renold Plc |
| Schaeffler AG |
| Others |
Supply Flow & Price Mechanics
Nickel-chromium alloy index volatility cascades through timing chain manufacturing tiers, compressing margin buffers for carbon-grade suppliers while hardening specification-locked premiums for metallurgy-forward producers serving German and Japanese OEM programs. China's NMPA noise-emission enforcement fragments procurement into decibel-certified premium tiers versus conventional roller alternatives facing aftermarket price erosion.
Pricing Analysis
Short-lead-time premiums of 15-25 percent apply to silent chain orders from German passenger vehicle OEMs facing Euro 7 homologation deadlines, while spot inventory of roller configurations trades at compressed margins. Three-tier pricing structure across premium silent, standard alloy, and economy carbon grades differentiates on fatigue-cycle certification and NMPA acoustic compliance. Pricing pressure stems from low-cost Asian import saturation in aftermarket roller replacement. Fleet operators in North America demonstrate lowest price sensitivity due to documented fatigue-traceability requirements, while independent jobbers in the replacement channel exhibit highest elasticity.
Supply Chain Analysis
Returns and remanufacturing flows from commercial vehicle fleets in North America feed certified distributor networks with serialized production-lot documentation, bypassing traditional jobber intermediaries. Primary manufacturing concentrates in Germany, China, and Japan, with Baden-Württemberg and Aichi Prefecture hosting metallurgy-specialist clusters. Nickel-chromium alloy feedstock and precision stamping tooling anchor upstream dependencies. Single-source vulnerability clusters around Tsubakimoto-level tolerance specialists for Japanese passenger vehicle programs. Distribution runs through captive OEM supply arrangements sustaining higher value capture than aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where China's NMPA decibel thresholds and Euro 7 preparation erect barrier-to-entry moats favoring metallurgy-capable incumbents with in-house alloy development.
For Market Incumbents: Deploy backward integration into heat-treatment capacity to anchor specification-locked supply relationships against low-cost Asian import substitution in aftermarket channels. Schaeffler-level in-house steel metallurgy capabilities should expand to capture hybrid vehicle localization demand from South Korean OEMs. Threat concentration sits with belt-drive substitution in sub-1.5L compact engines where load demands do not justify chain-drive premiums. For New Entrants and Emerging Players: Sub-50-micron pitch tolerance control technology offers entry wedge into South Korean hybrid vehicle programs where Hyundai and Kia are localizing precision chain production. White space concentrates in certified remanufacturing programs for North American commercial vehicle fleets demanding fatigue-cycle traceability. Go-to-market angle should target direct-to-installer contracts bypassing traditional jobber intermediaries. For Investors and Strategic Acquirers: The window for entry favors metallurgy-specialist mid-caps with JIS-grade precision manufacturing protocols transferable to Chinese joint-venture operations. Long-term viability hinges on five-to-ten year regulatory convergence between EPA friction-reduction mandates and Euro 7 noise-emission timelines. Acquisition target archetype: precision tolerance specialists with heat-treatment capacity in automotive manufacturing clusters. Signal to monitor: NMPA enforcement consistency and MIIT GB standard revision cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Captive control over fatigue-cycle performance anchors specification-locked OEM contracts against import substitution. |
| Hybrid Vehicle Localization Partnership | Proximity to Hyundai-Kia Ulsan operations reduces logistics exposure while meeting sub-50-micron tolerance requirements. |
| Certified Remanufacturing Program Launch | Serialized production-lot documentation captures fleet operator procurement consolidation away from low-cost Asian imports. |
| Silent Chain Acoustic Certification Investment | Third-party NMPA and KBA compliance testing enables premium tier positioning in tightening noise-emission regimes. |
| Cam-Phaser Module Integration | BorgWarner-type architectures reduce assembly complexity for North American light-truck OEMs facing EPA friction penalties. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, aftermarket distributor operations managers, and heat-treatment facility supervisors underwrites the qualitative findings in this study. Secondary validation draws from vehicle production databases, IHS Markit registration data, NMPA acoustic certification filings, and SEC supplier disclosures. Bottom-up segmentation modeling triangulates with top-down macroeconomic anchors across the analysis window.
Rate-of-change decomposition separates volume growth from value-mix shifts across silent chain, double row, single row, and roller architectures, further disaggregated by alloy steel versus carbon steel material grades and OEM versus aftermarket deployment channels. CAGRs derive from regression against vehicle production forecasts, content-per-vehicle trajectories, and replacement interval extensions from shot-peening process advances. Industry-specific inputs include Euro 7 preparation timelines and NMPA enforcement intensity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel-chromium price volatility and belt-drive substitution acceleration in compact engine segments. Practitioners should monitor NMPA decibel threshold revision announcements and EPA-NHTSA regulatory convergence signals for early indicators of specification migration speed.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Vents Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market