
 Global Automotive Torque Converter Market | 2026-2036
Global Automotive Torque Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Torque Converter Market Analysis
Software-defined transmission calibration is decoupling hardware sales from recurring revenue streams across the torque converter value chain. Aisin Corporation leverages its captive foundry capacity in Japan to sustain margin control on turbine blade forgings. ZF Friedrichshafen AG anchors European supply through integrated torque converter and transmission assembly lines in Germany. BorgWarner Inc. competes in North America by specializing in lock-up clutch modules that improve highway fuel economy ratings.
An automotive torque converter is a fluid coupling device that transmits rotating power from an internal combustion engine to an automatic transmission, typically using a pump impeller, turbine runner, and stator assembly with torque multiplication ratios between 1.7 and 2.5 at stall. Its primary commercial purpose is to enable smooth vehicle launch and load isolation while permitting engine idle operation without mechanical clutch engagement. The automatic product type segment retains dominant volume share across passenger and commercial vehicle applications, though hybrid technology variants are gaining fastest growth as electrified powertrains require modified torque converter architectures with integrated electric motor dampers. Hydraulic technology still occupies the majority of installed base, yet electric actuator controls are displacing traditional valve body hydraulics in premium segment designs where precision lock-up timing commands price premiums.
The EPA enforces Corporate Average Fuel Economy standards that compel torque converter manufacturers to optimize lock-up engagement maps for emissions compliance across the US light-duty fleet. EMA in Europe coordinates type-approval testing under Euro 7 provisions that will tighten particulate and nitrogen oxide limits, forcing redesigns of transmission thermal management where torque converter stall characteristics influence engine load cycles. China's MIIT administers dual carbon goals that pressure domestic automakers to source locally produced torque converters with efficiency ratings aligned to national new energy vehicle quotas. Stakeholders must monitor how split hybrid architectures alter the functional role of torque converters as powertrain electrification deepens across major automotive production regions.
Market Dynamics
Powertrain electrification is bifurcating torque converter demand between legacy internal combustion architectures and hybrid-electric variants requiring integrated motor-damper assemblies. This structural shift concentrates investment in lock-up clutch precision and thermal management systems.
Growth Catalysts
- EPA Phase 3 Standards:Fleet operators in the United States are expanding heavy-duty automatic transmission procurement to meet tightening greenhouse gas efficiency mandates.
- China MIIT Dual Carbon Goals:Domestic automakers must source locally manufactured torque converters aligned with national new energy vehicle quotas.
- Hybrid Powertrain Proliferation:Split hybrid architectures are sustaining torque converter relevance through modified turbine-stator designs with electric motor integration.
Market Restraints
- Steel and Aluminum Input Volatility:Turbine blade forging costs fluctuate with commodity prices, compressing margin control for independent suppliers.
- Foundry Capacity Concentration:Captive Japanese foundry networks limit third-party access to precision casting capabilities for high-stall-ratio designs.
- Electric Axle Substitution:Battery-electric powertrains eliminate torque converter functionality entirely in dedicated EV platforms.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive components attract localized torque converter manufacturing for domestic passenger vehicle expansion.
- Software-Defined Calibration:Over-the-air transmission tuning creates recurring revenue streams decoupled from hardware replacement cycles.
- Commercial Vehicle Electrification:Heavy-duty hybrid buses and trucks require torque converters with integrated torsional dampers for stop-start optimization.
Industry Challenges
- Multi-Physics Simulation Talent:Fluid-structure interaction modeling for lock-up clutch engagement requires scarce computational engineering expertise.
- Euro 7 Thermal Validation:Extended certification timelines for transmission thermal management systems delay platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Torque Converter Market |
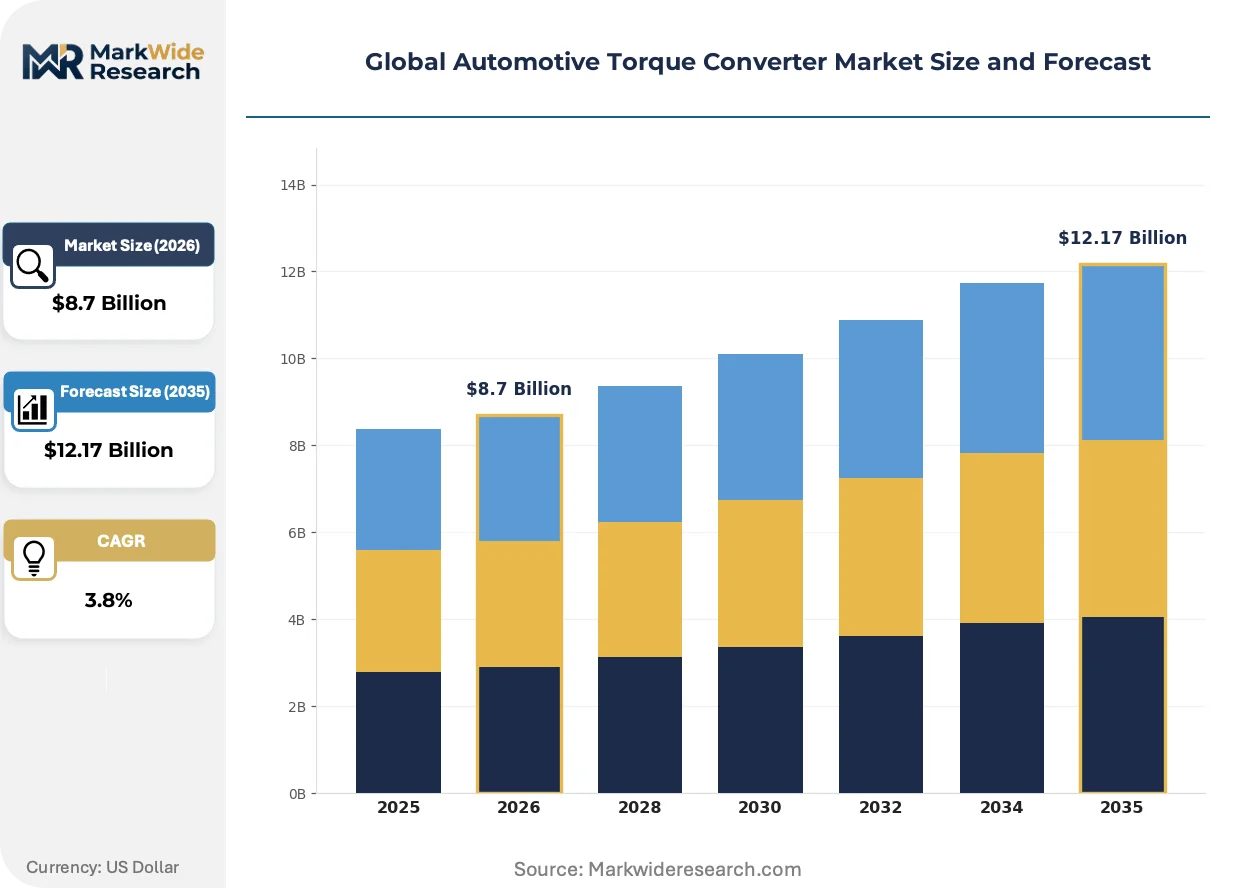
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, CVT, Dual-Clutch End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery Technology: Hydraulic, Mechanical, Electric, Hybrid Application: Gaming, Simulation, Training, Performance Testing |
| Companies Covered | Aisin Corporation, ZF Friedrichshafen AG, BorgWarner Inc., Continental AG, Schaeffler AG, Valeo SA, Voith GmbH & Co. KGaA, JATCO Ltd., EXEDY Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Torque Converter Market Emerging Trajectories
Control architecture migration from hydraulic valve bodies to electric actuators is redefining precision benchmarks across automatic transmission tiers. This shift enables software-defined engagement maps and real-time adaptive calibration.
Multi-plate lock-up clutches with integrated torsional dampers are electrifying highway fuel economy optimization. Premium passenger vehicle platforms in Germany and Japan are adopting these assemblies to meet WLTP efficiency bands. The technology is electrifying the traditional trade-off between launch comfort and direct mechanical coupling.
EMA coordination under Euro 7 provisions is forcing redesigns of transmission thermal management systems. Torque converter stall characteristics now influence engine load cycle optimization for particulate and nitrogen oxide compliance. European commercial vehicle manufacturers are responding with predictive lock-up scheduling algorithms.
Fleet procurement departments are compressing supplier qualification cycles from 36 months to 18 months for hybrid-compatible transmission platforms. Tier-1 suppliers in South Korea and Mexico are disintermediating traditional distribution channels through direct OEM engineering partnerships. This pattern is most visible in North American heavy-duty truck segments where vertical integration pressures mount.
Global Automotive Torque Converter Market Segmentation
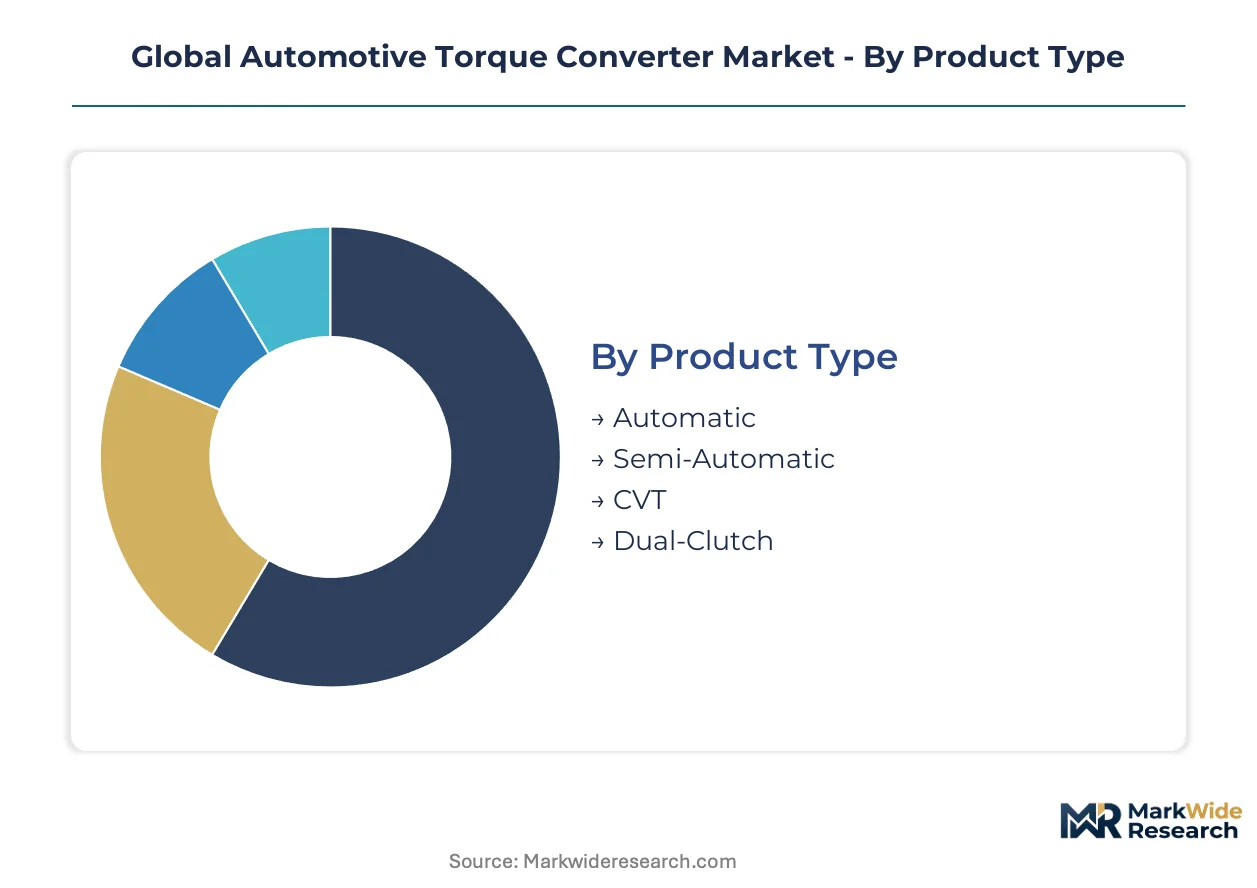
Torque converter architectures diverge sharply across transmission types, with each product category demanding distinct turbine-stator geometries and lock-up clutch specifications. End-use applications span radically different duty cycles, from passenger car highway cruising to mining equipment continuous stall operation.
Product Type:
Buyers in this category prioritize launch smoothness against fuel economy trade-offs, with fleet operators and individual consumers diverging on lock-up engagement priorities.
- Automatic:Traditional three-element fluid coupling with pump impeller, turbine runner, and stator assembly delivering torque multiplication ratios between 1.7 and 2.5 at stall. Demand concentrates in North American passenger vehicles and Chinese domestic brands where EPA Phase 3 and MIIT dual carbon goals compel lock-up clutch optimization for highway efficiency compliance.
- Semi-Automatic:Automated manual transmission architectures with torque converter dampers bridging clutch engagement gaps. European commercial vehicle manufacturers in Germany and France adopt these configurations to meet Euro 7 thermal management requirements while preserving driver control preferences.
- CVT:Continuously variable transmission torque converters with reduced stall ratios optimized for rubber-band effect mitigation. Japanese OEMs leverage these designs for kei-car and compact passenger vehicle platforms targeting urban efficiency benchmarks.
- Dual-Clutch:Wet multi-plate clutch alternatives with minimal torque converter content, typically limited to launch assist dampers. South Korean and German performance vehicle segments favor these architectures for direct-shift responsiveness.
Automatic configurations lead volumes today; hybrid-compatible variants are gaining share fastest.
End User:
Volume concentration and margin structure split across this category, with heavy machinery commanding premium pricing and passenger vehicles driving unit scale.
- Passenger Vehicles:Light-duty applications requiring compact axial dimensions and low-speed torque multiplication for urban stop-start driving. Chinese and Indian production bases generate the dominant order flows as domestic automakers expand automatic transmission penetration.
- Commercial Vehicles:Heavy-duty specifications with reinforced turbine blades and extended lock-up engagement maps for highway fuel economy. North American fleet operators expand procurement under EPA Phase 3 greenhouse gas mandates.
- Motorcycles:Miniaturized torque converter assemblies for automatic scooter and underbone platforms. Southeast Asian manufacturing clusters in Thailand and Indonesia concentrate demand for these compact, cost-optimized designs.
- Heavy Machinery:High-stall-ratio designs for mining excavators and agricultural tractors operating under continuous load. Brazilian and Australian mining corridors sustain specialized foundry orders for these severe-duty specifications.
Passenger vehicles dominate unit volumes; commercial vehicle electrification is expanding fastest.
Technology:
Control precision and thermal efficiency separate buyers, with premium segments accepting electric actuator cost premiums for calibration flexibility.
- Hydraulic:Conventional valve body architectures with fluid pressure modulation for lock-up clutch engagement. Installed base majority across emerging market vehicle fleets where cost sensitivity preserves legacy designs.
- Mechanical:Spring-loaded stator clutches and centrifugal lock-up mechanisms without electronic control. Entry-level passenger vehicles in India and Southeast Asia retain these architectures for manufacturing simplicity.
- Electric:Actuator-driven precision control enabling real-time adaptive calibration and over-the-air engagement map updates. German and Japanese premium platforms adopt these systems to achieve WLTP efficiency bands.
- Hybrid:Integrated motor-damper assemblies accommodating split hybrid powertrain torque paths. Chinese new energy vehicle quotas accelerate localized sourcing of these modified architectures.
Hydraulic systems retain the largest installed base; hybrid configurations show the steepest expansion trajectory.
Application:
Non-automotive demand in this category serves validation and development workflows, with procurement cycles tied to platform launch timelines rather than vehicle production.
- Gaming:Haptic feedback torque converter simulators for racing entertainment peripherals. Japanese and South Korean consumer electronics manufacturers integrate these modules for force-feedback steering systems.
- Simulation:Hardware-in-the-loop test benches replicating stall characteristics and thermal transients for transmission calibration development. German and US automotive engineering centers sustain demand for high-fidelity replication equipment.
- Training:Educational demonstrators for vocational programs teaching automatic transmission repair. Technical institutes in India and Mexico expand procurement as domestic vehicle parcs shift toward automatic penetration.
- Performance Testing:Dynamometer-grade torque converters for durability validation and efficiency mapping. Tier-1 supplier R&D facilities in Japan and Germany require these specialized test articles for lock-up clutch material qualification.
Simulation applications command the highest unit values; training equipment is climbing fastest as technical education expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting torque converter investment toward jurisdictions where carbon compliance costs remain lower than in mature European markets. Production capacity is migrating to manufacturing clusters where dual carbon mandates and EPA Phase 3 standards create differentiated sourcing requirements.
China
Domestic passenger vehicle production expansion concentrates demand in the Yangtze River Delta and Pearl River Delta manufacturing corridors. MIIT dual carbon goals compel automakers to source locally manufactured torque converters aligned with new energy vehicle quotas. Tianjin and Chongqing assembly plants are scaling hybrid-compatible torque converter lines to meet national electrification targets.
United States
Heavy-duty fleet operators in Michigan and Ohio are expanding automatic transmission procurement to satisfy EPA Phase 3 greenhouse gas efficiency mandates. The regulation tightens powertrain requirements through 2032, forcing lock-up clutch optimization for highway fuel economy. Detroit-area engineering centers are validating thermal management systems for commercial vehicle platforms.
Germany
Premium passenger vehicle manufacturers in Bavaria and Baden-Württemberg adopt electric actuator controls to achieve WLTP efficiency bands. EMA coordination under Euro 7 provisions is forcing transmission thermal management redesigns where torque converter stall characteristics influence engine load cycles. Stuttgart supplier parks are integrating predictive lock-up scheduling algorithms.
Japan
Kei-car and compact platform producers in the Chubu and Kanto regions sustain demand for CVT torque converters with reduced stall ratios. METI industrial policy supports captive foundry networks that limit third-party access to precision casting capabilities. Toyota City and Nagoya manufacturing clusters retain in-house turbine blade forging capacity.
India
Domestic automakers in Maharashtra and Tamil Nadu are expanding automatic transmission penetration as passenger vehicle production scales. The PLI scheme for advanced automotive components attracts localized torque converter manufacturing. Pune and Chennai technical institutes are expanding training equipment procurement for automatic transmission repair education.
Global Automotive Torque Converter Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated transmission-torque converter assemblers commanding premium positioning in European and Japanese markets. The structure tiers between captive suppliers serving single OEM families and independent component specialists competing on lock-up clutch precision. Three archetypes dominate: foundry-integrated conglomerates, precision clutch module specialists, and software-defined calibration providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification timelines compress.
Among foundry-integrated conglomerates, Aisin Corporation and ZF Friedrichshafen AG occupy positions exemplifying vertical control over precision casting supply. BorgWarner Inc. represents the specialist archetype competing through modular lock-up clutch expertise in North American markets. These three entities anchor the competitive structure without exhaustive claims about specific strategic actions or market positions.
| Leading Market Players |
|---|
| Aisin Corporation |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Continental AG |
| Schaeffler AG |
| Valeo SA |
| Voith GmbH & Co. KGaA |
| JATCO Ltd. |
| EXEDY Corporation |
| Others |
Supply Flow & Price Mechanics
Captive foundry networks in Japan anchor both supply security and pricing power for turbine blade forgings, insulating integrated manufacturers from commodity volatility while compressing margin room for independent suppliers competing on lock-up clutch modules. This structural concentration forces tier-2 specialists to differentiate through electric actuator precision rather than scale economics.
Pricing Analysis
Distributor margins in the aftermarket channel typically run thinner than direct-to-OEM contract pricing, where volume commitments secure preferential turbine forging allocations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with WLTP-compliant electric actuator systems commanding substantial premiums over hydraulic valve body architectures. Pricing pressure stems from steel and aluminum input volatility squeezing forging cost structures, while fleet operators in North America demonstrate the highest price sensitivity due to EPA Phase 3 compliance budget constraints.
Supply Chain Analysis
Ocean freight cost fluctuations between East Asian manufacturing clusters and North American assembly plants directly impact landed cost competitiveness for turbine blade forgings. Supply concentrates in Japan, China, and Germany, with precision casting capabilities drawing from specialized nickel-based alloys, high-grade steel billets, and aluminum forging stock. Single-source vulnerability around Japanese captive foundry networks creates structural risk, as third-party access to high-stall-ratio designs remains restricted. Distribution runs through Tier-1 transmission assemblers with integrated torque converter lines, disintermediating traditional component distributors in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into sustained demand visibility, with EPA Phase 3 standards tightening through 2032 and MIIT dual carbon goals accelerating Chinese electrification procurement.
For Market Incumbents: Acquire precision casting capacity in India or Mexico to escape Japanese foundry network constraints and secure margin control on hybrid-compatible turbine designs. Battery-electric powertrain substitution threatens legacy fluid coupling volumes, making backward integration into electric motor-damper assemblies essential for platform relevance. Certification investment in Euro 7 thermal validation capabilities defends positioning against European competitors with established EMA coordination relationships. For New Entrants and Emerging Players: EPA Phase 3 in the United States opens a window for lock-up clutch module specialists to penetrate heavy-duty fleet procurement cycles compressed from 36 to 18 months. White-space targets include commercial vehicle electrification torsional dampers and software-defined calibration services decoupled from hardware replacement. The most penetrable entry point is direct OEM engineering partnerships in South Korean and Mexican manufacturing clusters, bypassing established distribution channels through platform co-development agreements. For Investors and Strategic Acquirers: Roll-up economics work for precision clutch module specialists because fragmented independent suppliers lack captive foundry access and face margin compression from commodity volatility. Long-term viability hinges on electrification transition timing, with hybrid architectures sustaining torque converter relevance longer than pure internal combustion forecasts suggest. The acquisition target archetype is electric actuator control developers with WLTP certification track records. The signal to watch is fleet operator procurement cycle compression accelerating consolidation pressure on sub-scale forging operations.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Calibration Investment | Over-the-air transmission tuning creates recurring revenue streams decoupled from hardware replacement cycles. |
| Hybrid-Compatible Foundry Expansion | Integrated motor-damper assembly capacity in Tianjin and Chongqing aligns with MIIT dual carbon sourcing mandates. |
| Lock-Up Clutch Precision Partnership | Direct OEM engineering relationships in Stuttgart supplier parks secure WLTP efficiency band compliance. |
| Multi-Physics Simulation Talent Acquisition | Fluid-structure interaction expertise addresses scarce computational engineering capacity for engagement map optimization. |
| Predictive Thermal Management Development | Euro 7 stall characteristic algorithms reduce transmission thermal validation timelines for European commercial platforms. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation against vehicle production databases, IHS Markit registration data, EPA certification filings, and MIIT new energy vehicle quota disclosures. Bottom-up segment sizing and top-down macroeconomic cross-checks ensured triangulation integrity across modeling approaches.
Historical reference periods anchored the projection horizon through documented transmission platform launch timelines and regulatory milestone implementation schedules. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from fitted growth curves incorporating steel and aluminum price elasticity, foundry capacity utilization rates, and electrification penetration assumptions specific to torque converter content per powertrain type.
Revisions become necessary when battery-electric platform adoption accelerates beyond hybrid transition assumptions, or when Japanese foundry networks expand third-party access and alter competitive cost structures. Forecasts reflect documented assumptions about regulatory enforcement timelines and commodity price baselines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Exhaust System Muffler Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Transmission Oil Filters Market
Powertrain
Spark Plugs Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Clutch Friction Plate Market
Powertrain
Automotive Coil Spring Market
Powertrain
Car Active Purge Pump Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market