
 Uae Passenger Vehicles Lubricants Market | 2026-2036
Uae Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Uae Passenger Vehicles Lubricants Market Analytics
Skilled lubricant blending technicians is rotating toward synthetic formulation capabilities as OEM service specifications tighten across the Emirates. ADNOC leverages its upstream feedstock access to dominate domestic base oil supply. Emirates Lube Oil Co. Ltd anchors its position through specialized distribution to independent service stations. ExxonMobil Corporation competes on technology leadership in low-viscosity engine oil grades for high-temperature Gulf climates.
Uae Passenger Vehicles Lubricants comprise refined petroleum-derived or synthetic base stocks blended with performance additives to reduce friction, dissipate heat, and protect powertrain components in cars, SUVs, and light trucks operating under extreme thermal loads. These formulations typically meet SAE viscosity grades and API service categories specified by manufacturers for warranty compliance. Engine oil commands the largest revenue pool among product types, though synthetic formulations are capturing margin as OEM drain intervals extend. Aftermarket providers represent the fastest-growing end user channel, driven by independent workshops seeking certified bulk supply outside franchised dealer networks.
MOHAP regulates product safety and labeling for automotive chemicals entering the UAE market, while the Emirates Authority for Standardization and Metrology (ESMA) enforces Gulf Standard GSO specifications for lubricant quality and environmental compliance. These frameworks compel importers to maintain accredited testing documentation, filtering out uncertified bulk traders. Stakeholders must monitor how forthcoming Euro 6-equivalent emission standards for new vehicles reshape OEM fill specifications and aftermarket compatibility requirements.
Market Dynamics
MOHAP's tightened product registration requirements for automotive chemicals are forcing distributors toward certified supply chains, compressing margins for uncertified bulk traders while elevating compliance costs across the Emirates.
Growth Catalysts
- Extended OEM drain intervals:Synthetic formulations meeting API SP and ILSAC GF-6 specifications are displacing conventional oils as manufacturers push service intervals beyond 15,000 kilometers.
- Fleet operator consolidation:Corporate and government vehicle pools across Dubai and Abu Dhabi are centralizing lubricant procurement under long-term supply agreements with certified blenders.
- ESMA enforcement of GSO standards:Mandatory quality testing documentation is filtering out substandard imports and redirecting volume toward accredited distribution networks.
Market Restraints
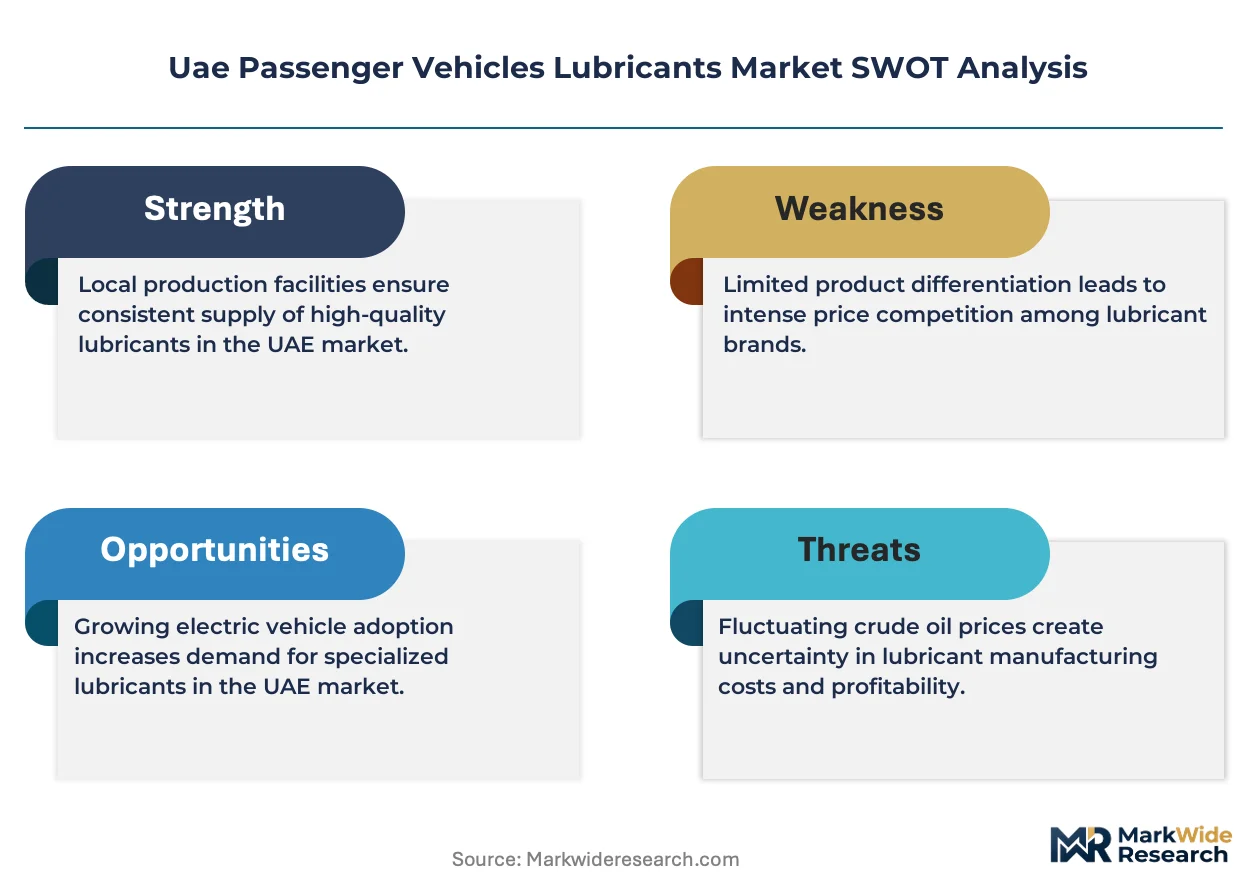
- Base oil supply concentration:ADNOC's dominance over Group II and III base stock production in Ruwais creates dependency risk for independent blenders lacking alternative feedstock arrangements.
- Synthetic additive cost volatility:PAG and ester-based friction modifiers face price pressure from fluctuating petrochemical feedstock costs and specialized chemical import duties.
- Technical compatibility barriers:Low-viscosity 0W-16 and 0W-20 grades specified for newer turbocharged engines create inventory complexity for workshops serving mixed-age vehicle fleets.
Strategic Opportunities
- Northern Emirates service infrastructure:Sharjah and Ras Al Khaimah present underpenetrated demand as vehicle populations expand beyond Dubai-Abu Dhabi concentration.
- EV thermal fluid convergence:Battery electric vehicle cooling and e-axle lubrication requirements are creating formulation crossover opportunities for synthetic fluid specialists.
- Independent workshop certification programs:Bulk supply partnerships with ESMA-accredited service chains offer channel bypass of franchised dealer networks.
Industry Challenges
- Blending technician capability gaps:Synthetic formulation expertise lags demand as vocational training programs emphasize conventional mineral oil processing.
- MOHAP registration timeline compression:Extended product approval cycles for new additive packages delay market entry against faster-certified competitors.
- Inventory reconfiguration costs:Workshops must invest in segregated storage systems to prevent cross-contamination between conventional and synthetic product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uae Passenger Vehicles Lubricants Market |
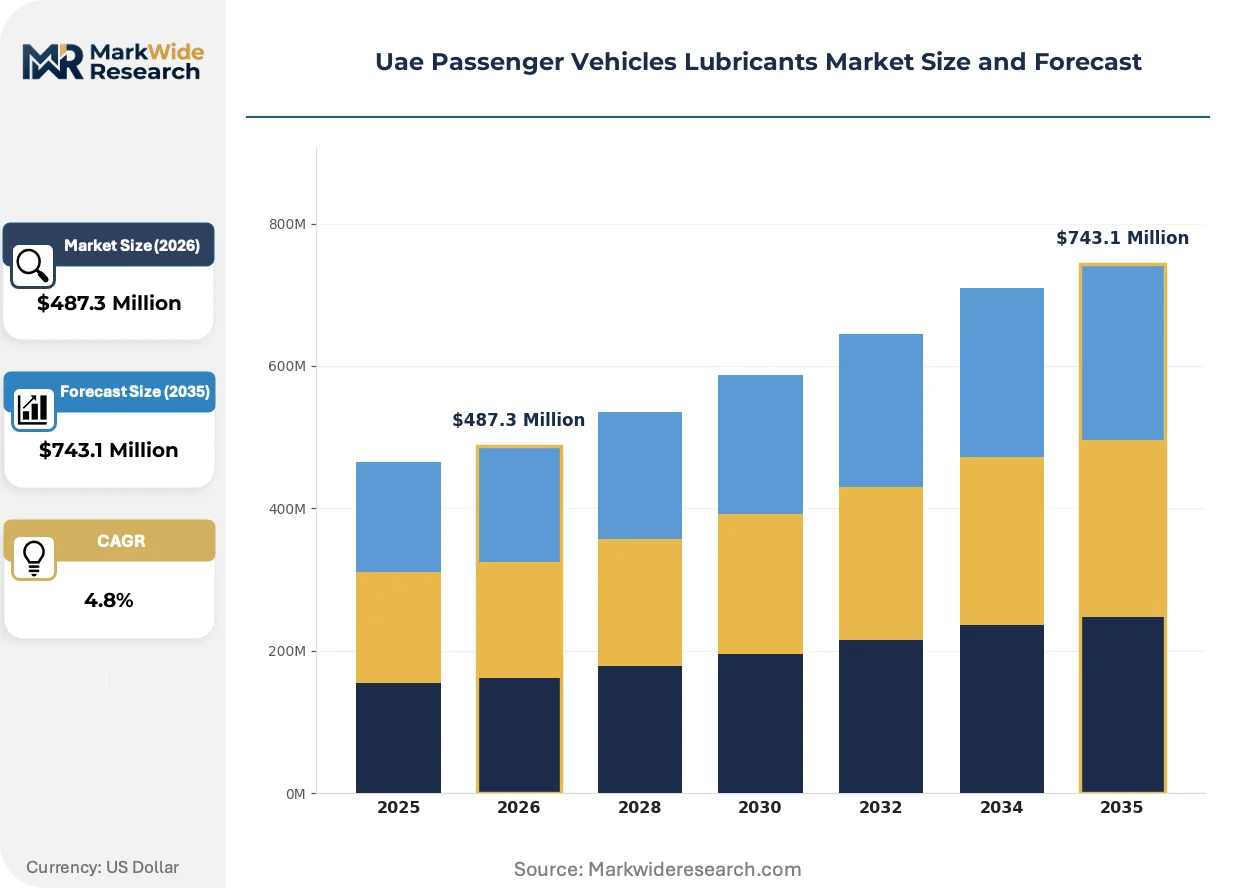
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Formulation: Synthetic, Semi-Synthetic, Mineral, Additive End User: OEMs, Aftermarket Providers, Service Stations, Fleet Operators Packaging Type: Bottles, Drums, Bulk Containers, Pouches |
| Companies Covered | ADNOC, Emirates Lube Oil Co. Ltd, EPPCO Lubricants, Royal Dutch Shell PLC, TotalEnergies, ExxonMobil Corporation, Gulf Oil International, Sharjah National Lube Oil Co. LLC (SHARLU), Emarat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uae Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and distribution mechanics are diverging simultaneously as climate-specific performance demands reshape product architecture and procurement patterns fragment across buyer tiers.
Synthetic base stock technology is bifurcating the product hierarchy. Group III+ and PAO formulations engineered for Gulf ambient temperatures exceeding 50°C are capturing premium positioning in dealer service bays. Fleet operators with mixed vehicle ages face SKU proliferation as they maintain parallel inventories for legacy mineral oils and extended-drain synthetics. The technology is compressing conventional oil volume share while expanding margin pools for certified blenders with in-house synthesis capabilities.
MOHAP's alignment with Gulf Standard GSO 1781/1782 specifications is tightening contaminant limits and biodegradability thresholds for automotive lubricants. Importers must now submit accredited laboratory testing from ESMA-recognized facilities before product registration approval. Independent distributors in Dubai's Jebel Ali free zone are restructuring supply documentation to satisfy these pre-market verification requirements.
Workshop procurement patterns are fragmenting across certification tiers. ESMA-accredited independent service stations are consolidating bulk purchasing power through cooperative buying groups, displacing traditional distributor relationships. Smaller operators without certification credentials face volume restrictions and price penalties. This behavioral shift concentrates premium synthetic demand in certified channels while pushing conventional product toward unregulated gray market supply.
Uae Passenger Vehicles Lubricants Market Segmentation
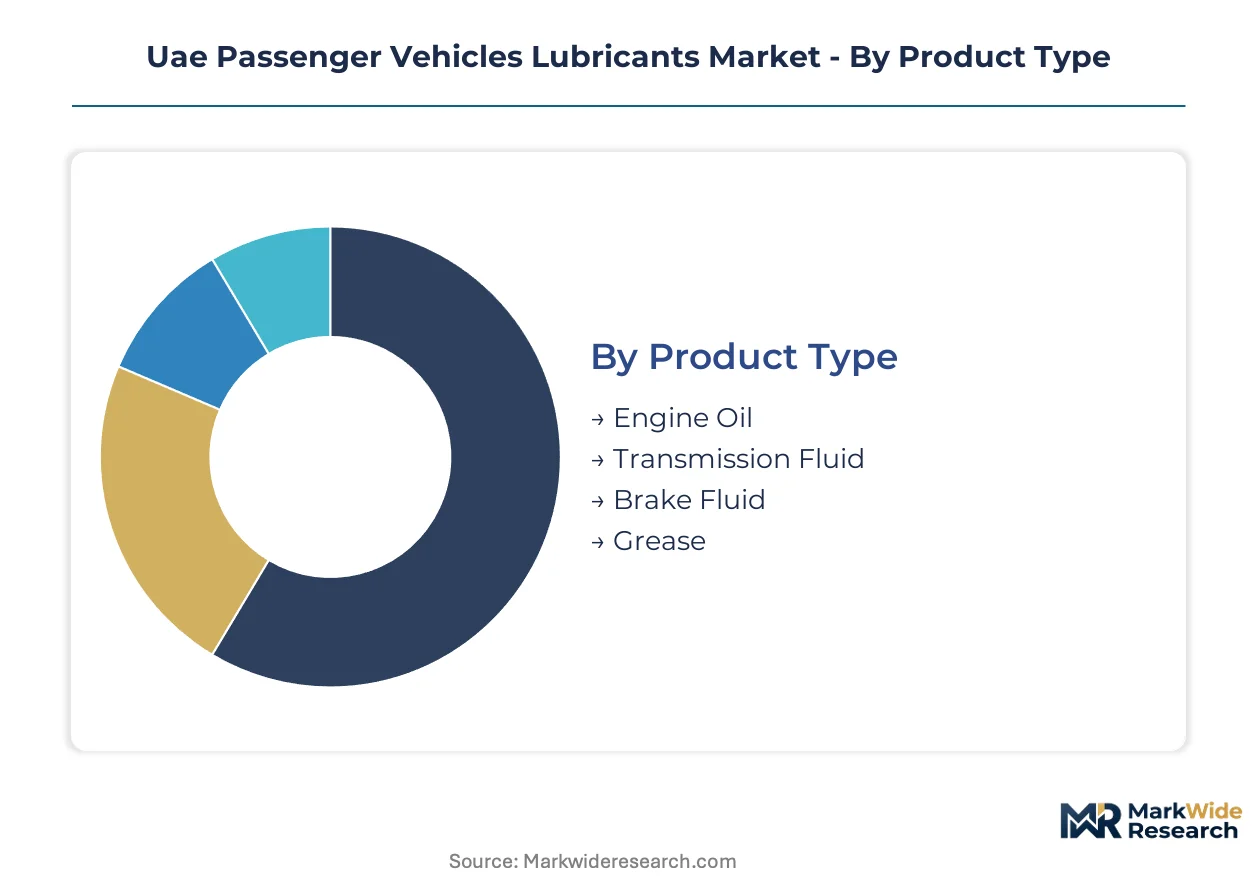
Segmentation in the UAE passenger vehicles lubricants market reveals how regulatory pressure from MOHAP and ESMA concentrates demand into certified channels while fragmenting procurement patterns across buyer sophistication tiers. Understanding these divisions exposes where margin pools accumulate and where volume shifts are accelerating.
Product Type:
MOHAP's tightened registration requirements apply differentially across product categories based on chemical complexity and safety-critical function.
- Engine Oil:Formulations meeting API SP and ILSAC GF-6 specifications dominate procurement volumes, with synthetic grades capturing dealer service bays in Dubai and Abu Dhabi as OEM drain intervals extend beyond 15,000 kilometers. Fleet operators face inventory complexity maintaining parallel stocks for legacy mineral oils and extended-drain synthetics.
- Transmission Fluid:ATF and CVT formulations command premium positioning due to specialized additive packages required for dual-clutch and continuously variable transmissions specified by manufacturers for warranty compliance. Demand concentrates in franchised dealer networks serving newer vehicle populations.
- Brake Fluid:DOT 3 and DOT 4 specifications face strict ESMA contaminant limits, filtering substandard imports toward gray market channels while accredited distributors capture service station volume.
- Grease:Lithium-complex and calcium-sulfonate thickeners serve chassis and wheel bearing applications with simpler registration pathways, sustaining independent workshop procurement outside certified networks.
Engine Oil handles the majority of throughput; Transmission Fluid is expanding most quickly on share as transmission complexity rises.
Formulation:
Cost tier stratification separates premium synthetic positioning from commodity mineral oil competition.
- Synthetic:Group III+ and PAO base stocks engineered for Gulf ambient temperatures exceeding 50°C are displacing conventional products in dealer service specifications. ADNOC's Ruwais feedstock access shapes domestic supply availability for certified blenders.
- Semi-Synthetic:Blends offering intermediate drain intervals capture fleet operator procurement seeking cost optimization across mixed-age vehicle pools without full synthetic premiums.
- Mineral:Group I and II base stocks face volume compression as OEM specifications tighten, retreating toward independent workshops serving older vehicle populations in Northern Emirates.
- Additive:PAG and ester-based friction modifiers face price volatility from petrochemical feedstock fluctuations, creating margin pressure for blenders lacking captive additive supply.
Synthetic formulations command the steepest expansion trajectory; Mineral oil retains residual volume in price-sensitive channels.
End User:
Customer type determines procurement scale, certification requirements, and channel access.
- OEMs:Factory fill specifications demand pre-approved lubricant partnerships with documented testing from ESMA-recognized facilities, creating high barriers for uncertified suppliers.
- Aftermarket Providers:Independent workshops in Dubai and Abu Dhabi are consolidating bulk purchasing through cooperative buying groups, displacing traditional distributor relationships and accelerating certified channel migration.
- Service Stations:ESMA-accredited facilities capture premium synthetic demand while uncertified operators face volume restrictions and price penalties.
- Fleet Operators:Corporate and government vehicle pools across the Emirates are centralizing lubricant procurement under long-term supply agreements with certified blenders, compressing spot market participation.
Aftermarket Providers are gaining share fastest; Fleet Operators anchor the largest contract volumes.
Packaging Type:
Supply concentration in Jebel Ali free zone shapes packaging economics and distribution reach.
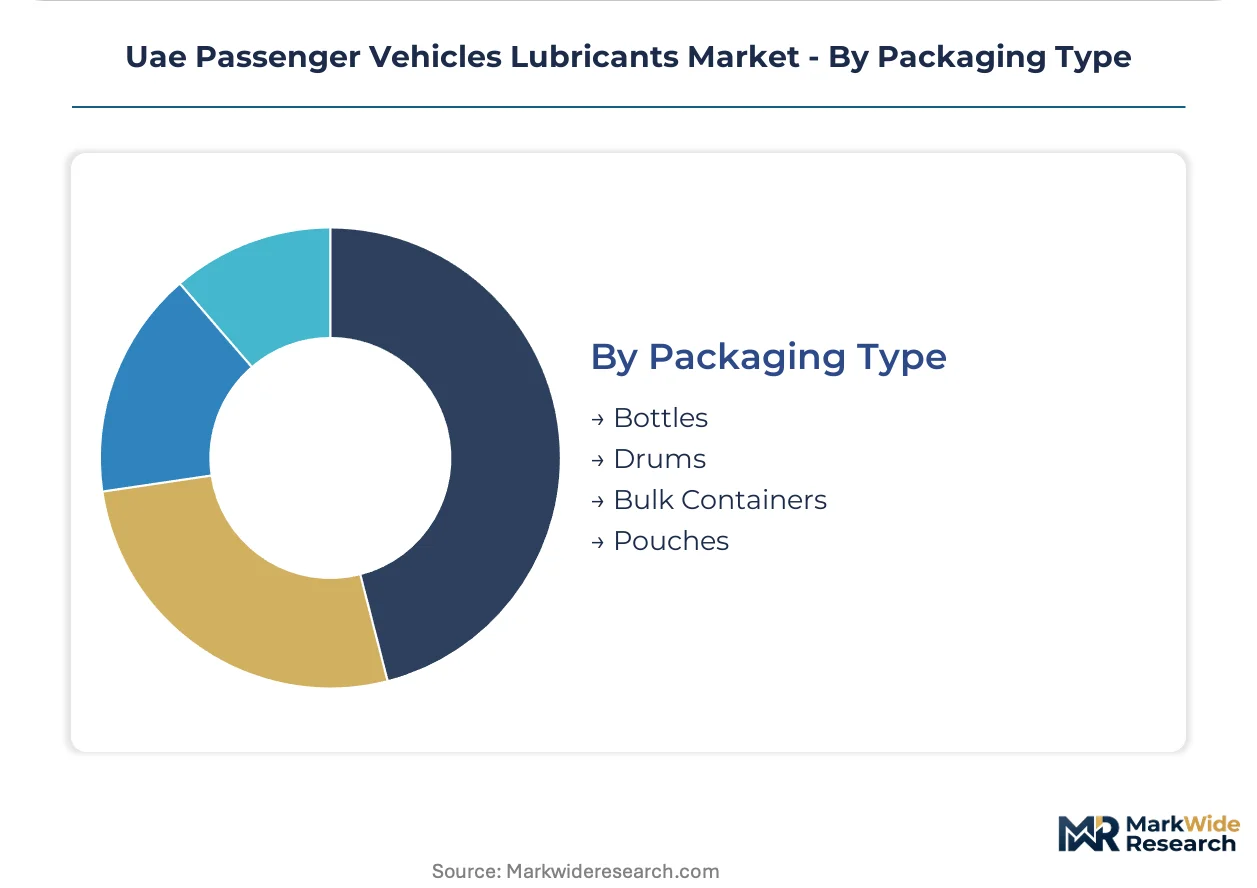
- Bottles:Retail-format packaging serves individual vehicle owners and small independent workshops with limited storage capacity, sustaining convenience-store and petrol station distribution.
- Drums:Intermediate bulk format dominates workshop procurement in Sharjah and Ras Al Khaimah service infrastructure expansion.
- Bulk Containers:Tanker and tote deliveries support fleet operator centralization and cooperative buying group consolidation in certified channels.
- Pouches:Single-use and sampling formats serve promotional and trial applications with limited sustained volume.
Bulk Containers handle the majority of certified channel throughput; Drums are climbing fastest as Northern Emirates service infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP's regulatory framework anchors lubricant distribution across the Emirates, with demand concentrating in commercial hubs where vehicle density and service infrastructure align. The analysis examines four sub-regions where procurement patterns and compliance requirements diverge.
Dubai
Franchised dealer networks and independent workshops drive synthetic lubricant volumes as OEM service specifications tighten. ESMA-accredited facilities cluster along Sheikh Zayed Road and Al Quoz industrial zones, filtering bulk procurement through certified channels. Jebel Ali free zone distributors restructure supply documentation to satisfy pre-market verification requirements.
Abu Dhabi
Government and corporate fleet operators centralize procurement under long-term supply agreements with certified blenders. ADNOC's Ruwais base oil production anchors domestic feedstock availability for Group II and III formulations. Khalifa Industrial Zone blending facilities serve OEM factory fill specifications requiring documented testing from ESMA-recognized laboratories.
Sharjah
Vehicle population expansion outpaces service infrastructure development, creating underpenetrated demand for intermediate bulk drum formats. Independent workshops without ESMA accreditation face volume restrictions and price penalties in procurement. Industrial areas along Emirates Road attract distributors seeking lower-cost warehousing outside Dubai-Abu Dhabi concentration.
Northern Emirates
Ras Al Khaimah and Fujairah present emerging opportunities as vehicle ownership rises beyond traditional commercial corridors. MOHAP registration requirements apply uniformly, yet accredited testing documentation remains scarcer than in southern Emirates. Fleet operators in these emirates rely more heavily on spot market participation due to limited long-term supply agreement penetration.
Uae Passenger Vehicles Lubricants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Emirates lubricant market. National oil companies with captive base oil supply dominate cost structures, while international majors compete on formulation chemistry and OEM approval portfolios. Three strategic archetypes define competitive positioning: upstream-integrated domestic producers, technology-focused international blenders, and regional distribution specialists. M&A activity concentrates among mid-scale distributors seeking ESMA accreditation, while capacity expansion focuses on synthetic blending lines for extended-drain specifications.
Within the upstream-integrated tier, ADNOC anchors domestic supply through Ruwais feedstock access. Emirates Lube Oil Co. Ltd occupies a specialist position serving independent service stations with certified bulk distribution. ExxonMobil Corporation represents the technology-driven archetype, competing on low-viscosity formulation capabilities for high-temperature Gulf operating conditions.
| Leading Market Players |
|---|
| ADNOC |
| Emirates Lube Oil Co. Ltd |
| EPPCO Lubricants |
| Royal Dutch Shell PLC |
| TotalEnergies |
| ExxonMobil Corporation |
| Gulf Oil International |
| Sharjah National Lube Oil Co. LLC (SHARLU) |
| Emarat |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for synthetic base stocks concentrate pricing power with ADNOC's Ruwais facilities, while independent blenders absorb margin compression from feedstock dependency and ESMA compliance documentation costs. This supply concentration shapes a market where certified distributors command premium positioning and uncertified traders face systematic price penalties.
Pricing Analysis
Dubai-Abu Dhabi price spreads for API SP synthetic grades exceed those in Sharjah and Ras Al Khaimah by meaningful margins, reflecting certification density and logistics concentration. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels separates ESMA-accredited service stations from gray market operators. Pricing pressure stems from ADNOC's feedstock dominance compressing independent blender margins. Fleet operators exhibit highest price sensitivity due to volume procurement scale, while franchised dealer networks absorb premium positioning for warranty compliance.
Supply Chain Analysis
Strategic stockpiling of Group III base oils prevails among certified blenders facing ADNOC supply allocation constraints, while smaller workshops maintain just-in-time drum procurement from Jebel Ali distributors. Supply draws from UAE domestic production, with residual additive packages sourcing from Singapore and European specialty chemical hubs. Raw material dependencies center on PAG friction modifiers, ester base stocks, and viscosity index improvers. Single-source vulnerability concentrates in ADNOC's Ruwais feedstock monopoly. Distribution runs through ESMA-accredited bulk terminals serving cooperative buying groups and fleet direct delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as vehicle ownership expansion across the Emirates drives maintenance interval compression and certified channel migration. Fleet operator consolidation and OEM drain interval extension create durable demand tailwinds for synthetic formulation specialists.
For Market Incumbents: Shield margin pools by deepening captive base oil arrangements outside ADNOC dependency and accelerating ESMA certification coverage across Northern Emirates distribution networks. Synthetic formulation capability investments defend against technology displacement from emerging EV thermal fluid requirements. Channel control through cooperative buying group partnerships anchors volume against independent workshop consolidation. For New Entrants and Emerging Players: Differentiate on EV thermal fluid formulation expertise as battery electric vehicle populations expand beyond early adoption in Dubai and Abu Dhabi. White-space targets concentrate in Sharjah and Ras Al Khaimah service infrastructure gaps, where ESMA-accredited bulk supply partnerships bypass entrenched distributor relationships. Go-to-market execution through fleet operator direct contracting avoids franchised dealer network barriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ESMA compliance cost escalation filters uncertified distributors toward acquisition or exit, concentrating volume with accredited mid-scale blenders. Acquisition targets center on Jebel Ali-based distributors with documented testing infrastructure and Northern Emirates warehouse footprints. The signal to watch is MOHAP registration timeline compression accelerating competitive exit rates among non-compliant traders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Captive PAG and ester production insulates blenders from petrochemical feedstock volatility and import duty exposure. |
| ESMA Certification Program Expansion | Accreditation investment unlocks cooperative buying group procurement and fleet operator long-term supply agreements. |
| EV Thermal Fluid R&D Partnership | Collaboration with battery OEMs positions synthetic specialists for e-axle lubrication and cooling system convergence. |
| Northern Emirates Distribution Buildout | Sharjah and Ras Al Khaimah warehouse infrastructure captures vehicle population expansion beyond Dubai-Abu Dhabi concentration. |
| Long-term Fleet Supply Agreement | Corporate and government vehicle pool contracts compress spot market participation and anchor synthetic volume commitments. |
Research Methodology
A standing panel of lubricant blending technicians, fleet procurement managers, ESMA compliance officers, and independent workshop operators provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources included customs trade data for base oil and additive imports, MOHAP product registration databases, ESMA laboratory accreditation records, and ADNOC supply allocation disclosures. Bottom-up volume modeling from individual emirate vehicle registration data triangulated against top-down synthetic penetration assumptions from OEM service specification analysis.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including formulation chemistry tier, end-user certification status, packaging format scale, and regional service infrastructure maturity. CAGRs derived from emirate-level vehicle population projections and synthetic share assumptions calibrated to API SP adoption curves. Industry-specific inputs incorporated MOHAP registration timeline data and ADNOC base oil production allocation patterns.
Material uncertainties — regulatory timeline shifts, feedstock price volatility, and EV penetration acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about ESMA enforcement intensity and OEM specification migration rates. Revision becomes warranted when EV thermal fluid specification convergence crosses commercial viability thresholds or MOHAP registration requirements tighten beyond current trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Europe Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Engine Valves Market